
 Flash Charger Adapter Market | 2026-2036
Flash Charger Adapter Market Size, Share, and Industry Trends Forecast 2026-2036
Flash Charger Adapter Market Intelligence
Manufacturing capacity expansion in China is fragmenting the supplier base for flash charger adapters. This shift creates opportunities for new entrants focused on specific power delivery protocols. Qualcomm sustains its market influence through its licensing of Quick Charge technology. In contrast, OPPO differentiates with its proprietary VOOC fast-charging standard, controlling its ecosystem.
A flash charger adapter is a power supply unit designed to charge electronic devices at a rate significantly faster than standard 5W or 10W chargers, often exceeding 18W. These devices utilize specific communication protocols between the adapter and the device to negotiate higher power levels safely. The technology landscape shows a split between open standards like USB Power Delivery, which is gaining traction in laptops, and proprietary protocols such as Oppo VOOC, dominant in certain smartphone ecosystems.
Product design and market access are governed by a web of international and national regulations. Compliance with CE marking in Europe, FCC Part 15 rules in the United States, and GB standards in China is mandatory for all consumer electronics. These standards primarily address electrical safety, electromagnetic compatibility, and energy efficiency. The key strategic decision for device manufacturers revolves around committing to the universal USB-PD standard versus investing in proprietary charging technologies.
Market Dynamics
The fundamental dynamic shaping the flash charger adapter market is the tension between open standardization, epitomized by USB Power Delivery, and closed, proprietary ecosystems. This conflict influences everything from product design and interoperability to licensing revenue streams and supply chain allegiances, forcing manufacturers to choose between universal compatibility and ecosystem lock-in.
Growth Catalysts
- Gallium Nitride (GaN) Technology:The industry-wide shift to GaN semiconductors enables the creation of smaller, lighter, and more power-efficient adapters compared to traditional silicon, meeting consumer demand for portability without sacrificing performance.
- High-Power Device Proliferation:The expansion of device categories requiring fast charging, including gaming smartphones, ultra-thin notebooks, and tablets, creates a persistent demand pull for adapters capable of delivering power well above standard levels.
- Regulatory Mandates for Standardization:European Union regulations promoting a common charger via USB-C ports accelerate the adoption of open standards like USB Power Delivery, simplifying the market and encouraging interoperability.
Market Restraints
- Thermal Management Complexity:Designing adapters that can safely dissipate heat at power levels exceeding 100W remains a significant engineering hurdle, increasing material costs and limiting form factor reduction even with GaN technology.
- Proprietary Protocol Fragmentation:The persistence of closed, licensed charging standards creates interoperability issues for consumers and increases design and testing costs for manufacturers who must support multiple protocols.
- Certification Hurdles:Navigating the distinct and rigorous safety and electromagnetic compatibility standards of different regions, such as FCC Part 15 in the US and GB standards in China, creates costly delays and barriers for market access.
Strategic Opportunities
- Industrial and B2B Applications:Extending USB-PD fast charging technology beyond consumer electronics into new verticals like portable medical devices, power tools, and light electric vehicles opens a significant new market segment.
- Underpenetrated Markets:Expanding into regions across Southeast Asia and Latin America, where smartphone penetration is high but the adoption of dedicated fast chargers is still nascent, offers substantial volume growth potential.
- Integrated Power Solutions:Developing multi-functional adapters that combine high-wattage USB-PD charging, multiple ports, and integrated wireless charging capabilities addresses the consumer trend of device consolidation.
Industry Challenges
- Intellectual Property Navigation:The complex web of patents and licensing agreements surrounding both open standards like USB-PD and proprietary technologies like Qualcomm Quick Charge creates a litigious and costly environment for developers.
- Interoperability Testing Burden:Ensuring seamless and safe communication between a vast and growing number of chargers and devices under the USB Power Delivery protocol requires extensive and continuous validation, straining testing resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flash Charger Adapter Market |
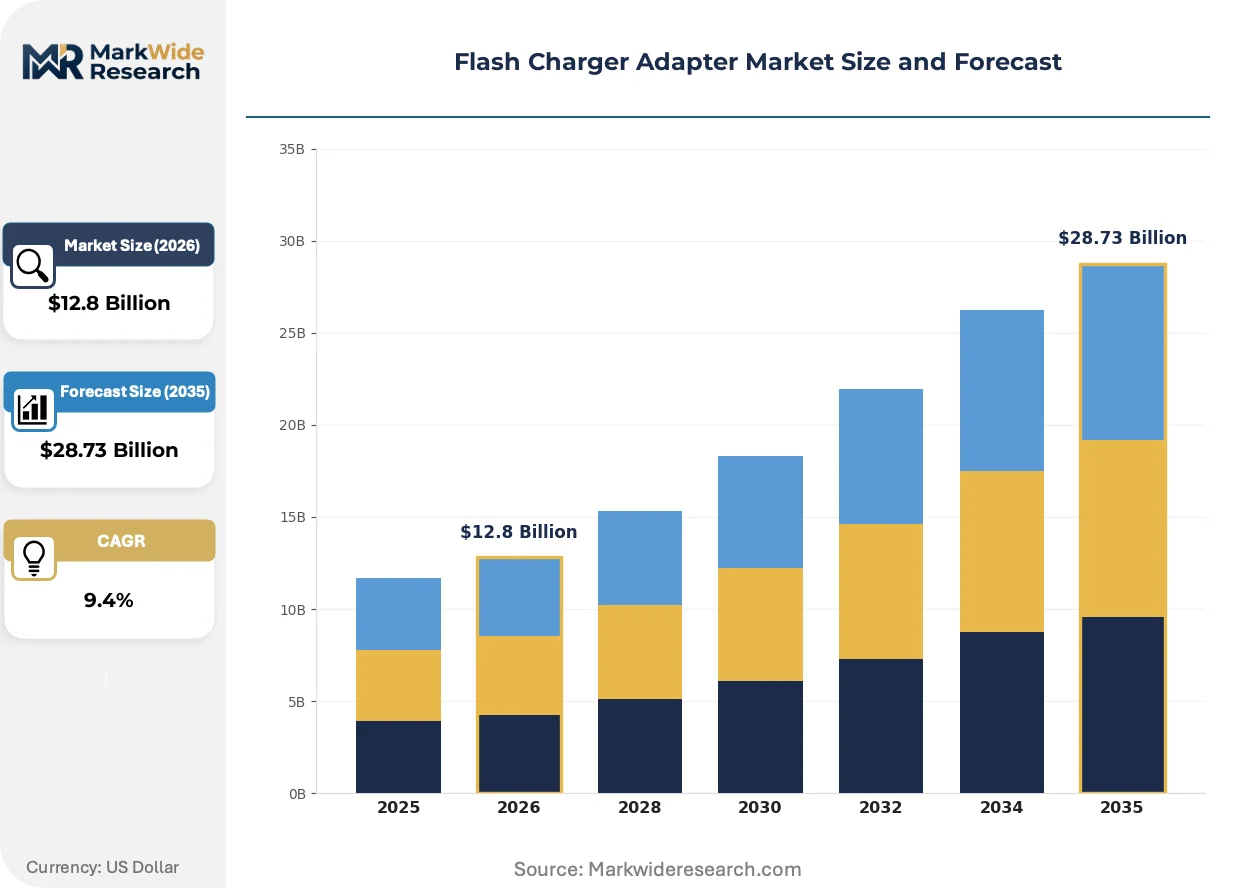
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Chargers, Car Chargers, Power Banks, Wireless Chargers, USB Adaptors Technology: Qualcomm Quick Charge, USB Power Delivery, MediaTek Pump Express, Oppo VOOC, Samsung Adaptive Fast Charging Application: Smartphones, Tablets, Laptops, Wearable Devices, Portable Gaming Consoles End User: Telecom Providers, Consumer Electronics Retailers, E-commerce Platforms, Specialty Electronics Stores |
| Companies Covered | Lenovo, OnePlus, Samsung, Xiaomi, Realme, OPPO, Vivo, Qualcomm, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flash Charger Adapter Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward universal power solutions, driven by regulatory pressure for standardization and technological advancements in semiconductor materials. This is compelling a fundamental re-evaluation of the adapter's role, from a bundled accessory to a standalone, high-performance peripheral.
Gallium Nitride (GaN) serves as a core enabling technology, offering superior thermal and electrical properties over traditional silicon. Consumer electronics brands are rapidly adopting GaN to achieve higher power outputs in smaller form factors for their premium chargers. The market's design philosophy is migrating from bulky, single-function silicon adapters to compact, multi-port GaN chargers that can power a laptop, phone, and wearable simultaneously.
European Union directives mandating USB-C as a common charging interface represent a powerful regulatory force. This policy compels manufacturers of smartphones, tablets, and laptops to standardize their hardware, effectively curtailing the use of proprietary connectors within the bloc. The consumer electronics segment is most affected, accelerating its investment in and alignment with the USB Power Delivery protocol to ensure market access.
A notable shift in consumer behavior is the preference for a single, versatile, high-power adapter rather than a collection of device-specific chargers. This trend disrupts the traditional OEM model of including a low-wattage charger in the box, fueling a robust aftermarket for powerful, multi-port third-party adapters. This purchasing pattern is particularly pronounced in developed markets like North America where consumers often own multiple high-power-draw electronic devices.
Flash Charger Adapter Market Segmentation
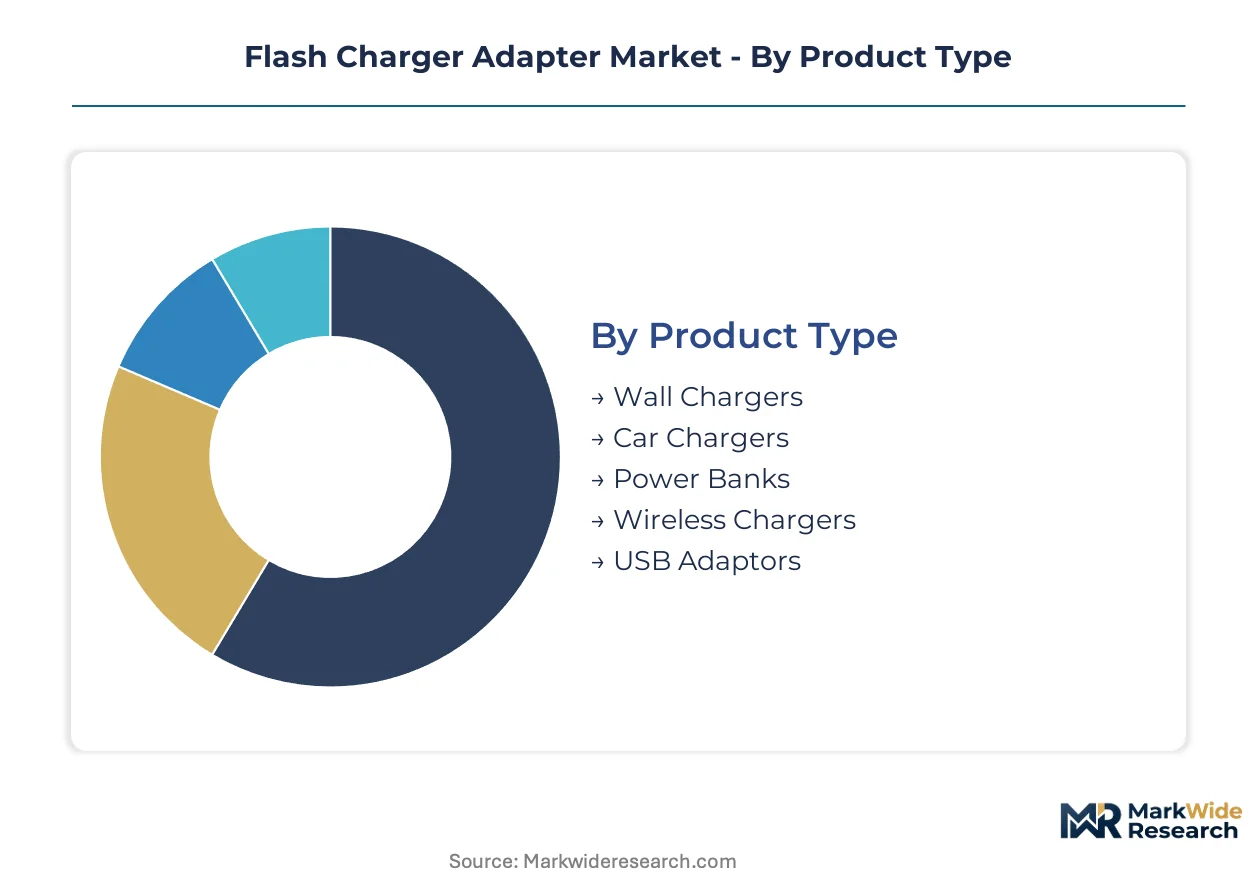
The flash charger adapter market segments by product type, underlying technology, primary application, and end-user distribution channels. Understanding these distinct categories provides clarity on demand drivers, technological evolution, and commercial strategies across the ecosystem. Each segment presents unique opportunities and challenges for manufacturers and distributors alike.
Product Type:
Product types within the flash charger adapter market exhibit varying replacement cycles. Wall chargers generally have longer lifespans than portable power solutions, influencing manufacturing priorities.
- Wall Chargers:Primary power delivery units connecting to AC outlets, integrating GaN for compact, high-wattage output. Demand concentrates in developed markets like Germany for efficient multi-device charging.
- Car Chargers:Designed for in-vehicle use, these adapters convert DC power into suitable output for devices, often with multiple USB ports.
- Power Banks:Portable battery packs store energy for on-the-go charging, incorporating advanced battery management. Consumer preference in China drives significant volume.
- Wireless Chargers:These devices transmit power inductively to compatible devices, offering convenience. Qi standard adoption expands this segment.
- USB Adaptors:Versatile units converting various power sources into USB output for charging or data transfer. Broad compatibility is key.
Wall chargers dominate the installed base due to universal necessity. Power banks are where expansion concentrates, driven by portable power needs.
Technology:
Flash charging technologies delineate the market by specific power delivery mechanisms and device compatibility. Protocols dictate speed and safety, impacting interoperability across ecosystems.
- Qualcomm Quick Charge:This proprietary technology, licensed by Qualcomm, facilitates rapid charging for devices with compatible Snapdragon processors.
- USB Power Delivery:An open standard utilizing USB-C to deliver high power, enabling universal fast charging for laptops, tablets, and smartphones. EU regulations accelerate adoption.
- MediaTek Pump Express:Developed by MediaTek, this proprietary standard targets devices using MediaTek chipsets, offering competitive charging speeds.
- Oppo VOOC:Oppo's proprietary fast-charging technology, including SuperVOOC, emphasizes high current for rapid charging of its own brand devices, creating a closed ecosystem.
- Samsung Adaptive Fast Charging:Samsung's proprietary solution, based on Quick Charge, provides fast charging for its Galaxy series smartphones and tablets.
Open standards like USB Power Delivery are gaining broad industry support. Proprietary solutions, like Oppo VOOC, maintain strong positions within their brand ecosystems.
Application:
The application segments define the primary devices utilizing flash charger adapters, influencing power output requirements and charging protocol prioritization. Each category presents distinct challenges.
- Smartphones:The largest application segment, demanding high-speed charging solutions to support intensive daily usage and advanced features. Volume of users in China drives immense demand.
- Tablets:These devices require higher power output than smartphones due to larger battery capacities, often leveraging USB Power Delivery.
- Laptops:Modern ultra-thin notebooks increasingly rely on USB Power Delivery for charging, necessitating adapters delivering 65W or more. Remote work fuels demand for compact chargers.
- Wearable Devices:Small battery capacities mean these devices require lower wattage but benefit from faster charging for convenience.
- Portable Gaming Consoles:These devices demand consistent, high-speed charging for extended gameplay, often integrating proprietary or USB-PD protocols.
Smartphone proliferation remains a primary growth driver for flash charger adapters. Laptop adoption of USB-PD represents a significant expansion area.
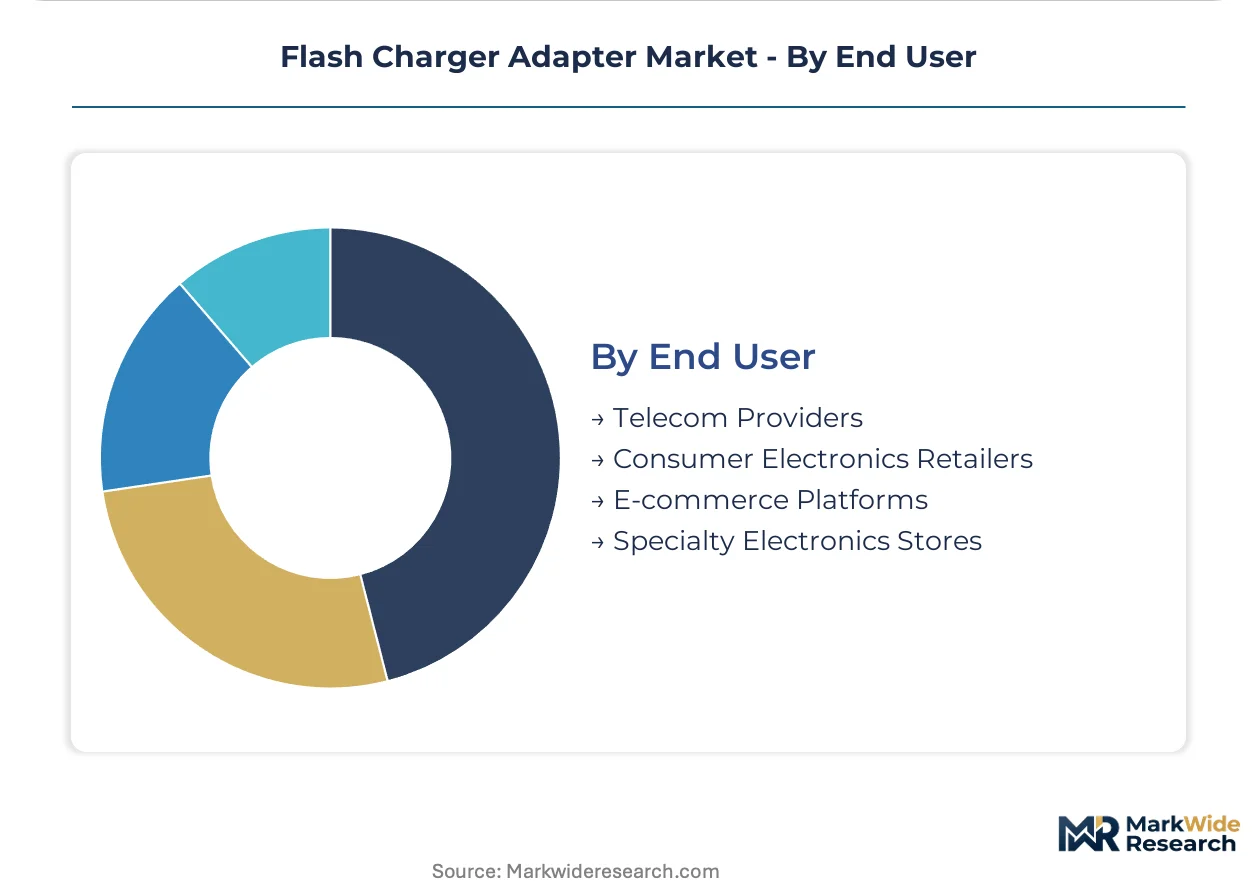
End User:
End-user segments illustrate the primary channels through which flash charger adapters reach consumers, influencing distribution strategies and market access. Each channel has distinct purchasing behaviors.
- Telecom Providers:These entities bundle flash chargers with new smartphone contracts or offer them as accessories in their retail stores.
- Consumer Electronics Retailers:Traditional brick-and-mortar stores offer a wide array of flash charger brands, allowing consumers hands-on evaluation. They cater to a broad customer base seeking immediate product availability.
- E-commerce Platforms:Online marketplaces provide extensive product selections, competitive pricing, and convenience for a global customer base. Digital shopping in the US boosts sales through these channels.
- Specialty Electronics Stores:These retailers focus on niche or premium electronic accessories, often offering high-end flash chargers with advanced features.
E-commerce platforms offer unparalleled market reach and convenience. Consumer electronics retailers provide critical physical access and product visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards in China significantly influence the flash charger adapter market, given the country's immense consumer electronics manufacturing and user base. European Union regulations promoting USB-C also accelerate open standard adoption, shaping product design and market access.
China
China's vast smartphone user base and extensive consumer electronics manufacturing generate immense demand for flash charger adapters. GB standards dictate electrical safety and electromagnetic compatibility. Shenzhen's electronics manufacturing hub drives innovation in adapter design and high-volume production.
United States
Consumer preference for high-power devices and multi-port adapters fuels significant demand across the United States. FCC Part 15 rules ensure electromagnetic compatibility for all electronic devices. Silicon Valley's tech ecosystem influences demand for advanced GaN-based charging solutions.
Germany
Developed markets like Germany exhibit strong demand for efficient multi-device charging solutions, particularly with GaN technology. CE marking compliance is mandatory for all flash charger adapters sold within the European Union. Bavarian industrial clusters integrate GaN technology into compact, high-wattage wall charger designs.
India
India's high smartphone penetration rate presents substantial volume growth potential for dedicated fast chargers in underpenetrated markets. BIS standards govern product quality and safety, impacting market entry. Bengaluru's tech industry drives demand for reliable fast charging solutions for its expanding digital consumer base.
Japan
Tech-forward consumers in Japan seek compact, high-performance flash charger adapters for their premium electronic devices. JIS standards ensure product quality and safety across various industrial and consumer goods. Tokyo's consumer electronics market demonstrates a strong preference for multi-functional adapters with integrated wireless charging capabilities.
Flash Charger Adapter Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the flash charger adapter market. The supplier base is fragmenting due to manufacturing capacity expansion in China, creating diverse competitive dynamics. Strategic archetypes include proprietary technology developers, universal standard proponents, and high-volume contract manufacturers focusing on specific power delivery protocols. Competitive moves involve aggressive technology licensing and strategic capacity expansion to capture emerging market opportunities.
Within the technology licensing archetype, Qualcomm, a US-based entity, sustains its market influence through its Quick Charge technology. OPPO, a Chinese smartphone manufacturer, exemplifies the proprietary ecosystem model with its VOOC fast-charging standard, controlling its device ecosystem. Samsung, a South Korean electronics giant, utilizes its Adaptive Fast Charging solution, based on Quick Charge, for its Galaxy series smartphones and tablets.
| Leading Market Players |
|---|
| Lenovo |
| OnePlus |
| Samsung |
| Xiaomi |
| Realme |
| OPPO |
| Vivo |
| Qualcomm |
| Sony Corporation |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints like CE marking requirements determine both pricing tier spreads and flash charger adapter supply chain shape. This affects market access and cost structures for manufacturers.
Pricing Analysis
Price spreads exhibit significant regional variation, with premium offerings in Europe and North America commanding higher prices. The dominant pricing model is per-unit transactional, often influenced by licensing fees for proprietary technologies like Qualcomm Quick Charge. Brand premium and certification level, such as CE marking, drive price differentiation. Pricing pressure stems from intense competition in the mass-market smartphone segment. Consumers in emerging markets like India are most price-sensitive, while early adopters in developed markets show less sensitivity.
Supply Chain Analysis
Single-source vulnerability in specific component categories like GaN semiconductors dominates the flash charger adapter supply chain. Geographic supply concentration remains high in China and Taiwan for manufacturing and assembly. Key raw material dependencies include GaN wafers and specialized integrated circuits. Logistics chokepoints, particularly port congestion, pose a structural risk. Distribution runs primarily through e-commerce platforms and consumer electronics retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
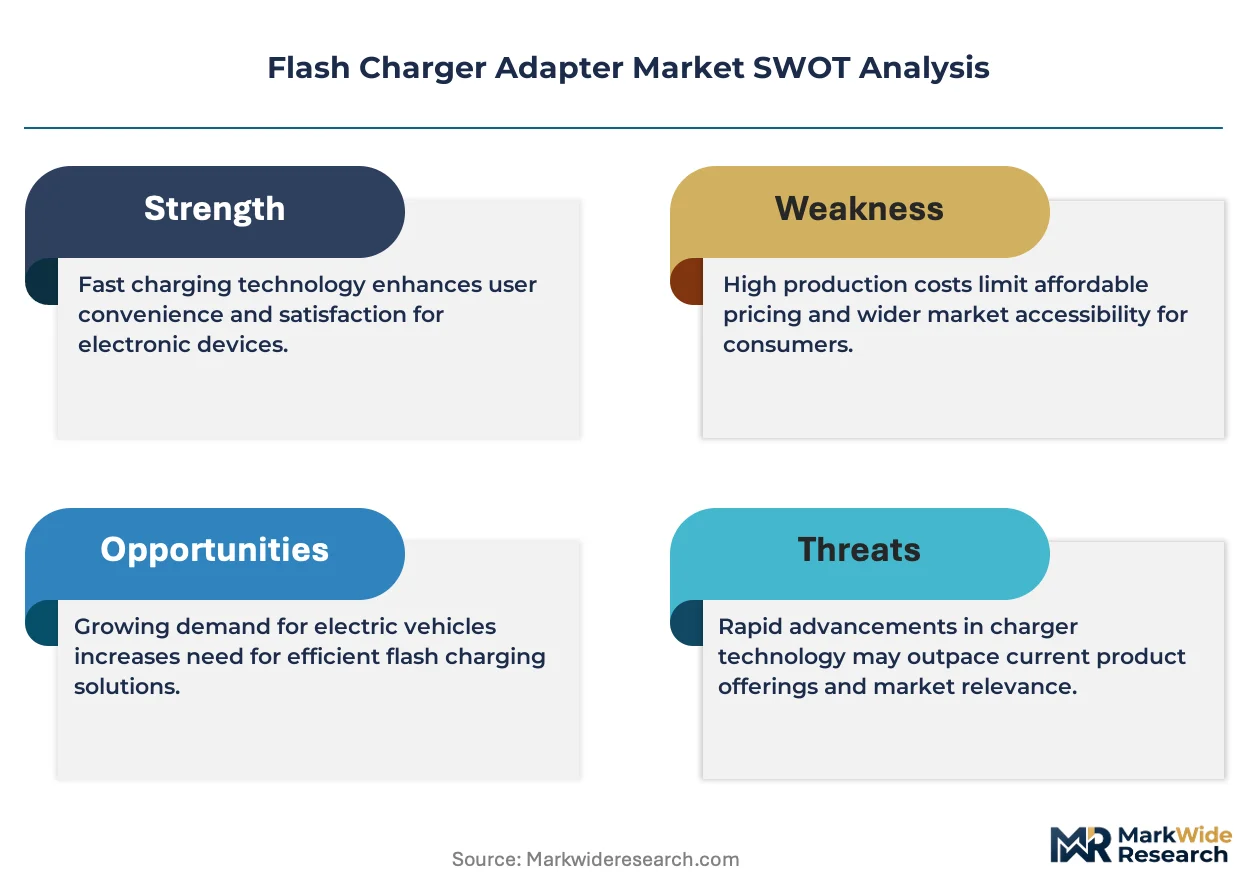
The flash charger adapter market is a high-growth disruption, driven by the technological inflection of Gallium Nitride (GaN) semiconductors. This enables compact, high-power solutions for an expanding device ecosystem.
For Market Incumbents: Build proprietary technology moats through continued investment in GaN research and advanced thermal management solutions. This counters the threat of commoditization from generic USB-PD offerings. Expand manufacturing capacity in diverse geographies to mitigate supply chain risks. Secure long-term licensing agreements for critical power delivery protocols like USB Power Delivery.
For New Entrants and Emerging Players: Build out niche market expertise in specific power delivery protocols or form factors. Target underpenetrated markets in Southeast Asia with multi-port GaN chargers for high-power devices. Focus on a direct-to-consumer e-commerce model, emphasizing value and compatibility. Penetrate the industrial and B2B applications segment with robust, high-wattage USB-PD solutions.
For Investors and Strategic Acquirers: European Union regulations promoting USB-C reshapes the acquisition landscape for flash charger adapter manufacturers. Long-term viability for this sector hinges on robust intellectual property portfolios and diversified manufacturing footprints over a five to ten-year window. Acquisition targets should be vertically integrated mid-cap specialists with strong GaN expertise. The signal to watch is the consolidation of proprietary charging standards.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Technology R&D Investment | Accelerates power density and miniaturization for premium flash charger adapters. |
| USB-PD Protocol Integration | Ensures broad device compatibility and market access under EU regulations. |
| Diversified Manufacturing Footprint | Mitigates geopolitical supply chain risks, particularly in China. |
| Strategic Licensing Partnerships | Expands market reach for proprietary charging standards like Qualcomm Quick Charge. |
| B2B Segment Expansion | Opens new high-volume revenue streams beyond consumer electronics. |
Research Approach
The analysis maps product types, underlying technologies, and primary applications, each validated through conversations with R&D directors, procurement managers, and channel partners. This combines extensive primary interviews with secondary validation from industry association reports, government trade data, and company annual filings. A rigorous bottom-up and top-down triangulation approach ensures data consistency across the ecosystem.
Assumptions held fixed include stable regulatory environments in major markets, while variables like GaN adoption rates and USB-PD proliferation were modeled. Segmentation dimensions included product type, technology, application, and end-user distribution, alongside regional adoption patterns. Compound Annual Growth Rates were derived from historical data trends and projected technological shifts. Key forecast inputs included smartphone penetration rates and laptop sales figures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by proprietary technology developers or new entrants would shift outcomes. Forecasts reflect assumptions about market dynamics and technological evolution across the modeling period. Geopolitical tensions or unexpected raw material price surges represent specific risk factors that could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Amplifier Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Structural Electronics Market
Electronic Components
Encoder Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Breadboards Market
Electronic Components
Digital Potentiometer Market
Electronic Components
Electric Capacitor Market
Electronic Components
Fuse Bases Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Audio Capacitor Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Flex-Rigid PCB Market