
 Europe Microcontroller Market | 2026-2036
Europe Microcontroller Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Microcontroller Market Insights
REACH compliance is pivoting the cost-of-entry calculus for new microcontroller suppliers entering European industrial channels. STMicroelectronics leverages its integrated fabrication footprint in France and Italy to sustain margin control across automotive-grade 32-bit lines. Infineon Technologies anchors its position through captive silicon carbide expertise tied to powertrain controllers. NXP Semiconductors dominates secure connectivity portfolios that channel into payment and vehicle-access applications.
A microcontroller integrates a processor core, volatile and non-volatile memory, and programmable input-output peripherals onto a single semiconductor die, typically manufactured through 40nm to 90nm CMOS processes at foundries or captive fabs. It executes real-time control tasks in embedded systems where deterministic response and minimal power draw matter more than raw compute throughput. 32-bit architectures command the largest revenue share as automotive ECU complexity rises, while IoT-enabled wireless communication variants represent the fastest-expanding technology tier. Energy harvesting interfaces remain nascent but carry above-average margins in medical device and industrial sensor deployments.
EMA equipment standards, CE marking requirements under the EU Medical Device Regulation, and REACH substance restrictions collectively shape product roadmaps and qualification timelines for microcontroller vendors serving European end markets. The EU AI Act introduces new conformity obligations for edge devices with autonomous decision-making capabilities, directly affecting embedded AI accelerator integration. Stakeholders must monitor how the F-Gas Regulation and evolving Ecodesign directives alter thermal management and packaging specifications for high-reliability controllers.
Market Dynamics
The EU Green Deal is compressing design cycles for automotive-grade microcontrollers as OEMs race to electrify powertrains while satisfying REACH substance restrictions and tightening Ecodesign efficiency mandates.
Growth Catalysts
- Electric powertrain mandates:Germany's KBA and France's DGEC are accelerating embedded controller deployment across battery management and motor control systems.
- REACH compliance barriers:ECHA substance restrictions are locking out Asian competitors without European fabrication footprints, concentrating demand among integrated suppliers.
- Industrial IoT retrofit waves:Germany's industrial corridor is replacing legacy 8-bit units with 32-bit wireless-enabled controllers for predictive maintenance applications.
Market Restraints
- Silicon carbide substrate scarcity:Powertrain controller manufacturers face input cost volatility as SiC wafer supply concentrates among three global vendors.
- Foundry concentration risk:Mature-node CMOS capacity at 40-90nm remains concentrated in Taiwan and South Korea, exposing European fabless designers to geopolitical supply disruption.
- Legacy 8-bit substitution ceiling:Cost-sensitive appliance and white-goods segments resist 32-bit migration despite performance advantages.
Strategic Opportunities
- Medical device edge AI:The EU AI Act is creating conformity-driven demand for embedded neural accelerators in diagnostic equipment across Switzerland and the Netherlands.
- Energy harvesting integration:Industrial sensor networks in Scandinavia are adopting photovoltaic and thermal harvester interfaces for battery-free operation.
- F-Gas thermal management:Evolving refrigeration regulations are opening design wins for high-temperature-rated controllers in commercial HVAC systems.
Industry Challenges
- Functional safety certification backlog:ISO 26262 ASIL-D qualification timelines for automotive MCUs now stretch 18-24 months, delaying revenue recognition.
- Legacy fieldbus integration friction:Factory automation upgrades require protocol translation layers between new wireless controllers and existing PROFIBUS/Modbus installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Microcontroller Market |
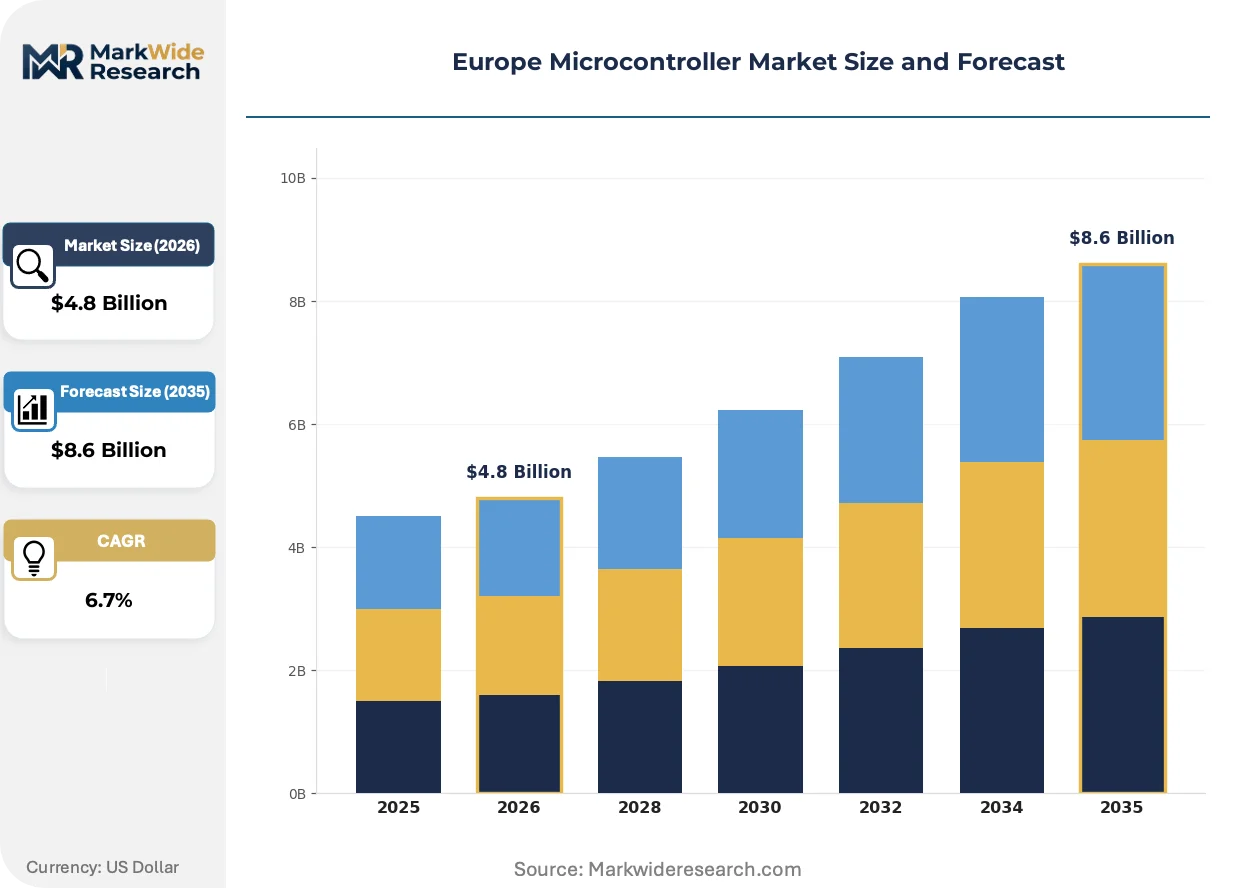
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 16-Bit, 32-Bit, 8-Bit, Digital Signal Controllers Application: Consumer Electronics, Automotive, Industrial Automation, Medical Devices End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators Technology: Embedded Systems, IoT, Wireless Communication, Energy Harvesting |
| Companies Covered | NXP Semiconductors, STMicroelectronics, Infineon Technologies, Microchip Technology, Renesas Electronics, Texas Instruments, Arm Limited, Analog Devices, Silicon Labs, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Microcontroller Market Trends and Innovations
Edge-native architectures are displacing cloud-dependent control models across European industrial and automotive installations, with deterministic real-time response becoming the decisive specification.
RISC-V open instruction set architectures are overtaking proprietary ARM cores in cost-optimized industrial controllers. German automation OEMs are qualifying RISC-V-based MCUs for non-safety-critical I/O modules. This shift is overtaking traditional licensing models and compressing royalty burdens for mid-volume European suppliers.
The EU AI Act's conformity obligations for autonomous edge devices are forcing embedded accelerator integration into medical and automotive controller roadmaps. Manufacturers must document decision transparency and fail-safe behaviors for classification as high-risk systems. French diagnostic equipment vendors are front-loading this compliance to secure early-mover positioning.
Direct procurement from semiconductor vendors is fragmenting traditional distribution channels for high-volume automotive programs. Tier-1 suppliers in Stuttgart and Munich are negotiating long-term supply agreements that bypass authorized distributors. This pattern is most visible in Germany's automotive belt where OEMs seek supply security over channel flexibility.
Europe Microcontroller Market Segmentation
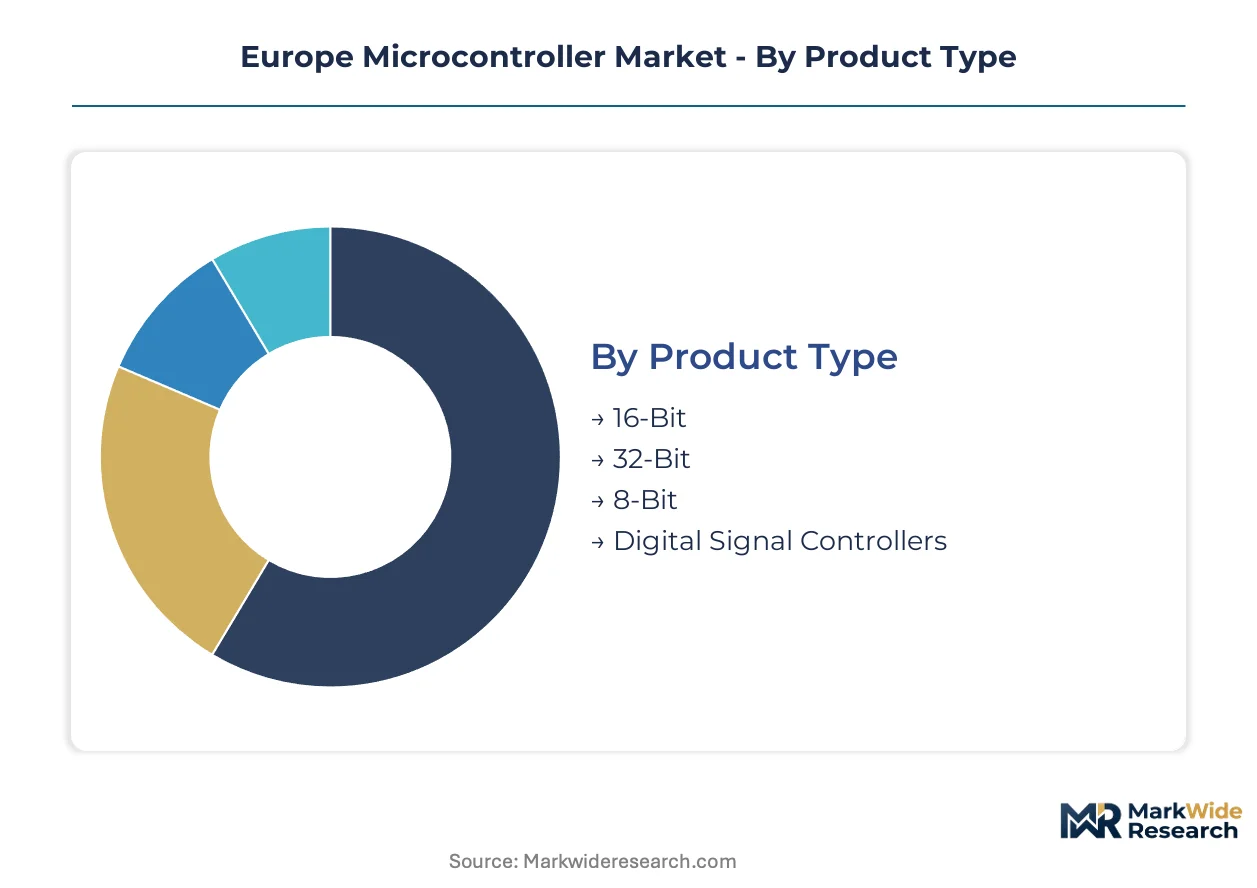
Microcontroller segmentation in Europe reflects divergent technical requirements across automotive safety-critical systems and cost-optimized consumer applications. The report dissects four intersecting dimensions—product architecture, deployment context, procurement channel, and connectivity technology—that collectively determine supplier positioning and margin capture.
Product Type:
Standardization dominates at the low end, while automotive and industrial segments demand extensive customization around memory configuration and peripheral integration.
- 32-Bit:ARM Cortex-M and proprietary architectures handle complex real-time control in electric powertrain ECUs and factory automation nodes. German automotive OEMs specify these for battery management systems under KBA electrification mandates. REACH-compliant fabrication footprints in France and Italy concentrate supply among integrated European vendors.
- 8-Bit:Mature architectures persist in cost-constrained appliance controls and basic sensor interfaces. White-goods manufacturers in Poland and Turkey resist migration despite 32-bit performance advantages, capping average selling price erosion.
- 16-Bit:Transitional positioning between legacy 8-bit and feature-rich 32-bit lines, serving mid-tier industrial motor controls where peripheral count matters more than raw throughput.
- Digital Signal Controllers:Specialized cores with DSP acceleration target motor control and power conversion in variable-frequency drives across Germany's industrial corridor.
Leading the category by volume: 32-Bit. Expanding most quickly: Digital Signal Controllers.
Application:
Margin structure inverts across this dimension—automotive commands certification premiums while consumer electronics extracts cost efficiency through scale.
- Automotive:Powertrain electrification, ADAS domain controllers, and body electronics require ISO 26262 ASIL-D qualification stretching 18-24 months. French and German OEMs specify 32-bit automotive-grade units with extended temperature ranges.
- Industrial Automation:Predictive maintenance retrofit waves in Germany's Ruhr and Bavarian industrial belts drive wireless-enabled 32-bit replacement of legacy 8-bit fieldbus nodes.
- Consumer Electronics:Smart home devices and wearable peripherals in Netherlands and Scandinavian markets prioritize cost-optimized 8-bit and 16-bit solutions with minimal peripheral integration.
- Medical Devices:Diagnostic equipment across Switzerland and the Netherlands faces EU AI Act conformity obligations for edge devices with autonomous decision-making capabilities, accelerating embedded neural accelerator integration.
Automotive generates the highest revenue per unit. Industrial Automation shows the steepest volume expansion trajectory.
End User:
Procurement concentration varies sharply—direct OEM engagement fragments traditional distribution while Tier-1 suppliers intermediate safety-critical programs.
- OEMs:Stuttgart and Munich automotive manufacturers negotiate long-term supply agreements bypassing authorized distributors, seeking supply security over channel flexibility.
- Tier-1 Suppliers:Continental, Bosch, and Valeo intermediate microcontroller specification for powertrain and chassis modules, absorbing functional safety certification burdens.
- System Integrators:German automation specialists bundle controllers with proprietary software stacks for smart factory deployments, capturing value through integration rather than silicon margin.
- Aftermarket Providers:Replacement controllers for legacy vehicle electronics and industrial equipment, constrained by reverse-engineering costs and sparse documentation.
OEMs dominate premium automotive procurement. System Integrators are gaining share fastest in industrial IoT retrofit programs.
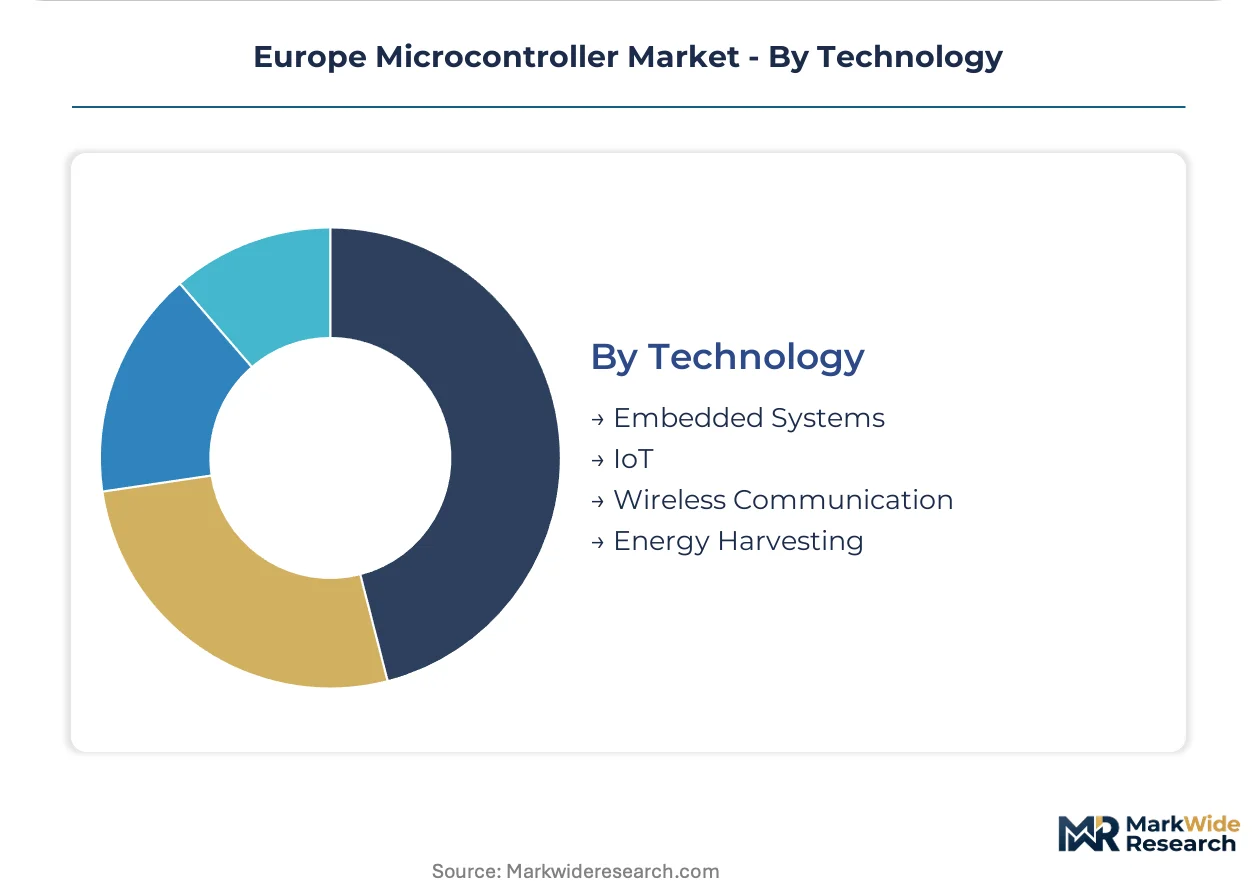
Technology:
Connectivity integration separates commodity controllers from margin-accretive platforms, with wireless and energy harvesting commanding above-average pricing.
- IoT:Wireless-enabled 32-bit units with integrated Bluetooth Low Energy and Thread protocols serve predictive maintenance and asset tracking across German factory floors.
- Energy Harvesting:Photovoltaic and thermal harvester interfaces enable battery-free operation in Scandinavian industrial sensor networks, carrying above-average margins despite nascent volume.
- Embedded Systems:Deterministic real-time architectures without wireless connectivity, serving cost-optimized appliance and basic automotive body electronics.
- Wireless Communication:Dedicated RF-integrated controllers for smart metering and building automation, subject to CE marking and RED compliance.
Embedded Systems leads by shipment volume. Energy Harvesting posts the fastest growth rate among technology tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive-grade microcontrollers concentrates in Germany's industrial corridor, where powertrain electrification mandates from KBA accelerate embedded controller deployment across battery management and motor control systems.
Germany
Automotive OEMs in Stuttgart and Munich negotiate direct supply agreements for 32-bit automotive-grade units, bypassing traditional distribution channels. KBA electrification timelines compress design cycles for ISO 26262 ASIL-D qualified controllers. The Ruhr and Bavarian industrial belts drive predictive maintenance retrofits, replacing legacy 8-bit fieldbus nodes with wireless-enabled 32-bit controllers.
France
DGEC mandates accelerate embedded controller deployment in electric powertrains, while diagnostic equipment vendors in Paris and Lyon front-load EU AI Act compliance for embedded neural accelerators. REACH-compliant fabrication footprints in Grenoble and Rousset concentrate supply among integrated European vendors. French OEMs specify extended temperature-range controllers for powertrain electrification programs.
Italy
Industrial automation clusters in Lombardy and Emilia-Romagna demand 32-bit wireless-enabled controllers for smart factory deployments. CE marking requirements under EU machinery directives shape product roadmaps for controller vendors serving Italian end markets. STMicroelectronics leverages its captive fabrication footprint in Agrate Brianza to sustain margin control across automotive-grade lines.
Switzerland
Diagnostic equipment manufacturers across Zurich and Basel face EU AI Act conformity obligations for edge devices with autonomous decision-making capabilities. Swissmedic regulations for medical devices intersect with REACH substance restrictions to elevate qualification barriers. Energy harvesting interfaces carry above-average margins in medical sensor deployments across Swiss industrial corridors.
Netherlands
Smart home device manufacturers in Eindhoven and Amsterdam prioritize cost-optimized 8-bit and 16-bit solutions with minimal peripheral integration. CE marking and RED compliance for wireless communication controllers shape procurement specifications. NXP Semiconductors anchors secure connectivity portfolios channeling into payment and vehicle-access applications from its Dutch operational base.
Europe Microcontroller Market Competitive Landscape
European producers anchor one tier; Asian specialists hold foundry-dependent positions at the mature-node CMOS level. The vendor base stratifies between integrated fabricators with REACH-compliant European footprints and fabless designers exposed to Taiwan and South Korea capacity concentration. Three archetypes dominate: captive fabrication specialists, secure connectivity portfolio holders, and powertrain controller vendors with silicon carbide expertise. Competitive moves center on long-term supply agreement negotiation and embedded AI accelerator integration to satisfy EU AI Act conformity obligations.
Within the integrated fabrication tier, STMicroelectronics exemplifies the captive production archetype through its French and Italian manufacturing footprint. Infineon Technologies occupies a position tied to powertrain controller specialization. NXP Semiconductors represents the secure connectivity portfolio anchor. These three European-based entities collectively illustrate how REACH-compliant fabrication geography determines competitive positioning in automotive and industrial channels.
| Leading Market Players |
|---|
| NXP Semiconductors |
| STMicroelectronics |
| Infineon Technologies |
| Microchip Technology |
| Renesas Electronics |
| Texas Instruments |
| Arm Limited |
| Analog Devices |
| Silicon Labs |
| Others |
Pricing and Supply Chain Analysis
Integrated European fabricators with captive production in France and Italy exercise pricing discipline through REACH-compliant supply security, while fabless designers absorb volatility from Taiwan and South Korea foundry concentration. Long-term supply agreements between Stuttgart automotive OEMs and silicon vendors now embed lead-time premiums that reward fabrication geography over spot-market flexibility.
Pricing Analysis
Premium pricing for sub-12-week lead times separates automotive-grade 32-bit units from standard industrial inventory, with KBA electrification timelines compressing procurement cycles. Three-tier pricing structure across ASIL-D certified, industrial-grade, and consumer-tier controllers reflects ISO 26262 qualification investment and temperature-range specifications. Cost compression in 8-bit appliance segments runs through Polish and Turkish white-goods manufacturers resisting 32-bit migration. Tier-1 suppliers in Germany's automotive belt show lowest price sensitivity due to supply security priorities, while Scandinavian industrial sensor buyers negotiate aggressively on energy harvesting interfaces.
Supply Chain Analysis
Direct-to-OEM channels handle high-volume automotive demand from Stuttgart and Munich manufacturers, bypassing authorized distributors for powertrain controller programs. Mature-node CMOS fabrication concentrates in Taiwan and South Korea, exposing European fabless designers to geopolitical disruption risk. Silicon carbide wafer supply feeds from three global vendors, creating single-source vulnerability for powertrain controller manufacturers. Raw material dependencies span 40-90nm CMOS capacity, SiC substrates, and noble-metal packaging alloys. Distribution runs through tiered channels: direct OEM engagement for automotive, system integrator bundling for industrial IoT, and traditional electronics distribution for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
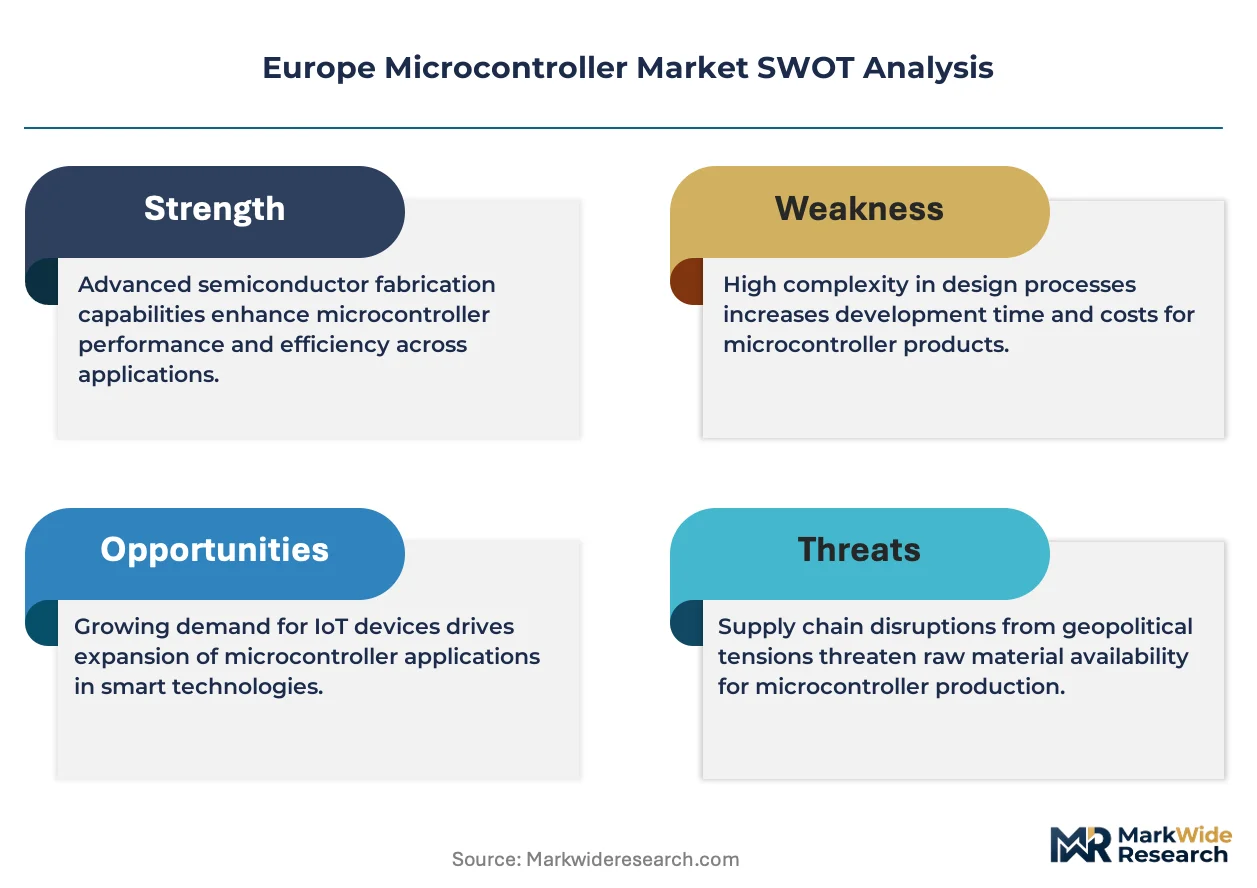
Mature-node foundry scarcity at 40-90nm geometry props pricing power for integrated European fabricators with captive capacity, while fabless competitors face allocation uncertainty from Taiwan and South Korea concentration.
For Market Incumbents: Extend REACH-compliant fabrication footprints in France and Italy to capture automotive OEM direct procurement shifts away from distribution channels. Lock in multi-year supply agreements with KBA-timeline powertrain programs before SiC substrate scarcity intensifies. Anchor defensive positioning through embedded AI accelerator roadmaps that satisfy EU AI Act conformity obligations for diagnostic equipment vendors.
For New Entrants and Emerging Players: Enter via energy harvesting interface specialization for Scandinavian industrial sensor networks, where above-average margins persist despite nascent volume. Target medical device edge AI segments in Switzerland and the Netherlands where EU AI Act compliance creates qualification barriers for established suppliers. Pursue RISC-V core qualification with German automation OEMs seeking royalty relief on non-safety-critical I/O modules.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless designers with automotive qualification progress and Taiwan foundry relationships in Germany's industrial corridor. Long-term viability hinges on backward integration into SiC substrate supply or captive fabrication migration to European REACH-compliant nodes. Monitor KBA electrification timeline acceleration and ECHA substance restriction expansion as inflection signals for capacity investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fabrication Expansion | REACH-compliant French and Italian capacity secures automotive OEM direct procurement relationships. |
| Embedded AI Accelerator Integration | EU AI Act conformity obligations force neural accelerator roadmaps for diagnostic equipment vendors. |
| RISC-V Architecture Adoption | German automation OEMs qualify open-instruction cores to compress ARM royalty burdens. |
| Long-term Supply Agreement Negotiation | Stuttgart and Munich manufacturers bypass distributors for powertrain controller supply security. |
| Energy Harvesting Interface Development | Scandinavian industrial sensor networks adopt battery-free photovoltaic and thermal harvester controllers. |
Research Methodology
Multi-period observation of KBA electrification timelines, ECHA substance restriction trajectories, and foundry capacity allocation patterns anchored the trend analysis, supplemented by interviews with automotive platform engineers, Tier 1 supplier procurement leads, industrial automation system integrators, and semiconductor fabrication operations directors. Secondary validation drew from SEC semiconductor filings, ECHA restriction candidate lists, EU Green Deal implementation progress reports, and IHS Markit vehicle production databases. Bottom-up unit shipment estimates across 32-bit, 16-bit, and 8-bit architectures triangulated against top-down European semiconductor consumption figures.
Segment-weighting approaches distributed value and volume across product architecture, application vertical, and connectivity technology tiers throughout the forecast period. CAGRs derived from regression analysis against electrification penetration curves, industrial IoT retrofit adoption rates, and REACH compliance cost pass-through elasticity. Modeled inputs included ISO 26262 ASIL-D qualification timeline compression, SiC substrate supply concentration effects, and RISC-V royalty displacement velocity in German automation channels.
Revisions become necessary when Taiwan foundry allocation disruptions materialize, ECHA expands substance restrictions beyond current candidate lists, or KBA accelerates powertrain electrification timelines beyond modeled scenarios. Forecasts embed assumptions around mature-node CMOS capacity expansion, automotive direct procurement pattern stability, and EU AI Act enforcement consistency. Practitioners should monitor Ecodesign directive evolution, F-Gas Regulation thermal management specification changes, and SiC wafer vendor consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
Middle East Distribution Panel Market