
 North America MLCC Market | 2026-2036
North America MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
North America MLCC Market Insights
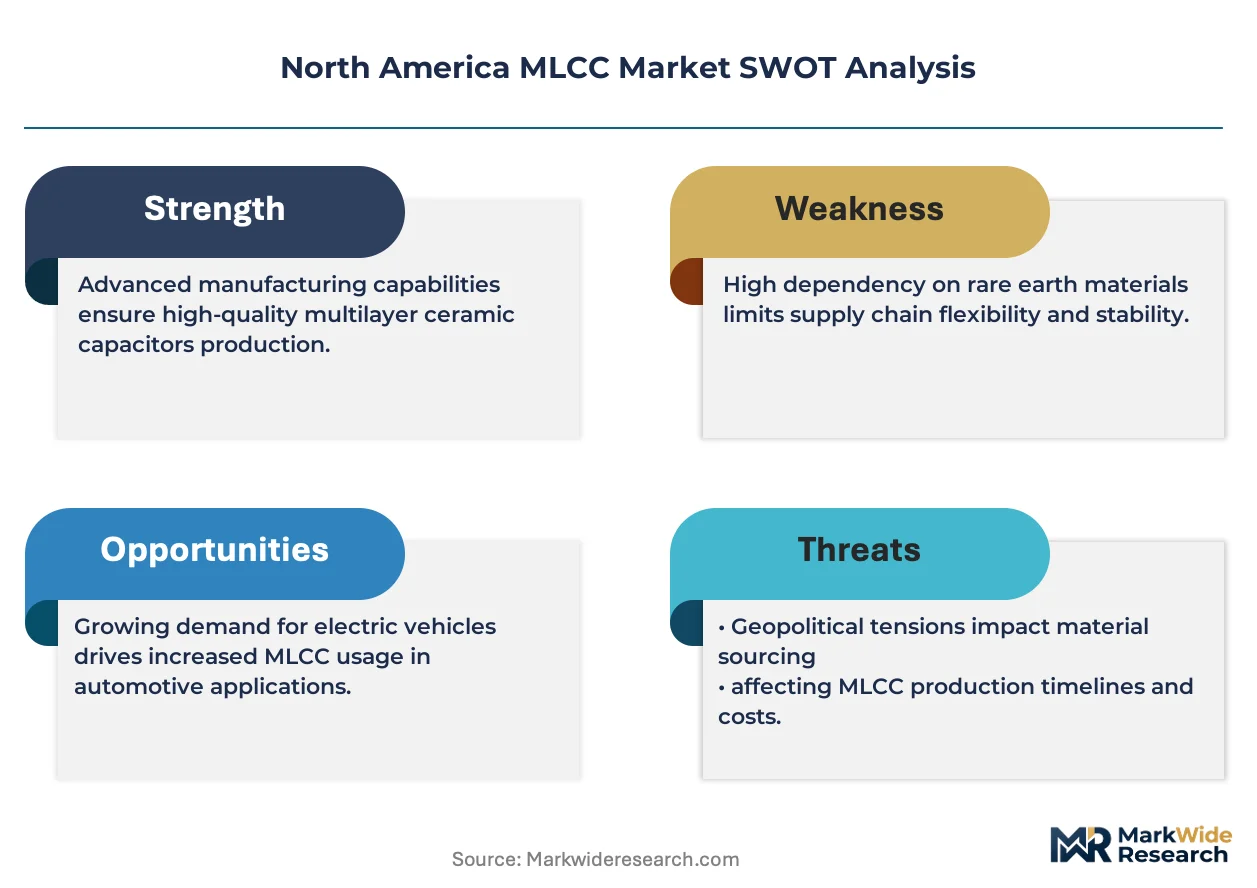
Base metal electrode formulations are expanding their share against traditional precious metal designs across the North America MLCC landscape. Murata Manufacturing sustains technology leadership through advanced thin-layer dielectric processing for automotive-grade components. Samsung Electro-Mechanics leverages its captive materials science capabilities to anchor high-reliability supply into Detroit-area EV programs. TDK Corporation specializes in high-voltage MLCC architectures that dominate grid-tied energy storage applications.
Multilayer ceramic capacitors are passive electronic components built from alternating layers of ceramic dielectric and metal electrode materials, typically achieving capacitance densities exceeding 100 microfarads per cubic centimeter in compact surface-mount packages. These components filter noise, stabilize voltage rails, and couple signals across printed circuit boards in everything from smartphones to traction inverters. Consumer electronics applications retain the largest volume footprint though automotive-grade segments command premium pricing due to AEC-Q200 qualification requirements and extended temperature specifications. High-frequency technology variants are capturing disproportionate investment as 5G base station deployments and millimeter-wave radar modules multiply layer counts and precision tolerances.
FCC equipment authorization rules govern electromagnetic interference compliance for MLCC-containing devices sold in the United States, while NHTSA functional safety standards propagate automotive-specific component traceability requirements through the supply chain. EPA rules on hazardous substance restrictions affect electrode material selections and end-of-life recycling obligations for manufacturers serving the region. Stakeholders must monitor how NHTSA's evolving autonomous vehicle guidance reshapes reliability specifications for mission-critical capacitor applications in braking and steering systems.
Market Dynamics
EV powertrain electrification is concentrating MLCC demand into automotive-grade specifications, tightening reliability thresholds while displacing legacy aluminum electrolytic capacitors across traction inverters and onboard chargers.
Growth Catalysts
- EPA emissions standards:NHTSA fuel economy rules force automotive OEMs to densify power electronics, multiplying high-temperature MLCC counts per vehicle.
- Base metal electrode formulations:Nickel-copper electrode systems slash material costs versus palladium-silver designs, accelerating adoption across cost-sensitive automotive programs.
- Michigan-Ohio automotive corridor:Proximity to Detroit-area EV assembly plants compresses logistics lead times for just-in-time capacitor supply.
Market Restraints
- Palladium price volatility:Precious metal electrode costs swing with South African mining output, squeezing margins for non-BME product lines.
- Japan-Korea supply concentration:Overreliance on East Asian ceramic powder and firing equipment vendors exposes North American buyers to geopolitical disruption.
- Dielectric thickness floor:Sub-micron layer deposition yields diminish below 0.3 micrometers, capping capacitance density gains in standard 0603 packages.
Strategic Opportunities
- Mexico nearshoring:Monterrey and Guanajuato capacitor assembly investments capture USMCA duty advantages while hedging Asia-Pacific logistics risk.
- Grid-tied energy storage:Utility-scale battery inverters demand high-voltage MLCC banks rated above 1 kilovolt DC, opening premium pricing tiers.
- IRA domestic content credits:Inflation Reduction Act incentives for North American battery supply chains pull capacitor sourcing into qualified manufacturing zones.
Industry Challenges
- AEC-Q200 certification timelines:Eighteen-month qualification cycles for automotive-grade components lag EV platform development cadences.
- Thin-layer process engineering talent:Deep expertise in tape-casting and cofiring for sub-micron dielectrics concentrates among retiring Japanese process engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America MLCC Market |
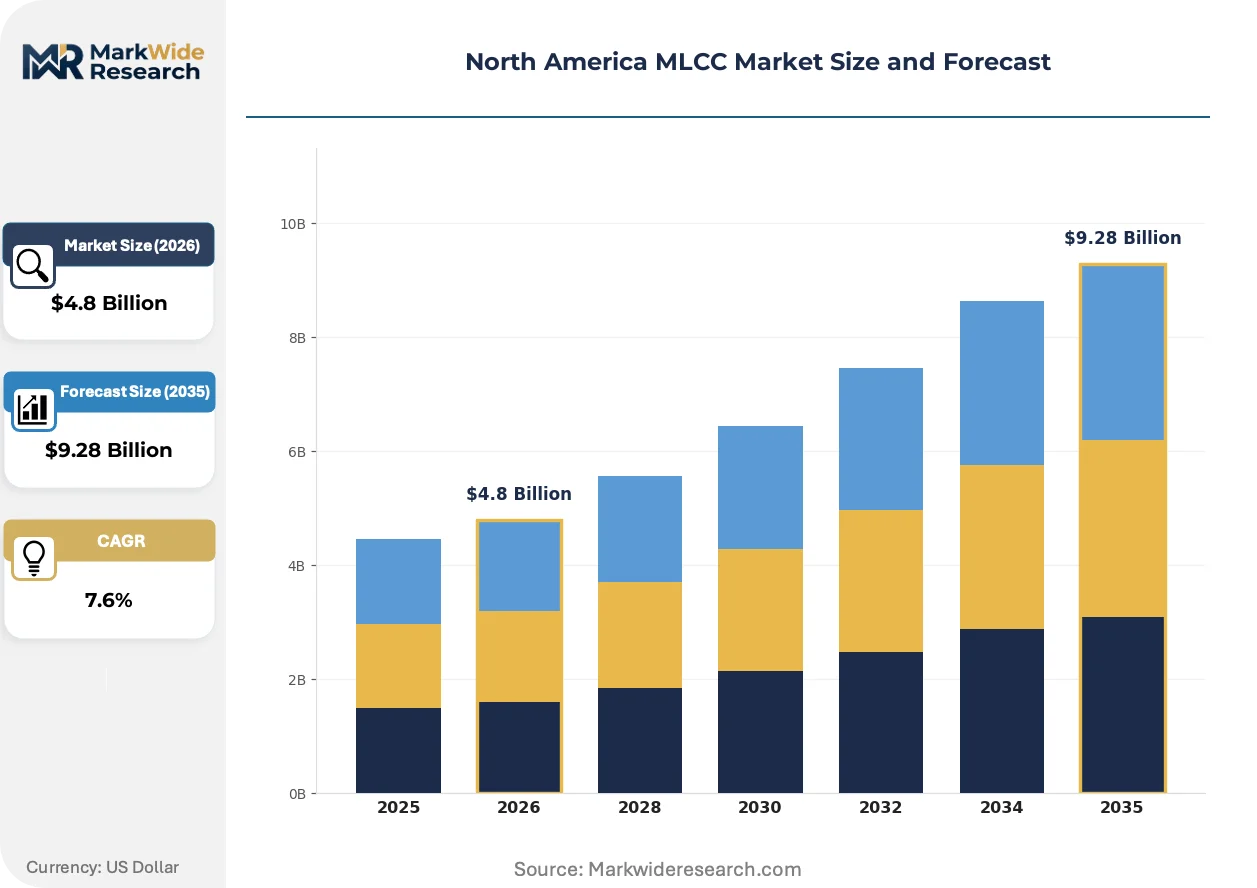
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multilayer Capacitors, Ceramic Capacitors, Tantalum Capacitors, Film Capacitors End User: Consumer Electronics, Automotive, Telecommunications, Industrial Application: Power Supply, Signal Coupling, Noise Filtering, Energy Storage Technology: Surface Mount, Through Hole, High Voltage, High Frequency |
| Companies Covered | Samsung Electro-Mechanics Co., Ltd., KYOCERA AVX Components Corporation, Murata Manufacturing Co., Ltd., Johanson Dielectrics, Inc., MARUWA Co., Ltd., TDK Corporation, Yageo Corporation, Walsin Technology Corporation, Taiyo Yuden Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America MLCC Market Trends and Innovations
Material science breakthroughs and regulatory tightening are compressing traditional capacitor architectures while opening new specification tiers across automotive and industrial segments.
Copper-terminated MLCC designs with nickel barrier layers are modularizing package footprints across 5G base station power amplifiers. Telecom equipment manufacturers in California and Texas are consolidating discrete component counts into integrated capacitor arrays. This modularizing architecture halves board space while demanding tighter capacitance matching across temperature extremes.
NHTSA functional safety standards propagate traceability requirements through automotive MLCC supply chains. Component lot tracking now extends from ceramic powder batch to finished vehicle VIN. Tier-one suppliers in Michigan and Ontario are deploying blockchain-based pedigree systems to satisfy audit demands.
Automotive buyers are consolidating supplier relationships around vertically integrated capacitor manufacturers capable of in-house ceramic formulation. Long-term supply agreements now specify three-year price locks with volume commitments. This concentration is most visible among Detroit-area EV powertrain programs qualifying second-source BME suppliers.
North America MLCC Market Segmentation
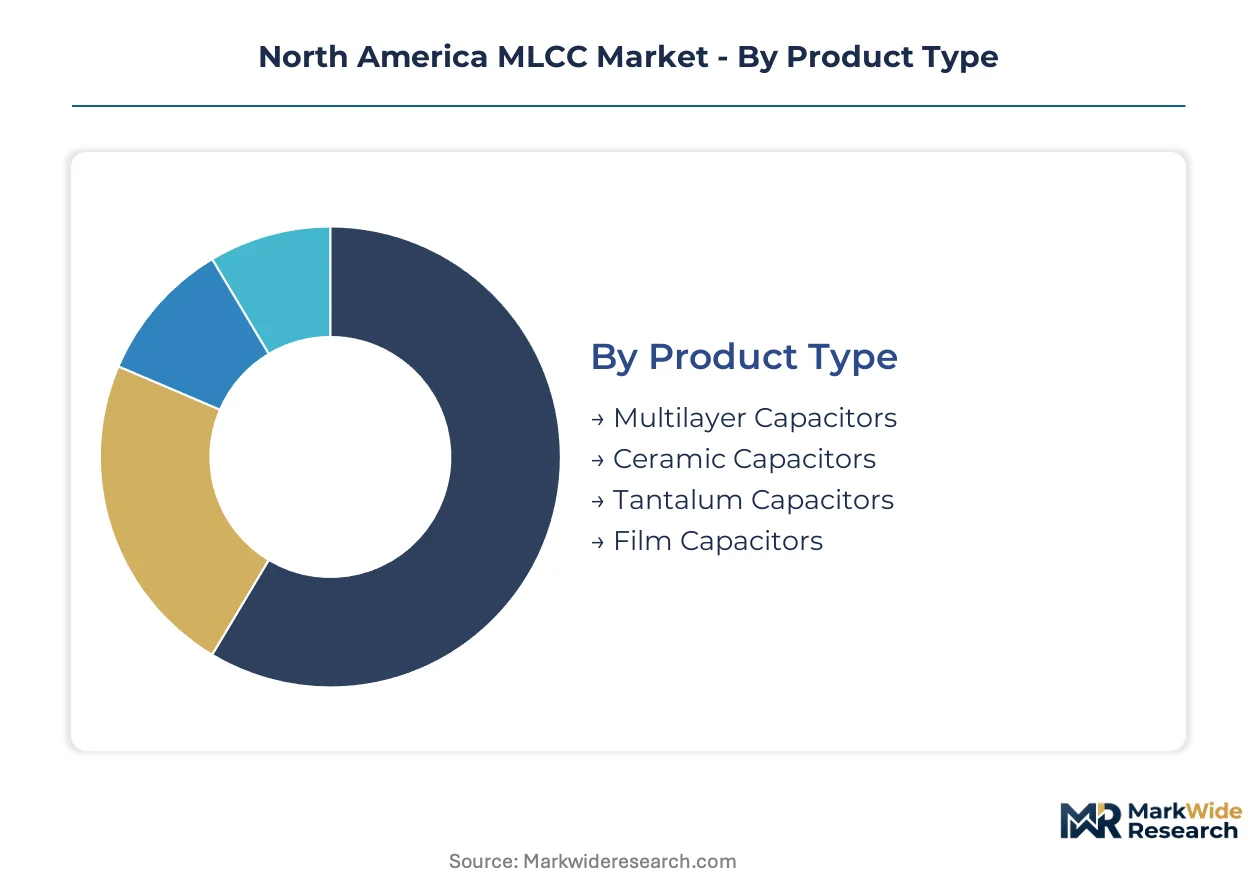
MLCC segmentation reveals how capacitor specifications diverge across reliability grades, mounting technologies, and voltage tolerances. Each axis shapes procurement patterns, qualification timelines, and margin structures differently across North American supply chains.
Product Type:
Dielectric material and electrode architecture define performance ceilings and cost floors across passive component categories.
- Multilayer Capacitors:Alternating ceramic and metal layers achieve capacitance densities above 100 microfarads per cubic centimeter in compact surface-mount footprints. Automotive powertrain electrification in Michigan and Ohio is concentrating procurement into AEC-Q200-qualified MLCCs with nickel-copper electrodes.
- Ceramic Capacitors:Single-layer and disc configurations serve cost-sensitive filtering applications where volumetric efficiency matters less than absolute price. Consumer electronics assembly in Mexico's Guanajuato corridor pulls standard-grade ceramic volumes for smartphone charger modules.
- Tantalum Capacitors:Manganese dioxide and polymer cathode variants deliver stable capacitance across extended temperature ranges for aerospace and medical devices.
- Film Capacitors:Polypropylene and polyester dielectrics dominate high-voltage DC-link applications in grid-tied inverters across Texas wind farms.
Multilayer capacitors lead on scale; ceramic capacitors lead on momentum.
End User:
Customer reliability requirements stratify pricing power and contract structures across North American demand pools.
- Consumer Electronics:Smartphones, laptops, and wearables drive the highest unit volumes with tight tolerance requirements for miniaturized boards. California design houses specify 0201 and 01005 case sizes for next-generation mobile devices.
- Automotive:Under-hood electronics and EV powertrains demand AEC-Q200 qualification with temperature ratings from minus 55 to 150 degrees Celsius. EPA emissions standards and NHTSA fuel economy rules force densification of onboard chargers and traction inverters.
- Telecommunications:5G base station deployments in Texas and California multiply layer counts for millimeter-wave power amplifiers.
- Industrial:Motor drives, programmable logic controllers, and robotics systems require extended life ratings under vibration and thermal cycling.
Consumer electronics leads on scale; automotive leads on momentum.
Application:
Functional role on the printed circuit board determines electrical stress profiles and failure mode criticality.
- Power Supply:Input filtering, output smoothing, and bulk capacitance stabilize voltage rails across switching converters. Data center server power supplies in Virginia and Oregon specify low-ESR MLCCs for multiphase buck regulators.
- Signal Coupling:AC coupling capacitors block DC bias while passing high-frequency signals between circuit stages. Telecommunications equipment in Texas demands tight capacitance matching for differential pairs.
- Noise Filtering:Decoupling networks suppress electromagnetic interference across digital and analog domains. FCC equipment authorization rules govern EMI compliance for filtering configurations.
- Energy Storage:Snubber circuits and pulse power applications require high volumetric efficiency for transient energy absorption.
Power supply leads on scale; energy storage leads on momentum.
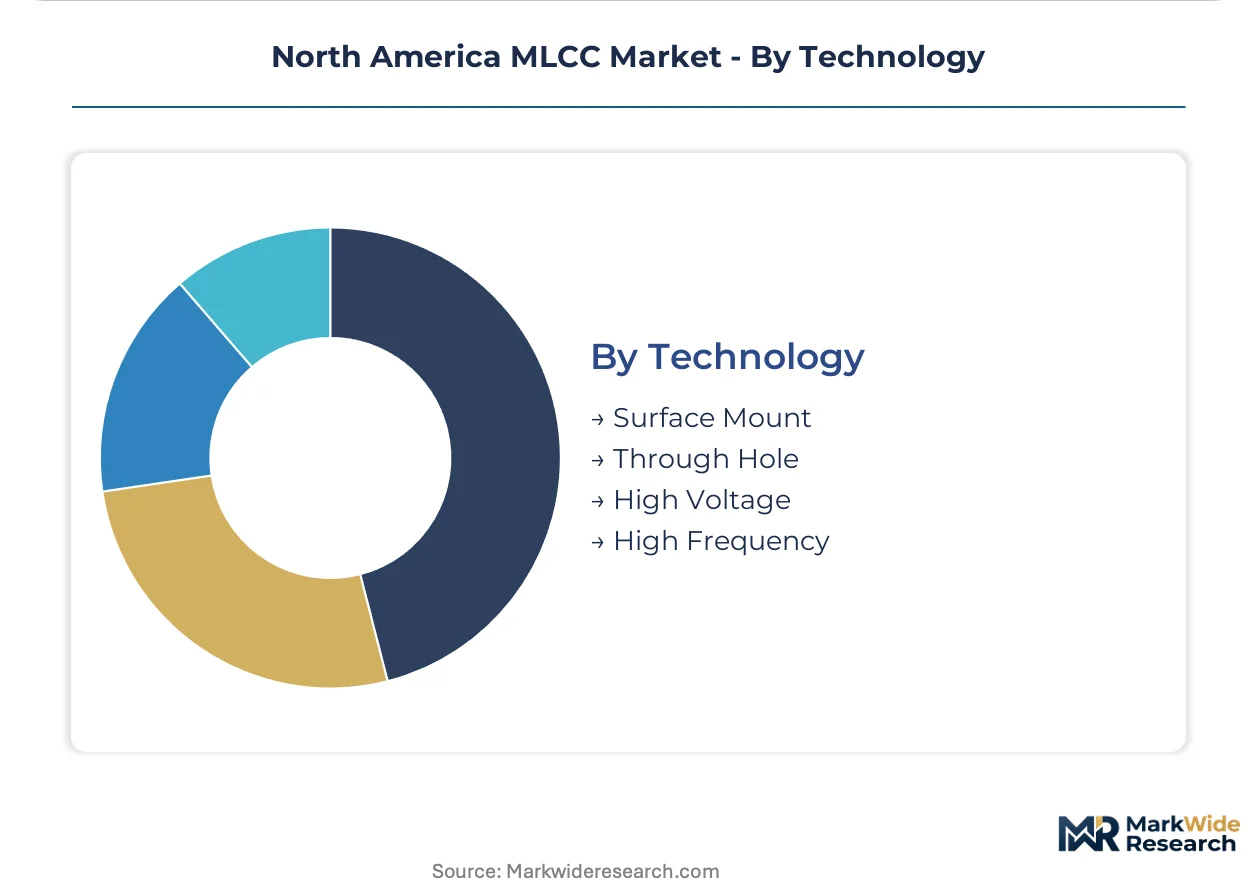
Technology:
Mounting methodology and electrical specification tiers separate commodity volumes from premium pricing brackets.
- Surface Mount:Tape-and-reel packaging enables high-speed pick-and-place assembly across automated production lines. Automotive tier-one suppliers in Michigan have nearly completed the transition from through-hole to surface-mount for all new EV platforms.
- High Voltage:Dielectric thickness engineering achieves ratings above 1 kilovolt DC for solar inverters and electric vehicle onboard chargers. Grid-tied energy storage installations in California and Texas specify high-voltage MLCC banks for DC-link stabilization.
- Through Hole:Radial and axial leaded packages persist in repair markets and high-vibration industrial environments.
- High Frequency:Low equivalent series inductance designs serve 5G millimeter-wave and automotive radar modules.
Surface mount leads on scale; high voltage leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Michigan's automotive corridor anchors North American MLCC procurement, with Detroit-area EV powertrain programs driving AEC-Q200-qualified component demand. EPA emissions standards and NHTSA fuel economy rules force densification of onboard chargers and traction inverters. The analysis covers three countries where capacitor supply chains concentrate.
United States
California's semiconductor design clusters specify 0201 and 01005 case sizes for next-generation mobile devices. FCC equipment authorization rules govern electromagnetic interference compliance for MLCC-containing devices sold nationwide. Data center server power supplies in Virginia and Oregon pull low-ESR MLCCs for multiphase buck regulators.
Canada
Ontario's automotive electronics suppliers serve Detroit-area EV assembly plants through integrated cross-border supply chains. Health Canada's medical device regulations drive demand for high-reliability capacitors in diagnostic equipment manufacturing. Toronto-Waterloo tech corridor companies prototype 5G millimeter-wave modules requiring tight capacitance matching.
Mexico
Guanajuato's consumer electronics assembly corridor pulls standard-grade ceramic volumes for smartphone charger modules. USMCA duty advantages accelerate Monterrey capacitor assembly investments hedging Asia-Pacific logistics risk. Baja California maquiladoras filter noise suppression components for telecommunications equipment bound for US markets.
North America MLCC Market Competitive Landscape
Strategic partnerships dominate the current landscape as Japanese and Korean manufacturers anchor automotive-grade supply into Detroit-area programs. The vendor base concentrates among vertically integrated ceramic formulators with captive powder production and firing capabilities. Two archetypes prevail: scale-driven commodity suppliers serving consumer electronics and premium-tier specialists commanding AEC-Q200-qualified automotive pricing. Capacity expansion and backward integration into ceramic powder production represent the dominant competitive vectors.
Within the premium-tier automotive vector, Murata Manufacturing Co., Ltd. and TDK Corporation exemplify Japanese vertically integrated specialists, while Samsung Electro-Mechanics Co., Ltd. represents Korean scale-driven fabrication. These three anchors demonstrate how geographic clustering of ceramic science expertise shapes competitive positioning across North American EV supply chains.
| Leading Market Players |
|---|
| Samsung Electro-Mechanics Co., Ltd. |
| KYOCERA AVX Components Corporation |
| Murata Manufacturing Co., Ltd. |
| Johanson Dielectrics, Inc. |
| MARUWA Co., Ltd. |
| TDK Corporation |
| Yageo Corporation |
| Walsin Technology Corporation |
| Taiyo Yuden Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Detroit-area EV powertrain procurement teams concentrate buying power around AEC-Q200-qualified suppliers, locking in three-year contract structures with volume-commitment pricing. This buyer consolidation feeds backward into nickel-copper electrode cost negotiations and ceramic powder sourcing terms.
Pricing Analysis
Input-cost pass-through from palladium and nickel powder markets governs margin splits between electrode suppliers and finished capacitor manufacturers. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade levels separates AEC-Q200-certified premiums from standard commercial tolerances. Cost compression in consumer-grade segments is intensifying because Mexico nearshoring investments expand assembly capacity. Automotive OEMs show least price sensitivity due to mission-critical reliability requirements, while smartphone charger manufacturers in Guanajuato operate on tightest margins.
Supply Chain Analysis
End-of-life MLCC recovery flows remain underdeveloped across North American electronics recycling infrastructure, with ceramic-to-metal separation costs exceeding recovered material value. Manufacturing concentration rests on Japan, South Korea, and Taiwan for ceramic powder, tape-casting equipment, and precision firing kilns. Raw material dependencies draw from South African palladium mines, Indonesian nickel laterite processing, and Chinese rare earth stabilizers. Single-source vulnerability around Japanese thin-layer dielectric expertise exposes Detroit-area EV programs to geopolitical disruption. Distribution runs through authorized distributors serving Michigan tier-one suppliers and direct OEM contracts for high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA emissions standards and NHTSA fuel economy rules tighten reliability thresholds faster than supply capacity expands. The Inflation Reduction Act domestic content credits accelerate this demand compression.
For Market Incumbents: Hedge against palladium price volatility by accelerating nickel-copper electrode qualification across remaining precious metal product lines. Secure captive ceramic powder supply through backward integration or long-term offtake agreements with Japanese material suppliers. Defensive consolidation around AEC-Q200 certification capacity protects margin structures from emerging Korean scale players. For New Entrants and Emerging Players: Begin with Mexico nearshoring assembly to capture USMCA duty advantages and compress logistics lead times for Detroit-area EV programs. Target grid-tied energy storage applications in Texas and California where high-voltage MLCC demand outpaces incumbent capacity expansion. Pursue qualification partnerships with Michigan tier-one suppliers seeking second-source BME suppliers. For Investors and Strategic Acquirers: Automotive OEMs are the most active acquirer in this space, pulling capacitor sourcing into qualified manufacturing zones for IRA compliance. Long-term viability centers on ceramic science expertise concentration among retiring Japanese process engineers. Acquisition target archetype: mid-cap specialists with AEC-Q200 qualification and captive powder formulation. Monitor NHTSA autonomous vehicle guidance evolution for reliability specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder | Captive barium titanate supply secures margin control against Japanese material concentration. |
| Mexico Nearshoring Expansion | Monterrey assembly investments capture USMCA advantages while hedging Asia-Pacific logistics risk. |
| AEC-Q200 Certification Acceleration | Eighteen-month qualification cycles must compress to match EV platform development cadences. |
| High-Voltage Dielectric Development | Grid-tied energy storage inverters demand MLCC banks rated above 1 kilovolt DC. |
| Blockchain Pedigree Implementation | Tier-one suppliers deploy lot tracking from ceramic powder batch to finished vehicle VIN. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged capacitor procurement managers at Detroit-area automotive tier-one suppliers, ceramic powder technical directors at Japanese material suppliers, MLCC plant managers in Mexico's Guanajuato corridor, and EV platform engineers at Michigan OEMs. Secondary validation drew from EPA emissions filings, NHTSA fuel economy rulemaking dockets, FCC equipment authorization databases, and USMCA trade flow records. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Comparable historical periods anchored the projection horizon to prior EV adoption cycles and automotive electronics densification waves. The analytical framework modeled segmentation across dielectric material, electrode architecture, end-user vertical, mounting technology, and voltage rating tiers. CAGRs derived from regression analysis against vehicle electrification penetration curves and power electronics component counts per platform. Forecast inputs included EPA regulatory stringency indices and NHTSA autonomous vehicle guidance timelines.
Several conditions sit outside the modeled scope, including unannounced trade policy shifts affecting Japan-Korea ceramic equipment flows and breakthrough solid-state capacitor technologies. Forecasts reflect assumptions around AEC-Q200 certification timeline stability and palladium price mean reversion. Practitioners should monitor NHTSA functional safety standard evolution and IRA domestic content credit rulemaking for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Coin Battery Holder Market
Electronic Components
Solder Paste for Mini LED Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
Acoustic Diaphragm Market
Electronic Components
Timing Relay Market
Electronic Components
Flexible Heater Market
Electronic Components
AC Adapter Market
Electronic Components
Breadboards Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
North America USB Retimer Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Switch Diode Market
Electronic Components
RAID Controller Card Market
Electronic Components
Braking Resistors Market