
 Audio and Visual Public Address System Market | 2026-2036
Audio and Visual Public Address System Market Size, Share, and Industry Trends Forecast 2026-2036
Audio and Visual Public Address System Market Analytics
Aftermarket service revenue is narrowing as manufacturers bundle cloud-based remote diagnostics with hardware contracts. Bosch Security Systems leverages its fire-safety distribution channels to cross-sell integrated PA installations across European infrastructure projects. TOA Corporation anchors its position in Asian transit markets through localized manufacturing and JIS-compliant acoustic engineering. Yamaha Corporation differentiates via proprietary digital signal processing platforms that unify audio and visual control under single-console management.
An audio and visual public address system combines electro-acoustic transducers, power amplification stages, and signal routing hardware to project voice and multimedia content across large spatial environments, typically operating at sound pressure levels exceeding 90 dB for intelligibility in reverberant spaces. The primary commercial purpose centers on emergency notification, passenger information, and live event reinforcement in facilities where direct communication fails due to scale or ambient noise. Wireless technology leads product-level margins due to installation cost savings in heritage buildings where cable routing proves prohibitive, while IP-based architectures represent the fastest-expanding technology category as facilities managers seek centralized monitoring across distributed campuses. Control systems capture concentrated margin pools because software licensing recurs annually and locks buyers into vendor ecosystems.
The FCC governs wireless spectrum allocation for microphone and intercom systems in the United States, with recent re-banding forcing hardware refreshes that accelerate digital migration. ETSI standards in Europe mandate electromagnetic compatibility and audio intelligibility thresholds for public safety installations, creating compliance barriers for non-certified suppliers. China's MIIT enforces GB standards for electromagnetic emissions and acoustic performance in transportation infrastructure. Stakeholders must monitor spectrum policy evolution and certification reciprocity agreements to anticipate replacement cycles and geographic market entry timing.
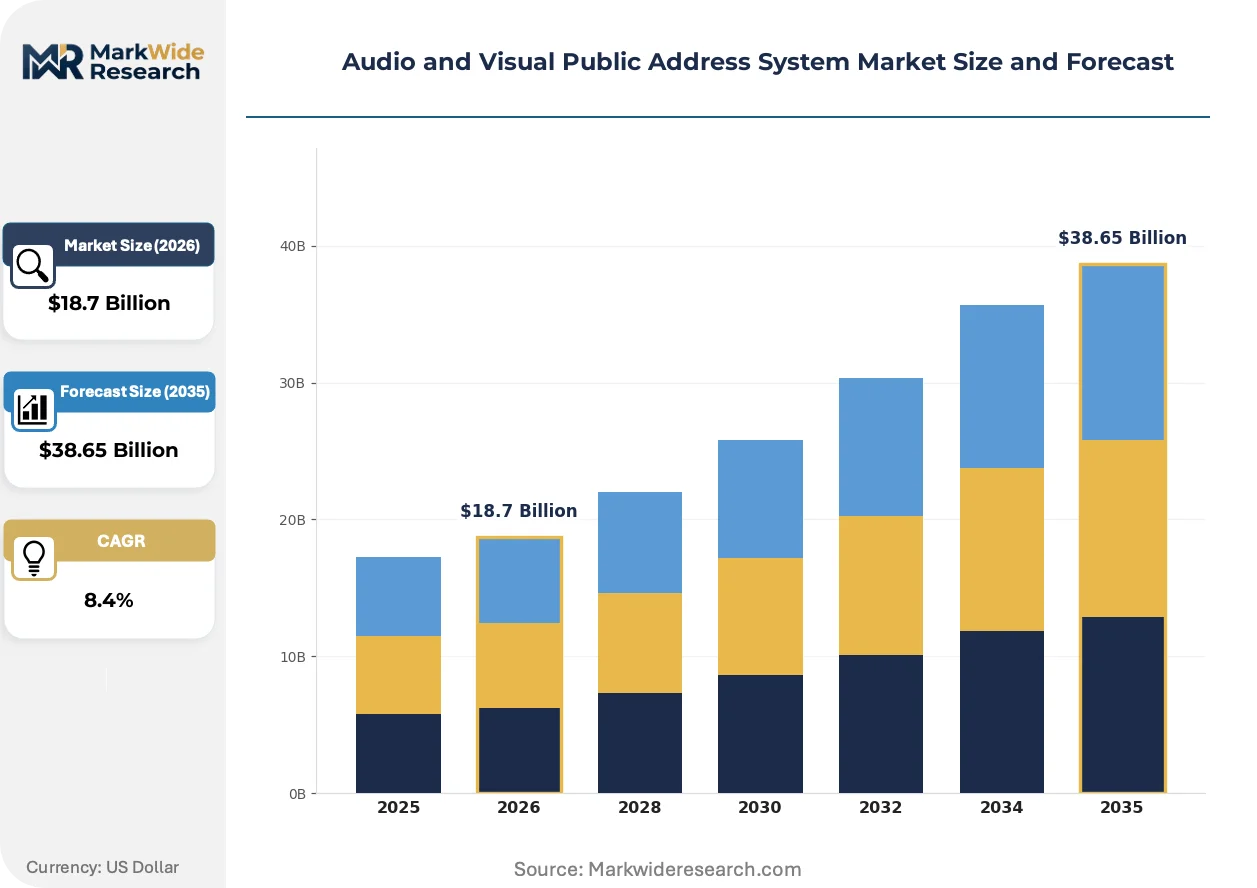
Market Dynamics
The Audio and Visual Public Address System Market is being fundamentally restructured by spectrum reallocation mandates that force hardware replacement cycles, compressing analog-to-digital transition timelines across installed bases while creating vendor consolidation pressure.
Growth Catalysts
- FCC spectrum re-banding:The United States regulator's 600 MHz clearance forces facility managers to replace legacy wireless microphone systems, accelerating procurement of IP-based architectures with centralized monitoring capabilities.
- Transit infrastructure modernization:Municipal governments in China are deploying networked PA arrays across subway terminals and high-speed rail stations ahead of international sporting events, creating concentrated demand spikes.
- Networked audio arrays:Stadium and arena operators are standardizing on Dante and AES67 protocols for distributed loudspeaker management, reducing cabling costs in heritage venues where structural modification is prohibited.
Market Restraints
- RF component supply concentration:Specialized RF transceiver modules for wireless microphone systems depend on Taiwanese semiconductor foundries, exposing procurement timelines to geopolitical friction and capacity constraints.
- Copper and rare earth magnet volatility:Neodymium prices for high-efficiency compression drivers and copper for amplifier windings create margin pressure that manufacturers cannot fully pass through in competitive tenders.
- ETSI electromagnetic compatibility certification:European public safety installations require extensive testing against EN 54-16 standards, extending product launch timelines by 8-14 months for non-EU suppliers.
Strategic Opportunities
- Cloud-based remote diagnostics bundling:Manufacturers can capture recurring software licensing revenue by embedding predictive maintenance platforms into hardware contracts, locking facilities managers into vendor ecosystems.
- India transit authority digitization:The country's metro rail expansion under the Smart Cities Mission creates greenfield demand for IP-based PA systems without legacy analog infrastructure to displace.
- Audio-visual control convergence:Integration of digital signal processing with video wall management under single-console architectures opens enterprise campus and command center verticals previously served by separate vendors.
Industry Challenges
- Acoustic engineering talent scarcity:Facilities require certified sound system designers capable of EASE modeling and STI-PA intelligibility verification, but vocational training programs have not scaled to match deployment velocity.
- Heritage building installation constraints:Cable routing through listed structures requires conservation board approval processes that extend project timelines and require specialized installation contractors with historic building certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio and Visual Public Address System Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microphones, Speakers, Amplifiers, Control Systems Technology: Wireless, Analog, Digital, IP-based End User: Education Institutions, Corporate Offices, Stadia, Event Venues Installation Type: Fixed, Portable, Mounted, Integrated |
| Companies Covered | Sennheiser Electronic, TOA Corporation, Harman International, Honeywell International, Audio-Technica, Bosch Security Systems, Yamaha Corporation, AtlasIED, Shure Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio and Visual Public Address System Market Evolving Landscape
Signal transport architectures are undergoing fundamental redesign as facilities abandon analog copper infrastructure. Three converging developments are compressing traditional product boundaries and reshaping competitive positioning.
Dante audio networking is collapsing the distinction between signal distribution and device control. The protocol enables 512 channels of uncompressed audio over standard Ethernet switches, allowing university campuses and corporate headquarters to consolidate IT and AV infrastructure teams. Facilities managers are eliminating dedicated audio cabling contractors, compressing installation bids by 30-40 percent in greenfield projects.
The FCC's 2020 completion of the 600 MHz incentive auction forced wireless microphone operators into 470-608 MHz and 941-960 MHz bands. Religious institutions and performing arts venues—heavy users of legacy UHF systems—faced simultaneous frequency coordination complexity and reduced available spectrum. Buyers responded by accelerating migration to 1.9 GHz DECT and 5 GHz unlicensed digital systems, bypassing licensed spectrum dependency entirely.
Facilities managers are unbundling hardware procurement from installation and maintenance contracts. Large stadium operators now source loudspeaker arrays through competitive tender while contracting directly with specialized acoustical consultants for system design. This disintermediation of the traditional AV integrator channel is most visible in North American collegiate athletic facilities, where procurement teams have adopted construction-industry practices of separating material supply from labor installation.
Audio and Visual Public Address System Market Segmentation
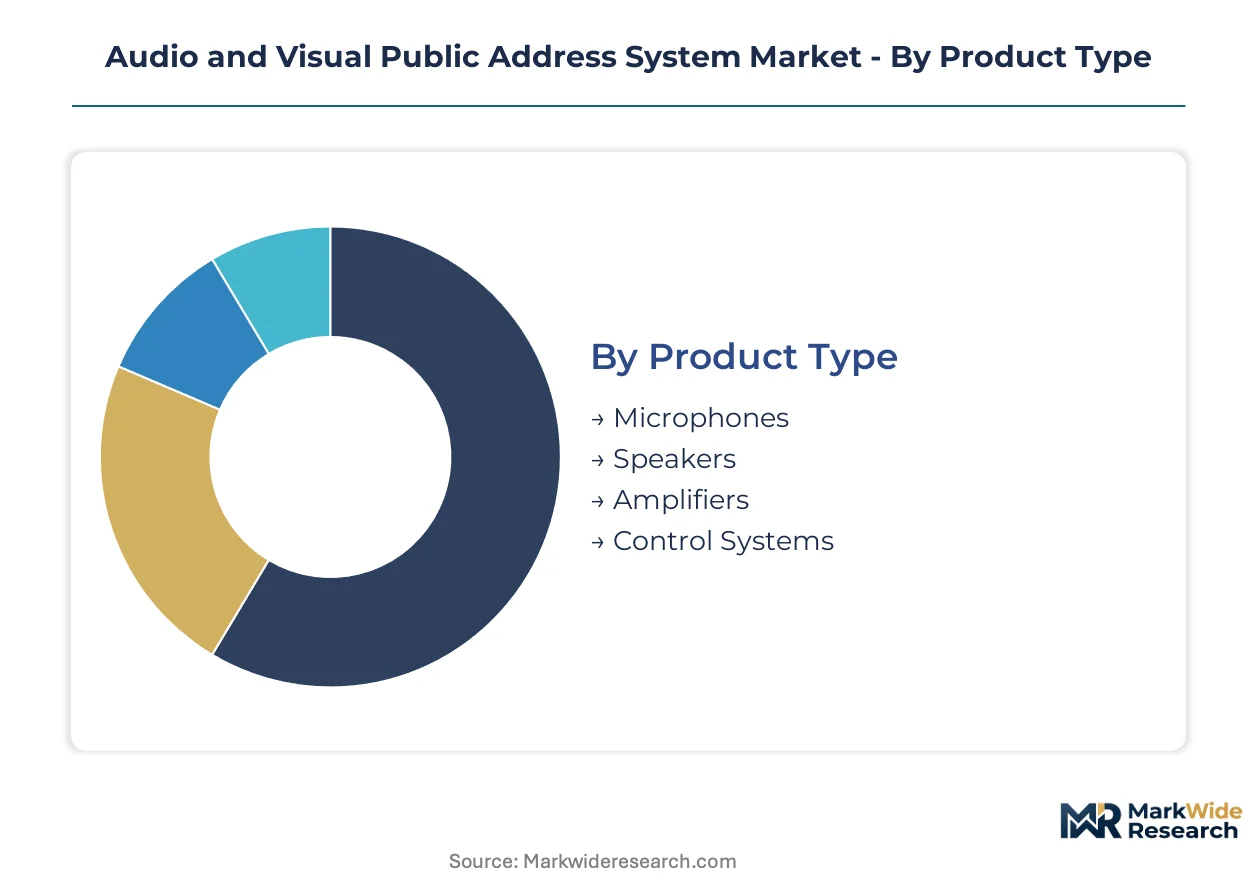
Audio and visual public address system procurement varies sharply by facility type, acoustic environment, and IT infrastructure maturity. Segment boundaries are blurring as Dante networking and IP-based control platforms collapse traditional hardware categories into unified signal chains.
Product Type:
Mature electro-acoustic components face margin compression while control systems capture recurring software revenue through vendor lock-in.
- Microphones:Handheld, lavalier, and gooseneck variants with cardioid or supercardioid polar patterns dominate house-of-worship and corporate boardroom installations. FCC spectrum re-banding in the United States accelerates replacement of UHF wireless units with 1.9 GHz DECT and 5 GHz unlicensed architectures in performing arts venues.
- Speakers:Line arrays, point-source enclosures, and column loudspeakers with neodymium compression drivers deliver sound pressure levels exceeding 90 dB for intelligibility in reverberant stadia. Chinese municipal transit authorities specify JIS-compliant acoustic engineering for subway terminal deployments ahead of international sporting events.
- Amplifiers:Class-D switching topologies reduce copper winding requirements and thermal management costs in rack-mounted installations.
- Control Systems:Digital signal processing platforms with annual software licensing lock facilities managers into vendor ecosystems through predictive maintenance dashboards.
Speakers handle the majority of throughput; control systems are climbing the fastest on share.
Technology:
Cost tiers separate legacy analog infrastructure from premium IP-native architectures with centralized monitoring capabilities.
- Wireless:RF transceiver modules operating in 470-608 MHz, 941-960 MHz, 1.9 GHz DECT, or 5 GHz unlicensed bands eliminate cable routing constraints in heritage buildings where structural modification is prohibited. Taiwanese semiconductor foundry concentration exposes procurement timelines to geopolitical friction.
- IP-based:Dante and AES67 protocols transport 512 channels of uncompressed audio over standard Ethernet switches, allowing university campuses to consolidate IT and AV infrastructure teams and compress installation bids by 30-40 percent.
- Digital:Pulse-code modulation and delta-sigma conversion architectures replace analog signal chains in greenfield transit infrastructure.
- Analog:Voltage-controlled amplification and copper-based distribution persists in budget-constrained educational institutions with legacy infrastructure.
IP-based architectures handle the majority of new deployment value; wireless maintains the steepest expansion trajectory in retrofit applications.
End User:
Application requirements dictate intelligibility standards, redundancy levels, and integration complexity across verticals.
- Stadia:Distributed loudspeaker arrays with networked audio routing serve 50,000-plus seat capacities where emergency notification and live event reinforcement must coexist. North American collegiate athletic facilities now separate hardware procurement from acoustical consulting contracts.
- Event Venues:Temporary rigging of line arrays and wireless microphone systems for touring productions demands rapid deployment and frequency coordination across multiple simultaneous events.
- Corporate Offices:Conference room automation and video wall integration drive convergence of audio and visual control under single-console management.
- Education Institutions:Campus-wide emergency notification systems and lecture hall reinforcement prioritize cost containment over acoustic performance in K-12 deployments.
Stadia handle the majority of high-value installations; corporate offices are gaining share fastest through audio-visual control convergence.
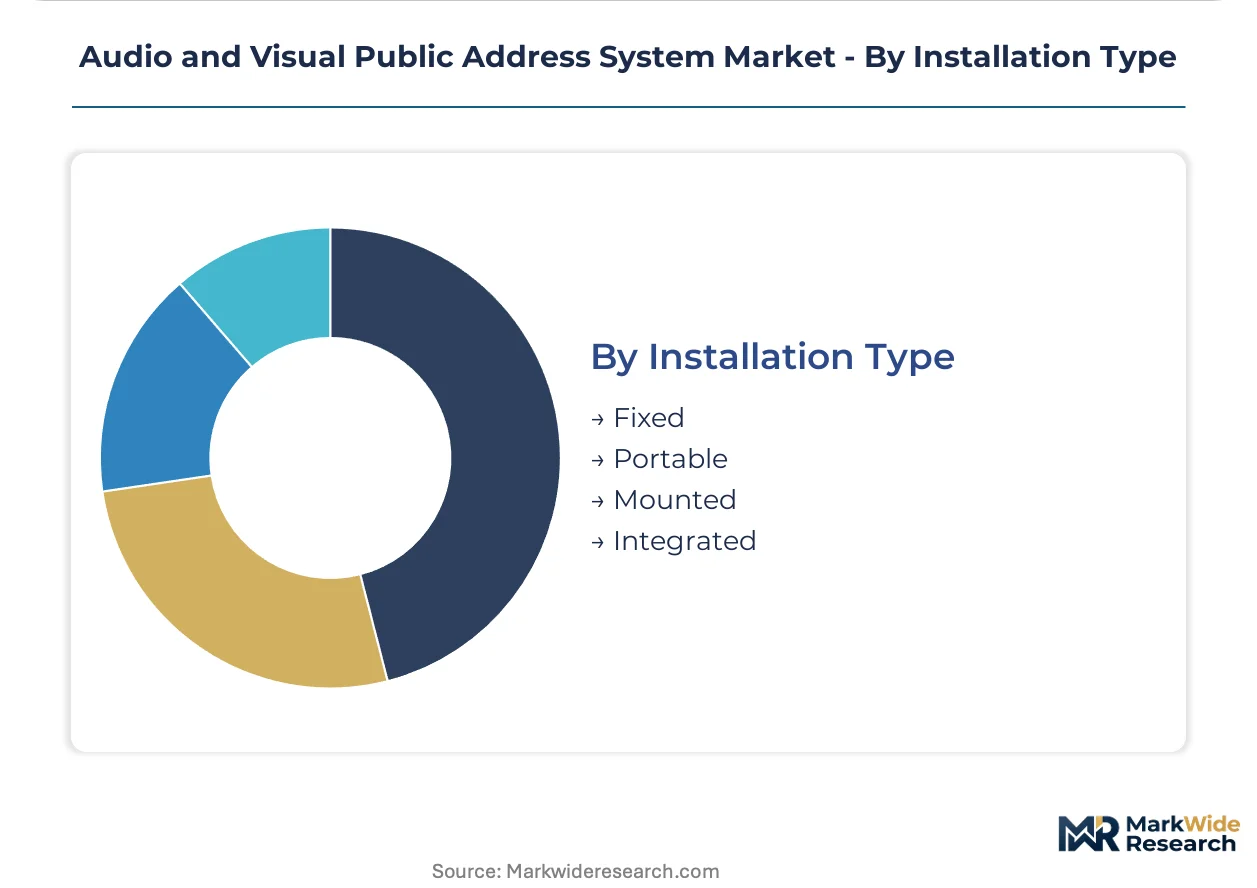
Installation Type:
Volume concentration favors fixed infrastructure while portable systems serve fragmented event production markets.
- Fixed:Permanently installed loudspeaker arrays, cable infrastructure, and rack-mounted equipment in transit terminals, stadia, and corporate campuses. Chinese high-speed rail stations specify fixed networked PA arrays under MIIT GB standards for electromagnetic emissions.
- Integrated:Concealed architectural loudspeakers and structured cabling within building fabric requires conservation board approval for heritage structures in European markets.
- Mounted:Surface-mounted or suspended enclosures in retrofit applications where concealed infrastructure is impractical.
- Portable:Self-powered loudspeakers and battery-operated wireless systems for outdoor events and temporary installations.
Fixed installations handle the majority of throughput; integrated systems are expanding most quickly in premium commercial real estate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stadium operators in the United States deploy distributed loudspeaker arrays for emergency notification and live event reinforcement, while Chinese municipal governments prioritize networked PA modernization across transit terminals ahead of international sporting events. European heritage venues face cable routing constraints that accelerate wireless adoption, and Indian metro rail expansion creates greenfield demand without legacy analog displacement.
United States
FCC spectrum re-banding in 600 MHz bands forces facility managers to replace legacy wireless microphone systems with IP-based architectures. The 2020 incentive auction completion compressed analog-to-digital transition timelines across religious institutions and performing arts venues. North American collegiate athletic facilities in Texas and California now separate hardware procurement from specialized acoustical consulting contracts.
China
Municipal governments in Beijing and Shanghai are deploying networked PA arrays across subway terminals and high-speed rail stations. MIIT enforces GB standards for electromagnetic emissions and acoustic performance in transportation infrastructure. Yangtze River Delta transit hubs specify JIS-compliant acoustic engineering for international event readiness.
Germany
Industrial facility managers seek centralized monitoring capabilities across distributed manufacturing campuses. ETSI electromagnetic compatibility certification under EN 54-16 standards creates compliance barriers for non-EU suppliers. Bavarian automotive plants and North Rhine-Westphalia chemical complexes drive demand for integrated emergency notification systems.
India
Metro rail expansion under the Smart Cities Mission creates greenfield procurement for IP-based systems without legacy infrastructure displacement. TRAI spectrum allocation policies influence wireless microphone deployment in temporary event installations. Maharashtra and Karnataka state transit authorities specify Dante protocol networking for new terminal constructions.
United Kingdom
Ofcom tightened RF spectrum allocations push buyers toward digital transmission architectures in heritage performance venues. Conservation board approval processes for cable routing through listed structures extend project timelines in London and Edinburgh. Corporate headquarters in the Southeast standardize on single-console audio-visual control management.
Audio and Visual Public Address System Market Competitive Landscape
Capability concentration sits with specialized acoustical engineering firms; scale advantage sits with diversified electronics conglomerates. The vendor base organizes into three tiers: integrated security providers leveraging fire-safety distribution channels, professional audio specialists with proprietary digital signal processing platforms, and regional fabricators serving localized transit markets. Consolidation pressure intensifies as spectrum mandates force hardware replacement cycles, while strategic partnerships between semiconductor suppliers and system integrators reshape component sourcing.
Among diversified electronics manufacturers, Bosch Security Systems and Yamaha Corporation exemplify contrasting positioning archetypes. TOA Corporation anchors the Asia-Pacific transit specialization tier. Bosch leverages cross-selling synergies across European infrastructure projects. Yamaha occupies the digital convergence position unifying audio and visual control architectures. These three entities represent the dominant competitive vectors: integrated security distribution, regional transit engineering, and platform-based ecosystem lock-in.
| Leading Market Players |
|---|
| Sennheiser Electronic |
| TOA Corporation |
| Harman International |
| Honeywell International |
| Audio-Technica |
| Bosch Security Systems |
| Yamaha Corporation |
| AtlasIED |
| Shure Incorporated |
| Others |
Value Network & Pricing Analysis
Overcapacity in Taiwanese RF semiconductor foundries compresses pricing power for wireless microphone transceivers while amplifying buyer leverage in contract negotiations. This utilization dynamic forces manufacturers to absorb neodymium and copper cost volatility rather than pass through increases, narrowing margins on electro-acoustic components while software licensing sustains control system profitability.
Pricing Analysis
Project-based contracting dominates large transit and stadium installations, with facilities managers separating hardware procurement from acoustical consulting fees. Price differentiation rests on EN 54-16 certification tier and Dante protocol integration depth, with European public safety premiums commanding substantial uplifts over uncertified alternatives. Cost compression in analog amplifier tiers intensifies as educational institutions defer replacement cycles, while corporate buyers show lowest price sensitivity for unified audio-visual control platforms with predictive maintenance bundling.
Supply Chain Analysis
Neodymium feedstock draws from Chinese rare earth processing facilities, with copper winding materials sourced from Chilean and Peruvian mining operations. Taiwanese semiconductor foundries fabricate specialized RF transceiver modules for wireless systems. Single-source vulnerability concentrates in neodymium magnet supply, exposing compression driver manufacturers to export restriction risk. Distribution runs through fire-safety and security integrators in European infrastructure, direct OEM relationships in Asian transit, and disintermediated procurement channels in North American collegiate athletics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
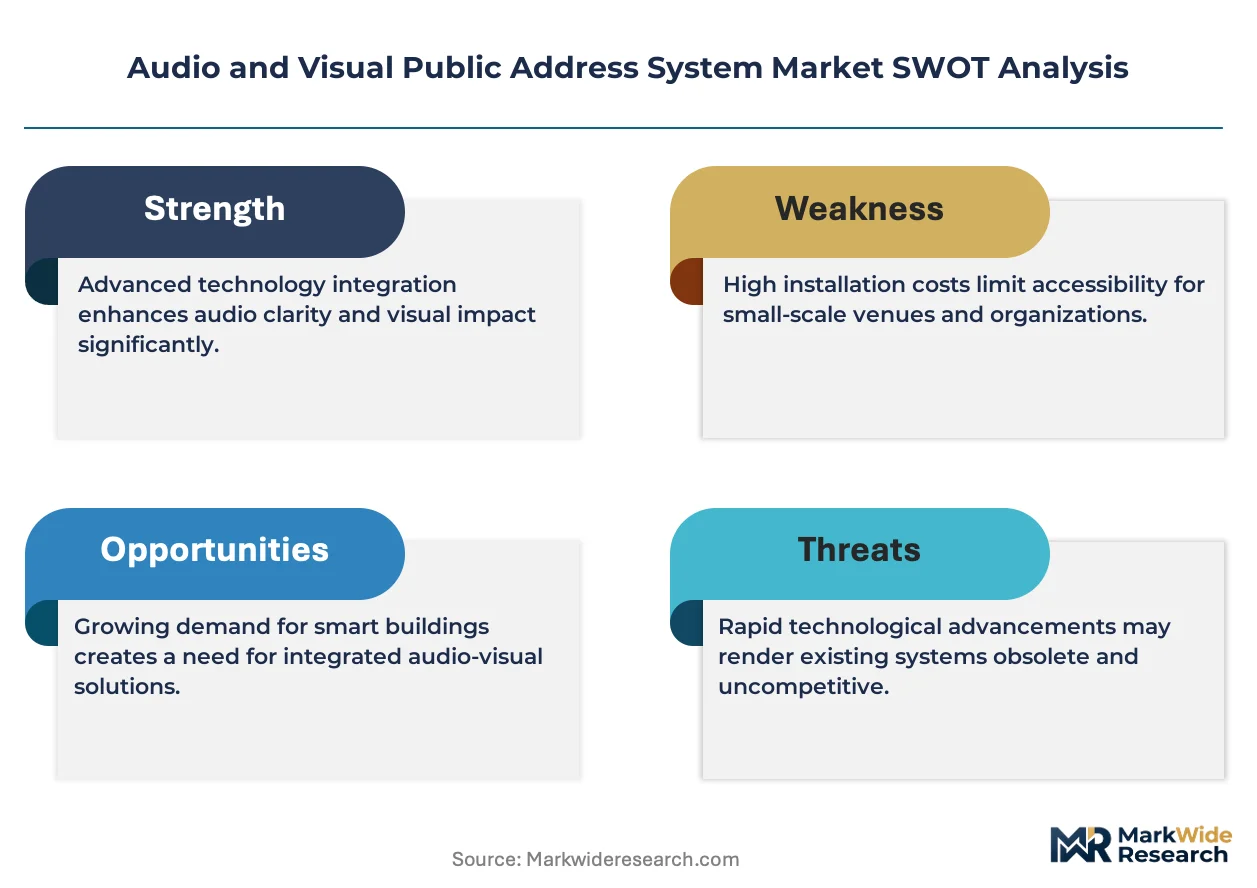
FCC spectrum re-banding constitutes a regulatory inflection forcing hardware replacement cycles across installed bases, compressing analog-to-digital transition timelines and creating vendor consolidation pressure in a high-growth disruption environment.
For Market Incumbents: Insulate recurring revenue streams by embedding cloud-based remote diagnostics into hardware contracts, locking facilities managers into vendor ecosystems through annual software licensing. Accelerate Dante protocol certification investments to defend against IP-native challengers in university and corporate campus verticals. Deepen backward integration into digital signal processing silicon to offset RF component supply concentration risk. For New Entrants and Emerging Players: Mid-market commercial buildings in India and Southeast Asia represent the most penetrable entry point, with Smart Cities Mission transit expansion creating greenfield demand without legacy analog displacement. Target audio-visual control convergence in command centers and enterprise campuses previously served by separate vendors. Pursue direct-to-facility-manager sales models bypassing traditional AV integrator channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among control system vendors with predictive maintenance platforms and annual software licensing structures. Long-term viability favors platform-based ecosystem plays over commoditized electro-acoustic component manufacturers. Monitor EN 54-16 certification reciprocity agreements as inflection indicator for European market entry timing and acquisition premium justification.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Dante and AES67 protocol adoption consolidates IT and AV infrastructure teams across university campuses. |
| Backward Integration | In-house digital signal processing silicon production reduces dependency on Taiwanese RF foundry capacity. |
| Certification Investment | EN 54-16 compliance opens European public safety installations previously blocked to non-EU suppliers. |
| Geographic Expansion | Indian metro rail greenfield deployment avoids legacy analog displacement costs entirely. |
| Strategic Partnership | Fire-safety distribution channel alliances replicate Bosch's cross-selling model across infrastructure verticals. |
Research Methodology
Cross-validation between primary interviews with facilities managers, acoustical consultants, and transit authority procurement officers anchors the qualitative findings, supplemented by secondary validation against FCC spectrum allocation filings, MIIT GB standard publications, and ETSI EN 54-16 certification databases. Bottom-up and top-down triangulation reconciles equipment shipment data from regional distributors with top-line infrastructure investment disclosures from municipal governments.
Calibration against historical replacement cycle patterns and spectrum policy implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, technology architecture, end-user vertical, and installation configuration, with CAGRs derived from installed base turnover rates and greenfield deployment velocity. Forecast inputs incorporate RF spectrum re-banding compliance deadlines and international sporting event infrastructure preparation schedules.
Practitioners should monitor spectrum policy evolution, rare earth export restriction signals, and certification reciprocity negotiations for early indicators of forecast revision. Cross-checking against municipal transit authority capital expenditure disclosures and stadium operator procurement tender databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Hydrogen Thyratron Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Europe Radiation-Hardened Electronics Market
Electronic Components
High Density Interconnect (HDI) PCB Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Flash Charger Adapter Market
Electronic Components
China Data Converter Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Operational Amplifier Market
Electronic Components
Screw Washer Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Loudspeaker Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Radiation Hardened Electronics Market