
 Lead-Free Solder Paste Market | 2026-2036
Lead-Free Solder Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Lead-Free Solder Paste Market Foresight
Capital-intensity divergence between integrated alloy producers and formulation specialists is rotating competitive advantage toward companies with captive smelting capacity. Henkel AG & Co. KGaA leverages its adhesives-chemicals platform to bundle solder pastes with underfill solutions for automotive module assembly. Indium Corporation sustains technology leadership in indium-bearing low-temperature formulations for temperature-sensitive substrates. Senju Metal Industry Co., Ltd. anchors Asian supply through integrated powder atomization and flux development operations in Japan.
Lead-free solder paste comprises tin-based alloy powders suspended in flux vehicles, typically SAC305 (Sn96.5/Ag3.0/Cu0.5) with melting points near 217-220°C, engineered for stencil printing and reflow soldering of printed circuit board assemblies. Sn-Ag-Cu alloys dominate volume owing to balanced wetting performance and thermal fatigue resistance in consumer electronics and automotive control modules. Sn-Bi formulations represent the fastest-expanding category as manufacturers adopt lower-temperature processing for LED assemblies and flexible substrates to reduce energy consumption and thermal damage. Paste form captures the majority of value given direct integration into surface-mount technology lines, while powder supply serves specialized jetting and additive electronics applications.
REACH and RoHS frameworks in Europe mandate lead-content thresholds below 0.1% in homogeneous materials, compelling reformulation across imported electronics supply chains. EPA enforcement of hazardous substance rules in the United States shapes domestic manufacturing compliance costs, while China's GB standards align with international restrictions through MIIT implementation protocols. Stakeholders must monitor alloy substitution timelines as bismuth and antimony supply constraints intersect with expanding automotive electrification requirements.
Market Dynamics
Automotive electrification is compressing alloy qualification timelines as EV powertrain manufacturers demand SAC305 formulations with enhanced thermal cycling resistance for 800V inverter modules. This demand surge is reshaping allocation priorities across tin-silver-cu supply chains.
Growth Catalysts
- REACH lead-content thresholds:European ECHA enforcement mandates sub-0.1% lead in homogeneous materials, compelling Asian contract manufacturers to reformulate export-bound assemblies.
- EV powertrain thermal management:Automotive tier-1 suppliers specify high-reliability SAC305 for DC-DC converters and battery management systems.
- Shenzhen-Suzhou PCB clusters:China's concentrated electronics manufacturing absorbs volume SAC305 and Sn-Bi formulations for consumer and industrial boards.
Market Restraints
- Indium supply concentration:Low-temperature indium-bearing formulations face input cost volatility as primary extraction ties to zinc mining economics.
- Bismuth supply constraints:Sn-Bi alloy expansion strains global bismuth output, which derives largely as a byproduct of lead and tungsten processing.
- RoHS compliance friction:Exemption renewal uncertainty for specific alloy additives creates formulation instability for medical and aerospace applications.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor packaging and PCB assembly create virgin demand for lead-free paste qualification.
- Jet dispensing additive electronics:Powder supply for 3D circuit printing bypasses stencil limitations in flexible and wearable device production.
- EU Green Deal material sourcing:CSRD disclosure requirements favor suppliers with documented conflict-free tin and recycled content streams.
Industry Challenges
- Reflow profile optimization:Transitioning from Sn-Pb to SAC305 demands recalibration of oven zones and nitrogen atmosphere controls.
- Flux chemistry IP licensing:Proprietary activator systems from Japanese and German specialists create royalty burdens for independent formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead-Free Solder Paste Market |
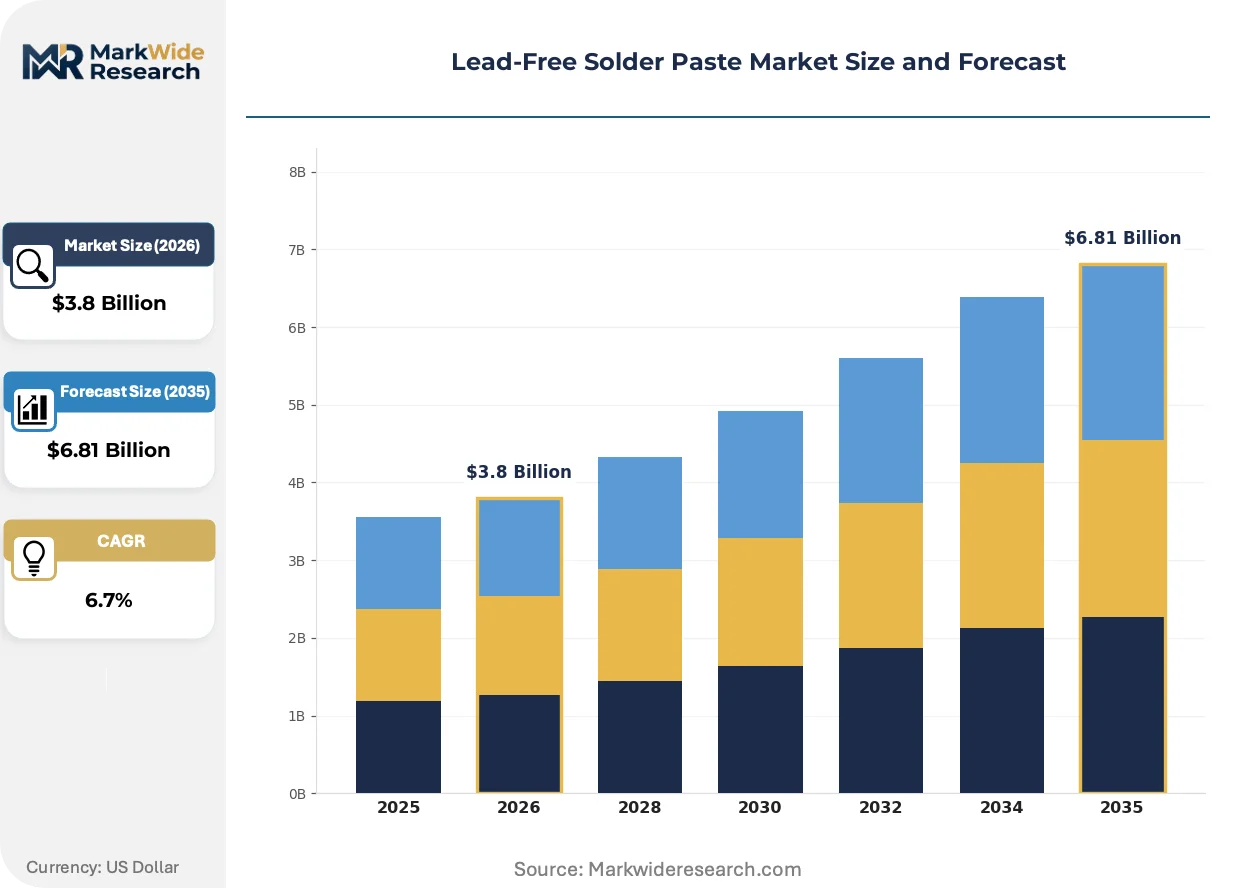
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sn-Ag-Cu, Sn-Cu, Sn-Ag, Sn-Bi Application: Consumer Electronics, Automotive Components, Industrial Equipment, Telecommunications Form: Paste, Powder, Granules, Solid End User: OEMs, Contract Manufacturers, Repair Facilities, Electronics Distributors |
| Companies Covered | Henkel AG & Co. KGaA, Indium Corporation, Senju Metal Industry Co., Ltd., MacDermid Alpha Electronics Solutions, Kester, Nihon Superior Co., Ltd., AIM Solder, Shenmao Technology Inc., Tamura Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead-Free Solder Paste Market Shifts & Advancements
Formulation science is diverging along temperature-performance axes as end-users fragment reliability requirements across automotive, medical, and consumer tiers. This specialization is proliferating alloy variants and collapsing economies of scale in paste production.
Sn-Bi near-eutectic alloys are fragmenting the traditional SAC305 dominance in temperature-sensitive applications. LED assembly houses adopt Sn57Bi43 formulations with 138°C melting points to eliminate substrate warpage and reduce reflow energy. This thermal budget compression is fragmenting equipment vendor roadmaps as oven manufacturers split development between high-peak and low-peak thermal platforms.
EU REACH Annex XVII amendments tighten cadmium and lead restrictions in electrical equipment placed on the European market. ECHA substance evaluation drives substitution of residual lead traces in solder alloys below 0.1% homogeneous thresholds. Automotive suppliers with European final assembly exposure accelerate SAC305 and SAC387 qualification to preempt border enforcement actions.
Automotive tier-1 procurement teams consolidate qualified paste suppliers to three-per-plant maximums, compressing vendor lists that previously accommodated six to eight regional formulators. This buyer concentration forces independent paste houses to pursue toll manufacturing arrangements or alloy tolling partnerships with integrated powder producers. The supplier base contraction is most visible in Germany and Japan, where OEM direct qualification requirements dominate sourcing decisions.
Lead-Free Solder Paste Market Segmentation
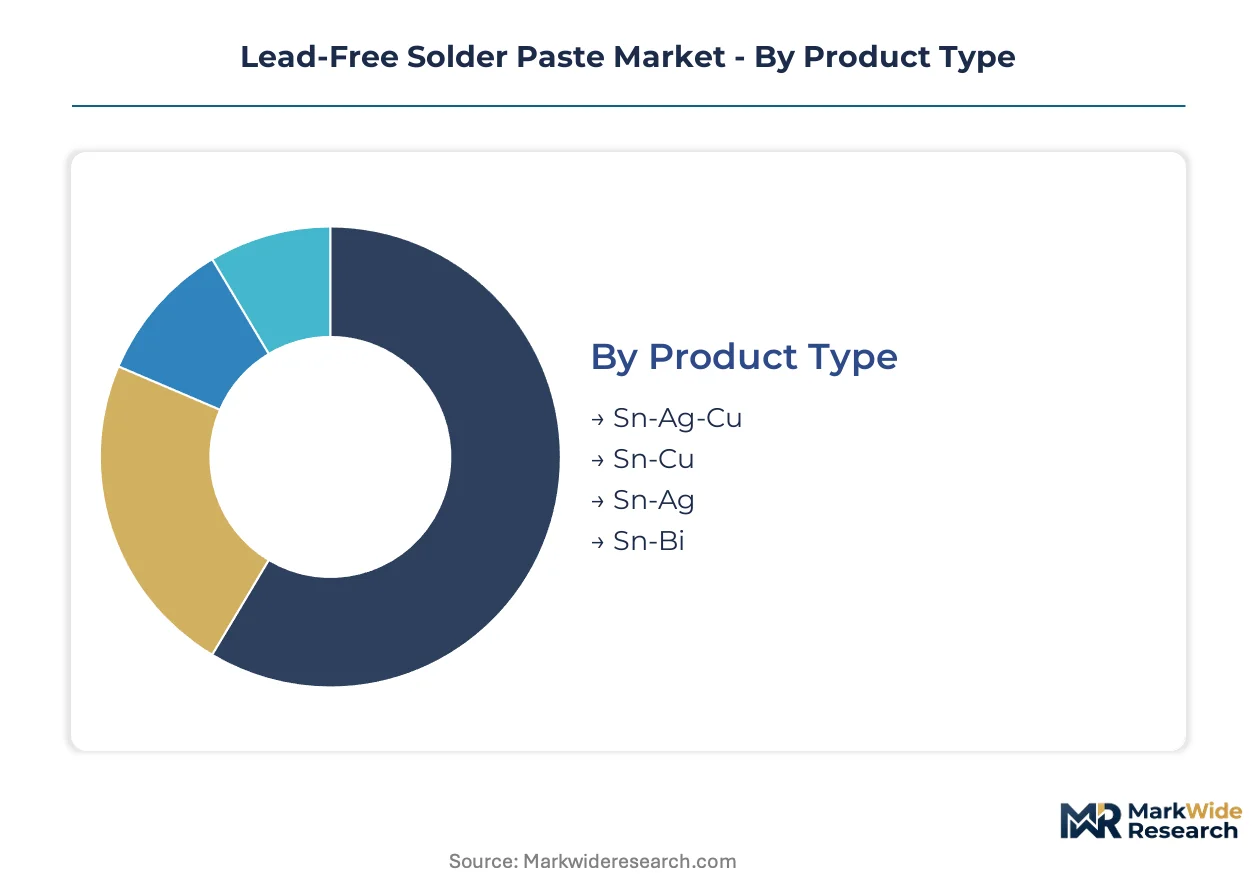
Lead-free solder paste segmentation reflects divergent thermal performance requirements across electronics assembly tiers. Alloy chemistry, application environment, and supply chain position each create distinct procurement patterns and margin structures.
Product Type:
Channel-mix varies sharply by alloy family, with SAC formulations dominating automotive direct procurement while Sn-Bi routes through distributor networks for LED and flexible substrate houses.
- Sn-Ag-Cu:Tin-silver-copper alloys, primarily SAC305 (Sn96.5/Ag3.0/Cu0.5), deliver 217-220°C melting points with balanced wetting and thermal fatigue resistance. Automotive tier-1 suppliers in Germany and Japan specify SAC305 for 800V inverter modules and battery management systems, compressing qualification timelines as EV production scales.
- Sn-Bi:Near-eutectic Sn57Bi43 formulations melt at 138°C, enabling low-temperature processing for temperature-sensitive substrates. Shenzhen LED assembly houses adopt these alloys to eliminate PCB warpage and reduce reflow energy consumption, straining global bismuth supply derived from lead and tungsten byproduct streams.
- Sn-Cu:Binary tin-copper systems offer cost-positioned alternatives with 227°C melting points, capturing industrial equipment applications where thermal cycling demands moderate.
- Sn-Ag:Silver-rich binary alloys provide enhanced creep resistance for high-reliability telecommunications infrastructure, though indium price volatility constrains low-temperature variants.
By volume, Sn-Ag-Cu leads. By growth pace, Sn-Bi is ahead.
Application:
Cost tier stratification separates premium automotive qualification from high-volume consumer electronics procurement, with industrial and telecom occupying mid-tier pricing bands.
- Consumer Electronics:High-volume smartphone and laptop assembly drives SAC305 consumption through Shenzhen and Suzhou PCB clusters, with contract manufacturers optimizing paste deposition for miniaturized component footprints.
- Automotive Components:DC-DC converters, inverters, and battery management systems demand enhanced thermal cycling resistance. ECHA REACH enforcement accelerates SAC305 and SAC387 qualification for European final assembly exposure.
- Industrial Equipment:Factory automation controllers and power electronics utilize Sn-Cu formulations where extended operating lifecycles meet moderate thermal stress profiles.
- Telecommunications:Base station and server infrastructure specifications prioritize Sn-Ag creep resistance for 10-15 year service intervals in climate-exposed installations.
Consumer electronics commands the largest volume share. Automotive components exhibits the steepest expansion trajectory.
Form:
Volume concentration favors paste for surface-mount lines, while powder serves emerging additive manufacturing channels with differentiated margin profiles.
- Paste:Alloy powder suspended in flux vehicles integrates directly into stencil printing and reflow soldering lines, capturing the majority of value across all application tiers.
- Powder:Unfluxed spherical powder enables jet dispensing and 3D circuit printing for flexible and wearable device production, bypassing stencil limitations in additive electronics.
- Granules:Intermediate particle sizing serves selective wave soldering and robotic dispensing applications in industrial equipment repair channels.
- Solid:Bar and wire forms address manual assembly and rework operations at repair facilities and prototype shops.
Paste dominates current revenue. Powder is gaining share fastest in emerging applications.
End User:
Customer type determines procurement sophistication, with OEMs and contract manufacturers driving formulation specifications while distributors and repair facilities absorb residual demand.
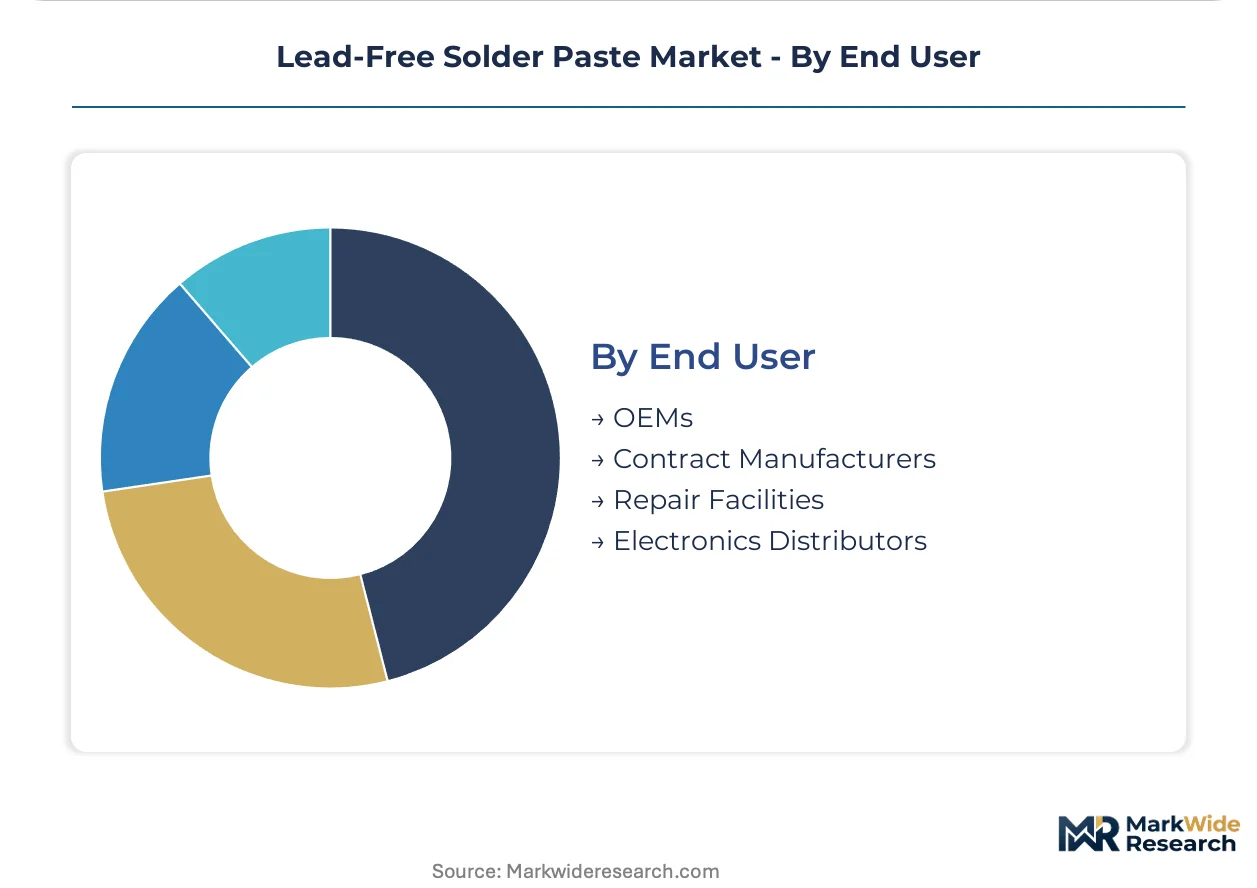
- OEMs:Automotive and consumer electronics original equipment manufacturers consolidate qualified suppliers to three-per-plant maximums, forcing independent paste houses toward toll manufacturing arrangements.
- Contract Manufacturers:Foxconn, Jabil, and Flex operations in China absorb volume SAC305 and Sn-Bi formulations, with REACH compliance mandates reformulating export-bound assemblies.
- Repair Facilities:Smaller-volume solid wire and paste demand for electronics refurbishment, with less stringent alloy qualification requirements.
- Electronics Distributors:Arrow, Avnet, and regional Asian distributors stock standard formulations for mid-tier industrial and prototyping customers.
Contract manufacturers process the highest paste volumes. OEMs set the fastest-moving specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German formulation specialists, while Chinese powder producers compete on volume. Shenzhen contract manufacturers absorb SAC305 at compressed margins. European REACH enforcement tilts procurement toward qualified suppliers with documented alloy traceability.
China
Shenzhen and Suzhou PCB clusters process volume SAC305 for consumer electronics exports. MIIT implements GB standards aligning with RoHS restrictions on lead content. Foxconn and BYD Electronics operations in Guangdong and Jiangsu provinces drive paste consumption for smartphone and EV component assembly.
Germany
Automotive tier-1 suppliers specify high-reliability SAC305 for 800V inverter modules and battery management systems. ECHA REACH Annex XVII mandates sub-0.1% lead thresholds in homogeneous materials. Bavarian and Baden-Württemberg manufacturing corridors host concentrated electronics assembly for European OEM final assembly exposure.
Japan
Integrated powder atomization and flux development operations anchor Asian supply chain reliability. METI oversees industrial standards coordination with international RoHS frameworks. Tokyo and Osaka metropolitan areas concentrate precision electronics manufacturing demanding qualified paste formulations.
United States
EPA hazardous substance enforcement shapes domestic manufacturing compliance costs for electronics assemblers. NHTSA automotive safety regulations intersect with electronics reliability requirements for EV powertrains. Texas and California host contract manufacturing operations serving aerospace and medical device applications.
India
PLI scheme incentives for semiconductor packaging and PCB assembly create virgin demand for lead-free paste qualification. BIS standards adoption accelerates alignment with international restriction frameworks. Karnataka and Tamil Nadu electronics manufacturing clusters attract SAC305 and Sn-Bi formulation trials.
Lead-Free Solder Paste Market Competitive Landscape
Concentration sits with diversified chemical conglomerates possessing captive alloy supply and integrated flux development capabilities. The vendor base splits between multinational formulation platforms and specialized powder metallurgy houses. Three archetypes dominate: adhesives-chemicals conglomerates with solder paste as a line extension; integrated Japanese metal powder specialists; and independent toll manufacturers serving regional contract assemblers. Competitive moves center on automotive qualification consolidation and bismuth supply chain locking.
Within the diversified chemicals tier, Henkel AG & Co. KGaA and MacDermid Alpha Electronics Solutions exemplify platform players bundling solder pastes with adjacent assembly materials. Indium Corporation and Senju Metal Industry Co., Ltd. represent integrated specialists with captive powder production. These four anchors occupy positions across the premium qualification and volume manufacturing segments respectively.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Indium Corporation |
| Senju Metal Industry Co., Ltd. |
| MacDermid Alpha Electronics Solutions |
| Kester |
| Nihon Superior Co., Ltd. |
| AIM Solder |
| Shenmao Technology Inc. |
| Tamura Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between automotive tier-1 suppliers and integrated powder producers lock in SAC305 supply access while providing 12-18 month price visibility against tin and silver volatility. These contracts concentrate procurement power among German and Japanese OEMs, compressing margins for independent formulators locked into spot metal markets. REACH compliance documentation requirements add non-price switching costs that reinforce incumbent positions.
Pricing Analysis
The customization-premium spread separates automotive-qualified SAC305 formulations from standard consumer-grade pastes by 15-25% at contract negotiation. Pricing stratifies across automotive certification tiers, volume scale commitments, and bundled technical service packages. Cost compression in consumer electronics tiers is intensifying because Shenzhen contract manufacturers consolidate purchasing across six to eight product lines. LED assembly houses exhibit highest price sensitivity due to Sn-Bi raw material volatility, while automotive OEMs prioritize thermal cycling reliability over unit cost.
Supply Chain Analysis
China and Japan anchor global solder powder production through integrated atomization facilities in Shenzhen, Suzhou, and Osaka metropolitan corridors. Downstream formulation draws from concentrated tin smelting in Yunnan province, silver refining in Mexico and Peru, and bismuth byproduct extraction from Chinese lead operations. Single-source vulnerability concentrates in indium supply tethered to Korean zinc mining economics. Distribution runs through authorized distributor networks for qualified automotive grades, while consumer electronics paste moves direct to Foxconn and BYD Electronics procurement centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EV powertrain electrification penetrates beyond early adopters into mass-market vehicle platforms. Automotive solder paste qualification timelines compress from 24 months to 12 months, accelerating replacement demand.
For Market Incumbents: Shield SAC305 automotive qualification positions by accelerating backward integration into tin powder atomization and locking bismuth offtake for Sn-Bi expansion. Japanese and German specialists face emerging toll-manufacturing entrants from India; defend through embedded flux chemistry IP licensing and direct OEM technical service relationships that raise switching costs.
For New Entrants and Emerging Players: Lead with jet-dispensing powder supply for additive electronics manufacturers bypassing stencil limitations in flexible wearable device production. India's PLI scheme incentives for semiconductor packaging create the most penetrable geography for virgin paste qualification trials. Target contract manufacturers in Karnataka and Tamil Nadu with localized blending operations and BIS certification support.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated powder metallurgy specialists with captive smelting relationships and automotive OEM direct qualification. Long-term viability over the next decade hinges on bismuth supply chain positioning as Sn-Bi alloys displace SAC305 in temperature-sensitive applications. Watch indium price volatility as the signal for low-temperature formulation substitution timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tin Powder Atomization | Captive supply secures SAC305 margin control against metal price volatility from Yunnan smelters. |
| Bismuth Supply Chain Locking | Long-term offtake agreements with Chinese lead refiners hedge Sn-Bi expansion against byproduct constraints. |
| Automotive Qualification Consolidation | Reducing qualified suppliers to three-per-plant maximums reinforces Henkel and Indium Corporation incumbent positions. |
| Jet Dispensing Powder Development | Unfluxed spherical powder enables 3D circuit printing for flexible substrate manufacturers in Shenzhen clusters. |
| EU CSRD Compliance Documentation | Conflict-free tin traceability and recycled content streams satisfy ECHA disclosure requirements for European OEMs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with automotive tier-1 procurement managers, SMT line engineers at Foxconn and Jabil facilities, flux chemistry R&D directors at Japanese specialists, and electronics distributors in Arrow and Avnet channel operations. Secondary validation drew from SEC 10-K filings of diversified materials conglomerates, MIIT GB standard implementation protocols, ECHA REACH Annex XVII amendment tracking, and customs trade data for tin powder imports. Bottom-up paste volume estimates from Shenzhen and Suzhou PCB clusters triangulated against top-down alloy consumption projections from smelter association reports.
Across the analysis window, volume and value outputs reflect segmentation modeling by alloy chemistry family, application environment tier, form factor, and end-user procurement sophistication. CAGRs derive from slope analysis of historical qualification timelines intersecting with EV production ramp assumptions and REACH enforcement phase-in schedules. Forecast inputs incorporate bismuth byproduct supply elasticity from lead mining economics and automotive thermal cycling reliability specification evolution.
Forecasts assume regulatory continuity in ECHA REACH enforcement and MIIT GB standard alignment; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Global Precision Resistor Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market