
 Coating Thickness Measurement Instruments Market | 2026-2036
Coating Thickness Measurement Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Thickness Measurement Instruments Market Outlook
A shortage of certified non-destructive testing technicians is reorganizing how coating thickness instrument vendors structure training and aftermarket service programs. Helmut Fischer sustains its position through deep calibration laboratory networks across industrial clusters. DeFelsko Corporation differentiates via ruggedized handheld designs purpose-built for field inspectors in marine and infrastructure settings. Elcometer Limited leverages century-old brand recognition in protective coatings inspection to dominate specification-driven procurement channels.
Coating thickness measurement instruments quantify dry film thickness on substrates using magnetic induction, eddy current, ultrasonic pulse-echo, or X-ray fluorescence principles, with typical resolution ranging from 0.1 micrometers on thin metallic layers to several millimeters on thick polymer coatings. Their primary purpose is ensuring corrosion protection, adhesion performance, and material efficiency in finishing operations. Eddy current and ultrasonic modalities are capturing expanded share as composite substrates and multilayer automotive paint systems proliferate. X-ray fluorescence commands premium positioning in electronics and semiconductor packaging where gold and palladium plating tolerances tighten. Magnetic gauges retain volume leadership in steel-heavy construction and shipbuilding applications where cost sensitivity dominates.
ISO 2808 paint film thickness standards, ASTM D7091 for non-magnetic coatings on ferrous metals, and SSPC-PA 2 coating application specifications collectively define instrument accuracy requirements and inspector certification pathways. EPA NESHAP rules for surface coating operations and REACH substance restrictions on hexavalent chromium coatings are elevating documentation burdens that only calibrated, auditable thickness systems can satisfy. Stakeholders must weigh capital deployment toward multi-technology platforms against the risk of stranded single-modality assets as substrate portfolios diversify.
Market Dynamics
Automotive lightweighting programs and EV battery enclosure coating verification are forcing metrology budget reallocations toward inline monitoring systems that can validate multilayer substrates in real time.
Growth Catalysts
- REACH compliance deadlines:European manufacturers face substance restriction mandates on hexavalent chromium coatings that require auditable thickness documentation systems.
- Composite substrate proliferation:Eddy current and ultrasonic modalities capture expanded share as carbon fiber-reinforced polymers replace steel in automotive body panels.
- Marine infrastructure inspection cycles:Port authorities and classification societies mandate dry film thickness verification for protective coatings on offshore platforms and ship hulls.
Market Restraints
- X-ray fluorescence capital intensity:Premium electronics and semiconductor packaging applications require six-figure instrument investments that limit buyer pools.
- Calibration laboratory concentration:Certified reference material supply clusters in Germany and Switzerland create geographic dependency for traceable calibration chains.
- Magnetic gauge substrate limitation:Ferrous-only measurement capability constrains addressable market as aluminum-intensive vehicle architectures spread.
Strategic Opportunities
- India automotive supplier corridor:Paint shops and galvanizing lines near Chennai and Pune lack real-time inline monitoring infrastructure.
- AI-integrated defect prediction:Machine learning algorithms trained on thickness variance patterns enable predictive maintenance for coating line operators.
- EPA NESHAP documentation burden:Surface coating operations require auditable measurement protocols that certified instruments can monetize through subscription calibration services.
Industry Challenges
- Certified NDT technician scarcity:ISO 17024-accredited inspector pipelines cannot match demand from expanding automotive and aerospace coating verification programs.
- Multi-technology platform integration:Buyers face stranded asset risk when single-modality instruments cannot accommodate diversifying substrate portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Thickness Measurement Instruments Market |
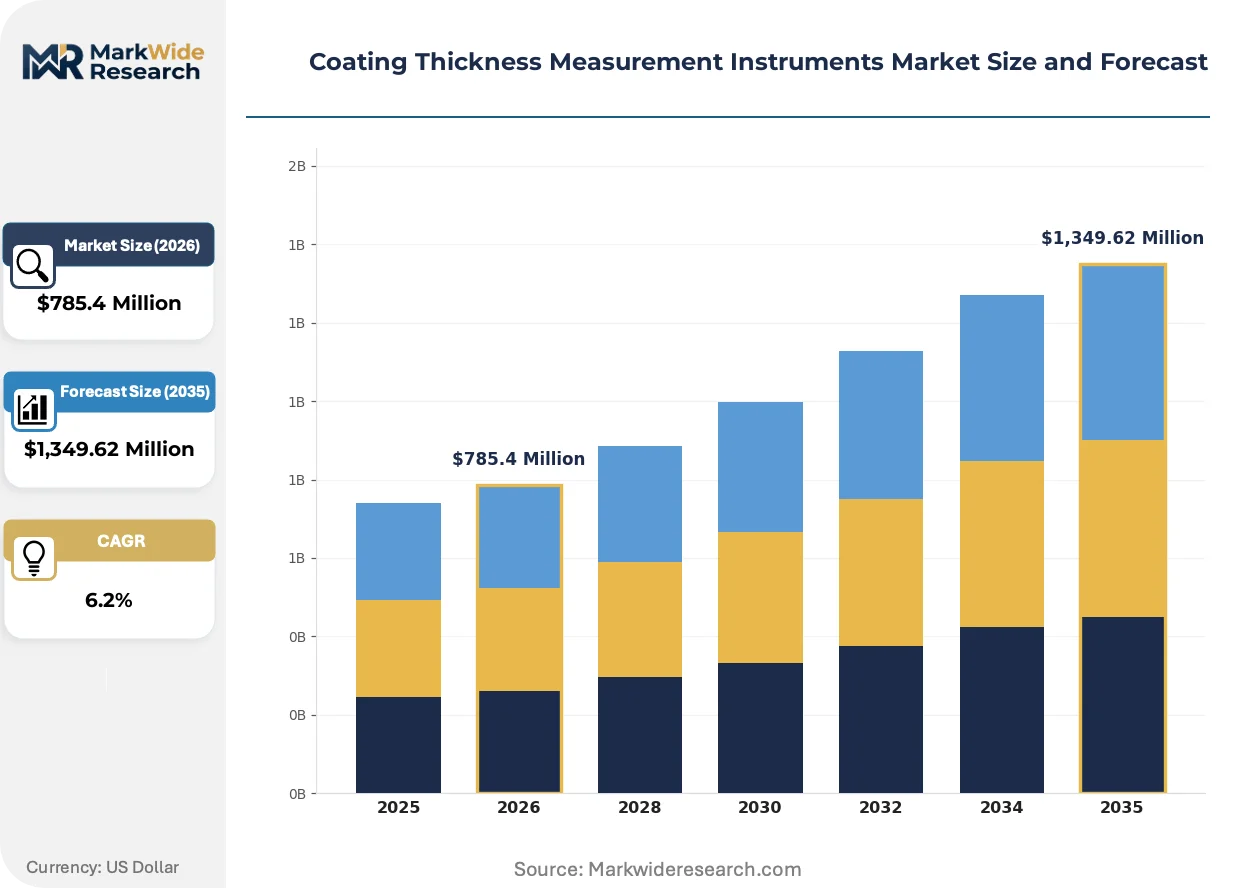
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,349.62 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic, Eddy Current, Ultrasonic, X-Ray Technology: Non-Destructive Testing, Optical, Laser, Capacitive End User: Aerospace, Automotive Manufacturers, Electronics, Construction Application: Metal Coatings, Plastic Coatings, Paints, Ceramics |
| Companies Covered | Elcometer Limited, Helmut Fischer, DeFelsko Corporation, Extech Instruments, ElektroPhysik, Erichsen, Oxford Instruments, KLA, Hitachi High-Tech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Thickness Measurement Instruments Market Strategic Shifts
Measurement modality convergence and regulatory documentation automation are compressing instrument replacement cycles while elevating software and service attach rates.
Ultrasonic pulse-echo technology with dry-couplant probes is displacing traditional magnetic and eddy current gauges in automotive paint shops where multilayer clearcoat-basecoat-primer systems require non-destructive validation of each interface. BMW and Mercedes-Benz assembly plants in Stuttgart and Spartanburg have standardized on these systems for EV battery tray coating verification. The shift is displacing handheld spot-check workflows with robotic inline stations that feed thickness data directly into manufacturing execution systems.
EPA industrial coating rules under NESHAP are mandating continuous parametric monitoring for surface coating operations above threshold emission levels. Facilities must maintain calibrated, auditable thickness records that link coating weight to solvent usage calculations. Automotive OEMs in Michigan and Ohio are responding by specifying ISO 17025-accredited instruments with automated data logging that satisfies both thickness quality and environmental compliance documentation.
Service unbundling is separating hardware procurement from calibration and certification contracts. Industrial buyers in marine and infrastructure sectors now source instruments through capital budgets while purchasing traceable calibration services through operational expenditure frameworks. This bifurcation is most pronounced in Germany's automotive supplier corridor, where paint shops negotiate three-year calibration subscriptions independent of initial gauge acquisition.
Coating Thickness Measurement Instruments Market Segmentation
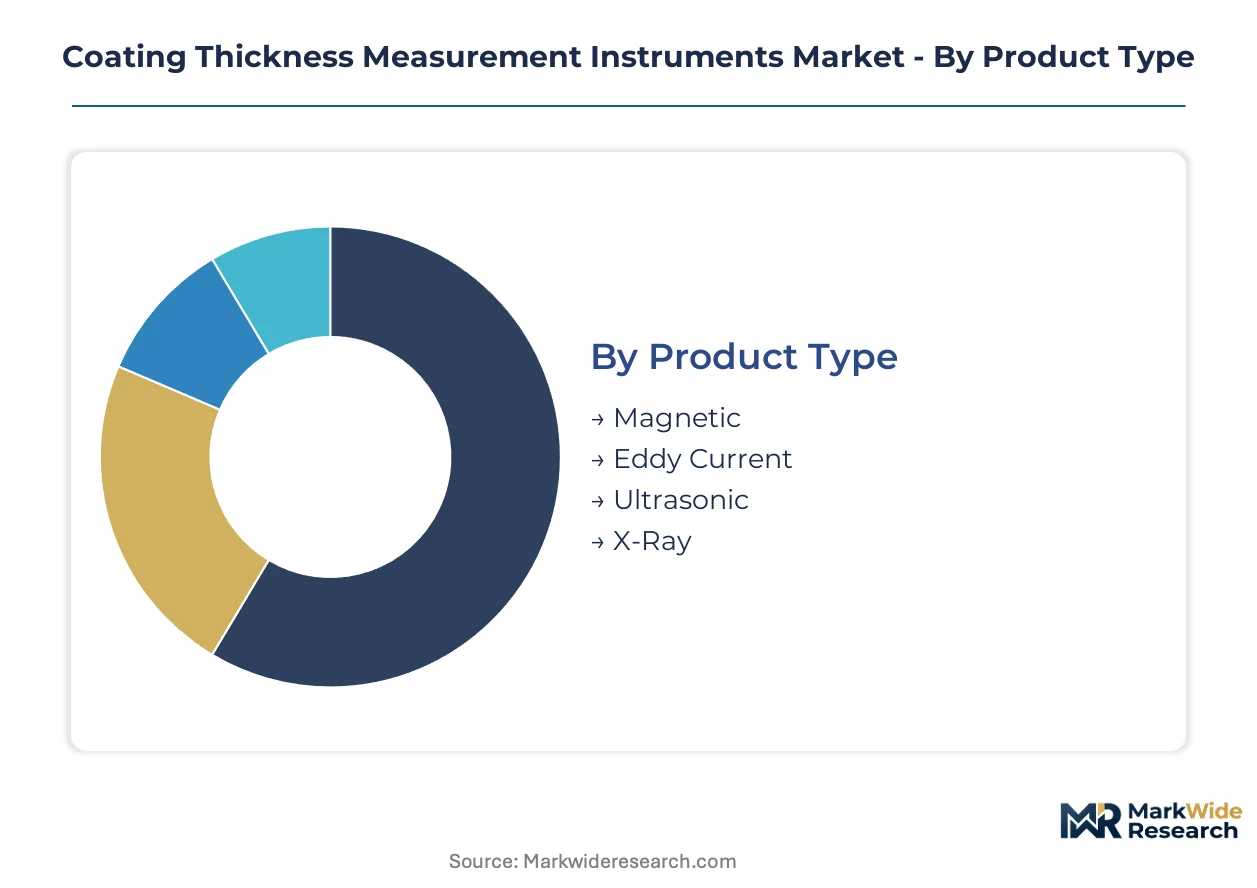
Segmentation reveals how coating thickness measurement instruments align with substrate evolution and regulatory documentation requirements. Technology choice directly determines capital intensity, calibration burden, and compliance auditability across end-use verticals.
Product Type:
Margin pools concentrate in modalities that handle multilayer substrates without destructive sampling, commanding premium positioning through calibration subscription attach rates.
- Magnetic:Ferromagnetic substrate measurement using Hall effect sensors achieves 0.1 micrometer resolution on steel galvanizing lines. German automotive supplier corridors in Stuttgart and Wolfsburg deploy these for cost-sensitive chassis component verification where aluminum penetration remains limited.
- Eddy Current:Electromagnetic induction penetrates non-ferrous metals and conductive coatings without surface contact. BMW Spartanburg and Mercedes-Benz Tuscaloosa assembly plants specify these for aluminum-intensive EV body architectures where magnetic gauges fail.
- Ultrasonic:Pulse-echo dry-couplant probes validate multilayer automotive paint systems in real time.
- X-Ray:X-ray fluorescence commands six-figure price points for precious metal plating verification in semiconductor packaging.
The dominant share belongs to Magnetic gauges, while Eddy Current is closing the gap fastest.
Technology:
Technology selection hinges on whether measurement occurs inline during production or offline in laboratory settings, with diverging software and service revenue models.
- Non-Destructive Testing:ISO 17025-accredited protocols enable regulatory documentation without substrate damage. EPA NESHAP compliance in Michigan and Ohio surface coating operations mandates these systems for continuous parametric monitoring linked to solvent usage calculations.
- Optical:White light interferometry and confocal microscopy resolve sub-micron transparent coatings on optical components.
- Laser:Triangulation and chromatic aberration methods scan moving webs in continuous galvanizing lines.
- Capacitive:Dielectric property measurement targets thin polymer films on non-conductive substrates.
Non-Destructive Testing holds the installed base lead, though Optical methods are expanding most quickly in electronics miniaturization applications.
End User:
End user segmentation tracks capital deployment cycles and certification stringency, with aerospace and automotive driving replacement demand toward multi-technology platforms.
- Aerospace:FAA airworthiness directives and EASA certification requirements mandate traceable thickness documentation for turbine blade thermal barrier coatings. Boeing Charleston and Airbus Mobile assembly plants specify X-ray fluorescence for superalloy substrate verification.
- Automotive Manufacturers:Lightweighting programs and EV battery enclosure coating verification force metrology budget reallocation toward robotic inline stations.
- Electronics:Tightening gold and palladium plating tolerances in semiconductor packaging favor X-ray fluorescence capital intensity.
- Construction:Steel-heavy infrastructure inspection in marine and bridge applications retains cost-sensitive magnetic gauge dominance.
Automotive Manufacturers command the largest procurement volume, while Aerospace shows the steepest expansion trajectory from fleet renewal and MRO documentation mandates.
Application:
Application segmentation mirrors substrate material evolution and coating functional requirements, with multilayer systems driving modality convergence.
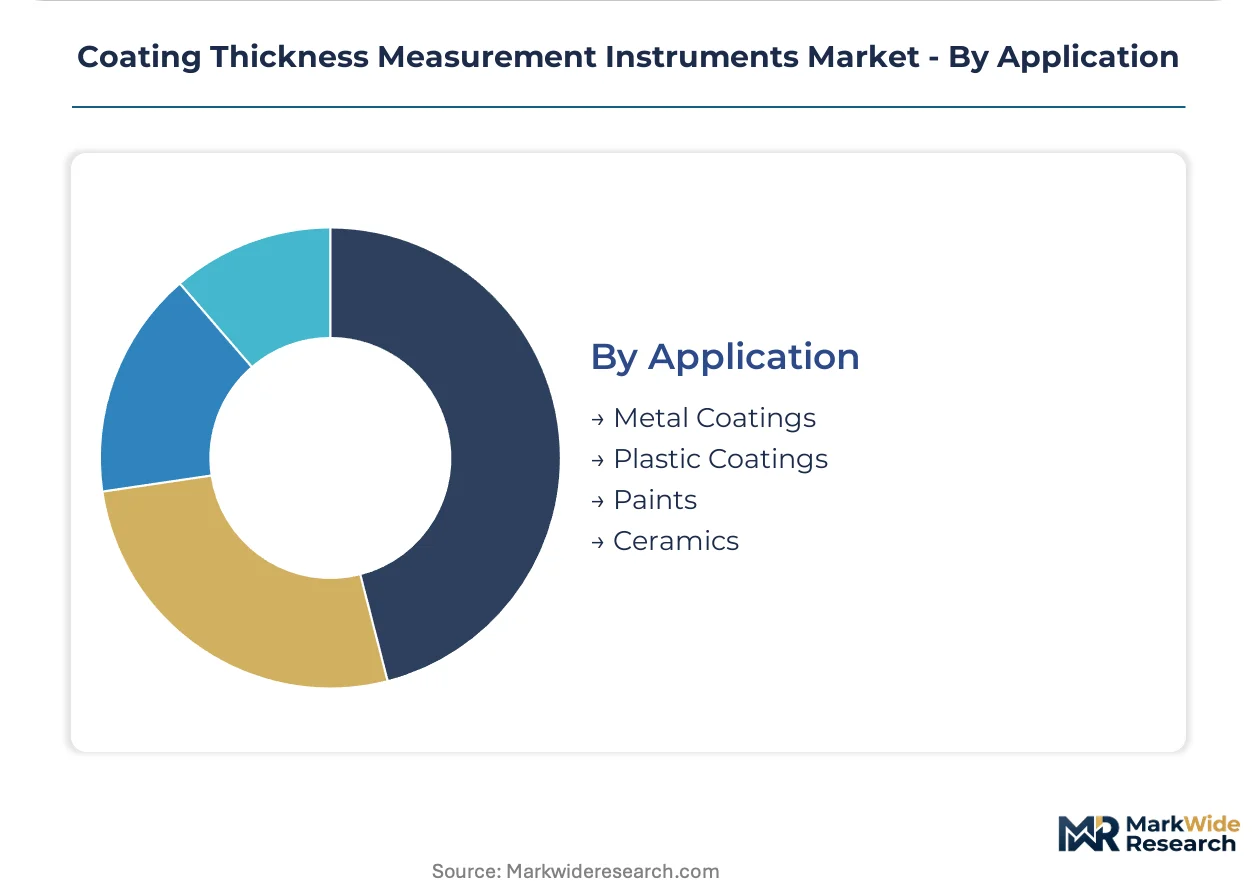
- Metal Coatings:Galvanizing, anodizing, and electroplating operations require non-destructive validation of zinc, chrome, and nickel layers. REACH hexavalent chromium restrictions in European galvanizing lines elevate documentation burdens that only calibrated, auditable systems satisfy.
- Plastic Coatings:Vacuum metallization and conductive coatings on polymer substrates demand eddy current or capacitive methods.
- Paints:Multilayer automotive clearcoat-basecoat-primer systems displace handheld spot-checks with ultrasonic inline monitoring.
- Ceramics:Thermal spray coatings on turbine components require specialized ultrasonic or optical gauges for high-temperature material stacks.
Metal Coatings retains volume leadership from construction and automotive supplier demand, though Paints is gaining share fastest from EV battery tray coating verification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers deploy inline ultrasonic systems for multilayer EV coatings, while US surface coating operations prioritize EPA-compliant documentation hardware. Indian paint shops and Japanese semiconductor packaging lines represent diverging modality mixes driven by substrate specialization and regulatory stringency.
United States
Automotive OEMs in Michigan and Ohio drive demand for ISO 17025-accredited instruments with automated data logging. EPA NESHAP rules mandate continuous parametric monitoring for surface coating operations above threshold emission levels. Detroit-area assembly plants specify robotic inline stations that feed thickness data directly into manufacturing execution systems.
Germany
Paint shops and galvanizing lines in Stuttgart and Wolfsburg require real-time inline monitoring systems for lightweighting program verification. REACH substance restrictions on hexavalent chromium coatings elevate documentation burdens that only calibrated, auditable systems satisfy. The automotive supplier corridor concentrates metrology budget deployment toward multi-technology platforms.
China
Electronics manufacturers in the Yangtze River Delta and Pearl River Delta purchase X-ray fluorescence systems for precious metal plating verification. GB standards and MIIT industrial quality regulations tighten tolerances on semiconductor packaging coatings. Shenzhen and Shanghai assembly plants drive capital deployment toward six-figure instrumentation for gold and palladium layer validation.
India
Paint shops and galvanizing lines near Chennai and Pune lack real-time inline monitoring infrastructure for automotive supplier verification. BIS certification requirements and the PLI scheme for advanced chemistry cell manufacturing elevate coating quality documentation standards. The automotive supplier corridor concentrates demand for cost-sensitive magnetic and eddy current gauges.
Japan
Semiconductor packaging facilities in the Kanto and Kansai regions specify X-ray fluorescence for sub-micron precious metal plating tolerances. METI industrial standards and JIS calibration protocols mandate traceable thickness documentation for electronics miniaturization. Yokohama and Osaka manufacturing clusters drive premium positioning for high-resolution instrumentation.
Coating Thickness Measurement Instruments Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that dominates modality-specific applications. The upper tier commands premium positioning through calibration laboratory networks and multi-technology platform integration. Three archetypes populate the competitive map: precision metrology houses with century-old brand recognition, ruggedized field instrument specialists, and semiconductor-focused X-ray fluorescence providers. Consolidation pressure is accelerating through strategic partnerships and geographic expansion into underpenetrated automotive supplier corridors.
Within the precision metrology tier, Helmut Fischer and Elcometer Limited exemplify divergent geographic anchoring strategies. Helmut Fischer sustains positioning through deep calibration laboratory networks across industrial clusters, while Elcometer leverages century-old brand recognition in protective coatings inspection. DeFelsko Corporation occupies the ruggedized field instrument position purpose-built for marine and infrastructure inspection cycles.
| Leading Market Players |
|---|
| Elcometer Limited |
| Helmut Fischer |
| DeFelsko Corporation |
| Extech Instruments |
| ElektroPhysik |
| Erichsen |
| Oxford Instruments |
| KLA |
| Hitachi High-Tech Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for ISO 17025-certified reference materials concentrate pricing power with German and Swiss calibration laboratories, while spot buyers in India's automotive supplier corridor face 15-20% premiums for expedited traceability documentation.
Pricing Analysis
Long-term calibration subscription contracts dominate procurement in Germany's automotive supplier corridor, where paint shops negotiate three-year service agreements independent of initial gauge acquisition. Price differentiation hinges on ISO 17025 accreditation tier and bundled software analytics, with premium tiers commanding 40-60% markups over uncertified field gauges. Cost compression in magnetic gauge segments is intensifying as Chinese manufacturers enter the construction and shipbuilding inspection markets. Tier 2 automotive suppliers in Michigan and Ohio exhibit the highest price sensitivity, while aerospace OEMs in Charleston and Mobile prioritize traceability over unit cost.
Supply Chain Analysis
Container availability constraints on Hamburg-Shanghai trade lanes inflate inbound logistics costs for precision sensor assemblies sourced from East Asian electronics clusters. Manufacturing concentrates in Germany, Switzerland, and Japan for calibration-grade reference materials, while gauge assembly draws from China and Mexico for cost-sensitive magnetic and eddy current models. Single-source vulnerability persists for X-ray fluorescence detector arrays tethered to Japanese semiconductor fabrication equipment. Distribution runs through authorized distributor networks in industrial corridors, with direct OEM relationships dominating high-value inline monitoring system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coating thickness measurement instruments market is recovering from a cyclical trough driven by automotive production normalization and EV battery enclosure coating verification program ramp-ups.
For Market Incumbents: Secure calibration laboratory accreditation expansion in underrepresented automotive supplier corridors before emerging X-ray fluorescence specialists capture semiconductor packaging accounts. Defend magnetic gauge margins through backward integration into Hall effect sensor production, insulating against Chinese cost competition in construction and marine inspection segments. For New Entrants and Emerging Players: ISO 17024 fast-track certification programs for NDT technicians unlock immediate service revenue in India's Chennai-Pune automotive corridor, where qualified inspector scarcity constrains inline monitoring adoption. Target cost-sensitive eddy current gauge segments for aluminum-intensive EV architectures, leveraging direct sales to Tier 2 paint shops bypassing established distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded coating thickness divisions lacking multi-technology platform integration. Long-term viability centers on software and calibration attach rates rather than hardware shipment volumes. Watch for EPA NESHAP enforcement acceleration in Michigan and Ohio surface coating operations as the inflection signal for compliance-documentation hardware demand.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | ISO 17025 accreditation in India's automotive supplier corridor captures EV battery tray verification demand. |
| Multi-Technology Platform Integration | Combined magnetic-eddy current-ultrasonic systems address diversifying substrate portfolios in Stuttgart assembly plants. |
| AI-Integrated Defect Prediction Software | Machine learning thickness variance algorithms enable predictive maintenance subscriptions for coating line operators. |
| Backward Integration into Sensor Production | In-house Hall effect and eddy current coil manufacturing defends margin position against Chinese cost competition. |
| Long-Term Calibration Subscription Contracts | Three-year service agreements with German automotive suppliers transform capital expenditure into recurring operational revenue. |
Study Parameters
The analysis maps magnetic, eddy current, ultrasonic, and X-ray fluorescence modalities, each validated through coating line engineers, calibration laboratory managers, automotive metrology directors, and marine inspection contractors. Primary interviews with these stakeholders combined with secondary validation from SEC filings of precision instrumentation firms, ISO 17025 accreditation registries, EPA NESHAP compliance databases, and automotive production statistics. Bottom-up gauge shipment data triangulated against top-down metrology budget allocations across end-use verticals.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include technology type, measurement principle, end-use vertical, application substrate, and geographic regulatory cluster. CAGRs derived from fitted growth curves incorporating automotive lightweighting program timelines, REACH compliance deadlines, and EV battery enclosure coating verification adoption rates. Industry-specific inputs included semiconductor packaging gold plating tolerance trajectories and marine infrastructure inspection cycle frequencies.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification investment, stable REACH enforcement trajectories, or continued EPA NESHAP documentation mandates would require recalibration. Forecasts reflect assumptions regarding substrate material substitution rates and certified NDT technician pipeline expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Spectrometry Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Digital Vernier Caliper Market