
 Handheld Devices Battery Market | 2026-2036
Handheld Devices Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Devices Battery Market Insights
Subscription-based battery health monitoring and predictive replacement services is recalibrating how OEMs monetize power systems over device lifecycles. Samsung SDI leverages its integrated materials science pipeline to sustain cost leadership in high-density cylindrical cells. Panasonic Corporation anchors premium supply relationships through its proprietary silicon-anode development programs. BYD Company Limited dominates vertical cell-to-pack integration for enterprise handheld fleets.
Handheld devices batteries are rechargeable electrochemical cells engineered to deliver sustained current densities between 500 mAh and 10,000 mAh within constrained volumetric envelopes, typically utilizing layered oxide cathodes and graphite or silicon-composite anodes separated by microporous polymer membranes. Lithium-ion and lithium polymer chemistries occupy the highest margin tiers due to energy density requirements in smartphones and wearable devices, while nickel-metal hydride retains niche positioning in cost-sensitive educational hardware. Application segmentation shows enterprise mobility scanners and medical point-of-care devices generating disproportionate margin contributions relative to consumer electronics volume.
The EU Battery Regulation and REACH compliance frameworks in Europe, alongside China's GB/T standards administered by SAMR and the US FAA guidelines for lithium-ion air transport, collectively elevate testing and certification burdens for cross-border shipments. Japan's METI circular economy mandates for portable electronics further tighten material recovery obligations. Stakeholders must monitor solid-state pilot production timelines and regional subsidy realignments to calibrate capacity commitments against evolving qualification thresholds.
Market Dynamics
Solid-state electrolyte research is compressing qualification timelines while China's GB/T standards and the EU Battery Regulation simultaneously expand testing burdens, creating a bifurcation between early adopters and compliance-laggards in handheld power systems.
Growth Catalysts
- Enterprise Mobility Expansion:Field service operations across logistics and healthcare are deploying rugged handheld scanners requiring extended cycle life. These fleets prioritize energy density over upfront cost.
- SAMR Certification Harmonization:China's GB standards for lithium-ion safety are streamlining cross-border approvals for Shenzhen-based manufacturers. Reduced retesting accelerates regional export velocity.
- Silicon-Anode Maturation:Silicon-composite anode architectures are achieving commercial scale in premium wearable devices. The technology extends runtime without volumetric penalty in constrained enclosures.
Market Restraints
- Cobalt Supply Concentration:DRC mining dependencies and Indonesian processing bottlenecks expose layered oxide cathode supply chains to price volatility. Alternative chemistries remain performance-constrained.
- Polymer Separator Import Reliance:Microporous membrane production concentrates in South Korean and Japanese specialty chemical corridors. Domestic capacity gaps in emerging manufacturing regions inflate working capital requirements.
- REACH Compliance Escalation:ECHA substance restrictions on fluorinated electrolyte additives are forcing formula reformulations. Reformulation cycles extend qualification timelines by 8-14 months for European-bound shipments.
Strategic Opportunities
- Indian PLI Localization:India's production-linked incentive schemes for advanced chemistry cell manufacturing are attracting cathode active material investments. Early entrants capture preferential offtake terms from domestic electronics assemblers.
- Diagnostic Tool Electrification:Point-of-care medical devices are transitioning from alkaline primary cells to rechargeable lithium polymer systems. This application commands 40-60% unit value premiums over consumer electronics.
- Battery-as-a-Service Models:Subscription-based health monitoring and predictive replacement services are decoupling hardware from power system monetization. OEMs capture recurring revenue across extended device lifecycles.
Industry Challenges
- Solid-State Process Engineering Talent:Thin-film electrolyte deposition and ceramic interface engineering expertise remains concentrated in Japanese and South Korean national laboratories. Western manufacturers face recruitment bottlenecks for pilot line scale-up.
- Multi-Jurisdiction Certification Parallelism:Simultaneous FAA air transport, METI circular economy, and EU Battery Regulation compliance requires redundant testing protocols. Documentation burdens consume 15-20% of product development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Devices Battery Market |
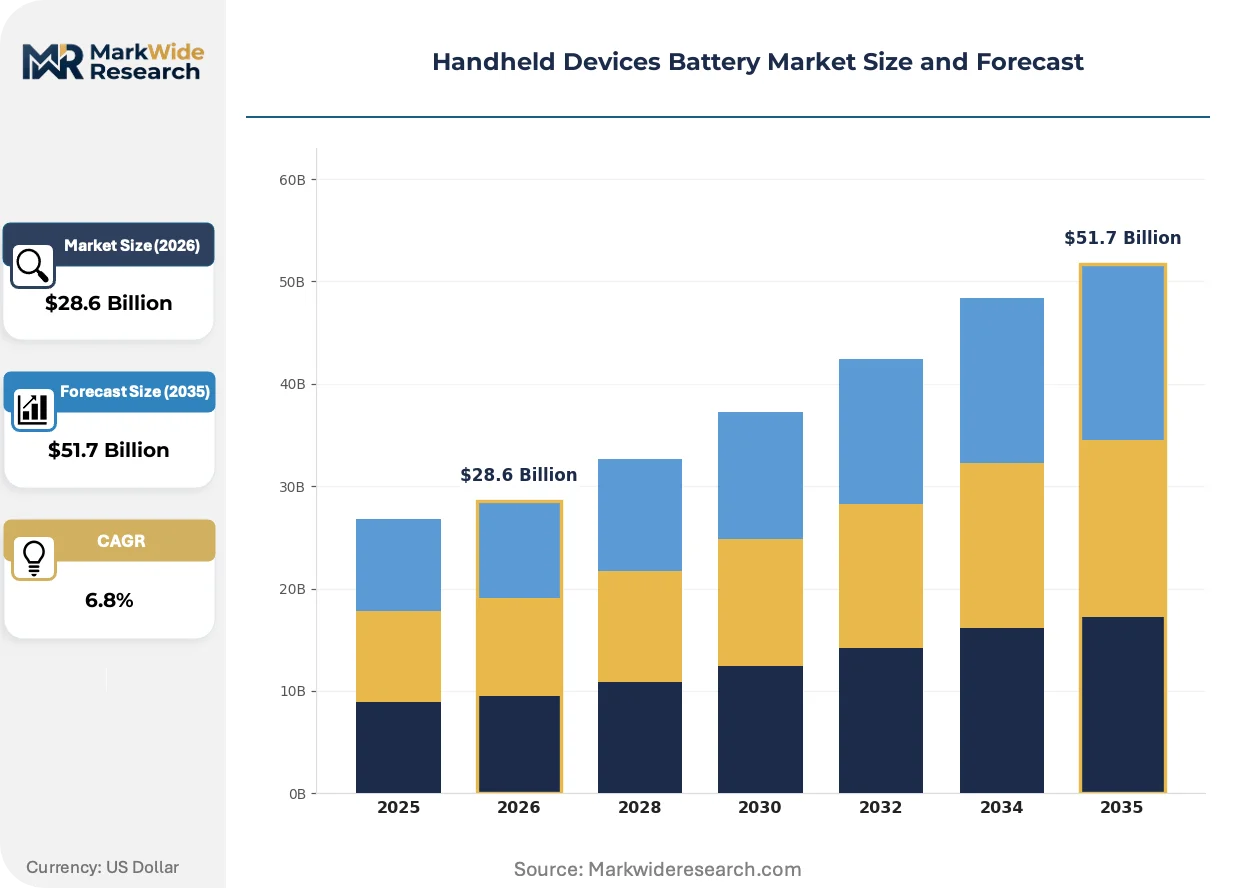
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-Metal Hydride, Lithium Polymer, Lead Acid Application: Smartphones, Tablets, Laptops, Wearable Devices End User: Consumers, Enterprises, Educational Institutions, Health Sector Form Factor: Flat, Cylinder, Custom, Modular |
| Companies Covered | LG Energy Solution, Samsung SDI, Panasonic Corporation, Amperex Technology Limited, Sony Corporation, Anker Innovations, Shenzhen Grepow Battery, Hitachi High-Tech, BYD Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Devices Battery Market Trends and Innovations
Handheld battery architectures are converging around three vectors: solid-state material platforms, regulatory-driven chemistry disclosure requirements, and service-based monetization models that decouple hardware from power system revenue.
Solid-state electrolyte technology is consolidating competitive positioning in premium handheld segments. Samsung SDI and Panasonic are accelerating pilot production of sulfide-based ceramic cells for enterprise diagnostic tools. The technology is consolidating margin capture among integrated materials science pipelines while compressing qualification timelines for second-tier suppliers.
REACH substance disclosure mandates and the EU Battery Regulation's digital passport requirements are reshaping supply chain transparency obligations. Manufacturers must now document cobalt provenance and carbon intensity across tier-three suppliers. Medical point-of-care device OEMs are most affected, responding by consolidating supplier bases to reduce audit complexity.
Enterprise buyers are compressing procurement cycles through centralized fleet management platforms. Third-party logistics providers and healthcare systems are unbundling battery replacement from device acquisition, contracting directly with cell manufacturers for volume pricing. This pattern is most visible in German automotive aftermarket channels and US hospital procurement consortia.
Handheld Devices Battery Market Segmentation
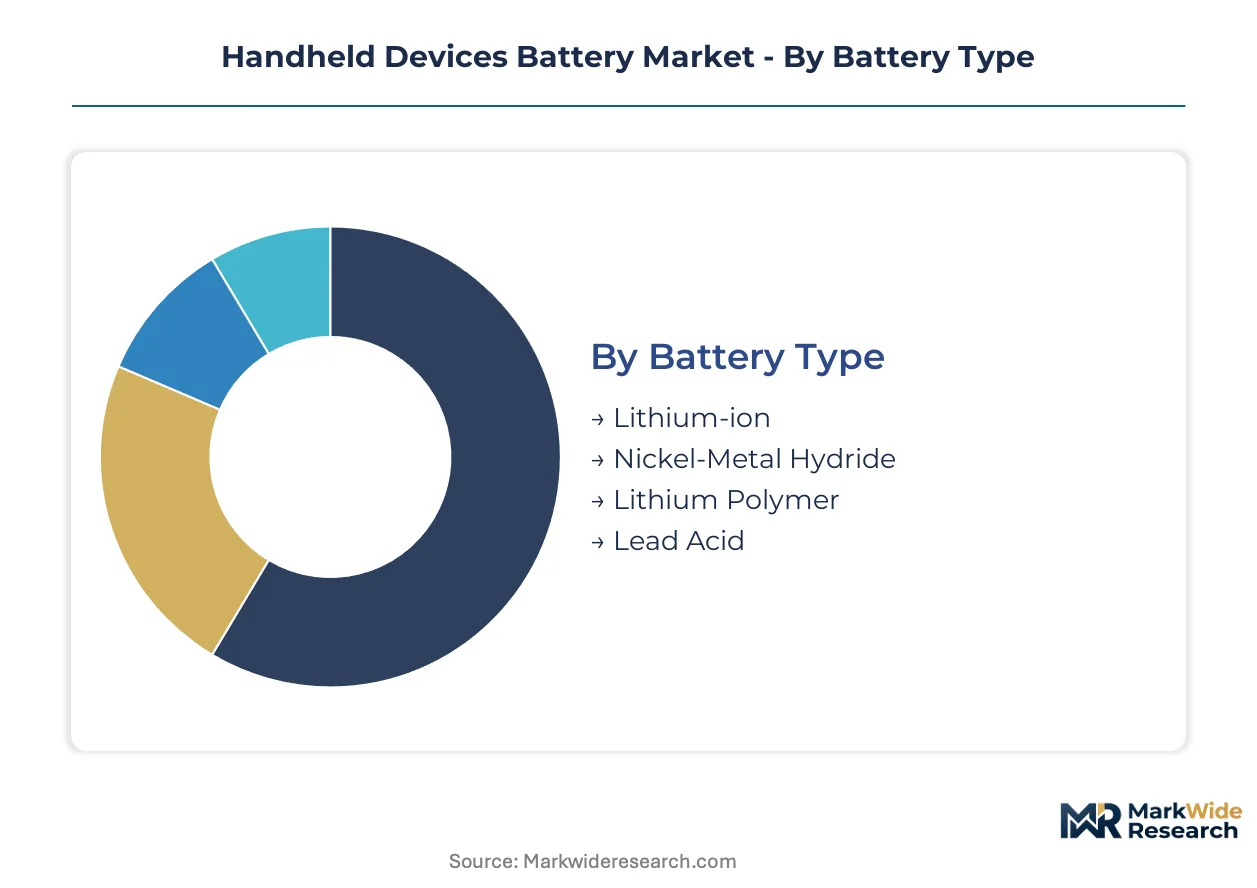
Handheld battery procurement decisions hinge on trade-offs between energy density, cycle life, and certification burden. Enterprise buyers prioritize volumetric efficiency and predictive service models over upfront unit economics. Consumer segments drive volume but compress margins through commoditized cylindrical and prismatic formats.
Battery Type:
Cost tier stratification determines supplier selection, with premium silicon-anode systems commanding 3-4x unit values over legacy chemistries.
- Lithium-ion:Layered oxide cathodes paired with graphite anodes deliver 500-10,000 mAh capacities in standardized 18650 and 21700 cylindrical formats. Demand concentrates in Shenzhen electronics corridors where GB/T certification harmonization accelerates export velocity to enterprise scanner manufacturers.
- Lithium Polymer:Pouch-cell architectures with gel electrolytes enable sub-3mm thickness for wearable enclosures. Samsung SDI and Panasonic anchor premium supply relationships through proprietary silicon-anode development programs targeting medical point-of-care devices.
- Nickel-Metal Hydride:Cost-sensitive educational hardware retains niche positioning due to simpler thermal management requirements and absence of lithium-ion air transport restrictions.
- Lead Acid:Sealed AGM variants persist in legacy industrial handheld diagnostic tools requiring deep-cycle tolerance in temperature-extreme field conditions.
Volume sits with Lithium-ion; growth tilts toward Lithium Polymer.
Application:
Margin contribution inversely correlates with shipment volume, as specialized medical and enterprise devices sustain 40-60% value premiums over consumer electronics.
- Smartphones:High-density stacked-cell designs with dual-cell architectures push 5,000+ mAh into sub-8mm profiles. South Korean R&D corridors dominate cathode active material innovation for flagship tier devices.
- Wearable Devices:Curved and segmented battery geometries accommodate biometric sensor arrays in constrained wrist-worn enclosures. Silicon-composite anode maturation extends runtime without volumetric penalty.
- Tablets:Prismatic lithium polymer cells balance screen-powering sustained discharge with thin-profile industrial design constraints.
- Laptops:3-4 cell series-parallel configurations prioritize cycle life degradation curves under constant partial-state-of-charge operating patterns.
Shipment scale favors Smartphones; margin expansion concentrates in Wearable Devices.
End User:
Procurement centralization is compressing vendor counts, with enterprise fleet managers and hospital procurement consortia unbundling battery replacement from device acquisition.
- Enterprises:Rugged handheld scanner deployments in logistics and field service prioritize extended cycle life over upfront cost. Third-party logistics providers contract directly with cell manufacturers for volume pricing.
- Health Sector:Point-of-care diagnostic tool electrification commands premium unit values for rechargeable lithium polymer systems replacing alkaline primary cells.
- Consumers:Replacement battery aftermarket concentrates in online retail channels with minimal brand loyalty and price-driven selection.
- Educational Institutions:Cost-sensitive hardware procurement retains nickel-metal hydride for student device fleets with lower utilization intensity.
Procurement scale sits with Enterprises; value capture tilts toward Health Sector.
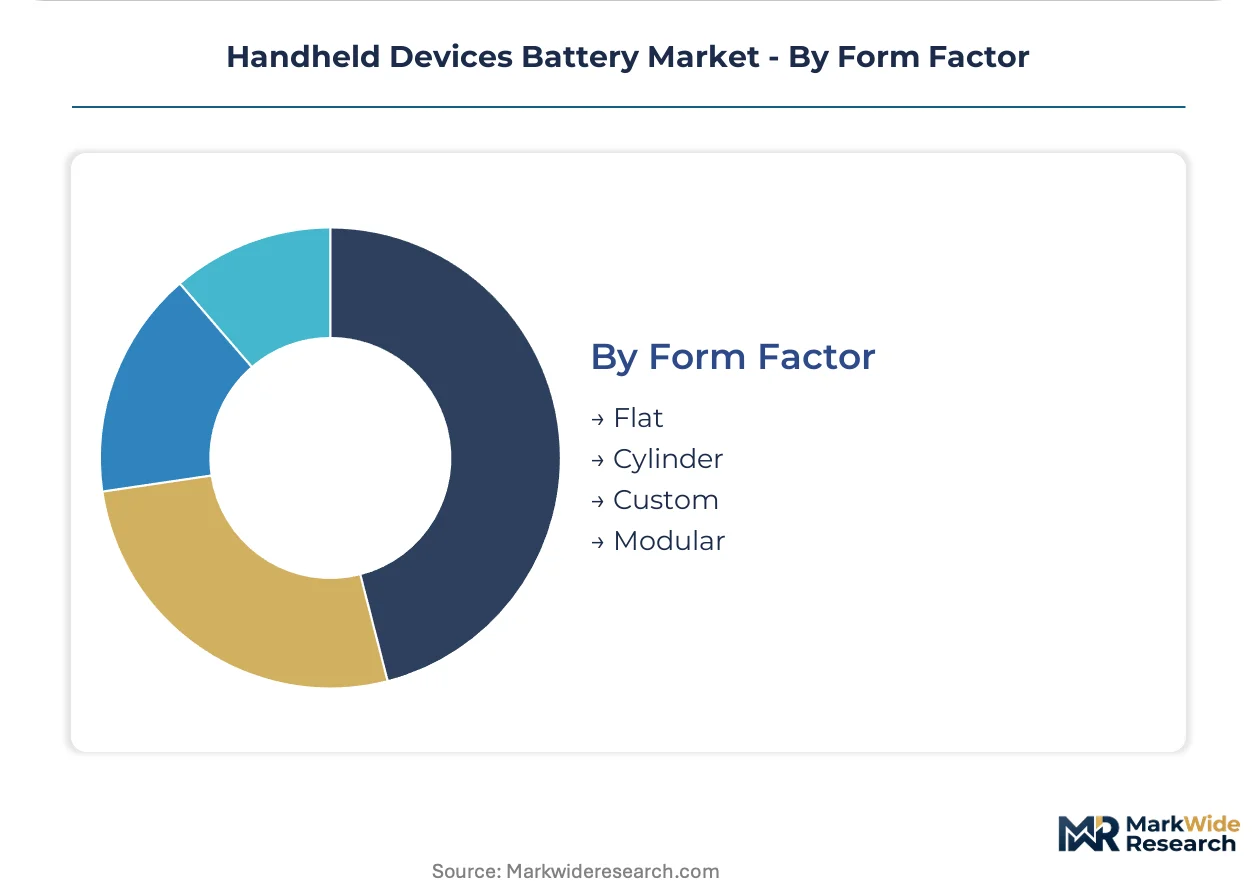
Form Factor:
Design integration depth separates captive cell-to-pack specialists from commodity cell suppliers.
- Custom:Medical device OEMs specify irregular geometries matching enclosure cavities, consolidating supplier bases to reduce REACH audit complexity.
- Flat:Prismatic and pouch formats dominate smartphone and tablet segments with maximized active area-to-volume ratios.
- Cylinder:Standardized 18650 and 21700 formats enable procurement flexibility but compress differentiation in aftermarket replacement channels.
- Modular:Hot-swappable designs in enterprise diagnostic tools support continuous operation without full device shutdown.
Standardization sits with Cylinder; integration value tilts toward Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters dominate cell production, while North American and European markets concentrate consumption in enterprise and medical device segments. This geographic split shapes regulatory compliance burdens and supply chain configuration decisions for handheld power system vendors.
China
Shenzhen's electronics ecosystem anchors global lithium polymer cell assembly for smartphone and tablet OEMs. SAMR's GB/T standards harmonization streamlines cross-border certification, reducing retesting cycles for export-bound manufacturers. The Pearl River Delta corridor concentrates cathode active material processing and pouch-cell fabrication capacity.
South Korea
Seoul Capital Area R&D corridors drive silicon-anode and high-nickel cathode innovation for premium wearable devices. METI circular economy mandates in neighboring Japan create compliance spillover effects for Korean exporters. Busan-Ulsan specialty chemical clusters supply microporous separator membranes to regional cell manufacturers.
United States
FAA lithium-ion air transport guidelines and FDA device electrification standards elevate testing burdens for medical point-of-care battery suppliers. Hospital procurement consortia in the Northeast Corridor unbundle power system replacement from device acquisition. Greater Boston's diagnostic tool manufacturers drive demand for extended cycle-life configurations.
Germany
ECHA REACH substance restrictions on fluorinated electrolyte additives force formula reformulations for European-bound shipments. Automotive aftermarket channels in Bavaria and Baden-Württemberg centralize fleet battery procurement through third-party logistics platforms. The country's national pharmaceutical regulator enforces stringent cell-to-pack traceability for medical device applications.
India
PLI schemes for advanced chemistry cell manufacturing attract cathode active material investments to Gujarat and Tamil Nadu. Domestic electronics assemblers in Karnataka and Maharashtra generate preferential offtake demand for localized suppliers. BIS certification requirements create entry barriers for non-compliant imports while supporting nascent cell fabrication capacity.
Handheld Devices Battery Market Competitive Landscape
Top-tier vendors anchor premium supply relationships through proprietary materials science pipelines, while mid-tier specialists compete on cycle-life specifications for enterprise scanner fleets. The vendor base stratifies across integrated cell-to-pack architects, captive R&D houses, and commodity cylindrical cell suppliers. Two dominant archetypes emerge: integrated materials science pipelines controlling cathode-anode-separator verticals, and regional fabricators leveraging certification proximity to local OEMs. Competitive moves concentrate on silicon-anode pilot scale-up and M&A targeting diagnostic tool electrification channels.
Among East Asian-integrated conglomerates, LG Energy Solution and Samsung SDI occupy positions exemplifying materials-forward competitive strategy, while BYD Company Limited anchors the vertical cell-to-pack integration archetype for enterprise handheld deployments. Panasonic Corporation sits within the premium-tier specialist category through its silicon-anode development focus. These three named entities collectively represent the strategic positioning spectrum visible across the competitive set: captive materials science, full vertical integration, and premium technology specialization.
| Leading Market Players |
|---|
| LG Energy Solution |
| Samsung SDI |
| Panasonic Corporation |
| Amperex Technology Limited |
| Sony Corporation |
| Anker Innovations |
| Shenzhen Grepow Battery |
| Hitachi High-Tech |
| BYD Company Limited |
| Others |
Pricing and Supply Chain Analysis
Enterprise procurement consortia unbundling battery replacement from device acquisition are compressing vendor counts and forcing supply base consolidation. This buyer-driven restructuring elevates contract-based long-term offtake agreements while squeezing spot-market premiums for commodity cylindrical formats.
Pricing Analysis
Margin tightening in standard lithium-ion tiers reflects GB/T certification harmonization flattening regional price premiums. Three-tier pricing structure across premium silicon-anode, certified enterprise-grade, and economy consumer tiers separates medical point-of-care applications from educational hardware. Cost-down pressure on cylindrical 18650 formats accelerates because Shenzhen-based manufacturers leverage SAMR streamlining for export velocity. Health sector procurement shows least price sensitivity; consumer aftermarket channels exhibit maximal elasticity.
Supply Chain Analysis
Specialized workforce availability for ceramic interface engineering concentrates in Seoul Capital Area and Osaka-Kobe corridors, constraining Western pilot line scale-up. Cell production draws from China, South Korea, and Japan, with cathode active material processing tethered to Pearl River Delta and Busan-Ulsan clusters. Microporous separator membrane supply rests on South Korean and Japanese specialty chemical producers, creating single-source vulnerability for emerging manufacturing regions. Distribution runs through OEM captive channels for enterprise fleets and online retail for consumer replacement segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The handheld battery market is becoming a vertical-integration race. Players are pursuing upstream control over silicon-anode material pipelines to capture margin otherwise lost to specialty chemical suppliers.
For Market Incumbents: Extend silicon-anode pilot production timelines ahead of solid-state commercialization to defend premium positioning. Lock in cathode active material offtake from Busan-Ulsan corridors before capacity commitments saturate. Counter emerging Chinese cell-to-pack specialists by embedding predictive health monitoring into enterprise fleet contracts. For New Entrants and Emerging Players: Solid-state electrolyte deposition expertise offers a technology-first wedge into medical point-of-care diagnostic tools. Target Indian PLI beneficiary zones for cathode material investments with preferential offtake terms from Karnataka electronics assemblers. Pursue certification-first entry via BIS compliance for domestic Indian supply before expanding export-facing capacity. For Investors and Strategic Acquirers: The window for entry favors integrated materials science pipelines with captive separator-anode-cathode verticals. Long-term viability hinges on solid-state process engineering talent access and multi-jurisdiction certification parallelism capabilities. Watch FAA-EU Battery Regulation testing burden divergence as inflection signal for regional manufacturing footprint decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Anode Pilot Scale-Up | Samsung SDI and Panasonic anchor premium supply relationships through proprietary development programs. |
| GB/T Certification Harmonization | SAMR streamlining reduces retesting cycles for Shenzhen manufacturers exporting to enterprise scanner OEMs. |
| Cell-to-Pack Vertical Integration | BYD dominates enterprise handheld fleet deployments through captive module and pack assembly. |
| Battery-as-a-Service Launch | Subscription health monitoring decouples hardware from power system monetization for extended lifecycles. |
| Indian PLI Zone Entry | Advanced chemistry cell incentives in Gujarat attract cathode investments with domestic offtake preference. |
Research Methodology
Trade databases, SAMR certification registries, and ECHA REACH substance filings formed the secondary backbone for supply chain mapping. Primary interviews with cell manufacturing executives, enterprise fleet procurement managers, medical device OEM sourcing leads, and specialty chemical R&D directors validated demand-side assumptions. Bottom-up and top-down triangulation cross-checked installed base estimates against cathode active material shipment data.
Analytical lenses combined bottom-up capacity build-up with top-down end-use consumption modeling across the projection horizon. Segmentation dimensions included battery chemistry tier, application device category, end-user procurement archetype, and form factor integration depth. CAGRs derived from elasticity-adjusted price-volume relationships with silicon-anode adoption curves and solid-state pilot production timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to FAA lithium-ion air transport guidelines and METI circular economy mandate enforcement variance. Forecasts reflect documented assumptions about SAMR-EU Battery Regulation testing burden parallelism. Material deviation in cobalt supply concentration or REACH fluorinated additive restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
GPIO Expanders Market
Electronic Components
Crystal Oscillators Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Film Capacitor Market
Electronic Components
Coaxial Coupler Market
Electronic Components
Solder Paste for Mini LED Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
North America MLCC Market
Electronic Components
Efuse Market
Electronic Components
Primary Charge Roller Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Microspeaker Market
Electronic Components
Surface Mountable Laser Direct Structuring Antenna (LDS) Market