
 Single Layer Capacitors Market | 2026-2036
Single Layer Capacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Single Layer Capacitors Market Analytics
The price-performance boundary between premium ceramic grades and commodity aluminum variants is hardening as automotive qualification requirements diverge from consumer electronics specs. Murata Manufacturing leverages its thin-film technology leadership to sustain margins in high-frequency telecommunications applications. Vishay Intertechnology anchors North American supply chains through specialized tantalum capacitor production for industrial and military end uses.
Single layer capacitors store electrical energy in a monolithic dielectric layer, typically achieving capacitance values from picofarads to microfarads with voltage ratings spanning 6.3V to several kilovolts depending on ceramic formulation or anodized dielectric construction. Their primary purpose centers on decoupling, filtering, and energy buffering in compact electronic assemblies where board space constraints dominate design decisions. MLCC and ceramic product types command the largest volume share, though tantalum formulations retain margin advantages in high-reliability automotive and aerospace applications where volumetric efficiency outweighs unit cost. Surface mount form factors dominate new designs, while through-hole configurations persist in industrial equipment with extended service-life requirements.
REACH substance restrictions and RoHS lead-free mandates in Europe constrain dielectric material formulations and solder termination compositions, pushing manufacturers toward barium titanate refinements and nickel electrode systems. China's SAMR enforces GB standards for capacitor reliability testing that affect market access for imported components. Japan's METI energy-efficiency labeling requirements for consumer electronics indirectly shape capacitor specification trends through downstream OEM procurement standards. Stakeholders must monitor evolving automotive functional safety certifications and material passport traceability rules as these frameworks increasingly determine supplier qualification thresholds.
Market Dynamics
Automotive functional safety mandates are compressing qualification timelines for high-reliability ceramic formulations, forcing capacitor manufacturers to accelerate validation cycles while maintaining dielectric stability across temperature extremes.
Growth Catalysts
- Automotive Electrification:Battery management systems and onboard chargers in electric vehicles require high-voltage single layer capacitors with AEC-Q200 automotive qualification, pulling volume toward specialized ceramic grades.
- REACH Substance Restrictions:European ECHA enforcement against lead-bearing dielectrics is accelerating nickel electrode adoption and barium titanate refinement investments across component suppliers.
- Advanced Driver Assistance Systems:LiDAR and radar modules for collision avoidance demand ultra-stable capacitance values, creating specification pull from tier-one automotive electronics suppliers.
Market Restraints
- Palladium Price Volatility:Precious metal electrodes in specialty tantalum formulations face input cost swings that compress margins on military-aerospace contracts with fixed pricing terms.
- East Asian Supply Concentration:Over 70% of high-capacitance ceramic production sits in South Korean and Japanese manufacturing clusters, exposing buyers to single-point disruption risks from seismic or geopolitical events.
- Aluminum Electrolytic Substitution:Commodity-grade applications in consumer white goods are migrating to wet aluminum capacitors where volumetric efficiency requirements remain relaxed.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and component assembly are attracting capacitor qualification investments for smartphone and appliance export hubs.
- Silicon Carbide Power Modules:Convergence of wide-bandgap semiconductors with high-temperature capacitors is opening thermal specification gaps that ceramic dielectrics can exploit in traction inverters.
- China Dual Carbon Goals:SAMR energy-efficiency labeling for consumer electronics is creating procurement preference for low-loss capacitor formulations in air conditioning and refrigeration compressors.
Industry Challenges
- Material Science Talent Scarcity:Formulation chemists with deep expertise in perovskite crystal structures and grain boundary engineering command premium compensation, constraining R&D expansion at mid-tier suppliers.
- AEC-Q200 Certification Timelines:Automotive functional safety documentation requires 18-24 month validation cycles that delay revenue recognition for new dielectric platforms.
- Legacy Equipment Integration:Industrial automation retrofits demand through-hole capacitor formats that conflict with surface-mount optimized production lines, forcing dual-format manufacturing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Layer Capacitors Market |
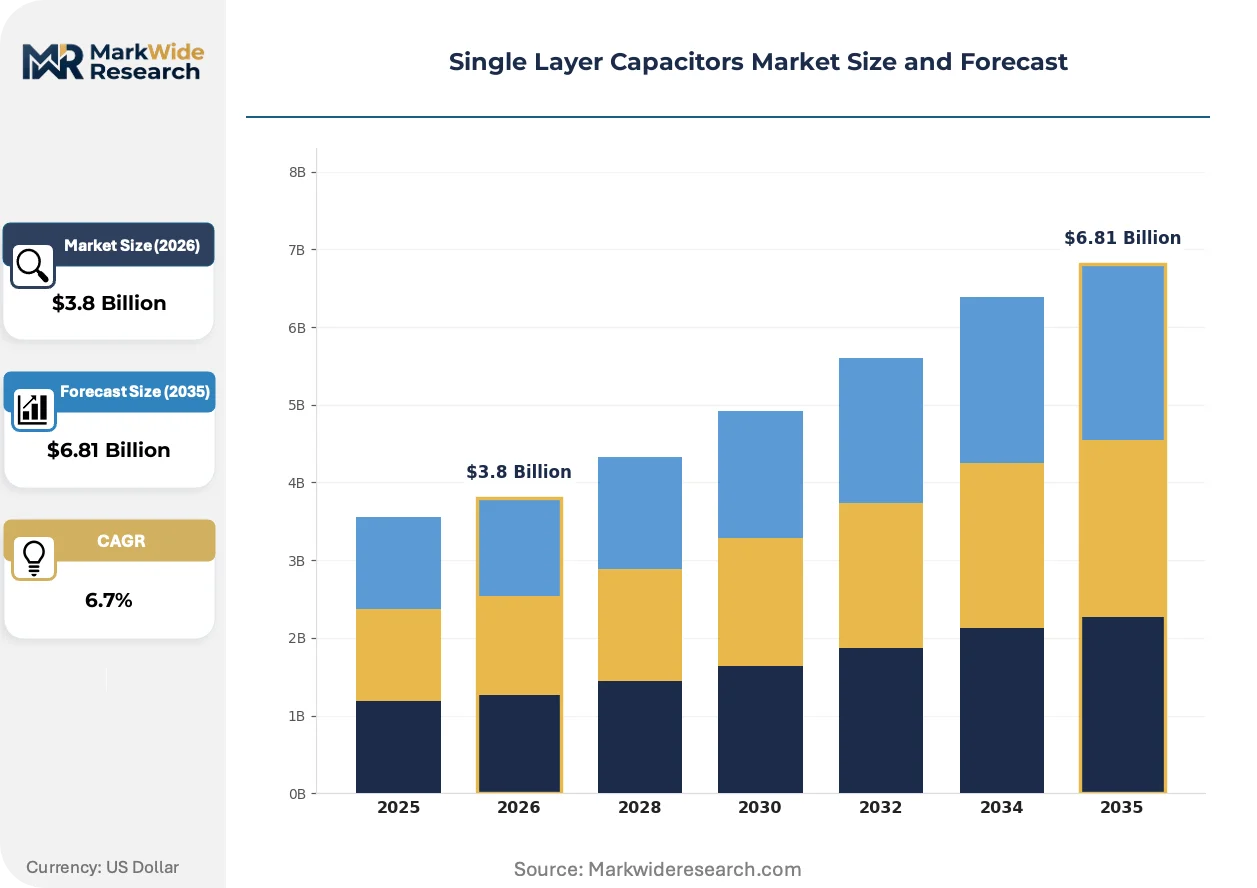
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MLCC, Tantalum, Ceramic, Aluminum Technology: Thin Film, Thick Film, Epitaxial, Plated Form Factor: Surface Mount, Through Hole, Radial, Axial Application: Consumer Electronics, Automotive, Telecommunications, Industrial |
| Companies Covered | Samsung ElectroMechanics, Kemet, Murata Manufacturing, Walsin Technology, Yageo Corporation, Vishay Intertechnology, Taiyo Yuden, Fenghua Advanced Technology, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Layer Capacitors Market Evolving Landscape
Thin-film deposition techniques and dielectric material refinements are compressing form factors while extending voltage-temperature envelopes, reshaping competitive differentiation around process chemistry rather than scale economies alone.
Nanoscale barium titanate powders with controlled grain boundary doping are electrifying high-frequency telecommunications infrastructure. Base station OEMs in South Korea and Japan are adopting these formulations for 5G millimeter-wave backhaul modules. The technology is electrifying margin structures by displacing multilayer alternatives in space-constrained RF front-ends.
China's GB standards for capacitor reliability testing under SAMR enforcement are tightening market access requirements for imported components. Foreign suppliers must maintain dual certification tracks for domestic Chinese production versus export-grade specifications. Industrial equipment and renewable energy inverter segments face the steepest compliance cost escalations as they source for both local installation and re-export markets.
Consolidated procurement through electronic component distributors is fragmenting as automotive tier-ones establish direct qualification relationships with capacitor manufacturers. Digi-Key and Mouser retain consumer electronics volume, but electrified vehicle programs in Germany and the United States are bypassing traditional channels for long-term supply agreements with Murata, Samsung ElectroMechanics, and Taiyo Yuden.
Single Layer Capacitors Market Segmentation
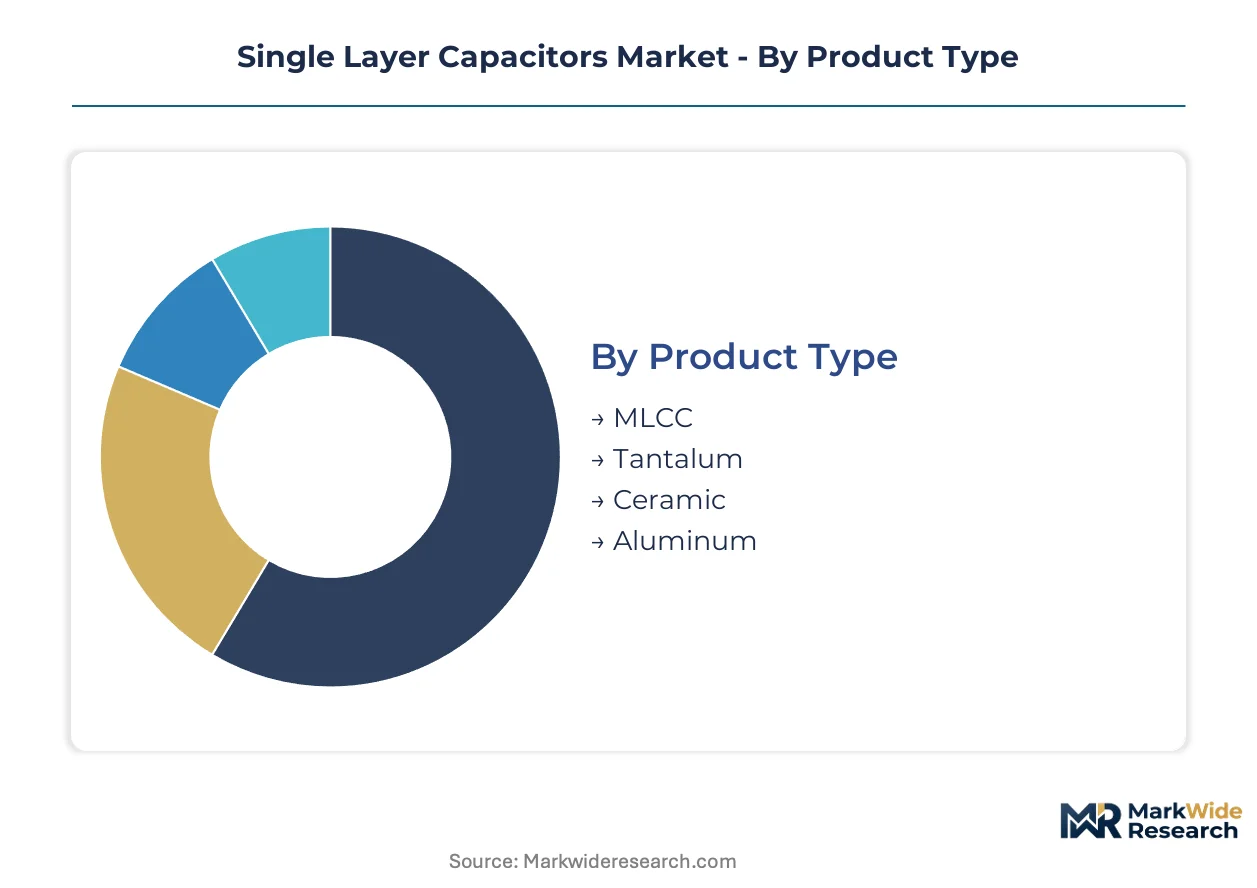
Segmentation in the single layer capacitors market reveals how certification requirements, thermal performance thresholds, and form factor constraints fragment procurement decisions across end-use verticals. Each dimension carries distinct margin structures and supplier qualification barriers.
Product Type:
MLCC and ceramic variants carry AEC-Q200 automotive qualification burdens, while tantalum formulations face MIL-PRF-55365 military-aerospace documentation requirements. Aluminum electrolytic types operate under less stringent industrial reliability standards.
- MLCC:Multilayer ceramic chip capacitors stack alternating dielectric and electrode layers to achieve high volumetric efficiency in compact packages. Samsung Electro-Mechanics and Murata Manufacturing in South Korea and Japan dominate high-capacitance supply for 5G base stations and electric vehicle inverters, where AEC-Q200 Rev. E thermal cycling requirements filter out commodity suppliers.
- Ceramic:Single-layer ceramic constructions using barium titanate or strontium titanate dielectrics serve high-frequency decoupling in RF front-end modules. Taiyo Yuden's thin-film ceramic lines for millimeter-wave telecommunications infrastructure in Japan command premium positioning as base station OEMs qualify alternative sources.
- Tantalum:Manganese dioxide or polymer cathode systems deliver stable capacitance across temperature extremes for aerospace flight control systems.
- Aluminum:Wet electrolytic and solid polymer formats address bulk energy storage in industrial motor drives and renewable energy inverters.
MLCC sits at the top of the volume ranking, with ceramic climbing the fastest as telecommunications infrastructure deployments accelerate.
Technology:
Process chemistry differentiation separates premium pricing tiers, with thin-film deposition commanding R&D recovery premiums over commodity thick-film screening methods.
- Thin Film:Physical vapor deposition creates nanometer-scale dielectric layers with exceptional thickness uniformity for microwave and millimeter-wave circuits. Murata's U2J and C0G formulations for 28GHz and 39GHz 5G backhaul in Japanese and South Korean networks achieve Q-factors exceeding 1000 at 6GHz, where thick-film alternatives exhibit unacceptable dielectric loss.
- Thick Film:Screen-printed dielectric pastes fired at elevated temperatures suit cost-sensitive consumer electronics filtering applications. Chinese domestic suppliers in Guangdong province leverage thick-film economies for white goods and appliance controllers serving export markets, though SAMR GB/T 2693 reliability testing requirements are tightening qualification thresholds.
- Epitaxial:Crystalline dielectric growth on oriented substrates enables precise permittivity control for specialty RF applications.
- Plated:Electrodeposition processes create conformal coatings for irregular substrate geometries in medical implant devices.
Thick Film dominates current production volumes, while Thin Film expands most quickly as 5G millimeter-wave deployments multiply.
Form Factor:
Mounting technology selection traces directly to assembly automation investments and field service accessibility requirements across customer segments.
- Surface Mount:Rectangular chip formats with nickel-barrier terminations enable high-speed pick-and-place assembly in smartphone and tablet production. Samsung Electro-Mechanics' 0201 and 01005 case sizes for wearable electronics in South Korean manufacturing clusters achieve placement rates exceeding 100,000 components per hour, though tombstoning defects in reflow soldering demand precise thermal profile control.
- Through Hole:Radial and axial leaded constructions support manual replacement and extended field service in industrial automation equipment. German machine tool manufacturers specify through-hole aluminum electrolytics for 20-year service life guarantees, where surface-mount thermal cycling fatigue would violate warranty terms.
- Radial:Vertical lead configurations optimize board space in power supply filtering stages.
- Axial:Horizontal lead arrangements suit vintage audio equipment restoration and military equipment form-factor legacy requirements.
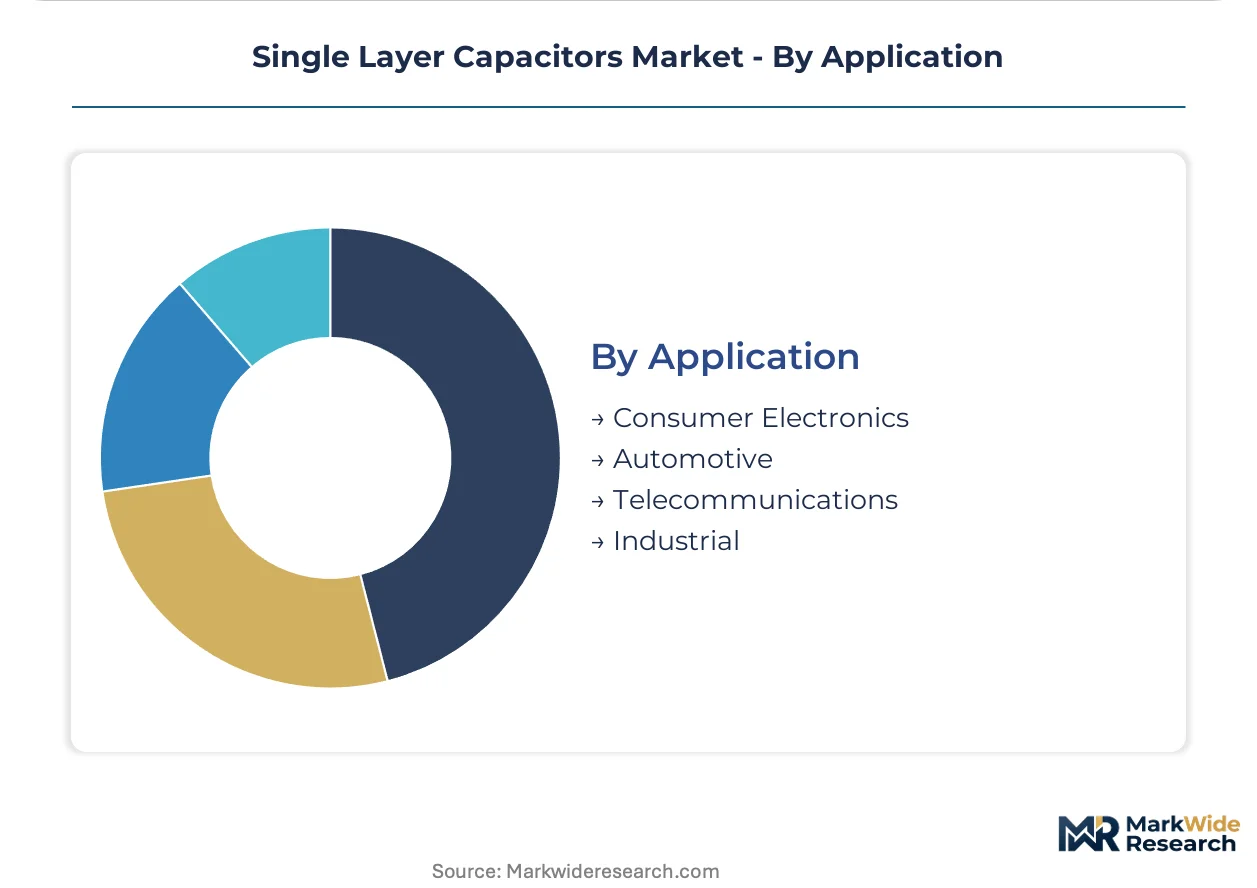
Surface Mount commands absolute volume leadership, with Through Hole retaining stable share in industrial equipment replacement cycles.
Application:
End-use verticals impose divergent qualification documentation, with automotive functional safety requirements creating the steepest supplier barriers.
- Automotive:Battery management systems, onboard chargers, and inverter DC-link applications demand AEC-Q200 Grade 1 (-40°C to +125°C) or Grade 0 (-40°C to +150°C) ceramic formulations. Infineon and STMicroelectronics traction inverter platforms for European electric vehicle programs specify Murata GCM series MLCCs with PPAP Level 3 documentation, where 18-month qualification timelines lock in supplier relationships.
- Telecommunications:Base station RF chains and optical transceivers require ultra-low equivalent series resistance for high-frequency signal integrity. Ericsson and Nokia 5G massive MIMO deployments in Finland and Sweden source Taiyo Yuden's high-Q ceramic chips for 3.5GHz and 28GHz active antenna systems, where insertion loss directly impacts radiated power efficiency.
- Consumer Electronics:Smartphones, laptops, and wearables prioritize volumetric efficiency and cost minimization over extended temperature ratings.
- Industrial:Motor drives, power inverters, and automation controllers emphasize long-term reliability and field serviceability.
Consumer Electronics maintains volume leadership, with Automotive gaining share fastest as electrification penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists with perovskite crystal expertise concentrate in Japanese and South Korean industrial corridors, anchoring high-reliability ceramic development. Their proximity to precision manufacturing infrastructure sustains competitive advantage in automotive qualification cycles.
Japan
Base station OEMs in Tokyo and Osaka drive demand for ultra-low-loss ceramic formulations in 5G millimeter-wave infrastructure. METI energy-efficiency labeling requirements for consumer electronics indirectly shape capacitor procurement standards through downstream OEM specifications. Murata Manufacturing and Taiyo Yuden anchor production clusters in Kyoto and Tokyo prefectures, where thin-film deposition expertise supports telecommunications margin premiums.
South Korea
Samsung Electro-Mechanics and smartphone manufacturers in Suwon and Gyeonggi Province pull volume toward sub-millimeter case sizes for wearable electronics. The MFDS enforces reliability testing protocols that align with automotive AEC-Q200 standards for components entering medical device supply chains. Busan-Ulsan manufacturing corridors host specialized ceramic firing facilities serving export markets.
China
SAMR GB standards for capacitor reliability testing tighten market access for imported components serving industrial equipment and renewable energy inverter segments. SAMR energy-efficiency labeling for air conditioning and refrigeration compressors creates procurement preference for low-loss formulations. Pearl River Delta clusters in Guangdong province concentrate thick-film production for white goods export markets.
Germany
Infineon and STMicroelectronics traction inverter platforms for electric vehicle programs specify AEC-Q200 Grade 1 ceramic formulations with 18-month qualification timelines. ECHA REACH enforcement against lead-bearing dielectrics accelerates nickel electrode adoption across component suppliers. Bavarian and Baden-Württemberg automotive electronics corridors concentrate tier-one supplier engineering centers.
United States
Vishay Intertechnology anchors North American supply chains through specialized production for industrial and military end uses. NHTSA automotive functional safety documentation requirements compress validation cycles for high-reliability formulations. Defense electronics corridors in Arizona and Massachusetts sustain demand for tantalum constructions with MIL-PRF-55365 documentation.
Single Layer Capacitors Market Competitive Landscape
Top-tier vendors anchor high-reliability automotive and telecommunications supply chains, while mid-tier fabricators compete on thick-film economies for consumer white goods. The vendor base stratifies across thin-film technology leaders, ceramic formulation specialists, and diversified passive component conglomerates. Three archetypes dominate: precision deposition specialists, high-volume MLCC manufacturers, and military-aerospace qualification holders. Capacity expansion in East Asian manufacturing clusters and direct qualification relationships with automotive tier-ones represent the dominant competitive moves.
Within the precision deposition tier, Murata Manufacturing and Taiyo Yuden occupy positions exemplifying thin-film technology leadership for high-frequency telecommunications applications. Samsung Electro-Mechanics represents the scale-driven archetype among South Korean fabricators, while Vishay Intertechnology anchors North American supply chain resilience for industrial and military end uses. These three companies collectively illustrate how geographic concentration of formulation expertise shapes competitive differentiation in automotive and telecommunications verticals.
| Leading Market Players |
|---|
| Samsung ElectroMechanics |
| Kemet |
| Murata Manufacturing |
| Walsin Technology |
| Yageo Corporation |
| Vishay Intertechnology |
| Taiyo Yuden |
| Fenghua Advanced Technology |
| Panasonic |
| Others |
Value Network & Pricing Analysis
Palladium electrode costs in specialty tantalum formulations cascade through fixed-price military-aerospace contracts into compressed margin tiers, while nickel-barrier terminations in automotive MLCCs absorb REACH compliance premiums before reaching tier-one OEM procurement desks.
Pricing Analysis
Bundled long-term supply agreements with AEC-Q200 certification documentation command premiums over unbundled spot-market transactions for commodity ceramic grades. Three-tier pricing structure across automotive-qualified, telecommunications-grade, and consumer-economy levels separates Murata's thin-film telecommunications lines from thick-film white goods suppliers in Guangdong. Cost compression in consumer electronics tiers is intensifying because aluminum electrolytic substitution relaxes volumetric efficiency requirements. Appliance OEMs in export manufacturing clusters exhibit highest price sensitivity; German automotive tier-ones with 18-month qualification lock-ins show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle electrified vehicle program demand from Infineon and STMicroelectronics traction inverter platforms, while distributor networks retain consumer electronics volume through Digi-Key and Mouser. Production gravity centers on South Korea, Japan, and China's Pearl River Delta clusters, where Samsung Electro-Mechanics, Murata Manufacturing, and domestic thick-film fabricators anchor capacity. Barium titanate powders, nickel electrode pastes, and precision firing equipment feed from upstream chemical and equipment suppliers. Single-source vulnerability concentrates in high-capacitance ceramic formulations qualified to AEC-Q200 Grade 0 thermal cycling standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH substance restrictions and China's SAMR GB standards tighten material sourcing thresholds faster than formulation innovation cycles can absorb.
For Market Incumbents: To counter palladium price volatility in fixed-price military contracts, anchor margin stability through backward integration into tantalum powder processing and captive electrode deposition capacity. Accelerate barium titanate refinement investments ahead of ECHA enforcement timelines to preempt competitor qualification advantages in nickel electrode systems. For New Entrants and Emerging Players: Electronic component distributors with automotive tier-one relationships offer the fastest qualification pathway for thin-film ceramic lines targeting 5G millimeter-wave infrastructure gaps. India's PLI scheme incentives for semiconductor packaging present the most penetrable geography, with smartphone export hub demand pulling volume toward sub-millimeter case size capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where AEC-Q200 certification timelines stretch 18-24 months and formulation chemist scarcity constrains R&D expansion at mid-tier suppliers. Long-term viability favors precision deposition specialists with telecommunications margin premiums over thick-film commodity fabricators. Watch SAMR enforcement intensity against imported industrial equipment components as the signal indicating qualification cost escalation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Grade 0 Certification Investment | Unlocks traction inverter supply to European electric vehicle programs with thermal cycling requirements. |
| Thin-Film Deposition Capacity Expansion | Captures 5G millimeter-wave backhaul demand from Ericsson and Nokia base station deployments. |
| Backward Integration into Barium Titanate | Insulates margin structure from REACH compliance cost escalations in European supply chains. |
| Direct Qualification with Automotive Tier-Ones | Bypasses distributor fragmentation to secure long-term supply agreements for battery management systems. |
| India PLI Scheme Manufacturing Footprint | Positions for smartphone and appliance export hub demand with domestic qualification advantages. |
Research Methodology
Multiple input streams — capacitor procurement managers at automotive tier-ones, formulation chemists at ceramic manufacturers, and reliability testing directors at SAMR-accredited laboratories — were reconciled against secondary validation from ECHA substance restriction filings, METI energy-efficiency labeling databases, and AEC-Q200 revision documentation. Bottom-up assembly of product-type volumes and top-down cross-check against end-use vertical spending patterns anchored the triangulation framework.
Historical capacity utilization patterns from Japanese and South Korean manufacturing clusters were cross-referenced against panel input from base station OEM procurement leads and industrial inverter engineering directors. Segmentation modeling spanned product type, dielectric technology, form factor mounting method, and end-use vertical qualification tier. CAGRs emerged from iterative reconciliation of shipment volumes against semiconductor content-per-vehicle trajectories and telecommunications infrastructure deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to palladium commodity cycles, seismic disruption risks in East Asian production clusters, and AEC-Q200 revision scope expansions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Bluetooth Adapter Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Structural Electronics Market
Electronic Components
Touch Screen Controllers Market
Electronic Components
Metal Oxide Varistor (MOV) Market
Electronic Components
Switch Diode Market
Electronic Components
Resonators Market
Electronic Components
Global Suction Tube Market
Electronic Components
Amplifier Market
Electronic Components
Printed Circuit Board Market
Electronic Components
2D Electronics Market
Electronic Components
Robotic Flat Cable Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Global Industrial Media Converters Market