
 Data Bus Market | 2026-2036
Data Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Data Bus Market Analysis
Buyer concentration in aerospace and defense procurement is hardening as prime contractors consolidate subsystem sourcing around qualified vendors. TE Connectivity leverages its MIL-DTL-38999 connector pedigree to dominate high-reliability backplane contracts. Amphenol Corporation sustains position through backward integration into cable harness assembly for naval combat systems. Honeywell International Inc. competes on integrated avionics suites where its proprietary data bus modules lock in platform-level design wins.
A data bus is a communication subsystem that transfers data between components inside a computer or between computers, typically operating with defined protocols, impedance-controlled transmission lines, and shielding specifications up to gigabit-per-second speeds for modern implementations. Its primary purpose is to enable deterministic, low-latency information exchange in mission-critical systems where electromagnetic interference tolerance and fault isolation are mandatory. Ethernet Bus segments are capturing the fastest expansion as automotive OEMs and defense primes migrate from legacy copper architectures to switched gigabit networks. Wired technology still anchors the revenue base, though hybrid optical-copper configurations are emerging as the margin-rich tier for applications requiring weight reduction without full fiber conversion.
FAA airworthiness directives and EU REACH substance restrictions are tightening material compliance for cabin and avionics wiring, pushing suppliers toward halogen-free insulations. NHTSA cybersecurity mandates for vehicle networks are forcing data bus architects to embed encryption and intrusion detection at the physical layer. Stakeholders must monitor how ISO 26262 functional safety grades and emerging EU AI Act connectivity requirements reshape qualification thresholds for automotive and industrial bus components.
Market Dynamics
The transition from MIL-STD-1553 to high-speed Ethernet backbones in military avionics is compressing retrofit cycles and forcing subsystem vendors to requalify architectures for deterministic latency under switched gigabit protocols.
Growth Catalysts
- NHTSA cybersecurity mandates:Vehicle network encryption requirements at the physical layer are pulling automotive-grade secure data bus modules into production pipelines ahead of 2026 model years.
- Fiber-optic architectures:German defense primes are specifying optical backplanes for next-generation combat vehicles, creating specification cascades through NATO procurement frameworks.
- EU REACH substance restrictions:Halogen-free insulation mandates are accelerating material qualification programs for cabin and avionics wiring suppliers.
Market Restraints
- Copper price volatility:Shielded twisted-pair cable harnesses remain input-cost exposed, squeezing margin on legacy platform spares.
- Qualified vendor concentration:MIL-DTL-38999 connector certification sits with a narrow tier of US and European suppliers, creating single-source risk for prime contractors.
- Optical transceiver thermal limits:Wide-temperature-range military specifications exceed commercial fiber component ratings, forcing custom packaging.
Strategic Opportunities
- Hybrid optical-copper configurations:Aerospace weight-reduction programs are accepting intermediate architectures that retain copper power delivery while migrating signal paths to fiber.
- ISO 26262 functional safety grades:Automotive ASIL-D certification for data bus components opens qualification pathways into autonomous vehicle platforms.
- EU AI Act connectivity requirements:Edge AI inference modules in industrial automation will require deterministic bus architectures with embedded anomaly detection.
Industry Challenges
- EMC test engineer scarcity:Gigahertz-range shielding effectiveness validation requires specialized anechoic chamber access and interpretive expertise that outpaces training pipelines.
- Legacy 1553 integration:Bridge architectures maintaining backward compatibility with 1 Mbps legacy buses add firmware complexity and latency budget pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Bus Market |
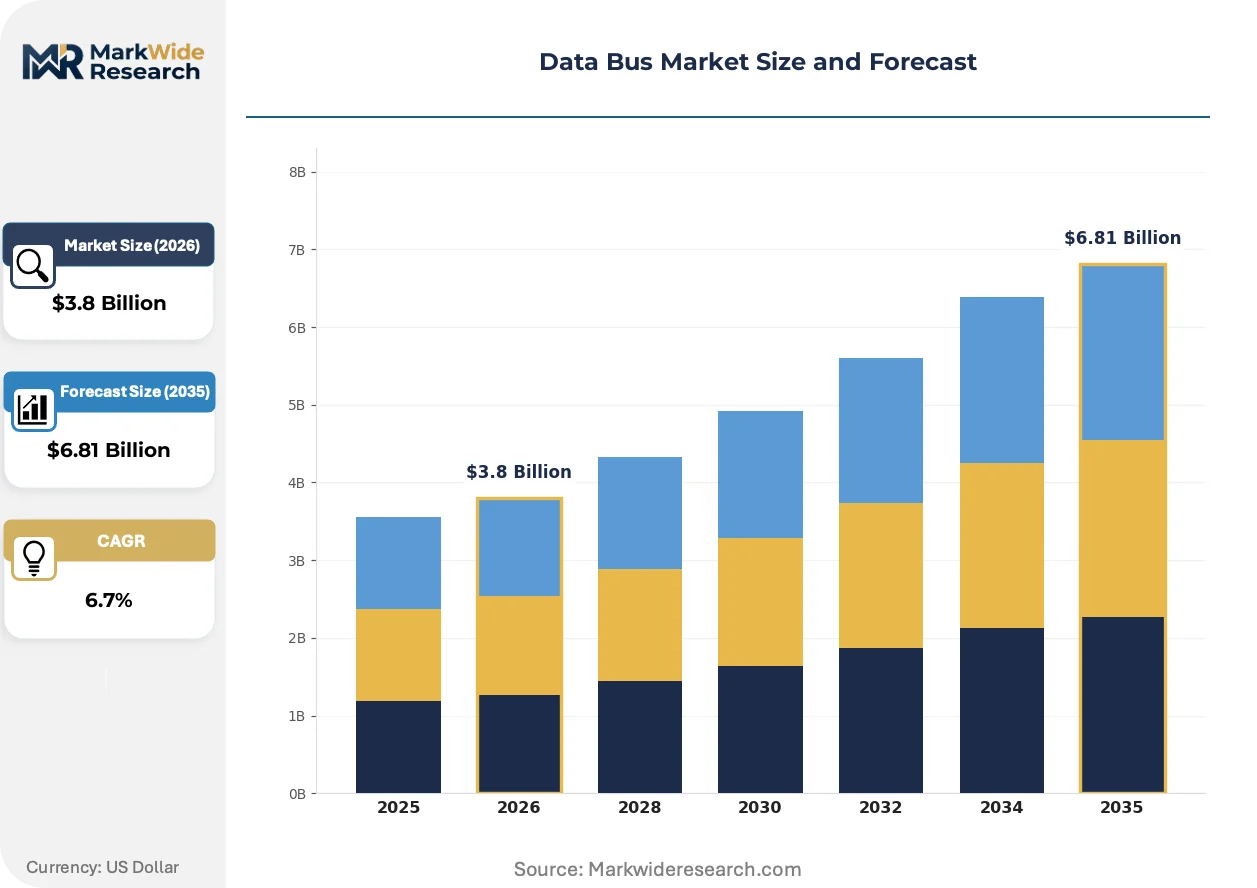
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAN Bus, LIN Bus, FlexRay, Ethernet Bus End User: Automotive, Aerospace, Industrial Automation, Commercial Transportation Technology: Wired, Wireless, Hybrid, Optical Application: Telematics, Vehicle Control, Industrial Monitoring, Smart Grid |
| Companies Covered | TE Connectivity, Amphenol Corporation, Fujikura Ltd., Corning Inc., Honeywell International Inc., Rockwell Collins, Lockheed Martin Corporation, Northrop Grumman Corporation, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Bus Market Emerging Trajectories
Deterministic Ethernet variants are collapsing the traditional separation between avionics control buses and passenger entertainment networks, forcing unified physical-layer architectures that must satisfy divergent certification regimes simultaneously.
Time-Sensitive Networking (TSN) extensions to IEEE 802.1 standards are enabling nanosecond-precision clock synchronization across switched Ethernet fabrics. Automotive OEMs in Germany and Japan are adopting TSN for drive-by-wire systems, displacing FlexRay in new platform designs. This convergence is decentralizing gateway hardware requirements and collapsing tier-one supplier value capture in central module categories.
ECHA enforcement of REACH Annex XVII restrictions on short-chain chlorinated paraffins is eliminating legacy cable jacket formulations from European aerospace supply chains. Manufacturers are qualifying magnesium hydroxide-filled polyolefin compounds that meet smoke toxicity specifications without halogenated flame retardants. German and French airframe integrators are now requiring full material disclosure documentation back to resin suppliers.
Defense procurement agencies are consolidating subsystem awards under platform-level system integrators, compressing the vendor base accessible to component suppliers. Tier-two data bus manufacturers are responding by pursuing direct airworthiness qualification with FAA and EASA rather than relying on prime contractor sponsorship. This channel restructuring is most visible in US Navy and Royal Navy combat system programs, where cable harness suppliers now compete for specification control at the shipyard level.
Data Bus Market Segmentation
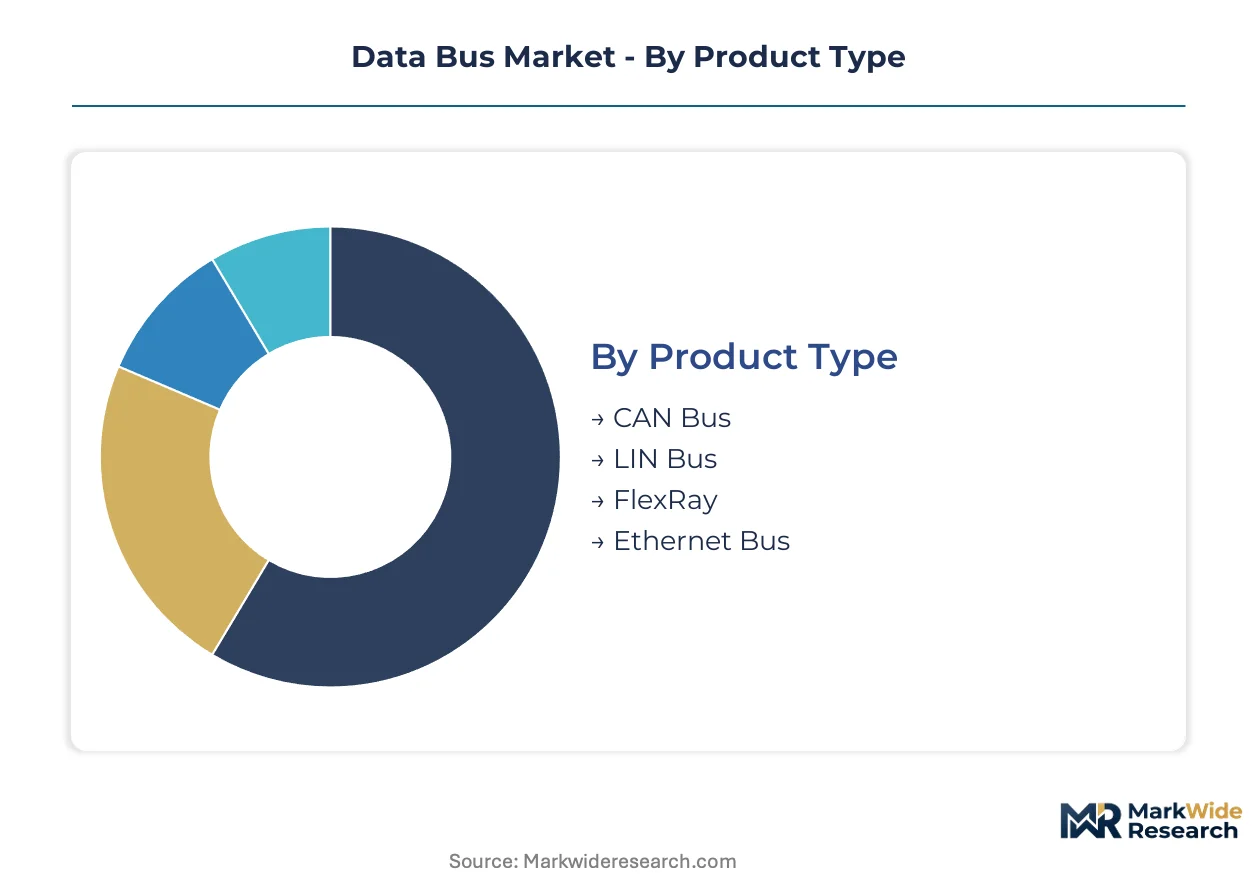
Data bus architectures fragment across protocol generations, physical media, and deterministic requirements that lock customers into multi-year platform commitments. Each segmentation dimension carries distinct qualification barriers and margin structures that reshape competitive positioning.
Product Type:
Capital intensity concentrates in Ethernet Bus and FlexRay segments where gigabit-speed validation and ASIL-D certification demand multimillion-dollar test infrastructure.
- Ethernet Bus:Switched gigabit architectures with Time-Sensitive Networking extensions now dominate automotive drive-by-wire and military avionics retrofits. German OEMs and NATO defense primes are specifying IEEE 802.1 TSN variants for deterministic latency under 50 microseconds.
- FlexRay:Dual-channel 10 Mbps deterministic protocol retains position in chassis control modules where fault-tolerant clock synchronization is mandatory. BMW and Daimler Truck continue sourcing FlexRay for brake-by-wire systems despite Ethernet displacement pressure.
- CAN Bus:Cost-optimized 1 Mbps controller area networks anchor body electronics and powertrain sensors across mass-market vehicles.
- LIN Bus:Single-wire 20 kbps protocol serves door modules, seat controls, and climate subsystems where bandwidth requirements are minimal.
Ethernet Bus absorbs the bulk of installed capacity in defense and premium automotive; FlexRay is expanding most quickly in heavy commercial vehicle safety systems.
End User:
Application maturity separates segments where data buses are commodity inputs from those requiring platform-specific architectural design.
- Automotive:Zonal E/E architectures are collapsing 70-plus ECU networks into domain controllers, concentrating high-speed bus procurement at tier-one module suppliers. NHTSA cybersecurity mandates are pulling encrypted physical-layer modules into 2026 model year pipelines.
- Aerospace:FAA and EASA airworthiness directives govern shielding effectiveness, smoke toxicity, and fault isolation in cabin and avionics wiring. The transition from MIL-STD-1553 to Ethernet backbones is compressing retrofit cycles for military platforms.
- Industrial Automation:Profinet and EtherCAT implementations over industrial Ethernet are displacing fieldbus networks in German and Japanese factory automation.
- Commercial Transportation:Fleet telematics and predictive maintenance systems are driving CAN-FD and Ethernet adoption in heavy trucks and rail rolling stock.
Automotive commands the deepest supplier qualification investment; Aerospace is climbing the fastest on defense modernization cycles.
Technology:
Physical layer selection determines weight, electromagnetic resilience, and thermal envelope constraints that cascade through platform engineering.
- Wired:Shielded twisted-pair and coaxial copper harnesses retain cost advantage in high-volume automotive and industrial applications. Copper price volatility and qualified vendor concentration create single-source risk for prime contractors.
- Optical:Fiber-optic backplanes specified by Rheinmetall and Airbus Defence for next-generation combat vehicles eliminate electromagnetic interference susceptibility. Wide-temperature-range military specifications exceed commercial transceiver ratings, forcing custom packaging.
- Hybrid:Optical-copper configurations retain copper power delivery while migrating signal paths to fiber, serving aerospace weight-reduction programs.
- Wireless:802.11p and cellular V2X modules are penetrating telematics and infotainment domains where deterministic latency is less critical.
Wired technology anchors revenue volume; Optical is gaining share fastest in defense procurement frameworks.
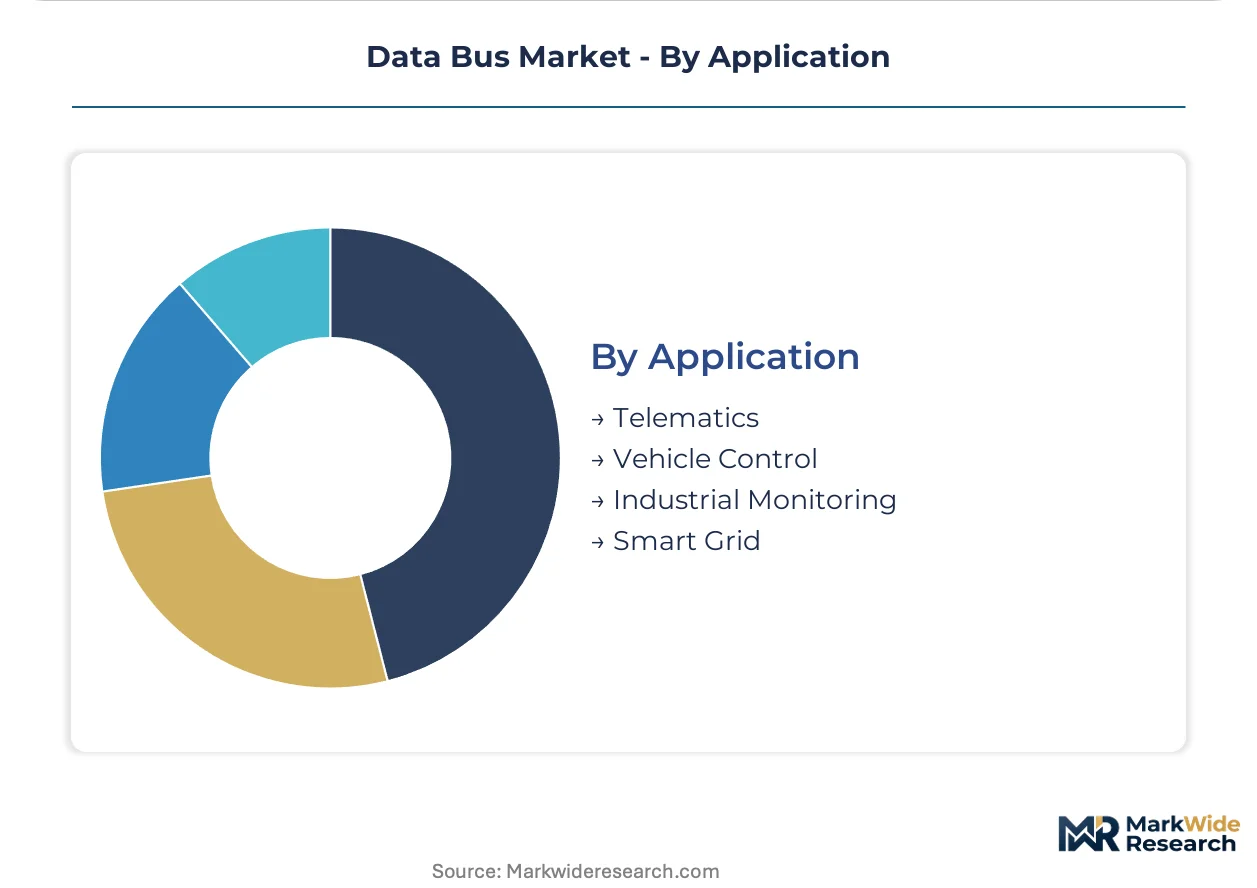
Application:
Functional safety grades and real-time determinism requirements partition segments by architectural complexity and certification burden.
- Vehicle Control:Brake-by-wire, steer-by-wire, and propulsion management demand ASIL-D functional safety and sub-millisecond latency. TSN-enabled Ethernet is displacing FlexRay in new German and Japanese platform designs.
- Telematics:Over-the-air update pipelines and connected infotainment require high-bandwidth buses with cybersecurity hardware roots of trust. NHTSA mandates are accelerating secure module deployment.
- Industrial Monitoring:Edge AI inference modules in smart factories require deterministic bus architectures with embedded anomaly detection under EU AI Act connectivity requirements.
- Smart Grid:IEC 61850 substation automation protocols operate over Ethernet and fiber for utility-scale power distribution monitoring.
Vehicle Control absorbs the bulk of safety-critical engineering resources; Industrial Monitoring is expanding most quickly on edge AI integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement agencies in Germany and the United States are driving embedded data bus deployments in next-generation combat vehicles and military avionics retrofits. These two markets anchor demand concentration as NATO modernization programs accelerate specification cascades through allied procurement frameworks.
United States
The FAA governs shielding effectiveness and fault isolation standards for cabin and avionics wiring through airworthiness directives that tighten material compliance. NHTSA cybersecurity mandates for vehicle networks are forcing encrypted physical-layer modules into 2026 model year production pipelines. Defense primes in the Washington-Baltimore corridor are consolidating subsystem awards under platform-level system integrators, compressing vendor access for component suppliers.
Germany
Rheinmetall and Airbus Defence are specifying fiber-optic backplanes for land and air platform modernization, creating specification cascades through NATO procurement frameworks. ECHA enforcement of REACH Annex XVII restrictions on short-chain chlorinated paraffins is eliminating legacy cable jacket formulations from aerospace supply chains. Industrial automation clusters in Bavaria and Baden-Württemberg are adopting Profinet and EtherCAT over industrial Ethernet, displacing fieldbus networks in factory automation.
China
MIIT standards for gigabit automotive Ethernet are accelerating domestic OEM migration from legacy CAN architectures to switched backbone networks. GB standards for electromagnetic compatibility are tightening validation requirements for shielded cable harnesses in electric vehicle platforms. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou are concentrating capacity for high-speed connector and cable assembly production.
Japan
METI industrial policy is promoting Time-Sensitive Networking adoption for drive-by-wire systems, displacing FlexRay in new platform designs from Toyota and Honda. JIS standards for wide-temperature-range components exceed commercial fiber transceiver ratings, forcing custom packaging for defense applications. Automotive engineering centers in Nagoya and Tokyo are collapsing 70-plus ECU networks into domain controllers, concentrating high-speed bus procurement at tier-one module suppliers.
United Kingdom
The UK Ministry of Defence is aligning combat vehicle procurement with NATO Ethernet backbone specifications, accelerating retrofit cycles for legacy 1553 architectures. EASA-equivalent military airworthiness requirements govern smoke toxicity and fault isolation in Royal Navy combat system programs. Bristol and Portsmouth shipyards are now awarding cable harness contracts directly to qualified suppliers rather than routing through prime contractor sponsorship.
Data Bus Market Vendor Landscape
US producers anchor the high-reliability defense tier; European specialists hold position in automotive and industrial automation segments. The vendor base concentrates around qualified suppliers of MIL-DTL-38999 connectors and ASIL-D certified modules, with certification barriers creating single-source risk for prime contractors. Three archetypes dominate: integrated avionics suite providers, connector and cable harness assemblers, and fiber-optic subsystem specialists. Competitive moves center on backward integration into cable harness assembly and direct airworthiness qualification with FAA and EASA rather than prime contractor sponsorship.
Among US-based defense contractors, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the platform-level system integrator archetype that compresses vendor access for component suppliers. TE Connectivity represents the connector pedigree tier that dominates high-reliability backplane contracts through MIL-DTL-38999 qualification. These three companies occupy positions that illustrate how certification concentration and procurement consolidation are reshaping competitive access in military and aerospace segments.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Fujikura Ltd. |
| Corning Inc. |
| Honeywell International Inc. |
| Rockwell Collins |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Migration from MIL-STD-1553 to TSN-enabled Ethernet backbones is simultaneously compressing qualification timelines and concentrating procurement leverage among platform-level system integrators. This protocol transition forces subsystem vendors to absorb multimillion-dollar requalification costs while defense primes consolidate awards under fewer qualified suppliers.
Pricing Analysis
Volume-mass-market automotive segments trade on per-unit transactional pricing with thin margins, while aerospace and defense tiers command project-based premiums tied to MIL-DTL-38999 certification and airworthiness qualification. Price differentiation rests on ASIL-D functional safety grades and REACH-compliant material disclosure depth. Cost compression in copper-intensive harnesses is intensifying because of raw material volatility and qualified vendor scarcity. Tier-one automotive module suppliers exhibit highest price sensitivity; NATO defense procurement agencies show lowest sensitivity due to mission-critical reliability mandates.
Supply Chain Analysis
Single-source vulnerability sits with US and German suppliers holding MIL-DTL-38999 connector certification and FAA-EASA airworthiness pedigree. Manufacturing concentration centers on the United States, Germany, and China, with Yangtze River Delta hubs dominating high-speed cable assembly capacity. Raw material dependencies encompass copper rod for shielded twisted-pair, optical fiber preform, and halogen-free polyolefin compounds. Tariff exposure on Chinese-sourced connector components threatens margin stability for European automotive tier-ones. Distribution runs through prime contractor sponsorship channels in defense, though direct shipyard and airframe integrator contracting is emerging in naval and aerospace programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over cable harness assembly and direct regulatory qualification—rather than prime contractor dependency—determines long-term margin capture.
For Market Incumbents: Deepen backward integration into REACH-compliant cable compound formulation and captive fiber-optic transceiver packaging to offset single-source vulnerability in halogen-free insulation supply. Lock in platform-level design wins through integrated avionics suite bundling before TSN-enabled Ethernet fully commoditizes backplane procurement. Threat: Prime contractor consolidation compressing vendor access in US Navy and Royal Navy programs. For New Entrants and Emerging Players: Tier-two shipyards and regional airframe integrators in the United Kingdom and Japan represent the most penetrable channel partners for bypassing prime contractor sponsorship barriers. Target direct FAA-EASA qualification pathways for MIL-DTL-38999 derivative connectors rather than competing through established defense supply chains. White-space opportunity: Hybrid optical-copper configurations for aerospace weight-reduction programs lacking full fiber conversion budgets. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-level system integrators seeking captive data bus capability for avionics suite bundling. Long-term viability favors specialists with dual-use automotive-defense certification and in-house EMC test infrastructure. Acquisition target archetype: Mid-cap fiber-optic subsystem vendors with custom wide-temperature-range packaging expertise. Signal to watch: NATO procurement framework adoption of German-specified optical backplane standards cascading through allied defense programs.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Airworthiness Qualification | Bypasses prime contractor sponsorship dependency in US Navy and Royal Navy combat system programs. |
| Backward Integration into Cable Harness Assembly | Captures margin from shielded twisted-pair and fiber-optic backplane production for NATO platforms. |
| ASIL-D Certification Investment | Opens automotive drive-by-wire procurement from German and Japanese OEMs displacing FlexRay. |
| REACH-Compliant Material Qualification | Meets ECHA Annex XVII enforcement eliminating legacy halogenated cable jackets from aerospace supply chains. |
| TSN-Enabled Ethernet Module Development | Addresses deterministic latency requirements under IEEE 802.1 standards for military avionics retrofits. |
Methodological Framework
SEC 10-K filings, ECHA REACH registration databases, and NATO procurement announcement records formed the secondary backbone for supplier capability mapping and regulatory timeline validation. Primary interviews with defense procurement officers, Tier 1 automotive module supplier executives, EMC test engineering directors, and cable harness procurement leads at airframe integrators informed qualification barrier and pricing structure assessments. Bottom-up and top-down triangulation cross-validated segment sizing against production volume disclosures and platform-level retrofit cycle announcements.
Bottom-up modeling aggregated individual program awards and platform retrofit schedules across military avionics and automotive drive-by-wire deployments, while top-down analysis tracked aggregate defense modernization budgets and zonal E/E architecture transition timelines. Segmentation dimensions encompassed protocol generation, physical media technology, end-use application, and deterministic safety grade. CAGRs were derived from installed base replacement curves and specification cascade patterns through NATO procurement frameworks. Industry-specific forecast inputs included NHTSA cybersecurity mandate compliance deadlines and ECHA enforcement trajectories for short-chain chlorinated paraffin restrictions.
Caveats apply where copper price volatility, optical transceiver thermal qualification delays, or EMC test engineer scarcity could materially shift the outlook for platform deployment schedules. Forecasts embed assumptions regarding NATO ally adoption of German-specified fiber-optic architectures and automotive OEM migration timelines from FlexRay to TSN-enabled Ethernet. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Primary Charge Roller Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Europe Water Cooled Capacitors Market
Electronic Components
Metal Oxide Varistor (MOV) Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Global Capacitor Market
Electronic Components
Chip Shield Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Surface Mountable Laser Direct Structuring Antenna (LDS) Market
Electronic Components
USB Wall Charger Market
Electronic Components
Audio Transistors Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
Global Active Electronic Components Market
Electronic Components
Intel Motherboards Market
Electronic Components
Touch Screen Controllers Market