
 Low-Dropout (LDO) Regulator Market | 2026-2036
Low-Dropout (LDO) Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Dropout (LDO) Regulator Market Foresight
Distributor consolidation across Asia-Pacific is rewriting how LDO regulators reach contract manufacturers. Texas Instruments Incorporated leverages its broad analog portfolio to sustain design-win relationships with top-tier OEMs. Infineon Technologies AG anchors automotive-qualified LDO supply through its Munich and Villach fabrication networks. Onsemi competes aggressively in the industrial segment with extended-temperature-range devices.
A low-dropout regulator maintains output voltage regulation even when the input-to-output differential falls below one volt, typically requiring quiescent currents under one hundred microamperes for portable applications. The device employs a pass transistor operating in the linear region to suppress ripple and deliver clean DC power to noise-sensitive loads. Ultra-low quiescent current variants lead the product type landscape as battery-powered IoT endpoints multiply. Fast response technology commands premium positioning in telecommunications infrastructure where load transients exceed one ampere per microsecond. Fixed voltage segments occupy mature volume tiers in consumer electronics, while adjustable voltage architectures capture margin pools in industrial automation.
The EU Green Deal and REACH chemical restrictions shape material selection and efficiency thresholds for LDOs sold into European automotive and industrial channels. EPA energy conservation standards in the United States push consumer electronics OEMs toward sub-microampere standby solutions. China's GB standards and dual carbon goals from MEE enforce domestic efficiency benchmarks that filter into export supply chains. Stakeholders must monitor how automotive functional safety certification timelines interact with foundry allocation cycles to secure qualified capacity.
Market Dynamics
Automotive electrification is compressing LDO qualification cycles as Tier-1 suppliers race to meet EU Green Deal power-consumption mandates for battery management systems.
Growth Catalysts
- EU Green Deal battery efficiency mandates:European automotive OEMs must reduce standby power draw in electric vehicle subsystems, forcing redesigns around sub-microampere LDO variants.
- China's dual carbon goals:MEE enforcement of GB efficiency standards is filtering into export supply chains, compelling contract manufacturers to source certified low-quiescent-current regulators.
- Telecommunications load transient requirements:Base station upgrades to 5G-Advanced architectures demand fast-response LDOs capable of handling current slew rates exceeding one ampere per microsecond.
Market Restraints
- Foundry allocation bottlenecks:Automotive-qualified BCD process capacity concentrates in Munich and Villach fabrication networks, creating 40-week lead times for AEC-Q100 certified devices.
- Silicon carbide driver substitution:Wide-bandgap power stages in high-voltage EV powertrains are displacing traditional LDOs in DC-DC auxiliary rails above 48 volts.
- REACH chemical compliance costs:ECHA restrictions on leadframe plating materials force expensive qualification reruns for industrial-grade fixed-voltage portfolios.
Strategic Opportunities
- India's PLI scheme for electronics:Contract manufacturing incentives under the Production Linked Incentive program are drawing LDO packaging and test operations to Gujarat and Tamil Nadu clusters.
- Medical implant convergence:Neurostimulator and pacemaker OEMs are merging ultra-low quiescent current LDOs with energy harvesting subsystems, creating premium pricing tiers.
- Industrial IoT battery-less endpoints:RF energy harvesting and thermoelectric generators require nanopower regulators operating below 500 nanoamperes, a specification band with limited qualified suppliers.
Industry Challenges
- AEC-Q100 Grade 0 certification timelines:Full automotive qualification cycles spanning temperature characterization, ESD testing, and production part approval processes extend 18-24 months, misaligning with 12-month vehicle platform development sprints.
- Legacy 5-volt system integration:Industrial automation retrofits require voltage translators and level-shifting LDOs to bridge 3.3-volt sensor rails with 24-volt PLC backplanes, adding BOM complexity and failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Dropout (LDO) Regulator Market |
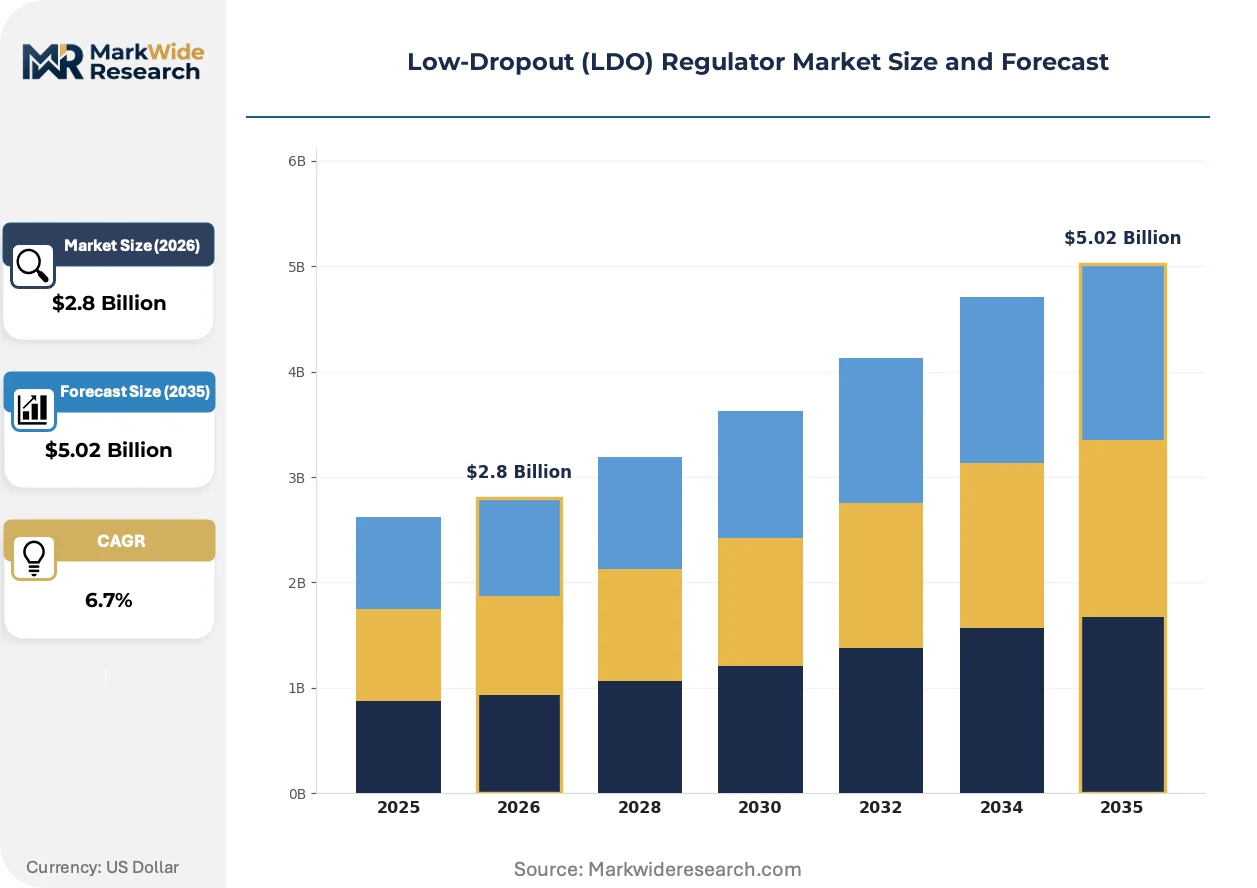
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Voltage, Adjustable Voltage, Ultra-Low Quiescent Current, High Voltage End User: Consumer Electronics, Automotive Electronics, Industrial Equipment, Telecommunications Technology: Low Noise, High Efficiency, Fast Response, Low Power Application: Power Management, Signal Processing, Communication Systems, Battery Charging |
| Companies Covered | Infineon Technologies AG, Onsemi, Texas Instruments Incorporated, Renesas Electronics Corporation, Microchip Technology Inc., Analog Devices, Inc., ROHM Semiconductor, NXP Semiconductors, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Dropout (LDO) Regulator Market Shifts & Advancements
Digital load-line control is displacing analog compensation networks in high-current LDOs, enabling real-time impedance matching through firmware-defined feedback loops rather than fixed external capacitors.
Capacitor-free LDO architectures are virtualizing the traditional output stage by embedding active ripple suppression circuits within the pass transistor bias network. Wearable device OEMs in South Korea and Japan are adopting these topologies to eliminate bulky ceramic capacitors from fitness tracker and hearing aid form factors. This integration is virtualizing the discrete component supply chain for sub-50 milliampere rails, collapsing the traditional two-chip regulator-plus-capacitor BOM into single-die solutions.
EPA energy conservation standards for external power supplies are tightening no-load power limits below 100 milliwatts, forcing consumer electronics brands to redesign USB adapters around sub-10 microampere quiescent current LDOs. The industrial consequence is a specification cascade into wall-mount and desktop power supply reference designs. White-box charger manufacturers in Shenzhen are responding by qualifying domestic LDO suppliers with competitive nanopower portfolios, displacing incumbent analog vendors in cost-sensitive tiers.
Direct procurement from foundries is fragmenting the traditional distributor-led channel for high-volume IoT deployments. Original equipment manufacturers in Germany and Taiwan are negotiating wafer-level agreements with BCD process specialists, bypassing catalog distributors for multi-million-unit wearable and sensor contracts. This disintermediation is most visible in TWS earbud supply chains, where acoustic component suppliers now source regulated die directly from foundry partners to protect margin on sub-dollar bill-of-material targets.
Low-Dropout (LDO) Regulator Market Segmentation
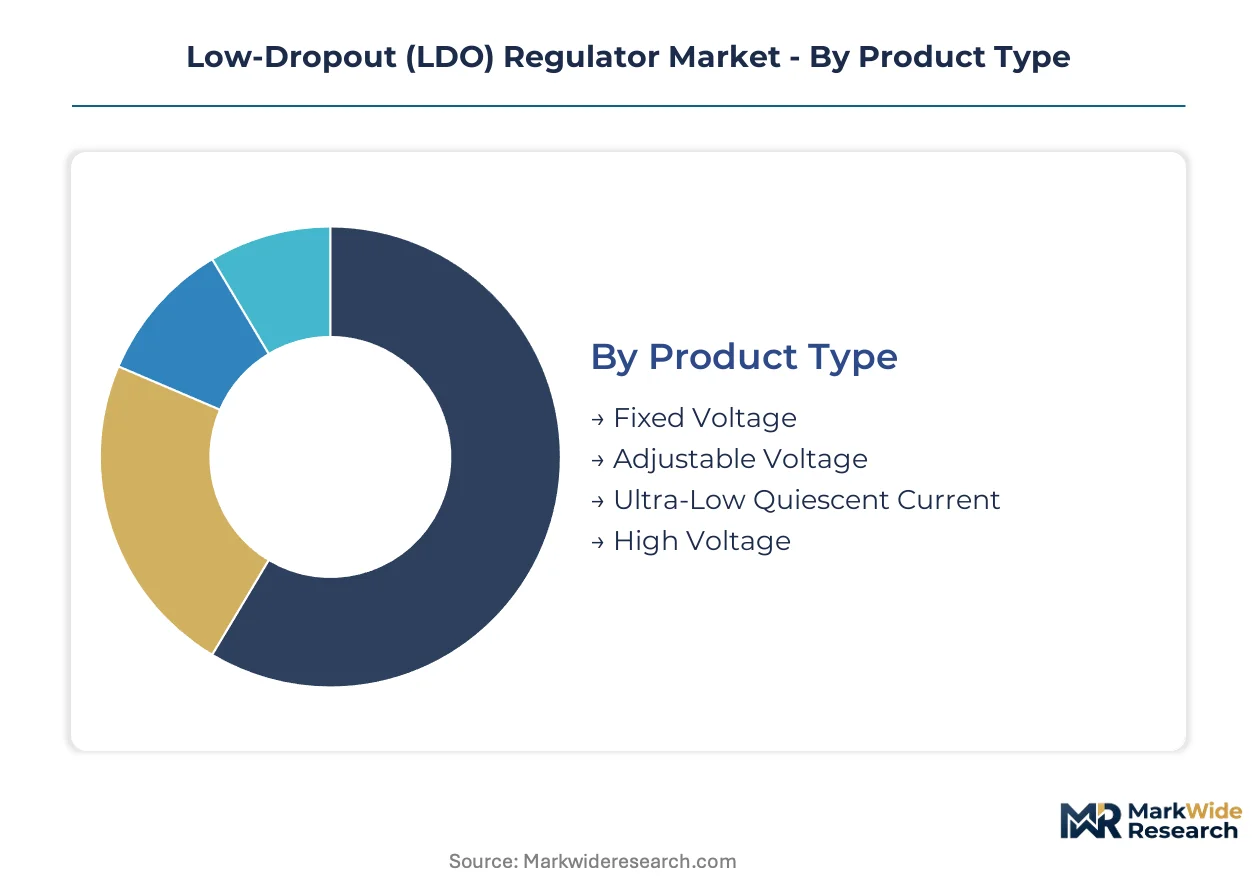
LDO regulator segmentation reveals how technical specifications map to divergent margin structures and qualification burdens across end-use verticals. Product architecture choices directly determine foundry process requirements, while application context dictates whether automotive-grade certification or consumer-grade cost optimization takes priority.
Product Type:
After-sales service intensity escalates dramatically with product complexity, as ultra-low quiescent current variants demand specialized failure analysis capabilities that fixed-voltage portfolios rarely require.
- Ultra-Low Quiescent Current:Sub-microampere bias current specifications enable multi-year battery life in IoT endpoints. Demand concentrates in Germany where Tier-1 automotive suppliers qualify these devices for electric vehicle subsystems under EU Green Deal efficiency mandates.
- Fixed Voltage:Predetermined output rails eliminate external resistor networks and reduce BOM complexity. Consumer electronics OEMs in Shenzhen source these in highest volumes for USB adapters and wearables, though margin compression limits supplier differentiation.
- Adjustable Voltage:External feedback networks permit programmable output ranges across industrial automation retrofits. These bridge legacy 5-volt sensor rails with modern 3.3-volt microcontroller domains.
- High Voltage:Extended input range capabilities serve 48-volt automotive auxiliary rails and industrial PLC backplanes before wide-bandgap displacement.
By volume, Fixed Voltage leads. By growth pace, Ultra-Low Quiescent Current is expanding most quickly.
End User:
Cost tier stratification separates automotive-qualified supply from commercial-grade catalog distribution, with certification overhead creating effective price floors that industrial customers reluctantly absorb.
- Automotive Electronics:AEC-Q100 Grade 0 qualification spans temperature characterization, ESD testing, and production part approval processes. Munich and Villach fabrication networks concentrate supply for powertrain control modules.
- Consumer Electronics:Sub-10 microampere quiescent current requirements dominate USB adapter redesigns under EPA energy conservation standards. White-box charger manufacturers in Shenzhen drive cost-sensitive procurement.
- Industrial Equipment:Extended temperature range specifications and 24-volt PLC compatibility define demand. REACH chemical restrictions on leadframe plating materials force expensive qualification reruns.
- Telecommunications:5G-Advanced base station architectures require fast-response devices handling current slew rates exceeding one ampere per microsecond.
Automotive Electronics commands the steepest expansion trajectory as electrification compresses qualification cycles.
Technology:
Application context determines whether noise suppression, thermal efficiency, transient response, or standby power dominates specification priorities.
- Fast Response:Digital load-line control enables real-time impedance matching through firmware-defined feedback loops. Telecommunications infrastructure premiums reward sub-microsecond settling times.
- Low Noise:Ripple suppression below 10 microvolts RMS serves precision analog-to-digital conversion in medical imaging and test equipment.
- High Efficiency:Minimized dropout voltage reduces power dissipation in thermally constrained wearable form factors.
- Low Power:Nanopower operation below 500 nanoamperes supports RF energy harvesting and thermoelectric generator interfaces in battery-less industrial IoT endpoints.
Fast Response claims the highest pricing premiums. Low Power is gaining share fastest as energy harvesting architectures proliferate.
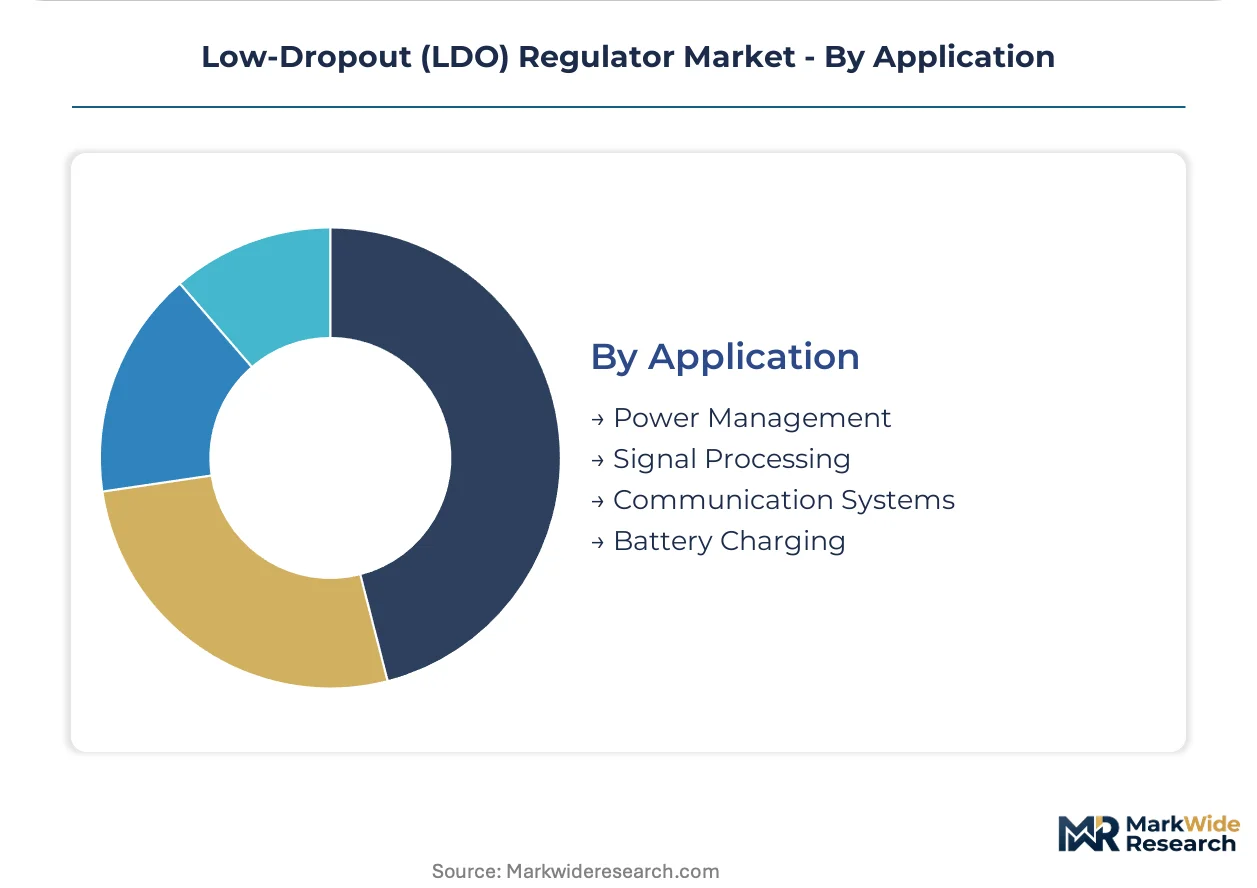
Application:
Customer type fragmentation separates high-volume direct procurement from distributor-mediated fulfillment, with power management dominating unit economics.
- Power Management:Core voltage regulation for processors, sensors, and communication subsystems. Capacitor-free architectures eliminate external ceramic components in South Korean and Japanese wearable designs.
- Battery Charging:Linear charging topologies for single-cell lithium-ion packs in TWS earbuds and fitness trackers. Wafer-level agreements bypass traditional distributors.
- Signal Processing:Clean DC rails for analog front-ends in audio codecs and precision instrumentation.
- Communication Systems:Supply isolation for RF transceivers and baseband processors in 5G subscriber equipment.
Power Management leads by unit volume. Battery Charging shows the steepest growth curve as hearable shipments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Villach-Munich rail corridor and Danube container terminals underwrite Central Europe's dominance in automotive-qualified LDO supply chains. Asian manufacturing clusters leverage Shenzhen port throughput and Kaohsiung harbor capacity to move packaged die into global electronics supply chains. North American demand flows through Pacific Northwest grid interconnections that power semiconductor fabrication in Oregon and Arizona.
Germany
Tier-1 automotive suppliers in Munich and Stuttgart are qualifying next-generation LDOs for powertrain control modules under EU Green Deal battery efficiency mandates. ECHA REACH restrictions on leadframe plating materials force expensive qualification reruns for industrial-grade portfolios. The Villach fabrication network anchors supply for AEC-Q100 certified devices serving electric vehicle subsystems.
China
White-box charger manufacturers in Shenzhen drive cost-sensitive procurement of sub-10 microampere quiescent current LDOs for USB adapter redesigns. MEE enforcement of GB efficiency standards and dual carbon goals filter into export supply chains. The Yangtze River Delta concentration of contract manufacturers sources certified low-quiescent-current regulators for consumer electronics exports.
United States
EPA energy conservation standards for external power supplies tighten no-load power limits below 100 milliwatts, forcing consumer electronics brands toward nanopower LDO solutions. The Pacific Northwest grid infrastructure supports semiconductor fabrication clusters in Oregon. Arizona fabrication investments are expanding BCD process capacity for automotive-qualified devices.
South Korea
Wearable device OEMs in Seoul are adopting capacitor-free LDO architectures to eliminate bulky ceramic components from fitness tracker and hearing aid form factors. METI-aligned efficiency standards through bilateral agreements shape component selection for export-oriented production. The Seoul Capital Area concentration of acoustic component suppliers now sources regulated die directly from foundry partners for TWS earbud supply chains.
Japan
Medical implant convergence around neurostimulator and pacemaker applications is merging ultra-low quiescent current LDOs with energy harvesting subsystems. JIS standards and PMDA quality frameworks enforce rigorous qualification protocols for implantable device power management. The Kansai region's precision manufacturing base supports premium pricing tiers for nanopower regulators operating below 500 nanoamperes.
Low-Dropout (LDO) Regulator Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying qualified die to module assemblers. The vendor base stratifies across three tiers: broad analog portfolio holders sustaining design-win relationships, automotive-qualified specialists anchoring AEC-Q100 supply, and industrial-focused competitors with extended-temperature-range devices. Dominant competitive moves include foundry-level wafer agreements that bypass traditional distribution channels and strategic partnerships between acoustic component suppliers and BCD process specialists.
Among Munich and Villach-anchored fabricators, Infineon Technologies AG occupies a position exemplifying automotive-qualified supply chain concentration. Texas Instruments Incorporated represents the broad analog portfolio archetype sustaining OEM design-win relationships across multiple end-use verticals. Onsemi sits within the industrial-specialist tier, competing with extended-temperature-range devices for automation and powertrain applications.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Onsemi |
| Texas Instruments Incorporated |
| Renesas Electronics Corporation |
| Microchip Technology Inc. |
| Analog Devices, Inc. |
| ROHM Semiconductor |
| NXP Semiconductors |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Undercapacity in automotive-qualified BCD process nodes tightens supplier pricing power while compressing lead times for industrial-grade portfolios. Tier-1 automotive OEMs absorb premium positioning for AEC-Q100 certified devices as foundry allocation cycles stretch qualification timelines against vehicle platform sprints.
Pricing Analysis
Volume-discount tiering structures separate AEC-Q100 Grade 0 automotive certifications from commercial-grade catalog distribution, with certification overhead creating effective price floors that industrial customers reluctantly accept. Price differentiation rests on qualification grade and volume scale, with white-box charger manufacturers in Shenzhen driving cost compression in consumer electronics tiers. Pricing pressure intensifies in fixed-voltage portfolios as domestic Chinese LDO suppliers displace incumbent analog vendors. Automotive electronics buyers exhibit least price sensitivity due to functional safety mandates, while USB adapter OEMs demonstrate highest elasticity.
Supply Chain Analysis
Silicon wafer feedstock draws from Germany, Austria, and Taiwan fabrication networks, with Munich and Villach concentrating automotive-qualified capacity. Raw material dependencies center on 200mm and 300mm silicon substrates, specialty leadframe alloys, and epoxy molding compounds. Single-source vulnerability concentrates in BCD process specialists serving AEC-Q100 Grade 0 requirements. Distribution runs through direct wafer-level agreements that bypass traditional catalog channels for high-volume IoT deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LDO regulator market tracks a cyclical recovery pattern as automotive electrification compresses qualification cycles and restocks channel inventory ahead of EU Green Deal implementation deadlines.
For Market Incumbents: Harden AEC-Q100 Grade 0 certification pipelines against silicon carbide driver substitution in 48-volt auxiliary rails. Expand captive BCD process capacity in Villach and Munich fabrication networks to secure qualified allocation against foundry bottlenecks. Deepen backward integration into specialty leadframe plating materials to preempt REACH compliance cost escalations. For New Entrants and Emerging Players: Pursue capacitor-free LDO architectures for South Korean and Japanese wearable OEMs eliminating external ceramic components. Target RF energy harvesting and thermoelectric generator interfaces in battery-less industrial IoT endpoints where nanopower specifications below 500 nanoamperes face limited qualified supply. Lead with direct foundry partnerships that bypass distributor markups for TWS earbud acoustic component suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a specialty analog consolidation play because automotive functional safety certification creates durable moats against commodity substitution. Acquisition targets cluster around BCD process specialists with AEC-Q100 qualification infrastructure and industrial-grade extended-temperature portfolios. Monitor foundry utilization rates in automotive-qualified nodes as the inflection signal for pricing power restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Acceleration | Compresses AEC-Q100 Grade 0 timelines to match 12-month vehicle platform sprints at Tier-1 suppliers. |
| Capacitor-Free Architecture Development | Eliminates external ceramic components for Seoul and Tokyo wearable OEMs collapsing BOM complexity. |
| Foundry-Level Wafer Agreements | Bypasses distributor channels for multi-million-unit TWS earbud contracts protecting sub-dollar margins. |
| REACH Compliance Material Transition | Preempts ECHA leadframe plating restrictions forcing expensive industrial-grade portfolio reruns. |
| Energy Harvesting Integration | Merges nanopower LDOs with RF harvesting subsystems for medical implant convergence in Kansai region. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with semiconductor design engineers, Tier-1 automotive supplier procurement leads, foundry operations managers, and industrial automation OEMs; and secondary validation through SEC 10-K filings, AEC-Q100 certification databases, EPA energy conservation standard dockets, and ECHA REACH restriction proposals. Bottom-up and top-down triangulation cross-checked unit shipment estimates against fabrication capacity disclosures.
Forecast inputs considered product architecture segmentation, end-use vertical qualification requirements, technology node migration patterns, and geographic regulatory enforcement intensity across the projection horizon. CAGRs derived from regression analysis against automotive electrification capex cycles and consumer electronics shipment trajectories. Modeled variables included BCD process utilization rates, EU Green Deal implementation pacing, and dual carbon goal enforcement by MEE.
Sensitivities concentrate around foundry allocation cycle volatility, REACH chemical restriction expansion timelines, and silicon carbide displacement acceleration in high-voltage EV powertrains. Cross-checking against IHS Markit automotive semiconductor demand forecasts and Yole Développement power electronics market trackers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
PTC Resettable Device Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Digital Audio Processor Market
Electronic Components
Docking Station Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Dual Relay Board Market
Electronic Components
Discrete Capacitors Market
Electronic Components
Global Suction Tube Market
Electronic Components
Crystal Oscillators Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
RAID Controller Card Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Impulse Relays Market
Electronic Components
Coaxial Attenuators Market
Electronic Components
Global Smartphone Cover Glass Market
Electronic Components
US Supercapacitor Market