
 PTC Resettable Device Market | 2026-2036
PTC Resettable Device Market Size, Share, and Industry Trends Forecast 2026-2036
PTC Resettable Device Market Intelligence
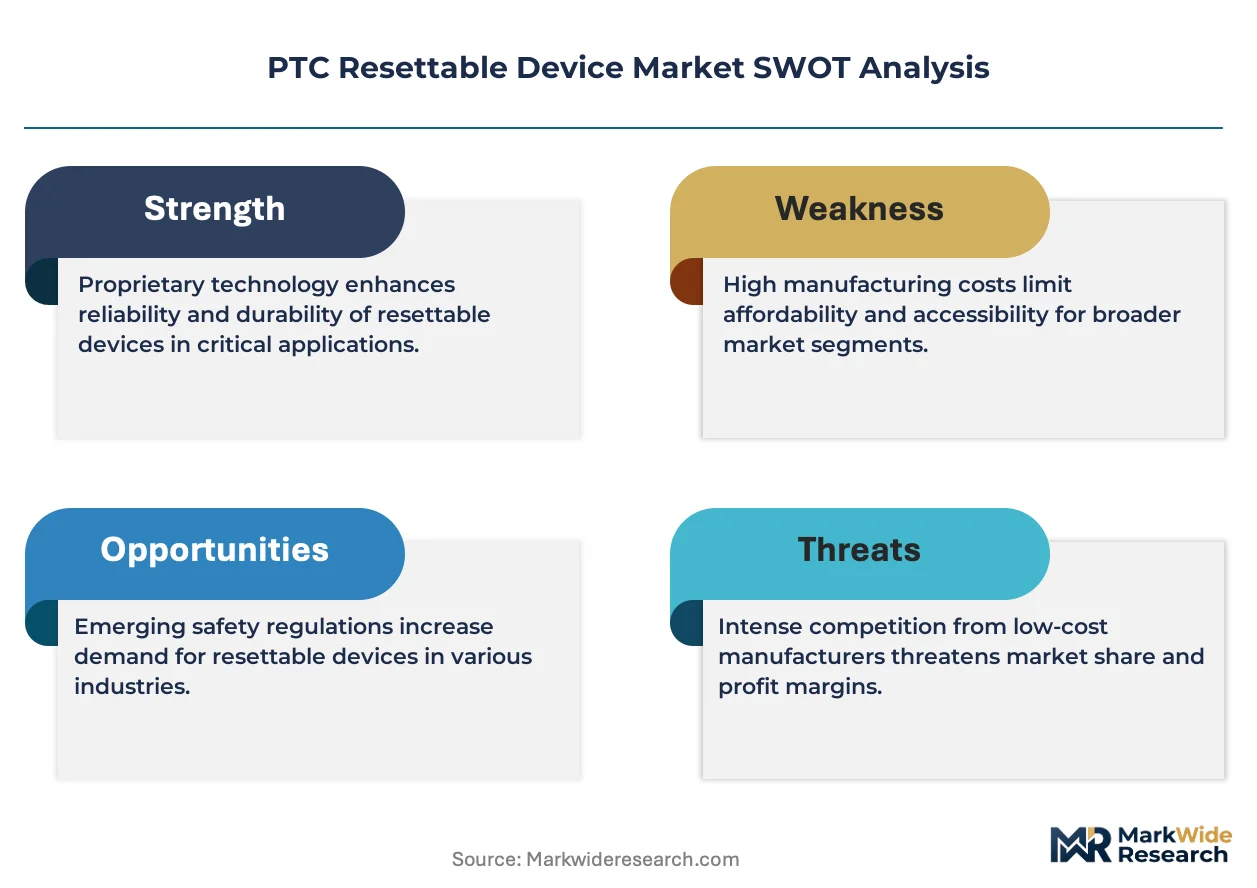
Automotive OEM procurement is restructuring around platform-standardized circuit protection specifications, reducing supplier counts while raising volume commitments per qualified vendor. Littelfuse anchors North American EV fuse integration through backward integration into polymer compounding. Bourns competes in Asian telecommunications infrastructure with ceramic PTC elements optimized for base station power distribution. TE Connectivity dominates aerospace and industrial channels through AS9100-certified manufacturing lines with extended temperature ratings.
PTC resettable devices are self-regulating overcurrent protectors fabricated from conductive polymer composites or doped silicon substrates that exhibit positive temperature coefficient resistance jumps at calibrated trip thresholds, typically resetting automatically upon fault clearance. Polymeric PTC thermistors sustain the largest installed base across consumer electronics and battery management systems due to cost scalability in surface-mount packages. Silicon PTC devices occupy premium automotive and industrial segments where trip precision within ±5°C tolerance commands higher unit economics. Hybrid PTC components are extending into renewable energy inverters where combined polymeric-silicon architectures balance resettability with surge endurance.
FCC Part 15 emissions rules shape telecommunications-grade device shielding requirements, while NHTSA FMVSS 302 flammability protocols drive automotive polymer formulation constraints. China's GB/T 18384 electric vehicle safety standards and the EU's F-Gas Regulation on fluorinated greenhouse gases are both forcing material substitutions in PTC manufacturing supply chains. Stakeholders must monitor how IEC 62368-1 hazard-based engineering standards for audio-video and IT equipment will redefine trip-characteristic certification testing across all product tiers.
Market Dynamics
Automotive platform standardization is compressing supplier qualification timelines while amplifying volume concentration among qualified PTC vendors serving EV battery management and motor control architectures.
Growth Catalysts
- EV Platform Proliferation:Electric vehicle manufacturers in China, Germany, and the United States are mandating resettable overcurrent protection across high-voltage battery packs and charging circuits, expanding unit demand per vehicle architecture.
- IEC 60730 Tightening:The international standard's stricter trip-time tolerances for automatic electrical controls is disqualifying legacy thermal fuses and accelerating polymeric PTC qualification in white goods and HVAC systems.
- Base Station Power Density:Telecommunications infrastructure buildouts are specifying ceramic PTC elements for 5G base station power distribution, driven by FCC Part 15 emissions compliance requirements and thermal management constraints.
Market Restraints
- Silver/Palladium Input Volatility:Conductive polymer formulations depend on precious metal fillers whose price swings compress gross margins for mid-tier device manufacturers without captive material hedging.
- East Asian Concentration Risk:Ceramic PTC substrate production clusters in specific Chinese provinces and South Korean industrial zones, creating single-source vulnerability for aerospace and telecommunications grade components.
- Trip Precision Ceiling:Polymeric devices face fundamental material limitations achieving sub-±10°C tolerance, ceding premium automotive and industrial segments to silicon alternatives regardless of cost differentials.
Strategic Opportunities
- India Manufacturing Incentives:The country's PLI scheme for electronic components is attracting PTC module assembly investments to serve domestic appliance and emerging EV supply chains with tariff-advantaged sourcing.
- Renewable Energy Inverter Integration:Solar and wind power conversion systems are specifying hybrid polymeric-silicon architectures that balance automatic resettability with surge endurance in grid-tied installations.
- EU F-Gas Material Substitution:The regulation's phase-down of fluorinated greenhouse gases is forcing reformulation of polymer substrates, creating first-mover advantage for vendors with compliant compound development capabilities.
Industry Challenges
- AS9100 Certification Timelines:Aerospace channel entry requires 18-24 month qualification cycles for extended temperature rating validation, straining working capital for specialty manufacturers targeting this premium segment.
- Legacy Fuse Replacement Friction:Industrial maintenance organizations resist retrofitting resettable devices into established thermal fuse architectures due to recertification costs and technician retraining requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PTC Resettable Device Market |
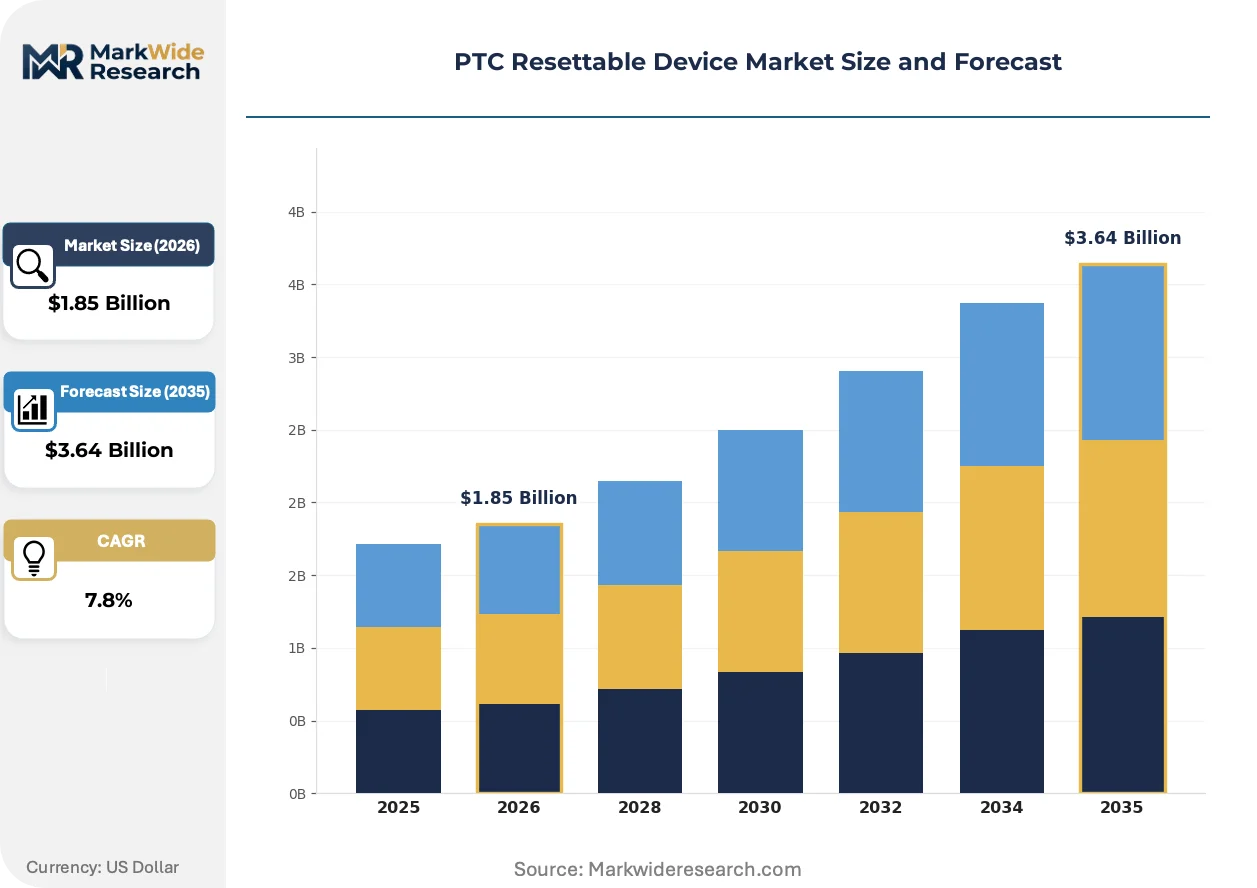
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric PTC Thermistors, Silicon PTC Devices, Hybrid PTC Components, Composite Resettable Fuses, Ceramic PTC Elements Application: Consumer Electronics Protection, Telecommunications Network Safety, Industrial Equipment Defense, Renewable Energy Systems, Data Storage Security End User: Original Equipment Manufacturers, Aftermarket Service Providers, Electrical Assemblers, Component Distributors, Electronic Repair Services Deployment: Circuit Board Integration, Inline Circuit Protection, Automotive Electrical Systems, Power Supply Units, Portable Device Protection |
| Companies Covered | Littelfuse, Bourns, TE Connectivity, Schurter, Eaton, Polytronics Technology, TDK, Vishay Intertechnology, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PTC Resettable Device Market Strategic Shifts & Innovations
Material science convergence and procurement centralization are redefining competitive advantage in circuit protection, with precision requirements and sustainability mandates accelerating product architecture evolution.
Hybrid polymeric-silicon PTC composites are absorbing surge endurance demands from renewable energy inverter manufacturers seeking automatic resettability without sacrificing thermal stability. Solar and wind power conversion system designers are adopting these architectures for grid-tied installations. The technology is absorbing market share from discrete fuse-thermistor combinations by consolidating protection functions into single surface-mount packages.
REACH substance restrictions and the EU F-Gas Regulation are forcing fluoropolymer substrate substitutions across European-sourced PTC device supply chains. Compounders are reformulating conductive polymer matrices with halogen-free flame retardants to maintain UL 1434 compliance. Automotive suppliers serving German OEMs face the most compressed compliance timelines as platform-standardized specifications lock in qualified materials through 2030 model years.
Consolidated procurement by tier-one automotive suppliers is compressing vendor counts while amplifying annual volume commitments per qualified PTC source. Battery management system integrators are unbundling fuse specification from module assembly, creating direct component sourcing relationships with resettable device manufacturers. This pattern is most visible in China and the United States where EV platform architectures concentrate purchasing power among dominant cell and pack producers.
PTC Resettable Device Market Segmentation
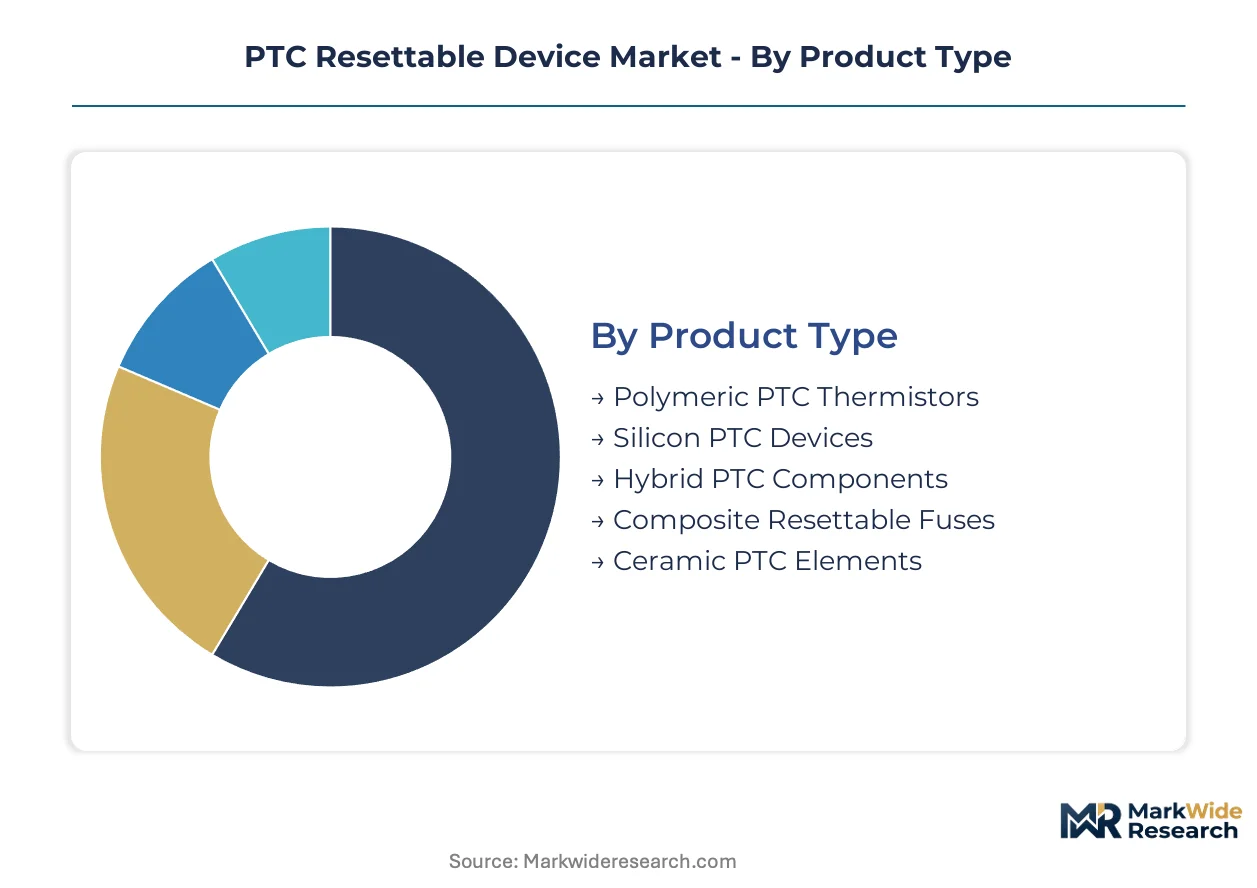
PTC resettable device procurement varies sharply across certification tiers. Automotive and aerospace channels demand AS9100-validated precision, while consumer electronics prioritize cost-scalable surface-mount compatibility.
Product Type:
UL 1434 and IEC 60730 certifications divide this category into precision-grade silicon versus cost-optimized polymeric alternatives, with hybrid architectures emerging for renewable energy crossover applications.
- Polymeric PTC Thermistors:Conductive polymer composites dominate consumer electronics and battery management systems through cost-scalable surface-mount packaging. Demand concentrates in China's EV battery pack supply chains where cell producers mandate resettable protection per GB/T 18384 standards.
- Silicon PTC Devices:Doped silicon substrates deliver ±5°C trip tolerance for premium automotive motor control and industrial automation. German OEM procurement for EV platform architectures commands the steepest expansion trajectory as NHTSA FMVSS 302 flammability protocols tighten polymer formulation constraints.
- Hybrid PTC Components:Combined polymeric-silicon architectures balance resettability with surge endurance in solar and wind inverter installations.
- Composite Resettable Fuses:Multi-layer conductive matrices serve power distribution modules requiring intermediate precision.
- Ceramic PTC Elements:Barium titanate substrates anchor telecommunications base station power distribution under FCC Part 15 emissions compliance.
Leading the category by volume: Polymeric PTC Thermistors. Growing fastest: Silicon PTC Devices.
Application:
End-use concentration tracks electrification intensity, with automotive and renewable energy applications commanding premium pricing against commoditized consumer segments.
- Consumer Electronics Protection:Smartphones, laptops, and wearables specify surface-mount polymeric devices for USB-C and battery pack protection. Volume concentrates in Shenzhen and Dongguan manufacturing clusters serving global OEM assembly.
- Telecommunications Network Safety:5G base station power distribution demands ceramic PTC elements with integrated shielding for FCC Part 15 emissions compliance. South Korean and Chinese infrastructure buildouts absorb the majority of qualified component output.
- Industrial Equipment Defense:Motor drives and HVAC controls require IEC 60730-certified trip precision for automatic electrical control integration.
- Renewable Energy Systems:Solar inverters and wind turbine power conversion specify hybrid architectures for grid-tied surge endurance.
- Data Storage Security:Server and data center power supplies employ polymeric resettable devices for hot-swap protection.
Telecommunications Network Safety captures the steepest margin expansion. Consumer Electronics Protection retains absolute volume dominance.
End User:
Procurement authority is shifting from distributors to direct OEM relationships as battery management system integrators unbundle fuse specification from module assembly.
- Original Equipment Manufacturers:Tier-one automotive suppliers and EV battery producers now source PTC devices directly, bypassing traditional distribution. China's CATL and BYD, plus US-based pack assemblers, concentrate annual volume commitments among qualified vendor pools.
- Aftermarket Service Providers:Repair networks for industrial equipment and automotive electrical systems stock polymeric resettable devices for field replacement.
- Electrical Assemblers:Contract manufacturers integrate PTC protection during wire harness and control module production.
- Component Distributors:Arrow, Avnet, and regional Asian distributors maintain inventory for mid-volume electronics producers.
- Electronic Repair Services:Independent technicians source consumer-grade resettable fuses for device refurbishment.
OEM direct procurement is accelerating fastest. Distributor channels still handle the greatest transaction volume.
Deployment:
Physical integration method determines thermal management requirements and corresponding material selection between polymeric and silicon substrates.
- Circuit Board Integration:Surface-mount PTC devices populate PCBs in consumer electronics, telecommunications equipment, and industrial controllers. Reflow soldering compatibility and compact footprints dominate design specifications.
- Automotive Electrical Systems:High-voltage battery packs, charging circuits, and motor control modules mandate resettable protection under GB/T 18384 and NHTSA safety protocols. Wire-in-line and busbar-mounted configurations predominate.
- Inline Circuit Protection:Discrete PTC devices protect wiring harnesses and cable assemblies in appliance and industrial applications.
- Power Supply Units:AC-DC and DC-DC converters integrate resettable fuses for input and output protection.
- Portable Device Protection:USB charging ports and battery compartments in handheld electronics employ compact polymeric resettable devices.
Circuit Board Integration leads by unit volume. Automotive Electrical Systems posts the fastest value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barium titanate deposits in China's Hunan province anchor ceramic PTC substrate supply chains. German polymer compounding facilities feed precision-grade silicon device fabrication. Japanese conductive filler specialists concentrate silver-palladium formulation expertise.
China
CATL and BYD battery pack producers mandate GB/T 18384-compliant resettable protection across high-voltage architectures. MIIT's dual carbon goals accelerate fluoropolymer substrate substitution timelines. Shenzhen and Dongguan manufacturing clusters absorb the majority of surface-mount polymeric device output for consumer electronics integration.
Germany
BMW, Mercedes-Benz, and Volkswagen platform standardization compresses supplier qualification windows for EV battery management systems. The EU F-Gas Regulation forces halogen-free flame retardant reformulation in polymer matrices. Bavarian industrial zones concentrate AS9100-certified precision manufacturing for aerospace channel supply.
United States
Tesla, Rivian, and Lucid Motors unbundle fuse specification from pack assembly, creating direct OEM procurement relationships. NHTSA FMVSS 302 flammability protocols tighten automotive polymer formulation constraints. Michigan and Ohio battery belt manufacturing anchors North American EV platform protection demand.
South Korea
Samsung SDI and LG Energy Solution integrate resettable devices into cylindrical and prismatic cell configurations. The national renewable energy portfolio standard drives solar inverter specification for hybrid PTC architectures. Busan-Ulsan industrial complexes host ceramic substrate production for telecommunications base station export.
Japan
Panasonic and Murata Manufacturing supply conductive polymer composites for precision automotive motor control. METI's carbon neutrality roadmap pressures material substitution in legacy fluoropolymer formulations. Kansai region chemical compounding facilities specialize in precious metal filler optimization for ±5°C tolerance devices.
PTC Resettable Device Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue renewable energy crossover applications and regional tariff-advantaged manufacturing. The vendor base stratifies across three tiers: integrated materials-compounders with captive polymer formulation, precision specialists holding AS9100 and automotive certifications, and regional assemblers serving consumer electronics through cost-scalable surface-mount packages. Dominant competitive moves include backward integration into conductive filler supply and strategic partnerships with battery management system integrators.
Among North American integrated suppliers, Littelfuse anchors polymer compounding capabilities for EV fuse integration. Bourns exemplifies the telecommunications infrastructure specialist with ceramic PTC element positioning. TE Connectivity represents the aerospace-industrial dual-channel archetype through extended temperature rating validation. These three occupy distinct tier positions without direct product overlap.
| Leading Market Players |
|---|
| Littelfuse |
| Bourns |
| TE Connectivity |
| Schurter |
| Eaton |
| Polytronics Technology |
| TDK |
| Vishay Intertechnology |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
Silver-palladium conductive fillers travel from Japanese and South Korean refineries through three distinct pricing tiers before reaching automotive OEMs, battery pack assemblers, and consumer electronics contract manufacturers downstream.
Pricing Analysis
Warranty and qualification support unbundle differently across buyer segments. Three-tier pricing structure across precision-certified, industrial-grade, and consumer-level devices separates aerospace procurement from white goods sourcing. Certification tier and volume commitment drive price differentiation, with AS9100-validated silicon devices commanding substantial premiums over polymeric alternatives. Pricing pressure stems from precious metal volatility compressing margins for non-integrated compounders. Consumer electronics buyers exhibit highest price sensitivity; aerospace channel purchasers prioritize trip precision tolerance over unit cost.
Supply Chain Analysis
Qualification gating through IEC 60730 and UL 1434 certification concentrates qualified supply among established compounders. Barium titanate ceramic substrate production clusters in China's Hunan province and South Korean industrial zones, while conductive polymer formulation draws from Japanese precious metal specialists. Silver, palladium, and fluoropolymer resin dependencies create input cost exposure. Single-source vulnerability for aerospace-grade ceramic elements constitutes the dominant structural risk. Distribution runs through direct OEM procurement for automotive battery management systems and tier-one supplier channels for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over conductive filler supply and captive polymer compounding capabilities determine margin defense.
For Market Incumbents: Hedge against silver-palladium volatility through long-term offtake agreements with Japanese and South Korean refiners. Secure AS9100 certification extensions for extended temperature ratings to defend aerospace channel position against emerging precision specialists. Capacity expansion in India's PLI-advantaged zones offsets tariff exposure in Chinese ceramic substrate sourcing.
For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for halogen-free flame retardant compound development serving German automotive OEM compliance timelines. Target renewable energy inverter integration where hybrid polymeric-silicon architectures lack established supplier relationships. Pursue direct qualification with CATL and BYD battery pack producers to bypass traditional distribution gatekeepers.
For Investors and Strategic Acquirers: First-mover fluoropolymer substitution announcements from compounders is the leading indicator that material science differentiation is reshaping competitive positioning. Mid-cap specialists with captive conductive filler supply and automotive certification depth represent prime acquisition targets across the analysis window. Watch for IEC 62368-1 hazard-based engineering standard implementation as the signal for trip-characteristic testing regime disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Littelfuse anchors North American EV fuse supply through captive conductive filler formulation. |
| AS9100 Certification Investment | TE Connectivity maintains aerospace channel dominance via extended temperature rating validation. |
| India Manufacturing Footprint Expansion | PLI scheme incentives attract module assembly investments serving domestic appliance and emerging EV chains. |
| Halogen-Free Flame Retardant Development | EU F-Gas Regulation compliance creates first-mover advantage for reformulated polymer substrate suppliers. |
| Direct OEM Procurement Relationship | Battery management system integrators unbundle fuse specification from pack assembly, bypassing distributors. |
Research Approach
Independent corroboration across primary interviews with polymer compounding engineers, Tier 1 automotive procurement officers, battery pack system integrators, and aerospace channel qualification managers underwrites the qualitative findings. Secondary validation draws from IEC standard documentation, NHTSA FMVSS protocols, SEC filings of listed component manufacturers, and customs trade data for silver-palladium conductive filler flows. Bottom-up demand modeling triangulates against top-down value chain analysis.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. The analytical framework models product type, application intensity, end-user procurement authority, and deployment method segmentation. CAGRs derive from fitted growth curves applied to certified installation bases. Forecast inputs include EV platform production schedules, telecommunications infrastructure buildout timelines, and renewable energy inverter deployment trajectories.
The model assumes a particular technology adoption path; alternative pathways for hybrid polymeric-silicon composite architectures would alter the outlook. Forecasts reflect assumptions about IEC 60730 tolerance tightening schedules and F-Gas material substitution timelines. A model refresh is warranted upon material change in precious metal price volatility or automotive platform standardization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
SAW Filters Market
Electronic Components
Braking Resistors Market
Electronic Components
US Supercapacitor Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Safety Relay Market
Electronic Components
China Data Converter Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Europe PCB Market
Electronic Components
Fuse Bases Market
Electronic Components
Audio Amplifier Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Power Inductors Market
Electronic Components
Electromechanical Relay Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Aluminum Electrolytic Capacitor Market