
 Capacitor Aluminum Polymer Market | 2026-2036
Capacitor Aluminum Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitor Aluminum Polymer Market Insights
Automotive OEM procurement is restructuring around consolidated supplier tiers for high-reliability components. Panasonic Corporation leverages its vertical integration in conductive polymer materials to anchor premium supply contracts. Nippon Chemi-Con Corporation sustains manufacturing scale across radial leaded and surface mount lines for industrial manufacturers. Nichicon Corporation differentiates through specialized high-frequency electrolytic formulations targeting telecommunications infrastructure.
Capacitor aluminum polymer denotes an aluminum electrolytic capacitor employing a conductive polymer cathode rather than traditional manganese dioxide or liquid electrolyte, typically achieving equivalent series resistance below 10 milliohms and operating temperatures up to 150°C for automotive-grade variants. This construction delivers stable capacitance under ripple current stress for switched-mode power supplies and DC-link filtering in compact electronics. Surface mount packages dominate consumer electronics volumes due to miniaturization requirements, while through hole formats retain structural importance in industrial equipment where mechanical robustness outweighs board density. Hybrid technology segments are capturing margin pools as manufacturers blend polymer cathodes with conventional electrolyte to bridge cost-performance gaps in automotive applications.
Japan's METI enacts industrial standards governing capacitor reliability metrics for automotive and telecommunications use, while the EU's RoHS and REACH frameworks restrict hazardous substances in polymer precursor chemicals and mandate supply chain disclosure. The US EPA and FCC impose complementary constraints on electronic waste streams and electromagnetic interference thresholds that shape product qualification pathways. Stakeholders must monitor evolving material compliance thresholds and polymer conductivity breakthroughs to secure qualification status across diverging regional certification regimes.
Market Dynamics
Electric vehicle power electronics are restructuring procurement volumes for aluminum polymer capacitors, as automotive OEMs consolidate supplier tiers around high-reliability DC-link filtering components capable of withstanding 150°C operating environments and ripple current stress in compact inverter designs.
Growth Catalysts
- REACH and RoHS compliance tightening:Europe's material purity requirements for electrolytic grades are accelerating substitution away from liquid electrolyte systems toward polymer cathode formulations that eliminate hazardous manganese dioxide precursors.
- Telecommunications infrastructure buildout:Base station power supplies and 5G network equipment require high-frequency electrolytic formulations with equivalent series resistance below 10 milliohms, pulling specialized surface mount packages into volume production.
- Japan manufacturing concentration:Panasonic, Nichicon, and Nippon Chemi-Con maintain captive conductive polymer material production and radial leaded manufacturing scale that anchors regional supply security for industrial equipment buyers.
Market Restraints
- Conductive polymer precursor cost volatility:EDOT monomer and related organic semiconductor feedstocks face price instability tied to petrochemical supply chains, compressing margins on standard-grade surface mount lines.
- Supplier geographic concentration risk:Three Japanese manufacturers control dominant shares of automotive-grade polymer capacitor output, creating single-source vulnerability for European and North American OEM qualification programs.
- Hybrid aluminum electrolytic substitution:Lower-cost hybrid constructions blending polymer cathodes with conventional electrolyte are capturing mid-tier automotive applications, limiting pure polymer penetration in cost-sensitive DC-link filtering.
Strategic Opportunities
- Underpenetrated industrial motor drive segment:Variable frequency drives and servo systems in factory automation present untapped demand for through-hole polymer capacitors with mechanical robustness exceeding surface mount alternatives.
- EU Green Deal industrial decarbonization incentives:Energy efficiency mandates for power electronics are creating regulatory tailwinds for low-ESR capacitor technologies that reduce switching losses in renewable energy inverters.
- Convergence of wide-bandgap semiconductors with polymer capacitors:Silicon carbide and gallium nitride power devices operating at higher frequencies and temperatures are forcing complementary upgrades in DC-link capacitor thermal performance and ripple current handling.
Industry Challenges
- Automotive AEC-Q200 certification timeline compression:Qualification cycles for 150°C-rated polymer capacitors now exceed 18 months, creating order backlog risks for OEMs launching new electric vehicle platforms.
- Polymer formulation IP licensing complexity:Conductive polymer cathode chemistry patents held by Japanese material suppliers impose royalty structures that constrain margin expansion for second-tier capacitor assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitor Aluminum Polymer Market |
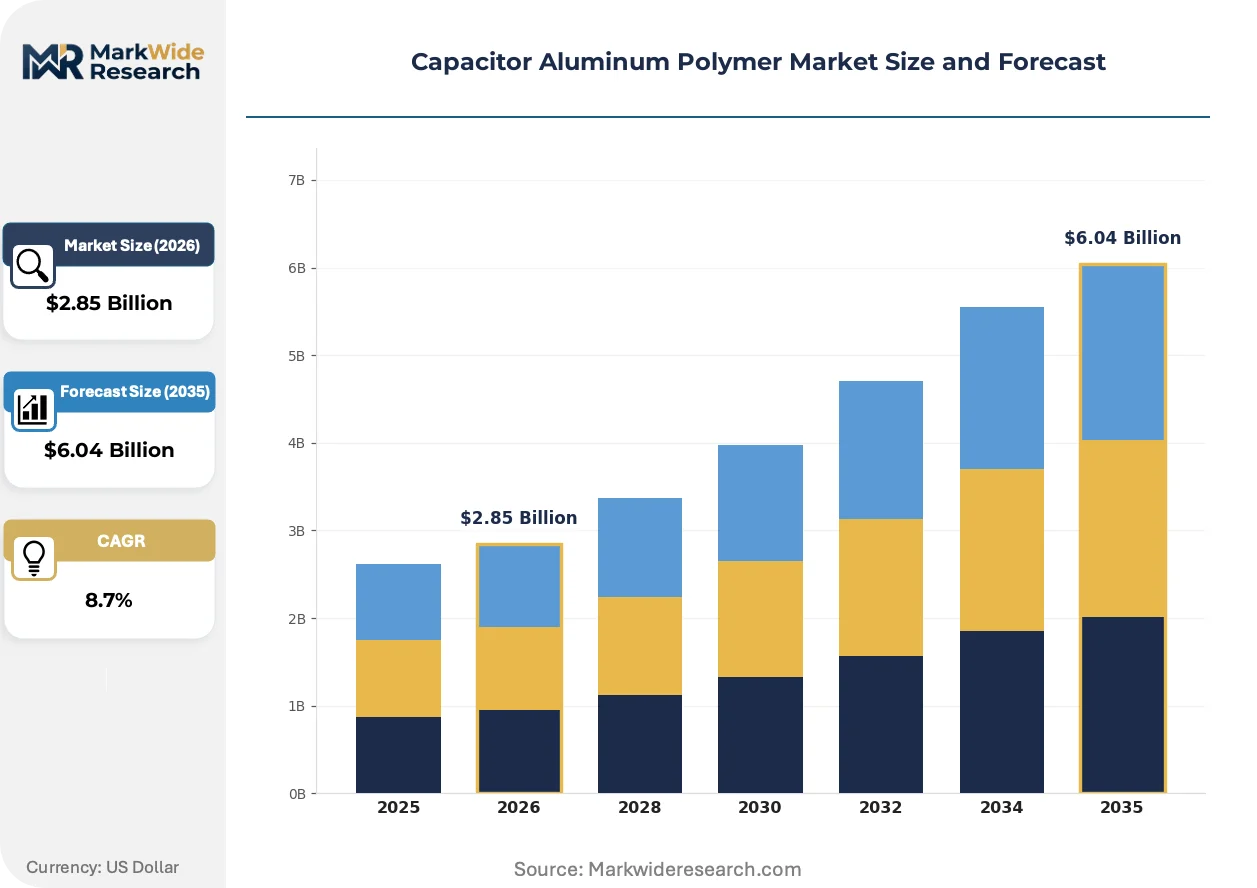
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $6.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Mount, Through Hole, Radial Leaded, Axial Leaded Application: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment End User: OEMs, Repair Services, Industrial Manufacturers, Distributors Technology: Electrolytic, Non-Electrolytic, Hybrid, High-Frequency |
| Companies Covered | Panasonic Corporation, Nippon Chemi-Con Corporation, Nichicon Corporation, Vishay Intertechnology, KEMET Corporation, Rubycon Corporation, ELNA, ROHM Semiconductor, Lelon Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitor Aluminum Polymer Market Trends and Innovations
Conductive polymer cathode technology is overtaking traditional manganese dioxide and liquid electrolyte systems across high-reliability applications, compressing equivalent series resistance thresholds and enabling thermal performance gains that redefine capacitor selection criteria for power electronics designers.
Hybrid polymer-electrolyte constructions are overtaking pure polymer formats in mid-tier automotive DC-link applications, delivering 80% of the ESR performance at 60% of the material cost. Tier-2 suppliers in South Korea and Taiwan are adopting this architecture to bypass Japanese patent thickets and qualify for second-source contracts with European OEMs. The technology is overtaking conventional aluminum electrolytics in 400V EV inverter designs where cost-performance tradeoffs favor blended cathode systems.
Japan's METI industrial standards for capacitor reliability metrics are tightening qualification thresholds for automotive and telecommunications use, forcing manufacturers to invest in accelerated life testing infrastructure. The framework mandates disclosure of polymer precursor chemical composition and supply chain provenance, adding compliance overhead that favors vertically integrated producers with in-house conductive polymer synthesis. European component distributors are responding by building buffer inventory of METI-certified parts to hedge against qualification delays.
Automotive OEMs are consolidating capacitor procurement around single-source qualification programs with extended volume commitments, replacing the spot-market purchasing that dominated industrial electronics. Tier-1 inverter suppliers are locking three-year supply agreements directly with Japanese manufacturers, bypassing traditional distribution channels. This concentration is most visible in Germany, where powertrain electrification programs at BMW, Volkswagen, and Mercedes-Benz have created dedicated supplier development teams for polymer capacitor qualification.
Capacitor Aluminum Polymer Market Segmentation
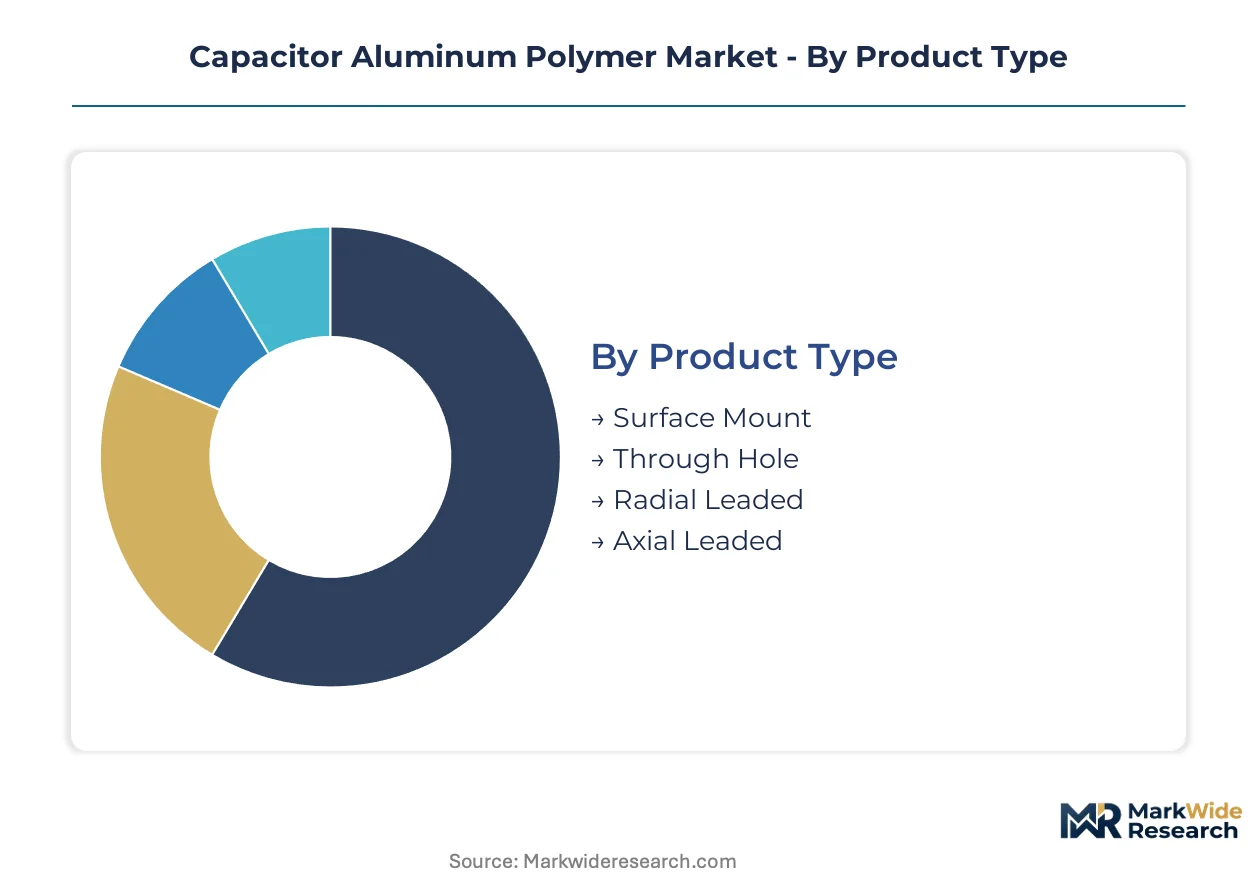
Capacitor aluminum polymer procurement patterns diverge sharply across mounting formats, end-use applications, and customer types. Supply concentration in Japanese manufacturing creates asymmetric access to high-reliability grades, forcing buyers to navigate tiered qualification pathways that segment the market into distinct commercial strata.
Product Type:
Japanese manufacturers concentrate captive polymer synthesis capacity around formats that anchor their automotive and industrial supply contracts.
- Surface Mount:Compact chip capacitors with polymer cathode layers deposited directly onto etched aluminum foil, achieving sub-10 milliohm ESR in 2.0mm x 1.25mm footprints. Consumer electronics assembly in South Korea and Taiwan pulls these volumes, though automotive-grade variants face 18-month AEC-Q200 qualification bottlenecks at Panasonic and Nichicon.
- Through Hole:Cylindrical aluminum cans with radial wire leads penetrating PCB substrates, delivering mechanical robustness for industrial motor drives and power supply filtering. German automotive OEMs specify these for inverter DC-link applications where vibration resistance exceeds surface mount capabilities.
- Radial Leaded:Wire leads emerging from a single end of the cylindrical body, dominating industrial equipment replacement markets.
- Axial Leaded:Leads extending from opposite ends of the capacitor body, retaining niche presence in legacy telecommunications hardware.
Today's leader: Surface Mount. Tomorrow's challenger: Through Hole.
Application:
End-use demand concentrates where thermal stress and ripple current density force polymer cathode adoption over conventional electrolytics.
- Automotive:DC-link filtering in 400V and 800V EV inverters, onboard chargers, and DC-DC converters operating at 150°C ambient. BMW, Volkswagen, and Mercedes-Benz procurement teams in Germany negotiate three-year supply agreements directly with Japanese manufacturers, bypassing distribution channels.
- Telecommunications:Base station power supplies and 5G radio units demanding high-frequency stability with ESR below 10 milliohms. METI reliability standards from Japan govern qualification for this segment.
- Consumer Electronics:Smartphones, laptops, and gaming consoles driving surface mount volumes through Taiwanese ODMs.
- Industrial Equipment:Variable frequency drives and servo systems requiring through-hole mechanical durability in factory automation settings.
Automotive commands premium pricing. Telecommunications offers steepest expansion trajectory as 5G buildouts accelerate.
End User:
Procurement authority is shifting from distributors toward direct OEM engagement as qualification requirements tighten.
- OEMs:Tier-1 automotive and telecommunications equipment manufacturers consolidating supplier tiers around single-source qualification programs with extended volume commitments.
- Industrial Manufacturers:Factory automation and renewable energy inverter producers sourcing through-hole formats for mechanical robustness.
- Distributors:European component distributors building buffer inventory of METI-certified parts to hedge against qualification delays.
- Repair Services:Aftermarket replacement demand for consumer electronics and industrial equipment maintenance.
OEM direct procurement dominates value capture. Distributor influence is eroding fastest under qualification compression.
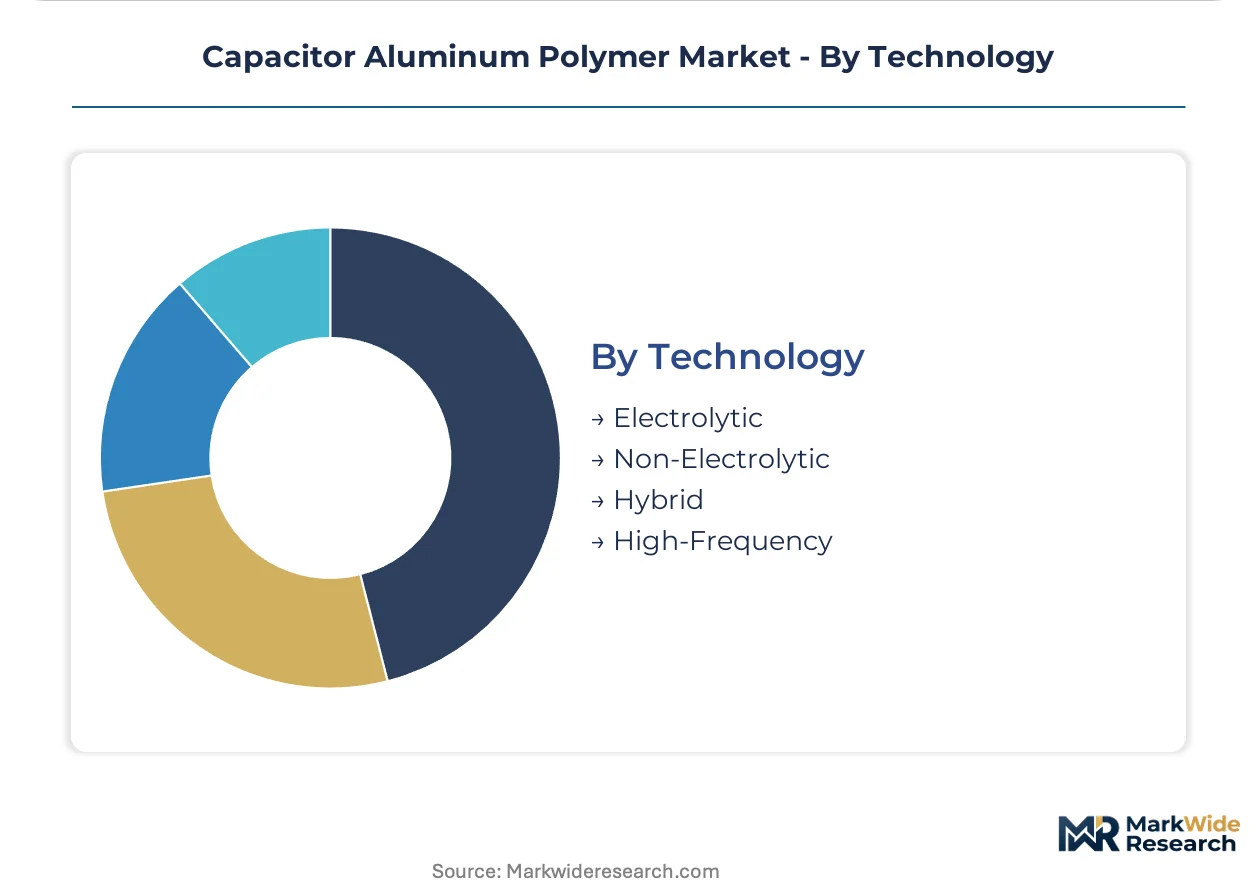
Technology:
Cathode chemistry differentiation determines thermal ceiling, ESR floor, and patent royalty exposure.
- Hybrid:Blended polymer and liquid electrolyte cathodes delivering 80% of pure polymer ESR performance at 60% of material cost. South Korean and Taiwanese suppliers adopt this architecture to bypass Japanese patent thickets and qualify for European OEM second-source contracts.
- High-Frequency:Optimized conductive polymer formulations for switching power supplies above 100kHz, with specialized surface mount packages for 5G infrastructure.
- Electrolytic:Traditional liquid electrolyte systems facing substitution pressure from REACH and RoHS compliance requirements.
- Non-Electrolytic:Solid-state ceramic and film alternatives competing at lower capacitance values.
Hybrid architectures are gaining share fastest in cost-sensitive automotive tiers. High-Frequency commands margin premiums in telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and power electronics engineers concentrate in Japanese manufacturing clusters, German automotive corridors, and Taiwanese electronics assembly zones. These talent pools anchor capacitor production networks that supply automotive inverters, telecommunications infrastructure, and consumer electronics worldwide.
Japan
Panasonic, Nichicon, and Nippon Chemi-Con employ conductive polymer specialists across Kansai and Kanto industrial belts. METI reliability standards govern automotive-grade qualification protocols. Osaka-based manufacturing campuses synthesize captive EDOT monomer and radial leaded capacitor lines for industrial equipment buyers.
Germany
BMW, Volkswagen, and Mercedes-Benz procurement teams negotiate three-year supply agreements directly with Japanese manufacturers for 150°C-rated DC-link components. REACH and RoHS frameworks restrict hazardous substances in polymer precursor chemicals. Bavarian powertrain electrification programs maintain dedicated supplier development teams for polymer capacitor qualification.
United States
Tier-1 inverter suppliers lock extended volume commitments with Asian manufacturers, bypassing traditional distribution channels. EPA electronic waste constraints and FCC electromagnetic interference thresholds shape product qualification pathways. Michigan and California automotive engineering centers specify high-reliability surface mount packages for EV platform launches.
South Korea
Hyundai and Kia electrification programs source hybrid polymer-electrolyte constructions for cost-sensitive 400V inverter designs. Domestic suppliers adopt blended cathode architectures to bypass Japanese patent thickets. Seoul-based electronics ODMs pull surface mount volumes for consumer device assembly.
Taiwan
ODM manufacturers drive surface mount package demand for smartphone, laptop, and gaming console production. Taiwanese suppliers qualify for European OEM second-source contracts using hybrid technology segments. Hsinchu and Taipei electronics corridors concentrate capacitor assembly capacity for consumer electronics brands.
Capacitor Aluminum Polymer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the capacitor aluminum polymer landscape. Three Japanese manufacturers control dominant shares of automotive-grade output, creating tiered supply access based on qualification status. Strategic archetypes include vertically integrated material producers, hybrid technology adopters, and regional assemblers serving cost-sensitive tiers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs consolidate supplier tiers.
Within the integrated-material-producer tier, Panasonic Corporation and Nippon Chemi-Con Corporation exemplify archetypes with captive conductive polymer synthesis. Nichicon Corporation occupies a specialized position in high-frequency electrolytic formulations. Among hybrid-technology adopters, South Korean and Taiwanese fabricators represent challengers bridging cost-performance gaps.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Nippon Chemi-Con Corporation |
| Nichicon Corporation |
| Vishay Intertechnology |
| KEMET Corporation |
| Rubycon Corporation |
| ELNA |
| ROHM Semiconductor |
| Lelon Electronics |
| Others |
Pricing and Supply Chain Analysis
Family-owned Japanese capacitor specialists anchor pricing discipline through captive conductive polymer synthesis, insulating premium automotive-grade supply from spot-market volatility while compressing margins on standard surface mount lines sourced through Taiwanese distribution channels.
Pricing Analysis
Unbundled component sales dominate automotive procurement, while bundled qualification services accompany long-term supply agreements. Pricing stratifies across AEC-Q200 certified, industrial-grade, and consumer-tier levels, with certification tier and volume scale as primary differentiation drivers. Cost compression in consumer electronics surface mount lines is intensifying because South Korean and Taiwanese hybrid-technology suppliers are bypassing Japanese patent royalties. Industrial manufacturers show highest price sensitivity, while German automotive OEMs prioritize thermal performance over unit cost.
Supply Chain Analysis
EDOT monomer supply rests on Japanese specialty chemical producers and German pharmaceutical-grade precursor manufacturers, with aluminum foil sourcing concentrated in Japan and China. Conductive polymer cathode deposition, etched anode forming, and automotive-grade testing feed from these inputs. Single-source vulnerability concentrates in AEC-Q200 certified polymer synthesis capacity. Distribution runs through direct OEM contracts for automotive tiers, with European distributors holding buffer inventory for industrial replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH and RoHS compliance deadlines are accelerating substitution away from liquid electrolyte systems toward polymer cathode formulations.
For Market Incumbents: Extend qualification infrastructure investments to compress AEC-Q200 certification timelines below 18-month thresholds. Deepen backward integration into EDOT monomer synthesis to offset petrochemical feedstock volatility. Lock three-year volume commitments with German automotive OEMs before hybrid-technology challengers qualify for second-source status.
For New Entrants and Emerging Players: Begin with hybrid polymer-electrolyte architectures targeting cost-sensitive 400V EV inverter designs where pure polymer penetration faces price ceilings. Industrial motor drive through-hole applications present the most penetrable white space, with European factory automation retrofit cycles offering entry timing. Qualify through Taiwanese ODM channels to establish volume credibility before approaching Tier 1 automotive procurement teams.
For Investors and Strategic Acquirers: Tier 1 automotive inverter suppliers are the most active acquirer in this space, seeking captive capacitor supply for electrification platform security. Five-to-ten-year viability hinges on conductive polymer IP licensing positions and METI certification infrastructure. Watch for inflection when silicon carbide power device adoption forces complementary DC-link capacitor thermal performance upgrades beyond hybrid-technology limits.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Polymer Synthesis | Captive EDOT production insulates Panasonic and Nippon Chemi-Con from petrochemical price volatility. |
| AEC-Q200 Certification Infrastructure Expansion | Accelerated life testing capacity addresses 18-month qualification bottlenecks for 150°C automotive grades. |
| Hybrid Technology Platform Development | Blended cathode architectures enable South Korean suppliers to bypass Japanese patent thickets. |
| Direct OEM Supply Agreement Structuring | Three-year volume commitments with BMW and Volkswagen bypass traditional European distribution channels. |
| Wide-Bandgap Semiconductor Partnership | Silicon carbide device convergence forces complementary upgrades in ripple current handling specifications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with capacitor procurement managers at Tier 1 automotive suppliers, polymer chemists at Japanese material producers, and European component distribution executives with secondary validation against METI certification databases, REACH compliance filings, and customs trade records. Bottom-up demand modeling from end-use application segments triangulated against top-down market sizing from manufacturer revenue disclosures.
Segment-weighting approaches applied differential growth assumptions across surface mount, through-hole, and hybrid technology formats, with automotive inverter content per vehicle, telecommunications infrastructure deployment cycles, and industrial equipment replacement rates as core input variables. CAGRs derived from polynomial trend fitting across historical shipment volumes and forward projection of electrification program timelines.
Several conditions sit outside the modeled scope, including speculative breakthroughs in solid-state capacitor technology and unannounced regulatory revisions to RoHS substance thresholds. Forecasts reflect documented assumptions regarding polymer precursor chemical supply stability and automotive platform launch schedules. A small set of named triggers warrants ongoing watch: silicon carbide inverter adoption curves, Japanese patent expiration timelines, and EU Green Deal industrial decarbonization incentive revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Solder Paste for Mini LED Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Screw Washer Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Class D Audio Amplifier Market
Electronic Components
Global Tantalum Capacitors Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
Electrolytic Capacitor Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Display Port Adapters Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Global Active Electronic Components Market