
 Global General Purpose Analog IC Market | 2026-2036
Global General Purpose Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
Global General Purpose Analog IC Market Foresight
AEC-Q100 qualification is redrawing competitive boundaries in automotive-grade analog IC supply. Texas Instruments sustains broadest catalog depth across voltage regulators and data converters. Infineon Technologies anchors European automotive exposure through power management specialization. STMicroelectronics competes on integrated MEMS-analog platforms for industrial sensing.
General purpose analog ICs are integrated circuits that process continuous electrical signals through specifications such as input offset voltage below one millivolt and bandwidth reaching tens of megahertz, serving fundamental conditioning, conversion, and regulation functions across electronic systems. Voltage regulators and operational amplifiers carry mature margin pools in industrial automation, while data converters capture expanding value in telecommunications infrastructure deploying 5G baseband processing. CMOS and BiCMOS technologies dominate volume production, with silicon-on-insulator variants gaining traction in aerospace applications requiring radiation tolerance.
FDA device-grade requirements and EPA hazardous substance rules in the United States, alongside REACH and RoHS frameworks in Europe, constrain material selection and reliability testing protocols for analog ICs entering medical and industrial equipment. China's MIIT and GB standards mandate domestic certification for telecom and automotive deployments, fragmenting market access procedures. Stakeholders must monitor how divergent qualification timelines across these jurisdictions reshape sourcing strategies and inventory positioning.
Market Dynamics
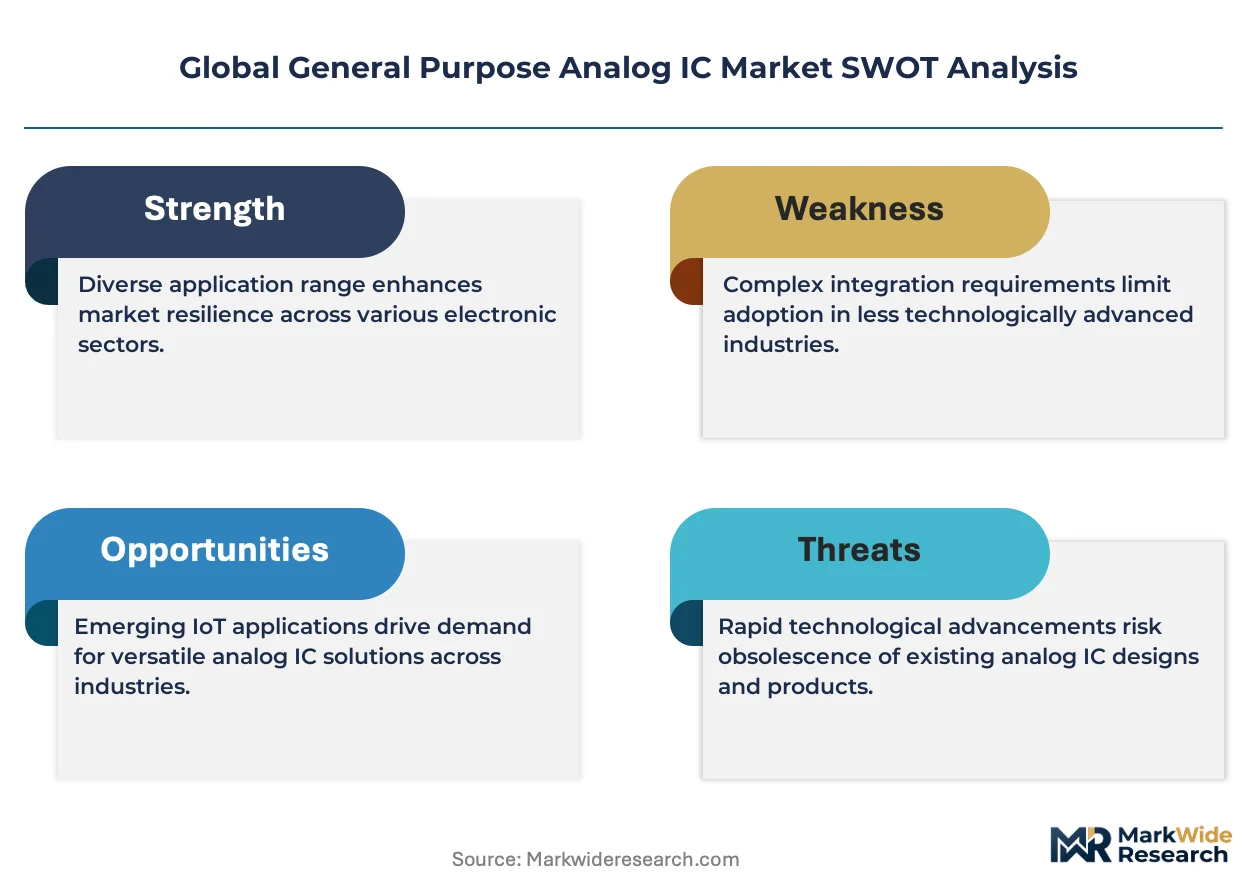
Automotive electrification is compressing qualification timelines while fragmenting certification requirements across jurisdictions, forcing analog IC suppliers to maintain parallel product portfolios for AEC-Q100, industrial, and consumer grades.
Growth Catalysts
- EU Green Deal:Binding carbon-neutrality targets for 2050 are mandating energy-efficient power management ICs across industrial motor drives and renewable inverters, expanding addressable unit demand.
- Battery Management Systems:Electric vehicle OEMs are specifying precision voltage references and current-sense amplifiers with sub-50ppm temperature drift for cell balancing and state-of-charge estimation.
- China:Domestic fabs in Shanghai and Wuxi are scaling 40nm BCD processes for integrated PMICs, reducing import dependency for telecom base stations and factory automation.
Market Restraints
- 12-inch Silicon Wafer Pricing:Foundry capacity constraints at TSMC and GlobalFoundries are elevating input costs for analog CMOS processes, compressing gross margins on commodity op-amps.
- Single-Source Analog Foundries:Mature-node capacity concentration in Taiwan exposes supply chains to geopolitical friction and export control enforcement.
- Digital-First Signal Chains:Software-defined radio and digital power controllers are displacing discrete analog front-ends in mid-range consumer electronics.
Strategic Opportunities
- India:PLI scheme incentives for semiconductor assembly and testing are attracting voltage regulator packaging investments to serve domestic appliance and automotive Tier-1 suppliers.
- Silicon Photonics Convergence:Co-packaged optical transceivers for AI data centers require precision transimpedance amplifiers and laser drivers, opening premium analog IC sockets.
- US CHIPS Act:Subsidies for domestic 300mm analog-capable fabs are enabling reshoring of automotive-grade voltage reference production from legacy 200mm Asian facilities.
Industry Challenges
- Mixed-Signal Design Talent:Scarcity of engineers proficient in precision analog layout and device physics is extending development cycles for sub-microvolt offset amplifiers.
- AEC-Q100 Rev-H Compliance:Extended temperature cycling and electrostatic discharge testing for Grade 0 automotive parts are adding 6-9 months to qualification schedules.
- Legacy System Integration:Industrial automation retrofits require voltage-level translation between 5V legacy PLCs and 3.3V modern analog ICs, complicating bill-of-materials consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global General Purpose Analog IC Market |
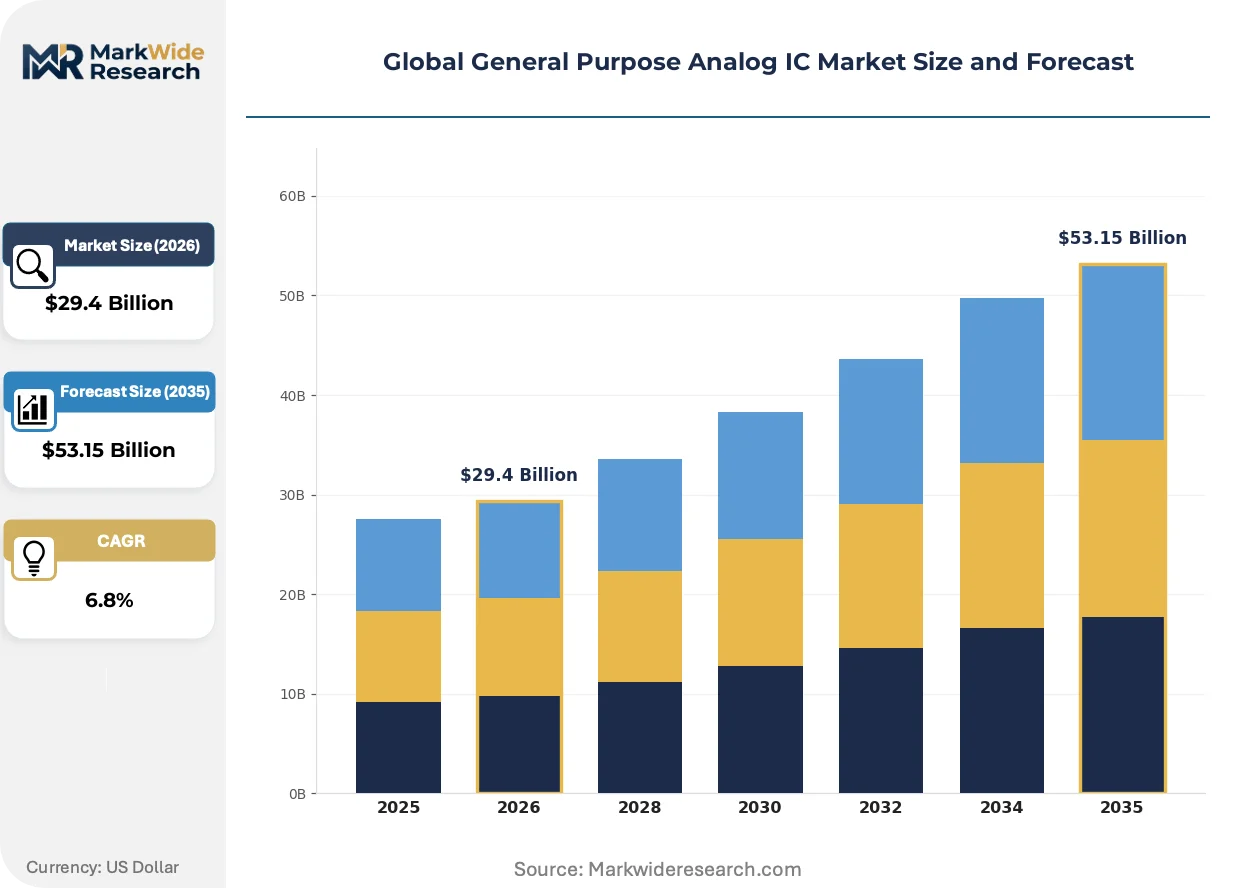
| Market Size in 2026 | $29.4 Billion |
| Market Size in 2035 | $53.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Comparators, Voltage Regulators, Data Converters, Amplifiers, Switches Application: Consumer Electronics, Industrial Automation, Telecommunications, Automotive Electronics, Aerospace, Home Appliances Technology: CMOS, Bipolar, BiCMOS, GaAs, Silicon-on-Insulator, LDMOS End User Segment: OEMs, Electronic Design Houses, Aftermarket Service Providers, Contract Manufacturers, System Integrators |
| Companies Covered | Infineon Technologies, Renesas Electronics Corporation, Texas Instruments, Microchip Technology, ON Semiconductor, Analog Devices, NXP Semiconductors, Skyworks Solutions, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global General Purpose Analog IC Market Shifts & Advancements
Process technology divergence and jurisdictional regulatory tightening are fragmenting product roadmaps, with suppliers now optimizing for application-specific performance rather than universal platforms.
Gallium nitride (GaN) power stages are bifurcating the voltage regulator landscape into silicon-dominated sub-20V rails and GaN-captured 48V-400V fast-switching domains. Data center power architects are specifying GaN-based 48V direct-conversion topologies for AI accelerator racks, collapsing the intermediate bus architecture that previously required multiple analog control loops. This technology shift is compressing addressable silicon content per watt while elevating analog gate driver and current-sense precision requirements.
REACH substance restrictions on lead and cadmium in Europe are forcing material substitutions in precision resistor networks and voltage reference die attach, extending reliability qualification timelines. Analog IC suppliers are reformulating mold compounds and plating chemistries to maintain RoHS compliance while satisfying automotive 1000-hour high-temperature operating life tests. Medical device manufacturers in Germany and France are experiencing 4-6 month delays as they revalidate biocompatible packaging materials under MDR documentation requirements.
Direct procurement contracts between automotive OEMs and analog IC suppliers are displacing traditional distribution for AEC-Q100-qualified parts, with Tier-1 module makers losing margin capture on voltage regulators and data converters. Bosch, Continental, and Denso are establishing preferred supplier agreements specifying 52-week buffer stock commitments and penalty clauses for allocation shortfalls. This channel consolidation is most pronounced in Germany and Japan, where just-in-sequence manufacturing leaves minimal inventory tolerance for power management IC shortages.
Global General Purpose Analog IC Market Segmentation
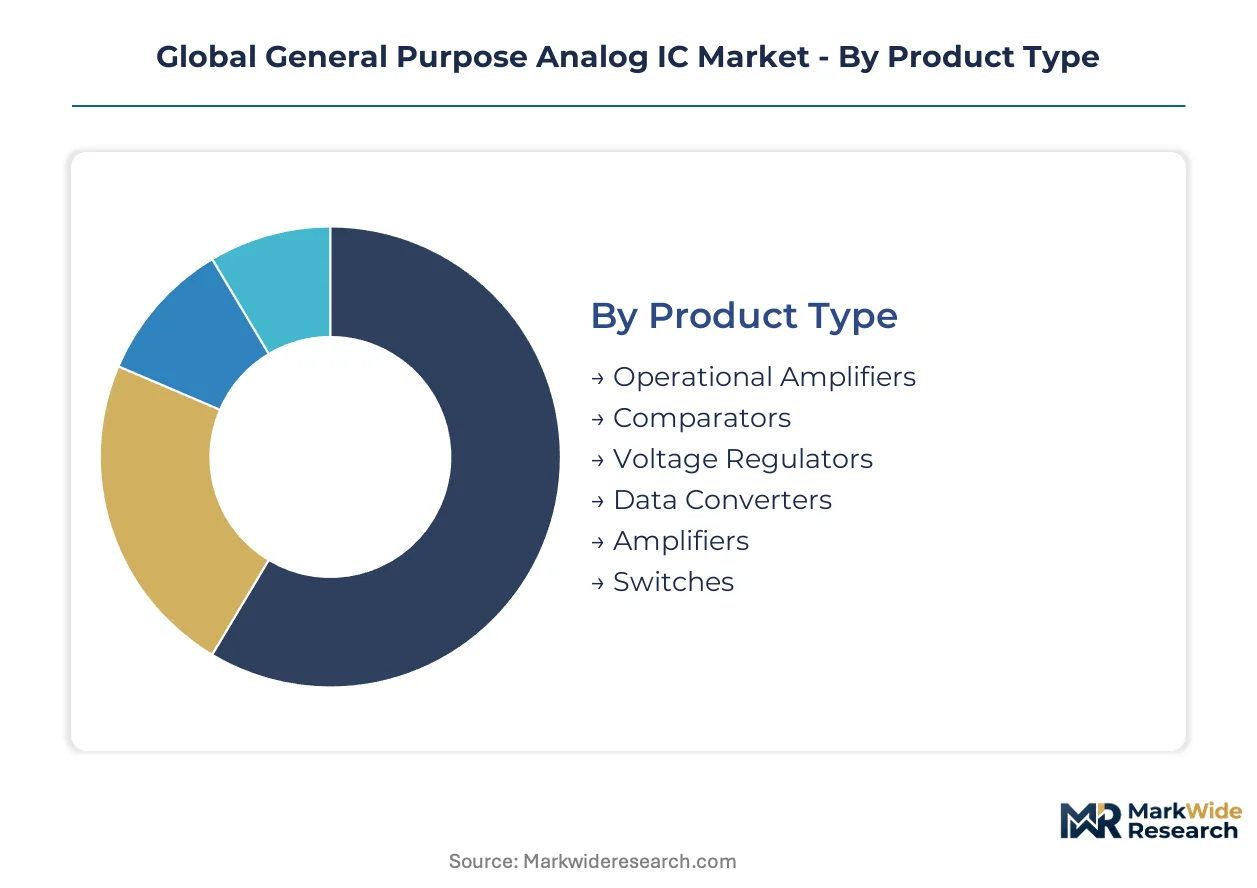
Product variety across voltage rails, signal fidelity, and temperature grades forces suppliers to maintain parallel inventories for automotive, industrial, and consumer channels. Channel partners stock discrete op-amps and voltage regulators in high volume, while direct procurement dominates precision data converters for automotive battery management.
Product Type:
Channel mix bifurcates between high-volume commodity parts flowing through distribution and precision-grade devices moving through direct OEM contracts.
- Operational Amplifiers:These devices amplify differential input signals with input offset voltages below one millivolt and bandwidth extending to tens of megahertz. Industrial automation in Germany and Japan concentrates procurement for motor control and sensor conditioning, where precision offsets command premium pricing over commodity alternatives.
- Voltage Regulators:Linear and switching topologies maintain stable output rails across load transients, with low-dropout variants dominating battery-powered applications. Automotive OEMs in China and South Korea are specifying integrated PMICs with multiple regulated outputs for electric vehicle subsystems, compressing discrete component counts.
- Comparators:High-speed threshold detection with propagation delays under 100 nanoseconds serves zero-crossing detection and window comparator functions.
- Data Converters:ADCs and DACs bridge analog and digital domains with resolutions spanning 8 to 24 bits.
- Amplifiers:Instrumentation and differential varieties provide high common-mode rejection for sensor interfaces.
- Switches:Analog multiplexers and solid-state relays route signals with minimal insertion loss across test equipment and medical imaging.
Voltage regulators dominate installed base across consumer and industrial applications. Data converters are where expansion concentrates, driven by 5G infrastructure deployment and automotive sensor fusion requirements.
Application:
Margin tiers separate automotive-grade qualification from consumer electronics volume, with certification requirements fragmenting supplier portfolios across end-use segments.
- Automotive Electronics:AEC-Q100-qualified parts withstand temperature extremes from minus 40 to 150 degrees Celsius and meet stringent electromagnetic compatibility standards. Battery management systems for electric vehicles in China, Germany, and the United States are specifying precision voltage references with sub-50ppm temperature drift for cell balancing algorithms.
- Industrial Automation:Programmable logic controllers, motor drives, and process control systems demand 24V-tolerant inputs and galvanic isolation compatibility. Factory automation retrofits in Japan and Italy are accelerating demand for voltage-level translators bridging 5V legacy equipment with 3.3V modern analog ICs.
- Consumer Electronics:Smartphones, tablets, and wearables prioritize power efficiency and miniaturization over precision specifications.
- Telecommunications:5G base stations and optical transport equipment require high-speed data converters and low-noise amplifiers.
- Aerospace:Radiation-hardened and high-reliability variants serve satellite and avionics applications with extended qualification timelines.
- Home Appliances:Motor control and power monitoring ICs address energy efficiency regulations across refrigeration and HVAC systems.
Industrial automation holds the largest installed base of mature-node analog ICs. Automotive electronics is gaining share fastest, propelled by electrification mandates across multiple jurisdictions.
Technology:
Process node selection trades off precision, power consumption, and radiation tolerance, with foundry capacity allocation constraining supply elasticity for specialized variants.
- CMOS:Dominant volume production technology offering low static power consumption and scalable lithography down to 40 nanometers for integrated PMICs. Domestic fabs in Shanghai and Wuxi are expanding 40nm BCD-CMOS capacity to serve telecom base stations and factory automation, reducing import dependency for Chinese equipment manufacturers.
- BiCMOS:Combines bipolar precision with CMOS density for high-performance data converters and precision amplifiers. Automotive sensor interfaces in Germany and Japan leverage BiCMOS for combined analog accuracy and digital calibration capabilities.
- Bipolar:Legacy technology retained for ultra-low-noise amplifiers and precision voltage references.
- Silicon-on-Insulator:Radiation tolerance and reduced parasitic capacitance serve aerospace and high-reliability defense applications.
- GaAs:High electron mobility supports microwave and millimeter-wave frequencies in radar and satellite communications.
- LDMOS:Lateral double-diffused MOS structures handle high voltages for RF power amplifiers and automotive ignition systems.
CMOS commands the broadest installed base across consumer and industrial segments. BiCMOS is where expansion concentrates for automotive and precision instrumentation applications.
End User Segment:
Procurement authority is shifting from distribution toward direct OEM engagement, with qualification requirements and buffer stock commitments restructuring channel economics.
- OEMs:Original equipment manufacturers in automotive and industrial sectors are establishing preferred supplier agreements with 52-week buffer stock commitments. Bosch, Continental, and Denso in Germany and Japan are displacing traditional distribution for AEC-Q100-qualified voltage regulators and data converters through direct procurement contracts.
- Contract Manufacturers:Foxconn, Jabil, and Flex manage high-volume assembly for consumer electronics brands, consolidating analog IC purchasing across multiple OEM customers. Their procurement leverage concentrates demand for commodity op-amps and voltage regulators serving smartphone and appliance production in China and Vietnam.
- Electronic Design Houses:Specialized engineering firms develop custom analog front-ends for medical and test equipment.
- System Integrators:Industrial automation and building control specialists combine analog sensing with digital processing platforms.
- Aftermarket Service Providers:Repair and refurbishment operations source replacement analog ICs for legacy equipment maintenance.
OEMs dominate value capture for automotive and industrial-grade parts. Contract manufacturers concentrate volume procurement for consumer electronics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsidy programs and carbon-neutrality mandates are redrawing manufacturing footprints across major economies. China, Germany, the United States, Japan, and South Korea concentrate the bulk of analog IC demand and supply-side investment.
China
Domestic fabs in Shanghai and Wuxi are scaling 40nm BCD-CMOS processes for integrated PMICs serving telecom base stations and factory automation. MIIT and GB standards mandate local certification for automotive and telecom deployments. Yangtze River Delta clusters are absorbing capacity expansion to reduce import dependency for industrial equipment manufacturers.
Germany
Automotive OEMs in Stuttgart and Munich are establishing direct procurement contracts with 52-week buffer stock commitments for AEC-Q100-qualified parts. The EU Green Deal and F-Gas Regulation tighten material and energy-efficiency requirements for semiconductor production. Bavaria's industrial automation sector is accelerating demand for voltage-level translators bridging legacy 5V PLCs with modern 3.3V analog ICs.
United States
CHIPS Act subsidies are enabling reshoring of automotive-grade voltage reference production from legacy 200mm Asian facilities. FDA device-grade requirements and EPA hazardous substance rules constrain material selection for medical and industrial equipment. Arizona and Texas are attracting 300mm analog-capable fab investments to serve domestic automotive Tier-1 suppliers.
Japan
Industrial automation retrofits in Nagoya and Osaka are driving procurement for precision operational amplifiers in motor control applications. METI policies support domestic semiconductor supply chain resilience amid geopolitical friction. Kyushu-based foundries are maintaining mature-node capacity for automotive sensor interfaces requiring combined analog accuracy and digital calibration.
South Korea
Electric vehicle OEMs are specifying precision voltage references with sub-50ppm temperature drift for battery management systems. The country's national semiconductor regulator enforces qualification timelines that parallel AEC-Q100 standards. Seoul Capital Area design houses are scaling CMOS output for consumer electronics and telecommunications infrastructure deploying 5G baseband processing.
Global General Purpose Analog IC Market Competitive Landscape
Listed leaders compete with private specialists across catalog breadth and application-specific depth. The vendor base clusters around three tiers: diversified catalog houses maintaining thousands of SKUs, automotive-focused power management specialists, and integrated MEMS-analog platform providers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct OEM contracts displacing traditional distribution for qualified automotive parts.
Within the diversified catalog tier, Texas Instruments and Analog Devices exemplify breadth across voltage regulators and data converters. Infineon Technologies occupies a position as a European automotive anchor through power management specialization. STMicroelectronics sits within the integrated platform segment, competing on combined MEMS and analog solutions for industrial sensing applications.
| Leading Market Players |
|---|
| Infineon Technologies |
| Renesas Electronics Corporation |
| Texas Instruments |
| Microchip Technology |
| ON Semiconductor |
| Analog Devices |
| NXP Semiconductors |
| Skyworks Solutions |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Fifty-two-week buffer stock commitments from Bosch, Continental, and Denso compress lead times for AEC-Q100-qualified voltage regulators while amplifying pricing power for analog IC suppliers with captive foundry capacity. This inventory obligation structure concentrates procurement leverage among automotive OEMs with direct supplier agreements, fragmenting margin capture across qualified and unqualified product tiers.
Pricing Analysis
Certification level creates the primary spread between automotive-grade AEC-Q100 parts and industrial or consumer alternatives. Three-tier pricing structure across AEC-Q100 Grade 0, industrial extended-temperature, and commercial-grade separates premium automotive sockets from commodity op-amp volumes. Cost compression in consumer-grade operational amplifiers intensifies because foundry capacity allocation favors automotive qualification timelines. Contract manufacturers serving smartphone and appliance production exhibit highest price sensitivity, while German and Japanese automotive OEMs absorb premium pricing for guaranteed allocation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for silicon wafer shipments from Taiwanese foundries. Analog IC production concentrates in Taiwan, South Korea, and China, with mature-node CMOS capacity at TSMC and GlobalFoundries feeding voltage regulator and data converter assembly. Raw material dependencies span 12-inch silicon wafers, BCD-process chemicals, and RoHS-compliant mold compounds. Single-source vulnerability at Taiwanese analog foundries exposes supply chains to export control enforcement. Distribution runs through direct OEM contracts for automotive-grade parts and authorized distribution for industrial and consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
General purpose analog IC demand sits in early-cycle expansion, propelled by electric vehicle battery management system penetration across multiple jurisdictions.
For Market Incumbents: Fortify AEC-Q100 qualification pipelines against GaN power stage substitution in 48V-400V fast-switching domains. Expand captive 300mm analog-capable fab capacity in Arizona and Texas to reduce exposure to Taiwanese foundry concentration. Deepen backward integration into BCD-process equipment to secure mature-node capacity allocation priority. For New Entrants and Emerging Players: Lead with silicon photonics convergence opportunities in AI data center transimpedance amplifiers and laser drivers, where precision analog IC sockets remain underserved by established catalog houses. Target India's PLI scheme assembly and testing incentives for voltage regulator packaging serving domestic appliance and automotive Tier-1 suppliers. Pursue design partnerships with Shanghai and Wuxi fabs scaling 40nm BCD processes for integrated PMICs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized analog IC divisions lacking automotive qualification infrastructure. Long-term viability centers on AEC-Q100 certification depth and foundry access security over the next decade. Monitor buffer stock commitment fulfillment rates at Bosch, Continental, and Denso as inflection indicators for supply allocation tightness.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Grade 0 Qualification Investment | Unlocks direct procurement contracts with German and Japanese automotive OEMs specifying 52-week buffer stocks. |
| 300mm Analog-Capable Fab Expansion | CHIPS Act subsidies enable reshoring of voltage reference production from legacy 200mm Asian facilities. |
| Silicon Photonics Co-Packaging Partnership | Captures premium analog IC sockets in AI data center optical transceivers requiring precision transimpedance amplifiers. |
| 40nm BCD-CMOS Process Scale-Up | Shanghai and Wuxi fabs reduce Chinese import dependency for telecom base station integrated PMICs. |
| GaN Gate Driver and Current-Sense Development | Addresses collapsing silicon content per watt in 48V direct-conversion topologies for AI accelerator racks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, MIIT certification databases, and AEC-Q100 qualification registries. Primary interviews engaged analog IC design engineers, automotive Tier-1 procurement managers, foundry capacity planners, and industrial automation system integrators. Secondary validation drew from EPA hazardous substance rules, REACH substance restriction notices, and EU Green Deal implementation guidelines. Bottom-up unit demand modeling triangulates against top-down semiconductor consumption estimates.
Segmentation dimensions modeled span product type, application, technology node, and end-user procurement authority across the projection horizon. Voltage regulator and data converter demand disaggregates by automotive electrification intensity, industrial automation retrofit cycles, and 5G infrastructure deployment phases. CAGRs derive from foundry capacity expansion schedules, OEM platform rollout timelines, and jurisdictional regulatory compliance trajectories. Forecast inputs incorporate BCD-process yield improvements and GaN power stage substitution elasticities.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification mandates, stable Taiwan Strait logistics, and continued REACH-RoHS material compliance would require recalibration. Forecasts reflect documented assumptions regarding foundry allocation priorities and OEM direct procurement adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Integrated CMOS Tri-Gate Transistor Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Display LSI IC Market