
 Automation Component Market | 2026-2036
Automation Component Market Size, Share, and Industry Trends Forecast 2026-2036
Automation Component Market Outlook
Multi-source procurement of precision motion components is consolidating around a smaller circle of qualified vendors with certified cleanroom manufacturing. Emerson Electric Co. leverages its programmable automation controller portfolio to anchor large process-industry accounts in North America. Siemens AG sustains dominance across European automotive OEM lines through its integrated drive systems architecture. Rockwell Automation, Inc. competes aggressively on edge-native controller platforms for hybrid cloud deployments.
Automation components encompass electromechanical and electronic devices—including proximity sensors rated to IP69K, servo actuators with sub-micron repeatability, and PLCs executing scan cycles below one millisecond—that translate control signals into physical action across industrial systems. Their primary purpose is closing feedback loops between digital process models and mechanical execution in continuous or discrete manufacturing. Controllers and HMIs capture the largest margin pools as software-defined functionality displaces dedicated hardware, while edge computing installations represent the fastest structural expansion as latency requirements tighten below ten milliseconds for robotic coordination. Sensors retain volume leadership but face commoditization pressure as Chinese producers scale MEMS fabrication capacity.
The US Department of Energy enforces motor efficiency standards through NEMA MG-1 Table 12-12, directly shaping variable-frequency drive and servo motor specifications for domestic manufacturing. China's MIIT mandates GB standard compliance for industrial control system cybersecurity, creating market access barriers for uncertified foreign component suppliers. The EU AI Act classifies certain autonomous control loops as high-risk, imposing conformity assessment burdens on AI-integrated automation architectures. Stakeholders must monitor divergence between US, Chinese, and European certification regimes when designing unified product platforms for multinational deployment.
Market Dynamics
Electric vehicle assembly lines are forcing rapid retooling of precision motion infrastructure as legacy internal-combustion tooling reaches obsolescence ahead of depreciation schedules. Tier-one suppliers must simultaneously absorb battery-pack automation requirements and F-Gas cooling retrofits without disrupting running production.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:Refrigerant-based cooling system replacements are accelerating retrofit procurement across German and French automotive plants, creating pull-through demand for compatible servo drives and thermal sensors.
- China Yangtze River Delta Cluster:Concentrated battery gigafactory construction is concentrating demand for IP69K-rated proximity sensors and sub-millisecond PLCs within a 200-kilometer manufacturing corridor.
- Edge-Native Controller Architectures:Latency requirements below ten milliseconds for robotic coordination are displacing centralized control rooms with distributed computing nodes at the machine level.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium processing dependence on Chinese refining capacity creates vulnerability for high-torque servo motor production outside Asia.
- MIIT GB Standard Cybersecurity Certification:China's mandatory industrial control system security compliance creates market access friction for uncertified foreign component suppliers without in-country testing partnerships.
- MEMS Commoditization Pressure:Chinese fabrication scale-up of microelectromechanical sensors is compressing margins on volume proximity and pressure sensing categories.
Strategic Opportunities
- India PLI Scheme for Manufacturing:Production-linked incentives for advanced cell chemistry and electronics assembly are creating greenfield automation demand in Gujarat and Tamil Nadu industrial corridors.
- AI-Integrated Control Loop Certification:EU AI Act high-risk system classification is opening consultative service revenue streams for automation vendors offering conformity assessment bundled with hardware.
- Hybrid Cloud Edge Deployment:Convergence of OT-IT networking standards is enabling controller vendors to capture recurring software revenue through subscription-based runtime licensing.
Industry Challenges
- Functional Safety Engineer Scarcity:SIL-rated system design expertise sits concentrated with aging European and Japanese specialists, constraining project execution speed for safety-critical automotive lines.
- Legacy PLC Protocol Migration:Proprietary fieldbus architectures in installed bases resist Ethernet-IP and OPC-UA standardization, forcing costly gateway hardware insertion or rip-and-replace decisions.
- Dual-Carbon Compliance Documentation:China's MEE carbon intensity reporting requirements for industrial equipment are extending sales cycles as vendors assemble supply-chain emission attestations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automation Component Market |
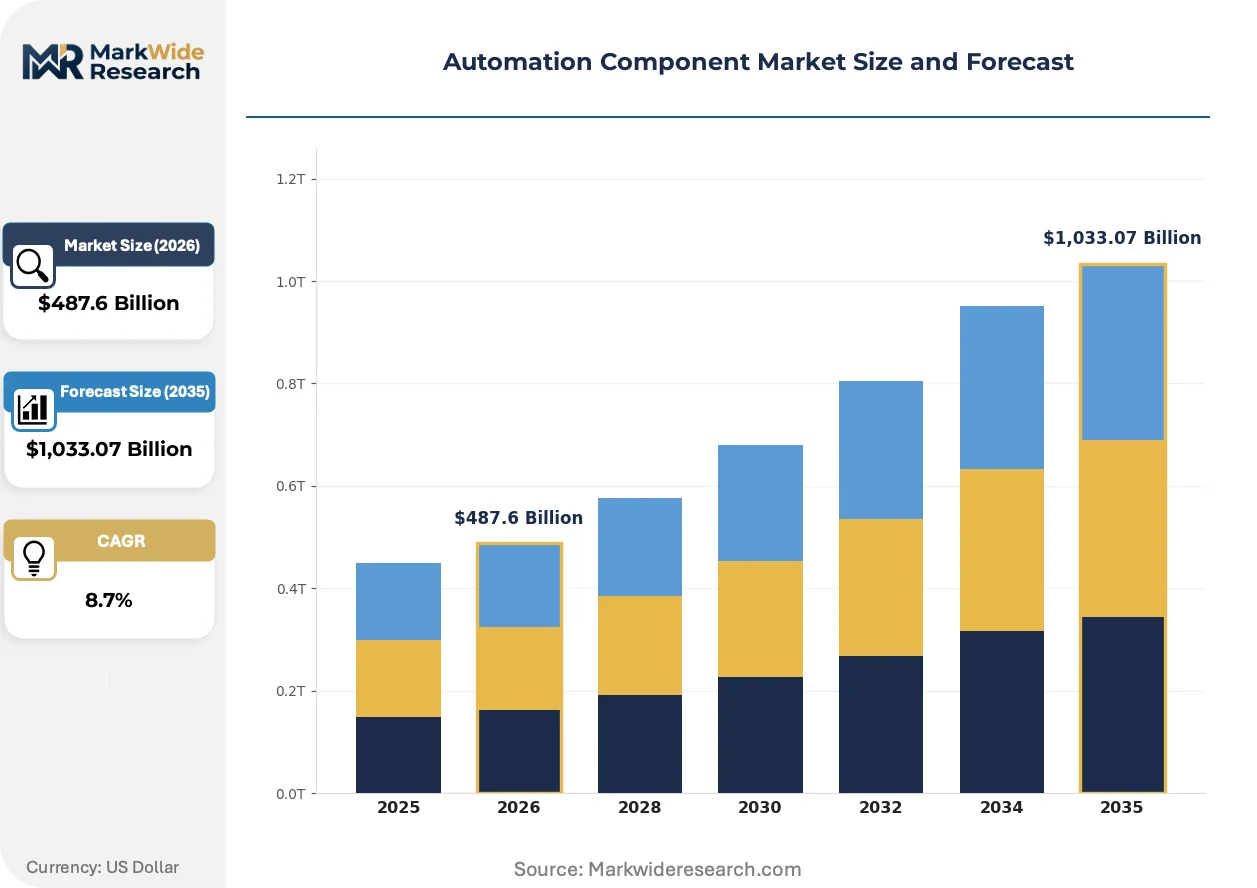
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,033.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Sensors, Actuators, Controllers, Relays Technology: PLC, SCADA, DCS, HMI Industry Application: Manufacturing, Oil & Gas, Automotive, Food Processing Installation Type: On-premises, Cloud-based, Edge Computing, Hybrid |
| Companies Covered | Emerson Electric Co., Rockwell Automation, Inc., ABB Ltd., Siemens AG, Schneider Electric SE, Parker Hannifin Corporation, Mitsubishi Electric Corporation, Honeywell International Inc., Nidec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automation Component Market Strategic Shifts
Software-defined functionality is compressing dedicated hardware margins while redistributing value toward runtime platforms and edge analytics. Three concurrent developments are restructuring competitive position.
Time-sensitive networking over standard Ethernet is decentralizing machine-to-machine coordination previously requiring proprietary fieldbus infrastructure. Automotive OEMs in Germany and the US are deploying TSN-enabled servo networks at greenfield battery plants, collapsing wiring complexity and enabling controller-agnostic sensor integration. This architecture is decentralizing hardware lock-in toward interoperable component sourcing.
EU F-Gas Regulation tightening of hydrofluorocarbon phase-down schedules is mandating refrigerant transition in automation cooling systems by 2027. Process industries with continuous thermal loads face accelerated chiller and heat-exchanger replacement cycles, favoring vendors with pre-certified low-global-warming-potential portfolios. Food and pharmaceutical packaging lines in France and Italy are most affected, with procurement specifications now excluding legacy refrigerant compatibility.
Automotive tier-one suppliers are consolidating vendor panels for precision motion components around qualified cleanroom manufacturers with certified contamination control. Multi-source procurement is narrowing to dual-vendor strategies with mutual manufacturing process equivalency. This concentration is most visible in German and South Korean EV battery supply chains, where component traceability requirements now extend to sub-tier material origins.
Automation Component Market Segmentation
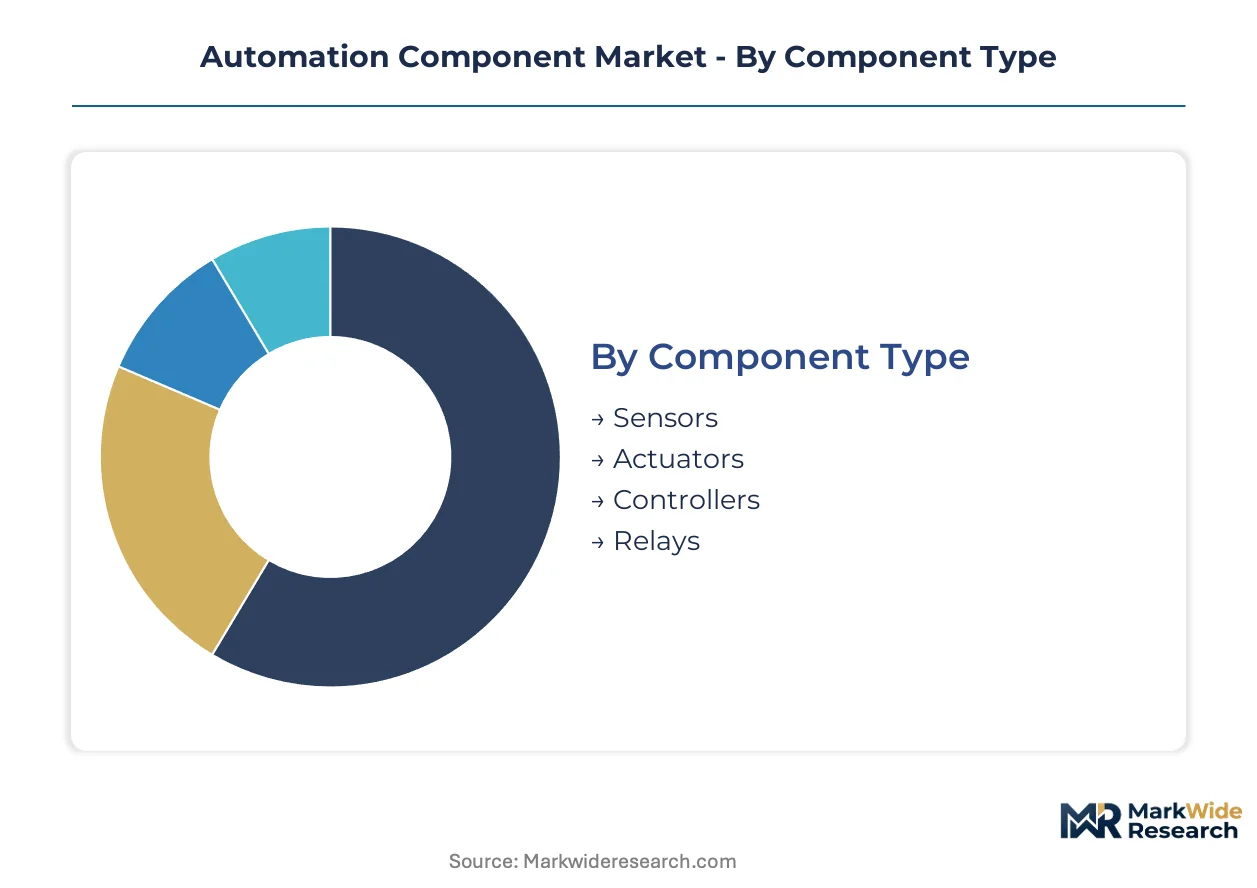
Automation component procurement patterns diverge sharply across technical specifications, control architectures, and deployment models. Vendors must align product roadmaps with the specific latency, environmental, and integration requirements of each segment cluster.
Component Type:
Supply concentration for precision-grade electromechanical devices favors established producers with certified cleanroom manufacturing and sub-micron repeatability verification.
- Sensors:IP69K-rated proximity devices with MEMS architectures dominate automotive battery plant installations. Demand concentrates in China's Yangtze River Delta corridor, where gigafactory construction is absorbing volume production from domestic fabrication scale-ups.
- Actuators:Servo motors with neodymium-dysprosium magnet rotors deliver sub-micron positioning repeatability for EV assembly tooling. German automotive OEMs are dual-sourcing from qualified cleanroom vendors to mitigate rare earth supply concentration risks.
- Controllers:Programmable units executing scan cycles below one millisecond anchor process-industry accounts.
- Relays:Electromechanical switching devices bridge legacy fieldbus architectures during Ethernet-IP migration projects.
Today's leader: Controllers. Tomorrow's challenger: Sensors.
Technology:
Control system architectures stratify by latency tolerance, with edge-native platforms gaining share in robotic coordination applications.
- PLC:Programmable logic controllers with sub-millisecond scan cycles execute discrete manufacturing sequences. Food processing lines in France and Italy specify OPC-UA connectivity to satisfy F-Gas retrofit integration timelines.
- SCADA:Supervisory control systems aggregate distributed sensor networks across continuous process operations. Oil and gas facilities in the US Gulf Coast deploy these for remote pipeline monitoring under EPA emissions tracking mandates.
- DCS:Distributed control architectures manage multi-variable process loops in chemical and refining operations.
- HMI:Human-machine interfaces capture expanding margin pools as software-defined functionality displaces dedicated hardware panels.
PLC installations retain volume leadership. HMI platforms are climbing the fastest on subscription runtime revenue models.
Industry Application:
End-use demand concentrates in sectors undergoing forced retooling from regulatory phase-outs or technology transitions.
- Automotive:EV assembly lines are forcing rapid precision motion infrastructure replacement as internal-combustion tooling reaches obsolescence. Tier-one suppliers in Germany and South Korea must absorb battery-pack automation requirements without disrupting running production.
- Manufacturing:Discrete production facilities deploy edge-native controllers for latency-critical robotic coordination.
- Oil & Gas:Continuous process operations with thermal loads face accelerated chiller replacement under EU F-Gas phase-down schedules.
- Food Processing:Packaging lines specify low-global-warming-potential cooling compatibility in procurement tenders.
Automotive commands current capital deployment. Food processing shows steepest expansion trajectory on regulatory retrofit deadlines.
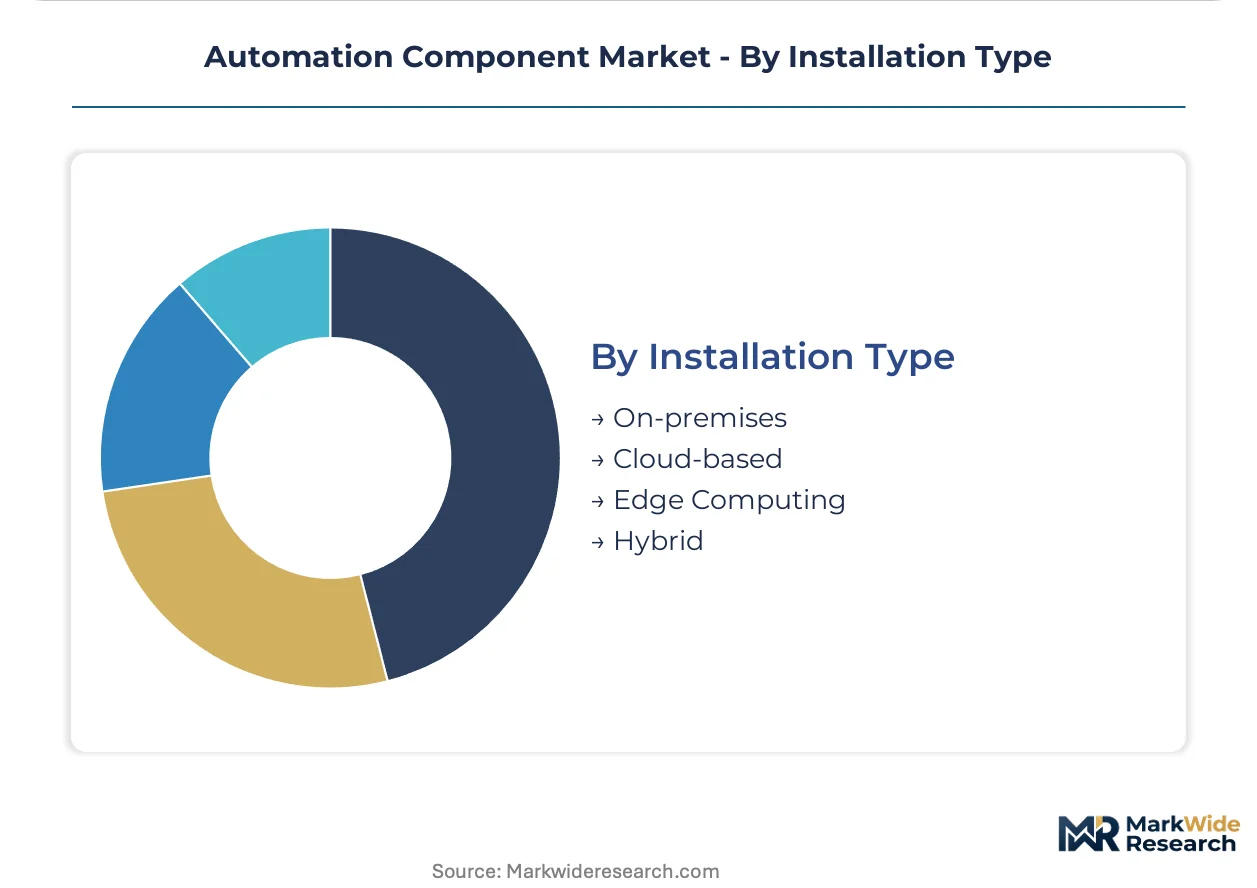
Installation Type:
Deployment models diverge by latency requirements, with sub-ten-millisecond robotic coordination favoring distributed over centralized architectures.
- Edge Computing:Distributed nodes at the machine level execute control loops with latency below ten milliseconds. German battery plants deploy TSN-enabled servo networks collapsing wiring complexity while enabling controller-agnostic sensor integration.
- Hybrid:Converged OT-IT architectures allow controller vendors to capture recurring software revenue through subscription-based runtime licensing.
- On-premises:Traditional control room installations persist in safety-critical applications requiring SIL-rated system design.
- Cloud-based:Centralized analytics and long-term data archiving support predictive maintenance algorithms.
Hybrid deployments are gaining share fastest. Edge computing anchors greenfield project specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing corridor concentrates the world's densest battery gigafactory construction, absorbing IP69K-rated proximity sensors and sub-millisecond PLCs at volumes unmatched elsewhere. Regulatory divergence across major economies is fragmenting certification requirements for multinational automation deployments.
China
Battery gigafactory construction in Jiangsu and Zhejiang provinces drives concentrated demand for precision motion components. MIIT mandates GB standard compliance for industrial control system cybersecurity, erecting market access barriers for uncertified foreign suppliers. The Yangtze River Delta corridor hosts the world's densest clustering of EV assembly automation procurement.
Germany
Automotive OEM retooling for electric vehicle platforms sustains demand for servo actuators with sub-micron repeatability. The F-Gas Regulation tightens refrigerant-based cooling standards through 2027, forcing retrofit procurement across Baden-Württemberg and Bavaria automotive plants. Stuttgart and Munich industrial zones anchor European precision motion component qualification.
United States
Process-industry accounts in the Gulf Coast deploy distributed control systems under EPA emissions tracking mandates. The Department of Energy enforces NEMA MG-1 motor efficiency standards through Table 12-12, shaping variable-frequency drive specifications. Houston and Baton Rouge chemical corridors sustain demand for SIL-rated safety systems.
South Korea
EV battery supply chains in Gyeonggi-do and Ulsan concentrate vendor qualification around cleanroom-certified precision motion manufacturers. KBA vehicle certification requirements extend to component traceability through sub-tier suppliers. The Seoul Capital Area anchors dual-source procurement strategies for rare-earth-dependent servo motors.
India
Production-linked incentives for advanced cell chemistry and electronics assembly create greenfield automation demand in Gujarat and Tamil Nadu. BIS certification requirements for industrial equipment extend sales cycles for imported components. The Ahmedabad and Chennai industrial corridors absorb edge-native controller deployments for latency-critical robotic coordination.
Automation Component Market Competitive Environment
Global majors compete with regional champions across certification regimes and integration architectures. The vendor base stratifies into three tiers: diversified industrial conglomerates with full-stack portfolios, specialized motion control houses with cleanroom manufacturing credentials, and emerging Asian fabricators competing on MEMS sensor volume. Consolidation pressure intensifies as automotive OEMs narrow vendor panels to dual-source strategies. Strategic moves center on conformity assessment bundling for EU AI Act compliance and captive rare earth magnet supply arrangements.
Among diversified industrial conglomerates, Emerson Electric Co., Siemens AG, and Rockwell Automation, Inc. occupy positions anchoring distinct geographic strongholds. Emerson exemplifies the process-industry account anchoring archetype across North American energy and chemical corridors. Siemens represents the integrated drive systems architecture dominance visible across European automotive OEM supply chains. Rockwell Automation sits within the edge-native controller specialization tier, competing on hybrid cloud deployment architectures for manufacturing accounts seeking OT-IT convergence.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Rockwell Automation, Inc. |
| ABB Ltd. |
| Siemens AG |
| Schneider Electric SE |
| Parker Hannifin Corporation |
| Mitsubishi Electric Corporation |
| Honeywell International Inc. |
| Nidec Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive rare earth magnet supply arrangements anchor both supply security and pricing power for high-torque servo motor producers. German automotive OEMs and South Korean battery manufacturers are underwriting in-country magnet processing partnerships to offset Chinese refining concentration, locking in cost visibility while competitors face spot market volatility.
Pricing Analysis
Input-cost pass-through from neodymium and dysprosium spot markets shapes servo actuator pricing tiers. Three-tier pricing structure across premium, standard, and economy levels separates cleanroom-certified sub-micron repeatability vendors from volume MEMS producers. Pricing pressure stems from Chinese MEMS fabrication scale-up compressing proximity sensor margins. Tier-one automotive suppliers show least price sensitivity for SIL-rated safety components, while packaging OEMs in Southern Europe resist premium cooling system retrofits.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese refining capacity for neodymium and dysprosium separation. Component sourcing draws from Germany for precision motion systems, China for MEMS sensors, and Japan for high-reliability controllers. Single-source vulnerability concentrates in magnet processing outside Asia. Distribution runs through qualified vendor panels with mutual manufacturing process equivalency certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. EV battery gigafactory construction is concentrating procurement around certified cleanroom manufacturers with sub-tier traceability documentation.
For Market Incumbents: Deepen captive rare earth magnet supply arrangements through offtake partnerships with Australian or Vietnamese mining ventures. Expand GB standard cybersecurity certification capabilities for MIIT compliance in China's Yangtze River Delta corridor. Lock in dual-source qualification status with German automotive OEMs before vendor panel consolidation completes. For New Entrants and Emerging Players: Mid-tier food processing OEMs in France and Italy represent underserved buyers for F-Gas-compliant cooling retrofits. Target this segment through bundled conformity assessment services for EU AI Act high-risk system classification. Lead with subscription-based runtime licensing models to capture recurring revenue without heavy upfront hardware investment. For Investors and Strategic Acquirers: Roll-up economics work for specialized motion control houses with cleanroom manufacturing credentials because automotive OEMs are narrowing vendor panels to dual-source strategies. Five-to-ten year viability favors targets with pre-certified low-global-warming-potential portfolios. Watch EU F-Gas Regulation enforcement intensity as inflection indicator for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive magnet sourcing insulates German servo motor producers from Chinese refining bottlenecks. |
| GB Standard Cybersecurity Certification Investment | MIIT compliance unlocks access to Yangtze River Delta battery gigafactory procurement channels. |
| Low-GWP Cooling Portfolio Pre-Certification | F-Gas Regulation alignment positions vendors for accelerated French and Italian food packaging retrofits. |
| TSN-Enabled Servo Network Deployment | Time-sensitive networking collapses wiring complexity at German greenfield battery plants. |
| Subscription Runtime Licensing Model Launch | Recurring revenue capture from hybrid cloud edge deployments displaces transactional hardware sales. |
Study Parameters
Bottom-up automotive and process-industry modeling reconciled against top-down component shipment tracking forms the analytical core. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and industrial control system integrators were validated against secondary sources including MIIT GB standard filings, EU F-Gas Regulation implementation guidance, EPA emissions tracking disclosures, and SEC 10-K segment reporting from diversified industrial conglomerates.
Historical trendline analysis across sensor, actuator, controller, and HMI category trajectories informed projection frameworks. Segmentation dimensions span component type, control architecture, industry application, and installation topology. CAGRs were derived from fitted growth curves adjusted for regulatory phase-in schedules and technology substitution patterns. Forecast inputs incorporate EV production ramp assumptions and F-Gas retrofit compliance deadlines.
Underlying measurement precision varies by segment; edge computing and hybrid cloud deployments carry tighter precision than legacy on-premises installations. Forecasts reflect documented assumptions regarding rare earth supply continuity and certification regime stability. A small set of triggers—including MIIT enforcement intensity, EU AI Act conformity assessment timeline, and Yangtze River Delta gigafactory construction pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Audio Transistors Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
Film Capacitor Market
Electronic Components
Acoustic Diaphragm Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
Ceiling Microphone Market
Electronic Components
USB Retimer Market
Electronic Components
Audio DSP Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
Display Port Adapters Market
Electronic Components
Global Capacitor Market
Electronic Components
RAID Controller Card Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market