
 High-Performance IMU Market | 2026-2036
High-Performance IMU Market Size, Share, and Industry Trends Forecast 2026-2036
High-Performance IMU Market Foresight
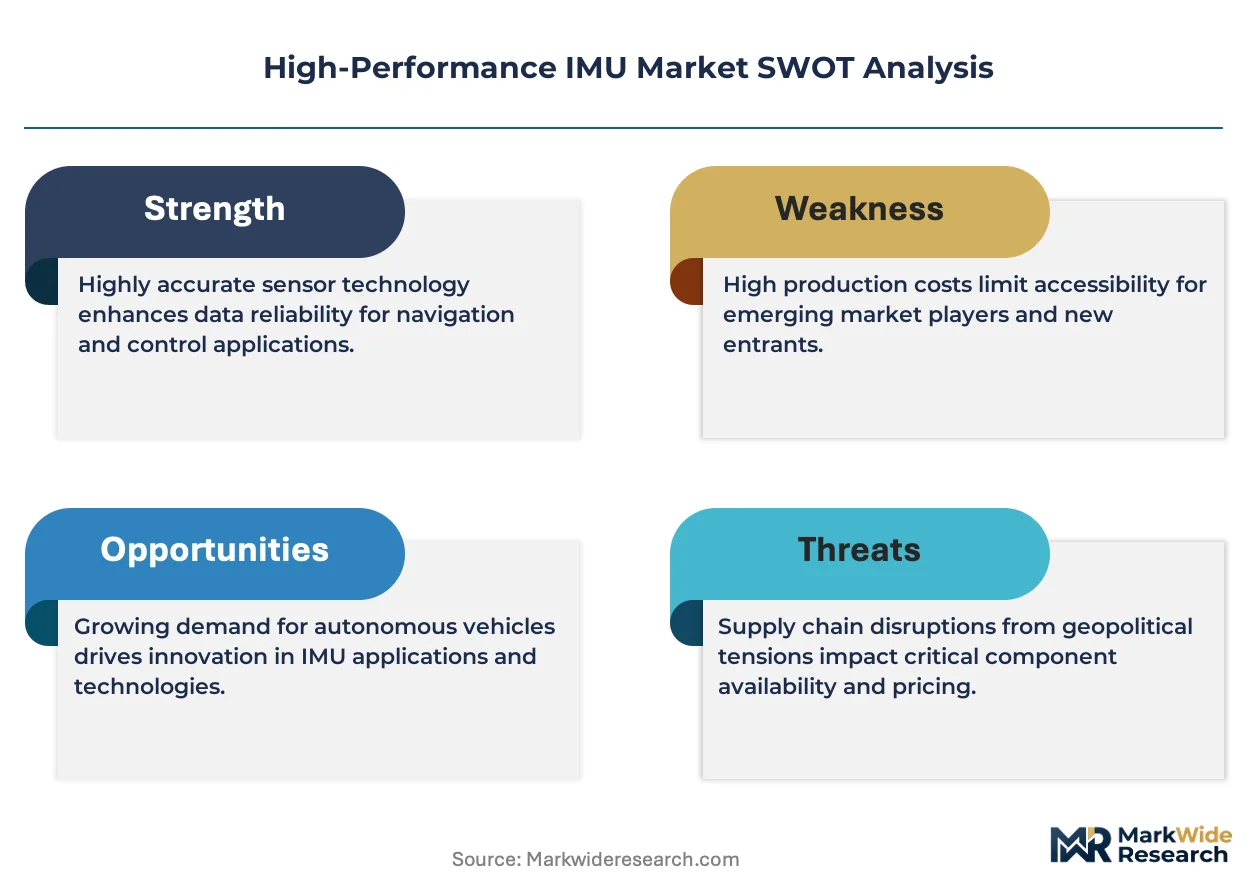
REACH substance restrictions and EU AI Act conformity requirements are broadening the cost-of-entry calculus for European IMU suppliers. Honeywell International leverages its captive MEMS foundry to sustain dual-use aerospace and defense output. Northrop Grumman anchors classified navigation programs with radiation-hardened fiber-optic designs. Safran competes across the full performance spectrum from tactical to navigation-grade units.
High-performance inertial measurement units combine accelerometers and gyroscopes in multi-axis configurations to output position, velocity, and attitude data with drift rates below 0.01 degrees per hour in navigation-grade variants. These systems enable dead-reckoning navigation where GPS denial or jamming compromises satellite-dependent positioning. Fiber optic gyroscope technology leads in maritime and strategic aerospace applications due to immunity to electromagnetic interference and absence of moving parts. MEMS-based IMUs represent the fastest-expanding segment as automotive and robotics buyers trade absolute precision for cost-scalable volume production. Sensor fusion architectures integrating inertial data with GNSS corrections now command premium positioning across autonomous platforms.
FAA certification standards for commercial aviation equipment and DoD MIL-STD-810 environmental testing requirements shape product development timelines and qualification costs for suppliers targeting North American defense and aerospace procurement channels. EASA's continuing airworthiness directives and EU MDR traceability mandates add parallel compliance layers for European market access. Stakeholders must monitor evolving export control classifications under Wassenaar Arrangement updates that could restrict fiber-optic gyroscope technology transfers to specific end-user jurisdictions.
Market Dynamics
MEMS process maturity is compressing cost curves for tactical-grade units while fiber-optic gyroscope suppliers defend navigation-grade premiums through radiation-hardening and strategic aerospace qualification. Dual-use export controls under the Wassenaar Arrangement are fragmenting supplier access to Chinese and Russian end-users.
Growth Catalysts
- Autonomous vehicle navigation mandates:Germany's KBA, Japan's MLIT, and NHTSA in the United States are accelerating procurement of tactical-grade inertial units for redundancy in GPS-denied environments.
- REACH substance restrictions:ECHA enforcement is filtering supplier bases toward vendors with certified clean-room fabrication capabilities in aerospace corridors around Toulouse.
- Sensor fusion architectures:Integration of inertial data with GNSS corrections now commands premium positioning across robotics manufacturing zones in Shenzhen.
Market Restraints
- Clean-room fabrication capex:Navigation-grade MEMS production requires Class 10 or better facilities, concentrating supply among foundry operators with captive aerospace qualification.
- Fiber-optic gyroscope input cost volatility:Polarization-maintaining fiber and specialty light sources face single-source dependency on Japanese and German optical component suppliers.
- Dual-use export friction:Wassenaar Arrangement updates restrict fiber-optic gyroscope technology transfers to specific end-user jurisdictions, compressing addressable market for strategic-grade suppliers.
Strategic Opportunities
- Maritime autonomous surface vessels:Uncrewed cargo and survey platforms in Norwegian and Singaporean waters create demand for EMI-immune fiber-optic units without GPS dependency.
- EU AI Act conformity tailwinds:High-risk system documentation requirements favor IMU suppliers with pre-existing aerospace certification and traceable supply chains.
- Quantum inertial convergence:Cold-atom interferometry paired with conventional IMU architectures promises navigation-grade performance without mechanical complexity, attracting defense research funding.
Industry Challenges
- Radiation-hardening engineering scarcity:Qualified designers for space-grade fiber-optic gyroscopes concentrate among legacy aerospace primes, constraining new entrant scale.
- Multi-standard certification timelines:Simultaneous FAA, EASA, and MIL-STD-810 qualification extends product development cycles and locks working capital in pre-revenue inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Performance IMU Market |
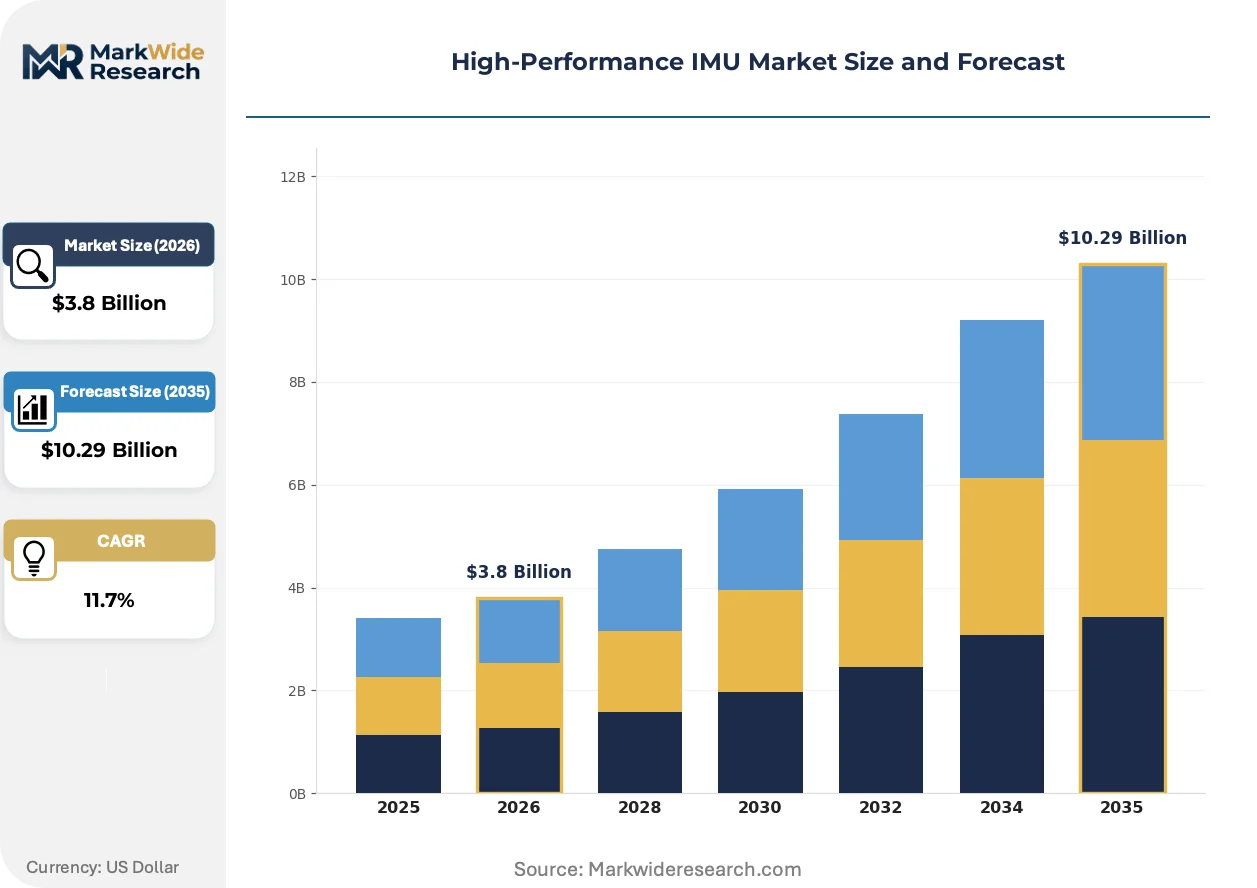
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microelectromechanical System, Fiber Optic, Ring Laser, Mechanical Gyroscopes End User: Aerospace, Defense, Robotics, Automotive Technology: Inertial Navigation, GPS-Aided Navigation, Attitude Heading Reference Systems, Sensor Fusion Application: Navigation Systems, Stabilization, Motion Tracking, Control Systems |
| Companies Covered | Honeywell International, Northrop Grumman, Safran, Thales Group, Bosch Sensortec, Analog Devices, STMicroelectronics, Collins Aerospace, KVH Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Performance IMU Market Shifts & Advancements
Silicon photonics is reshaping inertial sensor economics by enabling wafer-scale integration of optical gyroscope components. Three converging developments are compressing traditional technology boundaries and redrawing competitive maps.
Silicon photonics ring resonator gyroscopes is consolidating process economics for optical inertial sensing by leveraging CMOS-compatible foundries. Automotive LiDAR suppliers in Germany and the United States are repurposing existing photonics capacity for tactical-grade IMU production. This technology is consolidating the cost gap between MEMS and fiber-optic performance tiers, forcing navigation-grade incumbents to defend through radiation tolerance and strategic qualification moats.
EU AI Act high-risk system documentation requirements are mandating algorithmic transparency and training data provenance for autonomous navigation platforms. Industrial consequence includes mandatory third-party conformity assessment for IMU-integrated perception systems in commercial aviation and urban air mobility. European aerospace suppliers in Toulouse and Munich are responding by pre-certifying sensor fusion stacks to MDR traceability standards, compressing customer integration timelines.
Long-term performance-based service contracts are displacing unit-sales procurement in satellite constellation operators. Fleet managers at communications and Earth-observation ventures are unbundling sensor hardware from guaranteed availability commitments. This shift is most visible in California and Luxembourg, where venture-backed space operators prioritize capital efficiency over asset ownership, pressuring traditional aerospace suppliers to build recurring revenue capabilities.
High-Performance IMU Market Segmentation
High-performance IMU procurement splits across performance tiers, end-use environments, and integration architectures. Buyers trade absolute precision against unit economics, volume scalability, and certification burden depending on mission criticality.
Product Type:
Supply concentration clusters around MEMS foundries with captive aerospace qualification and fiber-optic gyroscope specialists with radiation-hardening legacy.
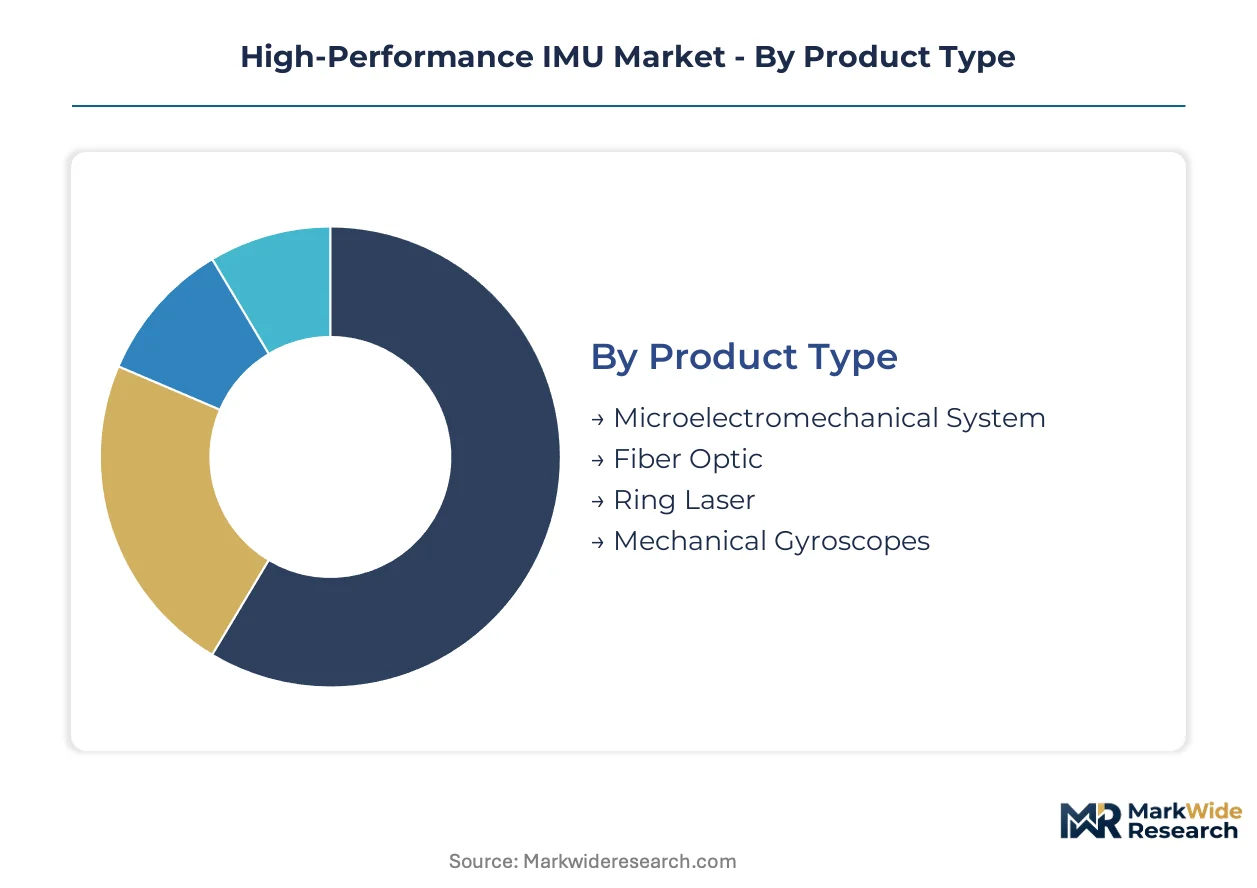
- Microelectromechanical System:Silicon-based accelerometers and gyroscopes fabricated through CMOS-compatible processes. Automotive programs in Germany and robotics manufacturers in Shenzhen are absorbing volume output for tactical-grade redundancy systems.
- Fiber Optic:Sagnac-effect gyroscopes using polarization-maintaining fiber coils. Maritime autonomous vessels in Norwegian waters and strategic aerospace platforms favor these units for electromagnetic immunity and absence of moving parts.
- Ring Laser:Helium-neon gas lasers in triangular resonant cavities delivering navigation-grade stability. Legacy deployment concentrates in submarine navigation and strategic missile guidance where maintenance access is limited.
- Mechanical Gyroscopes:Spinning mass designs with gimbal-mounted rotors. Niche retention in certain defense platforms persists where existing qualification chains resist technology substitution.
Fiber Optic absorbs the bulk of installed capacity in navigation-grade applications; Microelectromechanical System is expanding most quickly through automotive and robotics procurement.
End User:
Customer procurement patterns diverge sharply between regulated aerospace channels and volume-driven automotive programs.
- Aerospace:Commercial aviation and satellite operators demanding FAA and EASA certification with traceable supply chains. Toulouse and Munich clusters are consolidating procurement around pre-certified sensor fusion stacks.
- Defense:Classified navigation programs requiring radiation-hardened designs and Wassenaar-compliant export controls. Fiber-optic units dominate strategic applications.
- Robotics:Industrial automation and humanoid platforms in Shenzhen's manufacturing zone. MEMS-based units with sensor fusion architectures command premium positioning.
- Automotive:Autonomous vehicle mandates from Germany's KBA, Japan's MLIT, and NHTSA are accelerating tactical-grade procurement for GPS-denied redundancy.
Aerospace absorbs the bulk of installed capacity; Automotive is climbing the fastest through regulatory mandate acceleration.
Technology:
Integration architectures determine pricing power and customer switching costs across end-use segments.
- Inertial Navigation:Standalone dead-reckoning systems outputting position, velocity, and attitude without external references. Submarine and strategic aerospace platforms rely on these for GPS-denied environments.
- GPS-Aided Navigation:Tightly coupled inertial-GNSS integration correcting drift through satellite measurements. Commercial aviation and autonomous surface vessels favor this architecture.
- Attitude Heading Reference Systems:Simplified gyrocompassing for platform stabilization without full position fixing. Helicopter and urban air mobility applications concentrate demand.
- Sensor Fusion:Multi-sensor integration with algorithmic weighting across inertial, GNSS, and vision inputs. EU AI Act conformity requirements are mandating third-party assessment for these systems in high-risk applications.
Inertial Navigation absorbs the bulk of installed capacity in defense applications; Sensor Fusion is gaining share fastest through autonomous platform proliferation.
Application:
Functional use cases map directly to performance tier requirements and certification burdens.
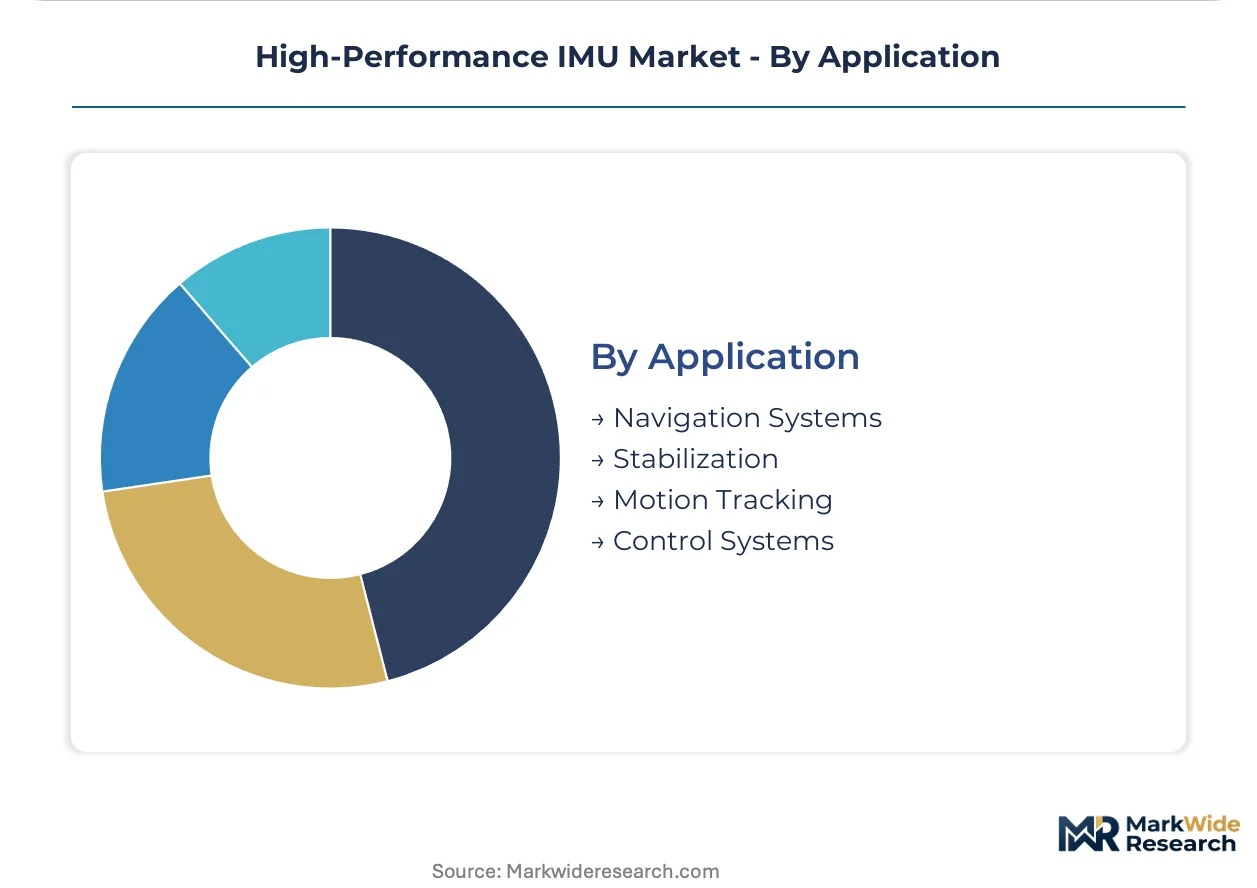
- Navigation Systems:Full position-velocity-attitude determination for mission-critical routing. Fiber-optic and ring-laser units dominate where GPS denial is probable.
- Stabilization:Platform leveling and vibration isolation for imaging and communication payloads. Satellite constellations and maritime radar platforms concentrate procurement.
- Motion Tracking:High-bandwidth acceleration and rotation measurement for biomechanical and industrial analysis. Robotics and virtual reality hardware favor MEMS implementations.
- Control Systems:Closed-loop feedback for vehicle dynamics and platform maneuvering. Automotive and aerospace flight control systems split demand between tactical and navigation grades.
Navigation Systems absorbs the bulk of installed capacity; Motion Tracking is expanding most quickly through robotics and immersive technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Free Trade Zone tax incentives are concentrating MEMS packaging capacity for robotics OEMs. Germany's high-tech manufacturing grants and Japan's MLIT certification streams are anchoring tactical-grade production clusters across three continents.
United States
NHTSA autonomous vehicle mandates and DoD navigation programs absorb fiber-optic and MEMS output from defense primes. FAA certification requirements for commercial aviation equipment shape product development timelines for suppliers targeting North American aerospace procurement. California's venture-backed space operators in Hawthorne and San Francisco are unbundling sensor hardware from availability commitments.
Germany
KBA regulations for autonomous vehicle redundancy systems are accelerating tactical-grade IMU procurement from automotive tier-ones. REACH substance restrictions enforced by ECHA are filtering supplier bases toward vendors with certified clean-room fabrication. Munich's aerospace cluster is pre-certifying sensor fusion stacks to MDR traceability standards.
Japan
MLIT navigation mandates for autonomous platforms are driving demand for EMI-immune fiber-optic units. METI industrial technology grants support domestic MEMS foundry expansion for robotics applications. Nagoya's automotive engineering corridor houses precision component suppliers serving both domestic and export markets.
China
MIIT smart manufacturing initiatives and dual carbon goals are channeling investment into domestic MEMS fabrication for industrial automation. GB standards compliance requirements shape local procurement specifications for navigation-grade systems. Shenzhen's robotics manufacturing zone concentrates demand for cost-scalable tactical-grade units with sensor fusion architectures.
France
EASA continuing airworthiness directives and EU AI Act conformity requirements add parallel compliance layers for European market access. ECHA enforcement of REACH substance restrictions favors vendors with traceable aerospace supply chains. Toulouse's satellite cluster anchors procurement of navigation-grade fiber-optic units for commercial aviation and space applications.
High-Performance IMU Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across performance tiers and certification regimes. The market structure concentrates around MEMS foundries with captive aerospace qualification and fiber-optic gyroscope specialists with radiation-hardening legacy. Three archetypes dominate: integrated defense primes with dual-use portfolios, automotive-tier sensor suppliers scaling through CMOS-compatible processes, and boutique navigation houses defending premium positioning through strategic qualification. Competitive moves center on backward integration into specialty optical components and pre-certification of sensor fusion stacks to compress customer integration timelines.
Within the defense-prime tier, Honeywell International exemplifies the integrated conglomerate archetype through its captive MEMS foundry sustaining dual-use output. Northrop Grumman occupies a position among classified navigation program suppliers with radiation-hardened fiber-optic specialization. Safran represents the European diversified competitor spanning tactical to navigation-grade performance tiers across aerospace and defense channels.
| Leading Market Players |
|---|
| Honeywell International |
| Northrop Grumman |
| Safran |
| Thales Group |
| Bosch Sensortec |
| Analog Devices |
| STMicroelectronics |
| Collins Aerospace |
| KVH Industries |
| Others |
Supply & Pricing Matrix
Navigation-grade and tactical-grade performance divergence manifests in dual supply chain configurations: fiber-optic specialists command premium positioning through radiation-hardening qualification moats while MEMS foundries compete on CMOS-compatible volume economics. This bifurcation concentrates pricing power among Japanese polarization-maintaining fiber suppliers and German clean-room operators while compressing margins for commodity tactical-grade producers in Shenzhen.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with navigation-grade fiber-optic units carrying 40-60% premiums for sub-16-week delivery against standard 28-week cycles. Three-tier pricing structure across navigation, tactical, and industrial grades tracks certification burden and volume scale. Cost compression in tactical-grade MEMS intensifies because automotive buyers in Germany and Japan consolidate procurement around multi-year offtake agreements. Robotics OEMs in Shenzhen exhibit highest price sensitivity, while satellite constellation operators in California and Luxembourg prioritize guaranteed availability over unit cost.
Supply Chain Analysis
Polarization-maintaining fiber supply rests on Japanese specialty optical component producers, with German and US suppliers holding secondary positions. Silicon wafer feedstock draws from Taiwan and South Korea, while MEMS packaging capacity concentrates in China's Qianhai Free Trade Zone and Malaysia. Single-source vulnerability in specialty light sources creates procurement risk for fiber-optic gyroscope assemblers. Distribution runs through defense prime direct channels for navigation-grade units and electronics distribution networks for tactical-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races are reshaping competitive positioning across performance tiers, with backward integration into specialty optical components and captive MEMS foundry capacity emerging as decisive levers for margin defense and supply security.
For Market Incumbents: Anticipate silicon photonics disruption by securing exclusive access to CMOS-compatible foundry slots in Taiwan and Germany. Lock in multi-year polarization-maintaining fiber supply agreements with Japanese suppliers before capacity constraints harden. Prioritize radiation-hardening qualification moats against emerging cold-atom interferometry substitutes. For New Entrants and Emerging Players: Capture maritime autonomous surface vessel demand in Norwegian and Singaporean waters where EMI-immune fiber-optic requirements exclude MEMS alternatives. Target sensor fusion software layers for EU AI Act pre-certification, leveraging algorithmic transparency mandates as entry barriers against hardware-centric incumbents. Pursue white-label partnerships with automotive tier-ones seeking second-source tactical-grade redundancy. For Investors and Strategic Acquirers: Re-rating potential sits with silicon photonics specialists given automotive LiDAR capacity repurposing for tactical-grade IMU production. Long-term viability favors archetypes with dual-use aerospace qualification and recurring revenue service contracts. Watch Wassenaar Arrangement update cadence as inflection indicator for strategic-grade supplier addressable market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Investment | Secures CMOS-compatible capacity for tactical-grade volume against automotive demand surges in Germany. |
| Specialty Optical Component Backward Integration | Reduces single-source dependency on Japanese polarization-maintaining fiber suppliers for navigation-grade units. |
| EU AI Act Pre-Certification | Compresses customer integration timelines for sensor fusion stacks in Toulouse and Munich aerospace corridors. |
| Performance-Based Service Contract Transition | Aligns revenue model with California and Luxembourg satellite operators prioritizing capital efficiency. |
| Cold-Atom Interferometry R&D Partnership | Positions for navigation-grade performance without mechanical complexity as defense research funding accelerates. |
Research Methodology
Independent corroboration across defense procurement officers, MEMS foundry operations directors, and satellite constellation supply chain managers underwrites the qualitative findings. Primary fieldwork encompassed aerospace certification engineers at EASA-notified bodies, automotive tier-one sensor procurement leads in Germany and Japan, and robotics OEM technical directors in Shenzhen. Secondary validation drew from FAA certification databases, ECHA REACH substance restriction enforcement records, Wassenaar Arrangement dual-use control updates, and customs trade data for polarization-maintaining fiber imports. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Rate-of-change decomposition structured the analytical framework across the projection horizon, modeling volume and value trajectories by performance tier, end-use environment, and integration architecture. Segmentation dimensions encompassed product type, end user, technology layer, and application function. CAGRs derived from regression analysis against autonomous vehicle regulatory mandate acceleration, satellite constellation deployment schedules, and robotics manufacturing capacity expansion. Industry-specific inputs included clean-room fabrication capex cycles, radiation-hardening qualification timelines, and sensor fusion algorithm development trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Wassenaar Arrangement export control revisions, silicon photonics process yield breakthroughs, and cold-atom interferometry technology maturation. Forecasts reflect documented assumptions regarding regulatory mandate enforcement cadence, foundry capacity expansion schedules, and defense research funding continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Chest Sensors Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Digital Barometer Market