
 Chip Ferrite Beads Market | 2026-2036
Chip Ferrite Beads Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Ferrite Beads Market Outlook
Software-defined impedance tuning is expanding what OEMs purchase beyond passive hardware. TDK Corporation leverages its materials science heritage to dominate high-frequency ferrite formulations. Murata Manufacturing anchors production scale across multi-layer chip bead architectures. Samsung Electro-Mechanics competes through captive demand from its parent's device ecosystem.
Chip ferrite beads are sintered ceramic components composed of nickel-zinc or manganese-zinc ferrite, manufactured through tape casting and firing processes to achieve precise impedance characteristics across megahertz to gigahertz frequencies. They suppress conducted electromagnetic interference in power and signal lines. Common mode chokes lead unit volume as differential signaling proliferates in computing interfaces. Noise suppression applications capture the widest margin pool where automotive qualification tiers command premium pricing. Power management use cases sustain faster growth as DC-DC converter density rises in compact electronics.
FCC Part 15 emissions rules in the United States, EU CE marking under the EMC Directive, and China's GB/T 9254 standard collectively elevate compliance costs for unqualified suppliers. Japan's VCCI self-regulatory framework adds voluntary certification layers that tier-one OEMs treat as mandatory. Stakeholders must monitor how automotive EMC testing protocols evolve alongside 800V EV architectures.
Market Dynamics
EV powertrain voltage escalation to 800V architectures is forcing wholesale redesign of noise suppression component specifications across automotive supply chains.
Growth Catalysts
- Automotive electrification:Battery management systems and onboard chargers in electric vehicles require dense ferrite bead arrays to manage switching noise from high-frequency DC-DC converters.
- MIIT EMC tightening:China's Ministry of Industry and Information Technology is enforcing stricter electromagnetic compatibility testing protocols, compelling domestic electronics manufacturers to upgrade filtering components.
- Multi-layer architecture proliferation:Computing interfaces adopting differential signaling standards are driving unit volume expansion for common mode choke configurations in data center and consumer electronics applications.
Market Restraints
- Raw material concentration:High-purity nickel oxide and manganese carbonate supply chains concentrate in southern African mining operations, exposing ferrite manufacturers to geopolitical disruption risk.
- Sintering energy intensity:Tape casting and high-temperature firing processes consume substantial natural gas and electricity, with European producers facing acute cost pressure from F-Gas Regulation compliance.
- Thin-film substitute emergence:Integrated passive device technologies are capturing frequency bands below 100 MHz in premium smartphone RF front-ends, compressing addressable market for discrete chip beads.
Strategic Opportunities
- Indian electronics manufacturing:Production-linked incentive schemes for semiconductor and component assembly are attracting ferrite bead suppliers to establish localized sintering capacity near Chennai and Bengaluru clusters.
- Software-defined impedance tuning:Active impedance matching circuits are converging with traditional passive bead architectures, creating hybrid product categories that command margin premiums in aerospace and medical imaging equipment.
- EU Green Deal alignment:REACH-compliant nickel-zinc formulations without hexavalent chromium passivation are qualifying for preferential procurement in European automotive tier-one supplier frameworks.
Industry Challenges
- Automotive qualification timelines:AEC-Q200 stress testing protocols demand 1,000-hour thermal cycling validation, extending new product introduction cycles to 18-24 months and freezing engineering resources.
- Legacy equipment integration:Retrofitting ferrite bead specifications into existing power supply designs requires board layout redesigns that conflict with established safety certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Ferrite Beads Market |
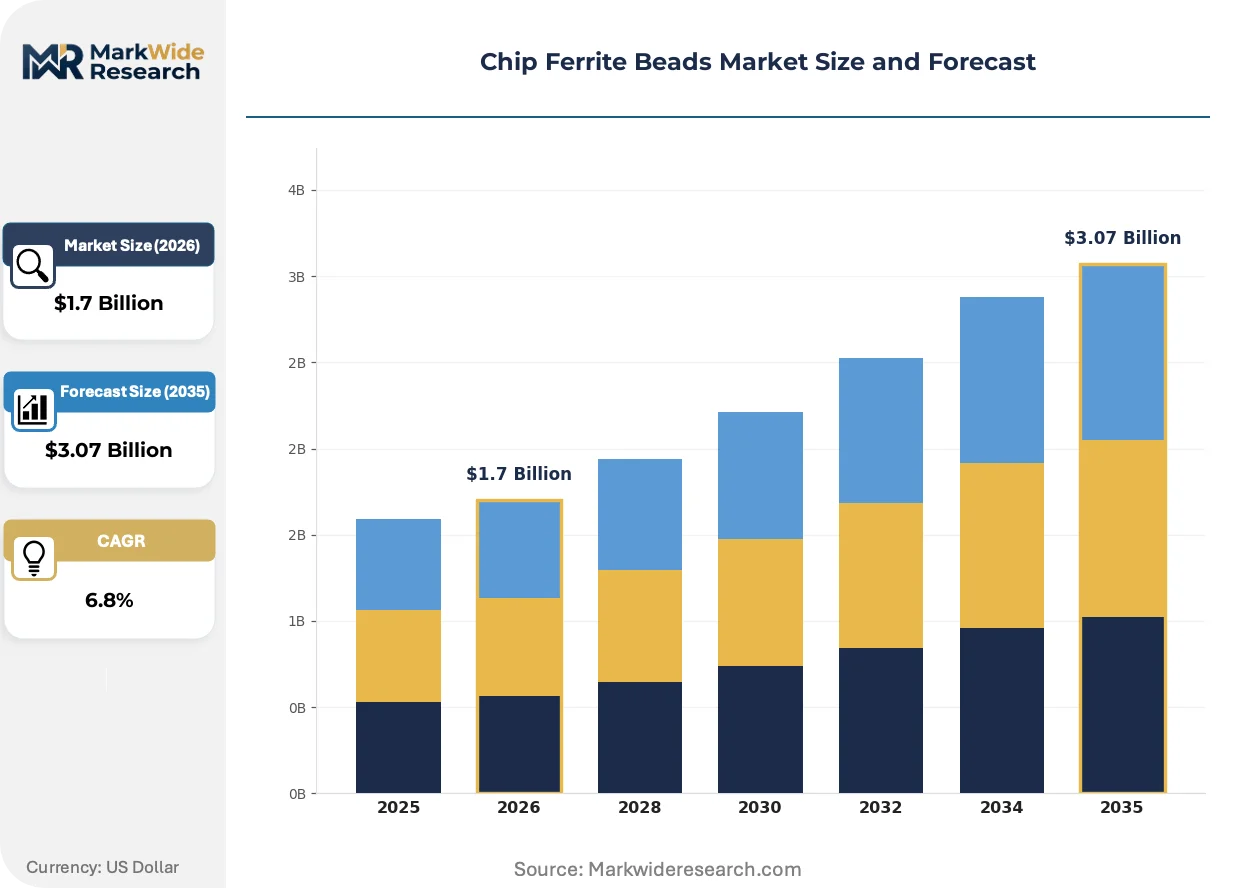
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chip Ferrite Beads, Common Mode Chokes, Differential Mode Chokes, Power Inductors Application: Consumer Electronics, Automotive Electronics, Industrial Equipment, Telecommunication Devices Use Case: Noise Suppression, Signal Filtering, Energy Storage, Power Management End User: OEMs, Electronics Manufacturers, Telecom Providers, IT Companies |
| Companies Covered | TDK Corporation, Murata Manufacturing, TAIYO YUDEN, Sunlord, Yageo, Samsung Electro-Mechanics, Vishay, Bourns, Würth Elektronik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Ferrite Beads Market Strategic Shifts
Materials science breakthroughs in ferrite composition and manufacturing process control are compressing impedance tolerance bands while expanding operational temperature ranges.
Nickel-zinc ferrite formulations with sub-micron grain structures are converging with additive manufacturing techniques for prototype validation. Aerospace subsystem suppliers are adopting these materials for satellite power conditioning units where thermal cycling extremes exceed terrestrial specifications. This convergence is enabling faster iteration cycles that compress traditional 24-month qualification timelines.
China's GB/T 9254 electromagnetic compatibility standard is tightening radiated emission limits for information technology equipment. Domestic OEMs are responding by specifying higher impedance-rated chip beads in HDMI and USB-C interface circuits. The regulatory friction is accelerating substitution of lower-performance manganese-zinc variants in coastal manufacturing facilities.
Consolidated procurement through electronic component distributors is displacing direct manufacturer relationships for mid-volume buyers. Tier-two automotive suppliers and industrial equipment manufacturers are migrating to Arrow and Avnet consolidated platforms that bundle ferrite beads with passive component kits. This channel shift concentrates price negotiation leverage in North American and European distribution hubs.
Chip Ferrite Beads Market Segmentation
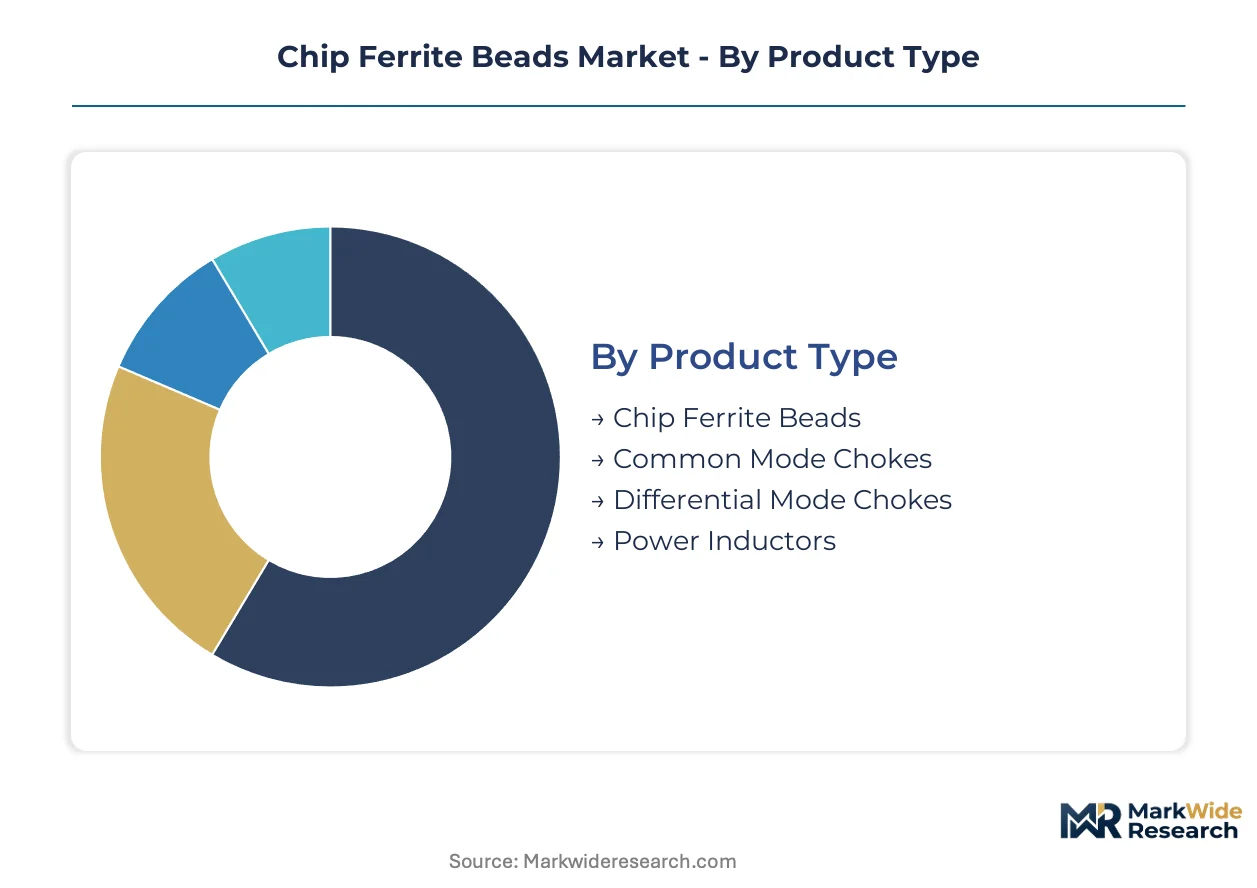
Component architecture and application voltage requirements determine ferrite bead specification hierarchies. Impedance tolerance bands, temperature coefficients, and automotive qualification tiers create distinct procurement categories that shape supplier margins and customer switching costs.
Product Type:
Magnetic core geometry and winding configuration define performance boundaries across frequency domains.
- Chip Ferrite Beads:Sintered nickel-zinc or manganese-zinc ceramic cores with monolithic construction achieve impedance values from tens to thousands of ohms across megahertz ranges. Surface-mount packaging dominates smartphone and tablet PC board assemblies in Shenzhen and Dongguan manufacturing corridors.
- Common Mode Chokes:Dual-winding toroidal configurations suppress electromagnetic interference in differential signaling interfaces. Data center server backplanes and USB-C port implementations in Taiwan ODM facilities drive volume concentration.
- Differential Mode Chokes:Single-wound inductors address asymmetric noise propagation in power line applications. Industrial motor drives and robotics controllers specify these for conducted emission compliance under EU CE marking directives.
- Power Inductors:Gapped ferrite cores with heavy-gauge wire windings store magnetic energy in DC-DC converter stages. Onboard charger modules in 800V EV architectures require thermally rated variants qualified to AEC-Q200 standards.
Chip ferrite beads lead on scale; common mode chokes lead on momentum.
Application:
Voltage escalation and interface density create divergent specification requirements across end-use sectors.
- Automotive Electronics:Battery management systems and inverter gate drives demand ferrite components with extended temperature ranges and vibration resistance. MIIT EMC tightening in China compels domestic EV manufacturers to upgrade filtering specifications for GB/T 9254 compliance.
- Consumer Electronics:Smartphones, tablets, and wearables prioritize miniaturized multilayer chip beads with tight impedance tolerances. Samsung Electro-Mechanics and Murata Manufacturing anchor supply relationships with flagship device assemblers in South Korea and Japan.
- Telecommunication Devices:5G base station power amplifiers and optical transceivers require low-DC-resistance beads for high-current RF paths. Ericsson and Nokia procurement frameworks specify these for European network deployments.
- Industrial Equipment:Programmable logic controllers and variable frequency drives specify robust through-hole chokes for factory floor electromagnetic environments. German automation OEMs source REACH-compliant formulations under EU Green Deal procurement guidelines.
Automotive electronics expands most quickly; consumer electronics retains volume dominance.
Use Case:
Functional deployment determines impedance curve shaping and thermal budget allocation.
- Noise Suppression:Broadband ferrite beads attenuate high-frequency conducted interference in clock lines and power rails. FCC Part 15 emissions testing in the United States elevates specification priority for computing peripheral manufacturers.
- Power Management:Low-ESL chip beads stabilize DC-DC converter output in compact multiphase architectures. Notebook PC and graphics card designs concentrate demand in Taoyuan City manufacturing clusters.
- Signal Filtering:Impedance-matched beads preserve signal integrity in high-speed differential pairs. HDMI and DisplayPort interface circuits specify these for eye diagram compliance.
- Energy Storage:Power inductors buffer transient currents in switching regulator stages. Telecom infrastructure power supplies specify these for hold-up time requirements.
Noise suppression commands premium pricing tiers; power management sustains steepest expansion trajectory.
End User:
Procurement sophistication and qualification burden stratify customer relationships.
- OEMs:Tier-one automotive and consumer device brands impose AEC-Q200 and custom reliability testing protocols. Direct engineering engagement with TDK Corporation and Yageo Corporation secures roadmap alignment.
- Electronics Manufacturers:Contract assemblers and EMS providers purchase through Arrow and Avnet distribution platforms for kit consolidation. Mid-volume buyers prioritize inventory flexibility over manufacturer-direct pricing.
- Telecom Providers:Network equipment vendors specify ferrite components for base station and router platforms. NTT and Deutsche Telekom procurement frameworks emphasize lifecycle stability.
- IT Companies:Hyperscale data center operators source power inductors for server and storage power delivery. Google and Microsoft sustainability mandates drive REACH-compliant nickel-zinc formulation preference.
OEMs anchor high-margin qualification tiers; electronics manufacturers concentrate unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping ferrite bead manufacturing geography as producers migrate toward jurisdictions with lower compliance costs and concentrated raw material access. Cost-of-compliance gaps between European F-Gas Regulation burdens and Asian industrial policy incentives are accelerating capacity relocation decisions.
China
MIIT's tightening GB/T 9254 electromagnetic compatibility standards are compelling domestic EV manufacturers to upgrade noise suppression specifications. The Ministry of Industry and Information Technology enforcement protocols now mandate stricter radiated emission testing for information technology equipment. Coastal manufacturing clusters in Shenzhen and Dongguan are absorbing expanded ferrite bead demand from smartphone and tablet PC assemblers.
Japan
VCCI self-regulatory framework certification layers are treated as mandatory by tier-one automotive OEMs sourcing components for hybrid powertrains. METI industrial policy supports advanced materials science research in nickel-zinc ferrite formulations. Kanto region manufacturing facilities around Tokyo anchor high-frequency component production for 5G base station exports.
South Korea
Captive demand from Samsung's device ecosystem concentrates ferrite bead procurement through vertically integrated electro-mechanics divisions. MFDS regulatory alignment with international EMC standards facilitates component exports to European automotive tier-ones. Seoul Capital Area manufacturing corridors supply multilayer chip bead architectures for flagship smartphone launches.
Germany
EU Green Deal procurement guidelines prioritize REACH-compliant nickel-zinc formulations without hexavalent chromium passivation. KBA automotive certification protocols extend AEC-Q200 validation requirements across European supply chains. Bavarian industrial automation OEMs specify robust through-hole chokes for factory floor electromagnetic environments under CE marking directives.
United States
FCC Part 15 emissions rules elevate specification priority for computing peripheral manufacturers targeting domestic retail channels. NHTSA automotive safety standards intersect with EMC testing protocols for advanced driver-assistance system electronics. Texas and Arizona semiconductor packaging clusters are attracting ferrite bead distributors for consolidated procurement through Arrow and Avnet platforms.
Chip Ferrite Beads Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement through distributors displacing direct relationships for mid-volume buyers. The vendor base stratifies into three tiers: integrated materials-science conglomerates controlling ferrite formulations, scale-focused multi-layer architecture producers, and regional specialists serving automotive qualification niches. Dominant competitive moves include backward integration into high-purity nickel oxide sourcing and geographic expansion toward Indian electronics manufacturing clusters under PLI schemes.
Within the materials-science conglomerate tier, TDK Corporation and Murata Manufacturing exemplify players leveraging multi-decade ferrite formulation heritage. Samsung Electro-Mechanics occupies a distinct position through captive demand integration from its parent's device ecosystem. These three anchors represent divergent strategic archetypes: formulation dominance, production scale, and vertical demand capture.
| Leading Market Players |
|---|
| TDK Corporation |
| Murata Manufacturing |
| TAIYO YUDEN |
| Sunlord |
| Yageo |
| Samsung Electro-Mechanics |
| Vishay |
| Bourns |
| Würth Elektronik |
| Others |
Value Chain & Pricing Dynamics
Specialized sintering technicians in Japan's Kanto region anchor premium-tier pricing, with labor-cost differentials between Tokyo-adjacent facilities and emerging Indian sintering clusters widening spreads between AEC-Q200 qualified and standard-grade chip ferrite beads. European F-Gas Regulation compliance burdens on high-temperature firing processes amplify these tier distinctions, forcing buyers to trade off qualification depth against unit economics.
Pricing Analysis
Capacity additions in India under PLI schemes are reshaping price floors for standard-grade multilayer chip beads. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-tier products stratifies procurement, with AEC-Q200 certification and REACH-compliant nickel-zinc formulations commanding substantial premiums over manganese-zinc variants. Cost compression in consumer-tier segments intensifies as Sunlord and domestic Chinese suppliers expand tape-casting capacity. Contract electronics manufacturers through Arrow and Avnet platforms exhibit highest price sensitivity; tier-one automotive OEMs direct-engineering TDK and Murata show lowest.
Supply Chain Analysis
AEC-Q200 qualification gating restricts qualified supplier pools to Japanese and South Korean conglomerates with multi-decade formulation archives. Raw material supply concentrates in China, Japan, and South Korea for ferrite precursor chemicals, with high-purity nickel oxide and manganese carbonate drawing from southern African mining operations. Single-source vulnerability runs through concentrated nickel oxide refining. Distribution runs through Arrow, Avnet, and regional electronics distributors consolidating passive component kits for mid-volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through automotive electrification premium-tier shifts and sintering automation cost-downs in emerging manufacturing clusters.
For Market Incumbents: Cement formulation dominance by deepening captive supply of high-purity nickel oxide against thin-film integrated passive device substitution threats. Extend AEC-Q200 qualification pipelines to lock in 800V EV architecture redesign cycles. Prioritize sintering automation investments in Tamil Nadu PLI corridors to compress labor-cost differentials versus Japanese Kanto facilities. For New Entrants and Emerging Players: Software-defined impedance tuning architectures offer entry wedges into aerospace and medical imaging equipment where hybrid active-passive configurations command premium positioning. Target Indian electronics manufacturing clusters near Bengaluru for localized sintering partnerships with PLI-qualified contract assemblers. Lead with rapid-prototype additive manufacturing capabilities to compress traditional 24-month automotive qualification timelines. For Investors and Strategic Acquirers: Automotive tier-one suppliers are the most active acquirer in this space, seeking ferrite formulation capabilities to secure 800V EV noise suppression component supply. Five-to-ten year viability hinges on qualification moat sustainability rather than commodity scale. Watch MIIT GB/T 9254 enforcement intensity as inflection indicator for domestic Chinese supplier consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Oxide Refining | Secures precursor supply against southern African geopolitical disruption risk for Japanese formulators. |
| AEC-Q200 Qualification Pipeline Expansion | Captures 800V EV architecture redesign cycles with 18-24 month customer lock-in periods. |
| PLI-Aligned Sintering Capacity in India | Positions cost-competitive supply near Chennai and Bengaluru electronics manufacturing clusters. |
| Software-Defined Impedance Hybrid Development | Opens aerospace and medical imaging premium tiers beyond commodity bead competition. |
| REACH-Compliant Formulation Certification | Qualifies for EU Green Deal preferential procurement by German automotive tier-one suppliers. |
Study Parameters
Multiple input streams — ferrite materials scientists, automotive Tier 1 procurement officers, EMS supply chain managers, and electronics distributor category leads — were reconciled against trade flow data, MIIT regulatory filings, and AEC-Q200 test protocol documentation. Primary field engagement with sintering facility operators in Japan's Kanto region and Tamil Nadu PLI corridors complemented secondary validation. Bottom-up unit demand modeling across smartphone, EV powertrain, and data center server backplane applications triangulated against top-down materials consumption estimates.
Historical capacity utilization patterns cross-referenced against expert panel inputs on 800V EV adoption curves and MIIT EMC enforcement trajectories shaped projection parameters. Segmentation modeling spanned product architecture, application voltage tier, qualification level, and regional manufacturing cluster. CAGRs derived from impedance demand elasticity coefficients and substitution threat assessments for integrated passive devices. DC-DC converter density trends and differential signaling proliferation provided industry-specific demand anchors.
The model holds under steady MIIT enforcement and linear EV voltage escalation; deviation in automotive qualification timeline compression or thin-film substitute frequency-range expansion would shift supplier margin distributions. A model refresh is warranted upon material change in F-Gas Regulation cost burdens or PLI scheme subsidy structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
High Density Interconnect (HDI) PCB Market
Electronic Components
North America MLCC Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Global Capacitor Market
Electronic Components
Pneumatic Components Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Capacitive Stylus Pen Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Crystal Oscillators Market
Electronic Components
Touchless Tubes Market
Electronic Components
Dual Relay Board Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
Power Inductors Market
Electronic Components
Motherboard Battery Market