
 Microbial Fuel Cell Market | 2026-2036
Microbial Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Fuel Cell Market Analysis
A shift from single-source membrane suppliers toward multi-source electrode procurement is decoupling production bottlenecks across the value chain. Cambrian Innovation leverages its anaerobic treatment heritage to anchor commercial deployments in brewery and food-processing effluent. Electro-Active Technologies competes through continuous-flow reactor architectures optimized for high-organic-strength waste streams. MICROrganic Technologies specializes in miniaturized air-cathode designs for educational and remote-sensing applications.
A microbial fuel cell harvests electrical current from the metabolic oxidation of organic substrates by electroactive bacteria, typically operating at 0.3–0.7 V per cell and requiring proton-exchange or cation-exchange membranes to maintain charge balance. Dual-chamber configurations dominate laboratory validation but face manufacturing cost barriers; membrane-less architectures represent the fastest-growing technology segment as simplified fabrication reduces material overhead. Wastewater treatment anchors application demand, while power generation occupies an emerging niche where low-voltage output suits distributed sensor networks. Stacked systems lead product-type revenue as series-connected cells overcome single-unit voltage limitations.
The EPA enforces effluent discharge limits that push U.S. industrial facilities toward energy-neutral treatment alternatives, while REACH compliance in Europe restricts platinum-group catalyst use and redirects electrode development toward carbon-based substitutes. China's MEE integrates MFC pilots into national dual-carbon demonstration zones, accelerating domestic membrane-electrode assembly capacity. Stakeholders must weigh membrane durability against capital cost trade-offs as scale-up decisions crystallize before standardized performance benchmarks emerge.
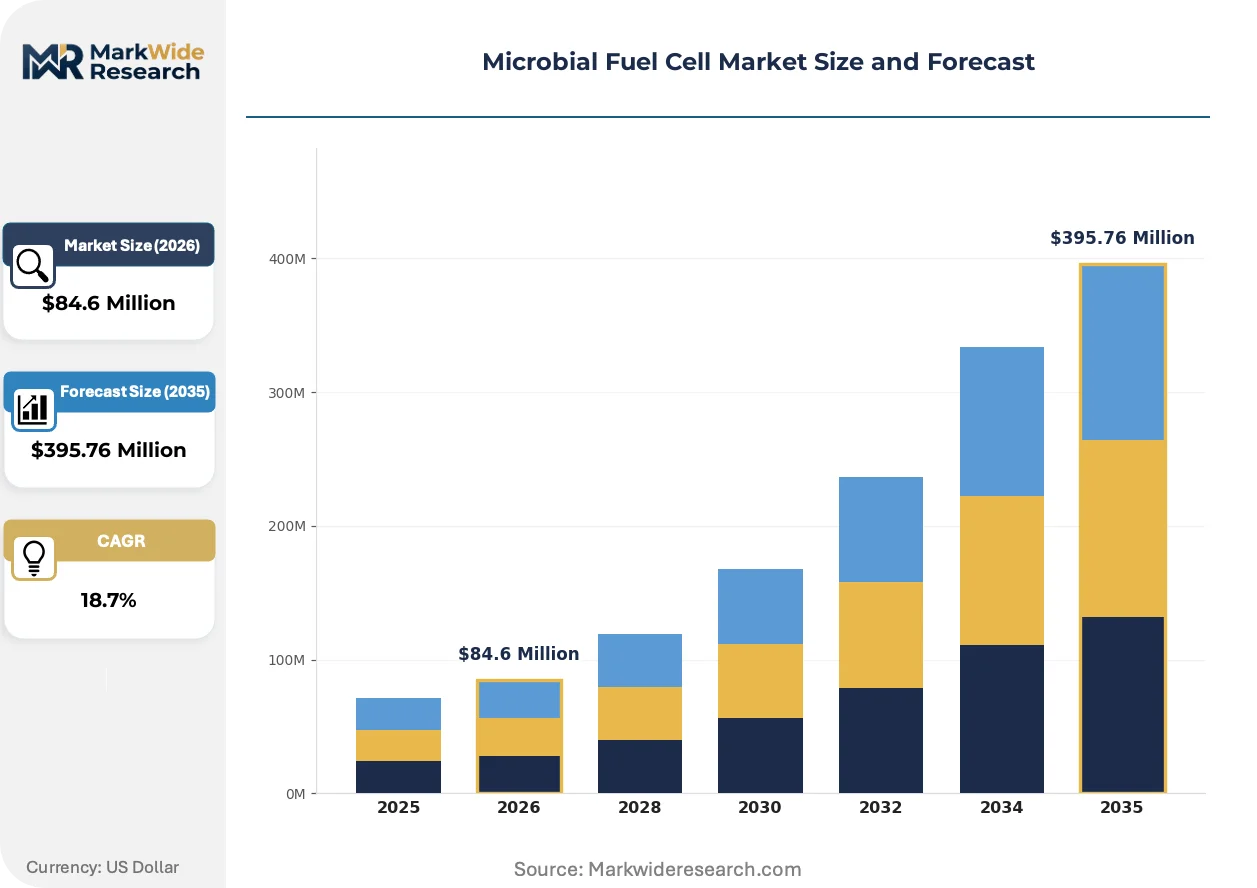
Market Dynamics
Membrane-less reactor architectures are compressing capital costs and unlocking scale-up feasibility for wastewater-integrated power systems, fundamentally restructuring supplier relationships across the electrode and membrane value chain.
Growth Catalysts
- EU Green Deal wastewater-energy mandates:Germany's municipal utilities are expanding pilot deployments, creating anchor demand for stackable MFC systems in European effluent treatment infrastructure.
- Carbon-based electrode substitution:REACH compliance restrictions on platinum-group catalysts are redirecting R&D toward activated carbon and graphene composites, decoupling supply from precious metal volatility.
- Industrial effluent treatment:Food-processing and brewery sectors in China and the United States are deploying continuous-flow reactors to offset energy costs in high-organic-strength waste streams.
Market Restraints
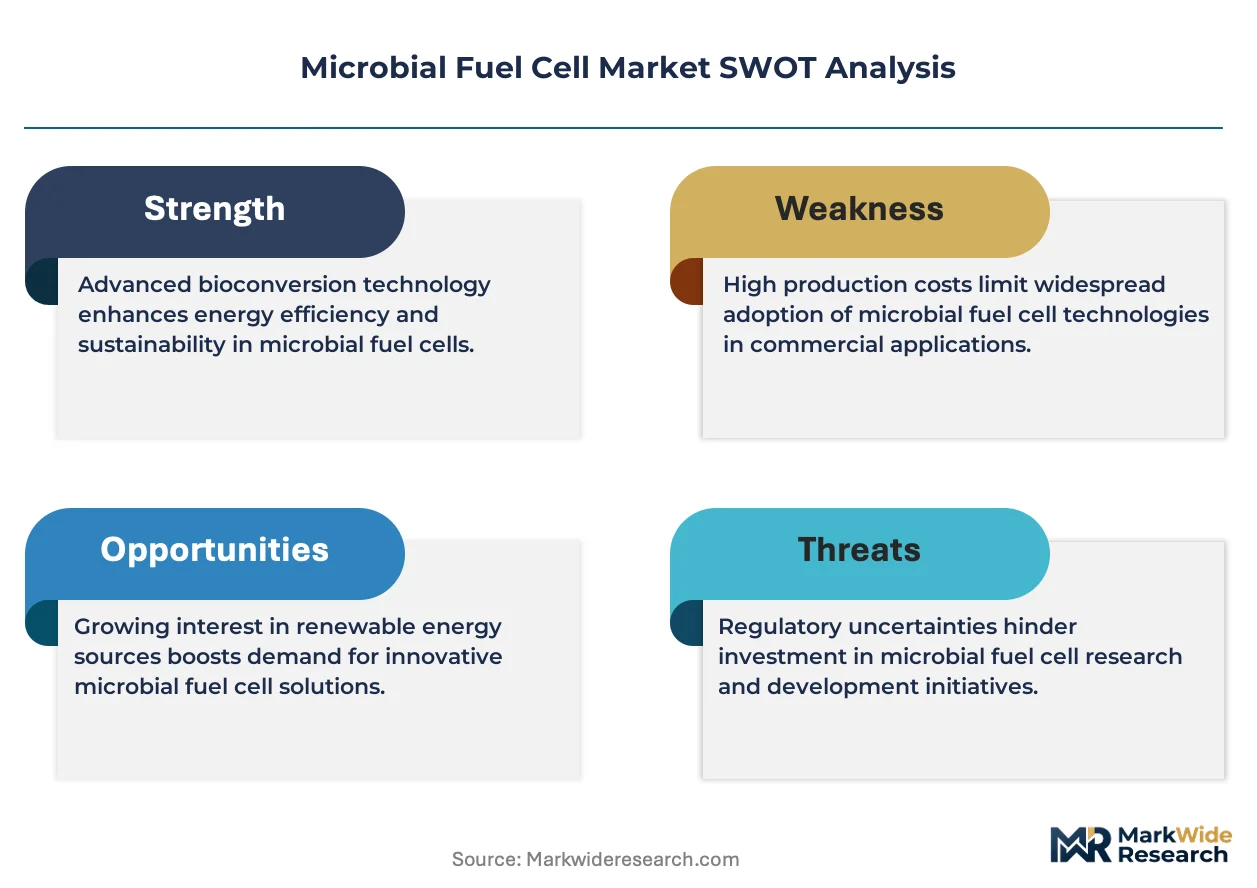
- Proton-exchange membrane cost concentration:Specialized membrane suppliers in East Asia control critical ionomer supply, exposing project developers to input cost volatility and lead-time risk.
- Single-cell voltage ceiling:Individual MFC units operate at 0.3–0.7 V, requiring series-connected stacks that multiply manufacturing complexity and failure points.
- Competing anaerobic digestion:Established biogas recovery systems in mature wastewater markets present lower capital barriers and proven performance benchmarks.
Strategic Opportunities
- Remote sensor network electrification:Miniaturized air-cathode designs are penetrating environmental monitoring and IoT infrastructure where grid connection is uneconomical.
- China's dual-carbon demonstration zones:The MEE is integrating MFC pilots into national decarbonization showcases, accelerating domestic membrane-electrode assembly capacity buildout.
- Educational equipment channels:University and technical college laboratories represent an underpenetrated procurement segment for bench-scale demonstration units.
Industry Challenges
- Electrochemist talent scarcity:The intersection of microbiology and electrochemical engineering lacks standardized training pathways, constraining deployment velocity for commercial projects.
- Performance benchmark fragmentation:Absence of standardized power density and longevity metrics complicates buyer evaluation and financing due diligence.
- Legacy SCADA integration:Wastewater treatment facilities require custom interface development to incorporate MFC voltage monitoring into existing process control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Fuel Cell Market |
| Market Size in 2026 | $84.6 Million |
| Market Size in 2035 | $395.76 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Single-Chamber, Dual-Chamber, Membrane-less, Enzyme-based Application: Wastewater Treatment, Portable Devices, Monitoring Systems, Power Generation End User: Industrial, Municipal, Agricultural, Research Institutions Product Type: Stacked Systems, Standalone Units, Hybrid Systems, Custom Solutions |
| Companies Covered | Sainergy Tech, Electro-Active Technologies, Fluence Corporation Limited, Prongineer R&D, Cascade Clean Energy, Cambrian Innovation, MICROrganic Technologies, Triqua International, Pilus Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Fuel Cell Market Emerging Trajectories
Fabrication simplification and regulatory chemistry restrictions are converging to reshape material selection and procurement patterns across the microbial fuel cell supply base.
Membrane-less architectures are overtaking dual-chamber configurations as the dominant laboratory-to-pilot pathway. Simplified fabrication eliminates proton-exchange membrane material overhead, reducing per-unit capital by removing the costliest stack component. Brewery and food-processing effluent treatment operators in Germany and the United States are accelerating adoption timelines, compressing the traditional membrane supplier bottleneck.
REACH platinum-group restrictions are forcing electrode catalyst reformulation across European manufacturing. Carbon-based substitutes including activated carbon felts and nitrogen-doped graphene are achieving competitive electron transfer rates in high-organic-strength environments. Stackable system producers are responding by qualifying multi-source carbon electrode supply chains, reducing dependency on single-source precious metal coatings.
Sensor network operators are unbundling after-sales service from equipment procurement, treating MFC units as disposable power modules rather than capital assets. Environmental monitoring agencies in remote geographies are driving this shift, prioritizing field-replaceable units over centralized maintenance contracts. Educational and research institutions remain the exception, where extended service agreements persist for precision calibration requirements.
Microbial Fuel Cell Market Segmentation
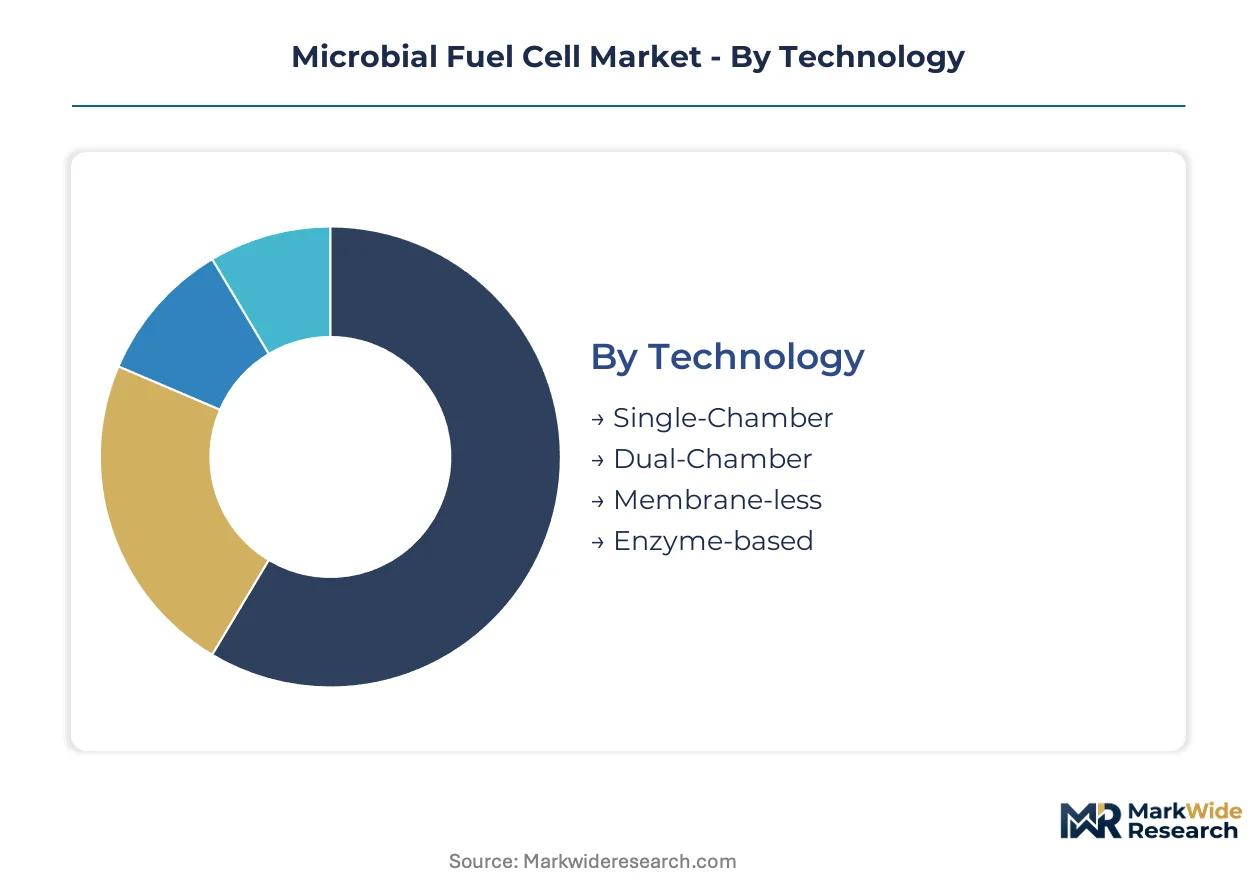
Segmentation in microbial fuel cells separates architectures by electrochemical configuration, deployment scale, and operational environment. Each dimension carries distinct capital requirements, performance ceilings, and regulatory exposure that shape procurement decisions across wastewater utilities, industrial facilities, and research networks.
Technology:
Upgrade cycles in MFC technology follow membrane durability failures and electrode fouling events, driving replacement decisions every three to five years in continuous-flow installations.
- Membrane-less:Eliminates proton-exchange membrane material overhead through single-compartment designs where electrode spacing maintains ionic conductivity. Brewery and food-processing effluent operators in Germany deploy these architectures to compress capital costs and sidestep East Asian membrane supply bottlenecks.
- Dual-Chamber:Separates anodic and cathodic reactions with dedicated proton-exchange or cation-exchange membranes, achieving higher coulombic efficiency in laboratory validation. Municipal wastewater pilots in China favor this configuration for performance benchmarking against anaerobic digestion baselines.
- Single-Chamber:Combines air-cathode exposure with submerged anode design for simplified fabrication.
- Enzyme-based:Replaces whole-cell bacterial metabolism with isolated oxidoreductase enzymes for targeted substrate specificity.
Volume placements concentrate in membrane-less configurations; the faster expansion belongs to dual-chamber systems in China's dual-carbon demonstration zones.
Application:
Cost tier differentiation separates high-volume municipal contracts from premium-priced remote sensing deployments where grid connection economics are unfavorable.
- Wastewater Treatment:Anchors commercial demand through energy-neutral effluent processing, with continuous-flow reactors achieving organic load reduction alongside electrical current harvest. Germany's municipal utilities under EU Green Deal mandates are expanding pilot footprints for stackable systems in urban treatment infrastructure.
- Power Generation:Occupies an emerging niche where distributed voltage output suits off-grid sensor networks and IoT infrastructure. Environmental monitoring agencies in remote geographies treat these units as field-replaceable power modules rather than maintained capital assets.
- Portable Devices:Miniaturized air-cathode designs power educational demonstrations and field-deployable electronics.
- Monitoring Systems:Voltage output signals metabolic activity levels for real-time organic contamination detection.
Capital deployment concentrates in wastewater treatment; the steepest expansion trajectory appears in power generation for distributed environmental sensing.
End User:
Customer type segmentation maps to procurement sophistication, with industrial buyers demanding performance guarantees and research institutions accepting technical risk for parameter exploration.
- Industrial:Food-processing and brewery sectors in the United States deploy continuous-flow reactors to offset energy costs in high-organic-strength waste streams, with EPA effluent discharge limits pushing facilities toward energy-neutral treatment alternatives.
- Research Institutions:University and technical college laboratories represent concentrated demand for bench-scale demonstration units requiring precision calibration and extended service agreements.
- Municipal:Public wastewater utilities prioritize proven longevity metrics over experimental performance.
- Agricultural:Livestock operations and food processing cooperatives evaluate MFCs against anaerobic lagoon alternatives.
Procurement volume concentrates in industrial end users; research institutions are climbing the fastest as educational equipment channels deepen penetration.
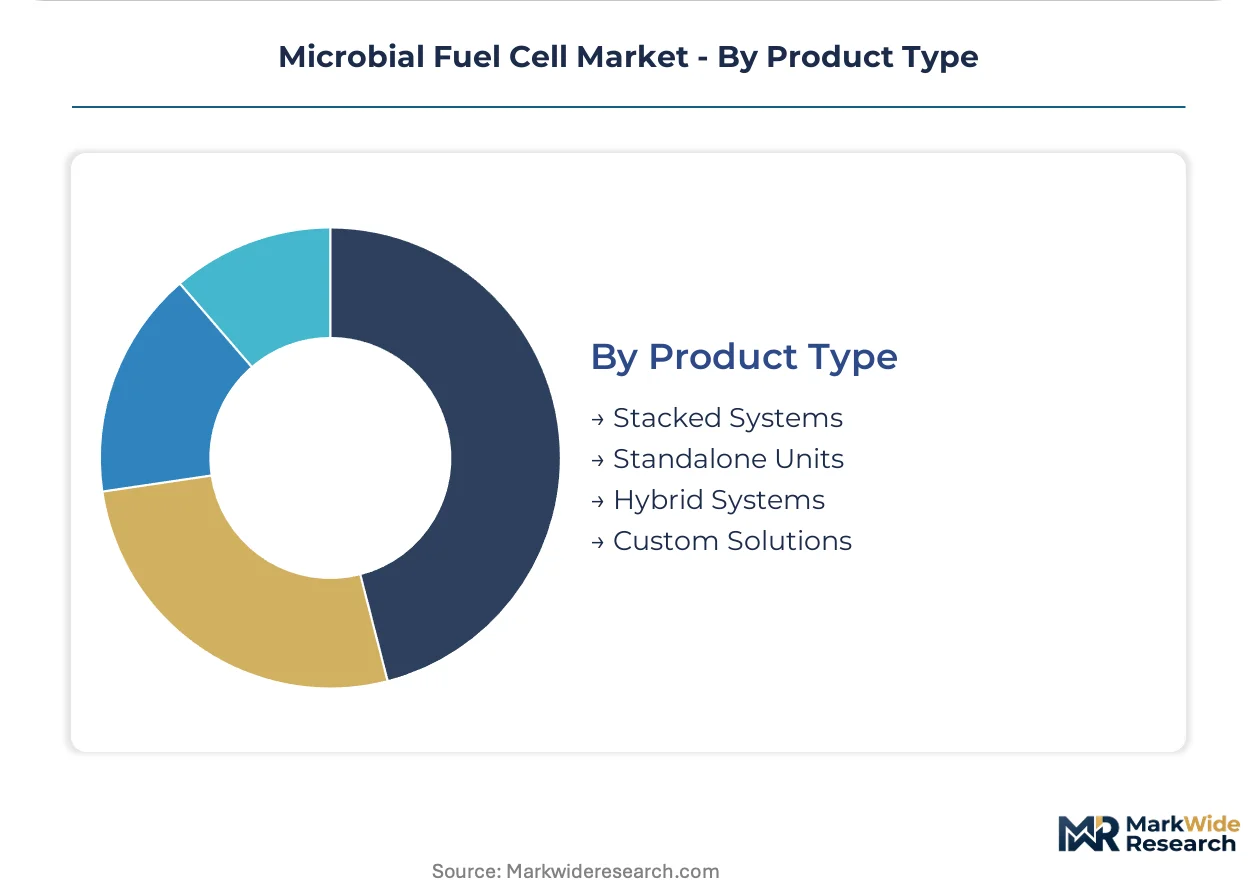
Product Type:
Supply concentration in membrane-electrode assembly favors stacked system producers with multi-source carbon electrode qualification capabilities.
- Stacked Systems:Series-connected cells overcome single-unit voltage limitations of 0.3–0.7 V through modular architecture, multiplying manufacturing complexity but enabling practical current delivery. China and the United States concentrate near-term demand for these architectures in industrial effluent treatment scale-up.
- Standalone Units:Single-cell configurations serve educational demonstrations and sensor network pilots where voltage requirements remain minimal.
- Hybrid Systems:Integrate MFC stages with anaerobic digestion or membrane bioreactor processes.
- Custom Solutions:Engineered configurations for site-specific organic load profiles and space constraints.
Revenue concentration sits with stacked systems; custom solutions are gaining share fastest in specialized industrial integration projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and the United States concentrate near-term demand for stackable MFC architectures in industrial effluent treatment, while Germany anchors European pilot deployments under EU Green Deal mandates. Municipal wastewater utilities across these three markets are expanding procurement footprints for membrane-electrode assembly systems.
United States
Food-processing and brewery sectors deploy continuous-flow reactors to offset energy costs in high-organic-strength waste streams. The EPA enforces effluent discharge limits that push industrial facilities toward energy-neutral treatment alternatives. Greater Boston hosts Cambrian Innovation's commercial deployments anchoring brewery sector adoption.
China
Industrial effluent treatment operators concentrate demand for stackable MFC systems in coastal manufacturing zones. The MEE integrates MFC pilots into national dual-carbon demonstration zones, accelerating domestic membrane-electrode assembly capacity. Yangtze River Delta municipalities are scaling pilot footprints for urban wastewater infrastructure.
Germany
Municipal wastewater utilities expand pilot deployments under EU Green Deal wastewater-energy nexus mandates. REACH compliance restricts platinum-group catalyst use, redirecting electrode development toward carbon-based substitutes. Bavarian treatment operators are qualifying multi-source carbon electrode supply chains for stackable system procurement.
Japan
Research institutions and precision electronics manufacturers evaluate miniaturized air-cathode designs for remote sensing applications. METI funding programs support demonstration projects integrating MFC stages with existing anaerobic digestion infrastructure. Kanto region universities are deepening procurement channels for bench-scale demonstration units.
India
Municipal corporations in high-growth urban centers pilot membrane-less architectures for cost-compressed capital deployment. The CEA evaluates distributed power generation from organic waste streams under national renewable energy targets. Maharashtra state utilities are testing continuous-flow reactors for textile effluent treatment clusters.
Microbial Fuel Cell Market Vendor Landscape
Strategic partnerships dominate the current landscape as membrane-electrode assembly producers qualify multi-source carbon electrode supply chains. The vendor base clusters around three archetypes: anaerobic treatment heritage firms pivoting to electrochemical systems, continuous-flow reactor specialists optimizing for high-organic-strength environments, and miniaturized air-cathode designers serving educational and remote-sensing niches. Capacity expansion and technology licensing represent the dominant competitive moves as scale-up feasibility crystallizes before standardized performance benchmarks emerge.
Within the anaerobic treatment heritage tier, Cambrian Innovation and Electro-Active Technologies exemplify contrasting strategic positioning. Cambrian Innovation occupies a position anchored in brewery and food-processing effluent commercial deployments, while Electro-Active Technologies represents the continuous-flow reactor optimization archetype for high-organic-strength waste streams. MICROrganic Technologies sits within the miniaturized air-cathode specialization vector, serving educational equipment channels and remote sensor network operators.
| Leading Market Players |
|---|
| Sainergy Tech |
| Electro-Active Technologies |
| Fluence Corporation Limited |
| Prongineer R&D |
| Cascade Clean Energy |
| Cambrian Innovation |
| MICROrganic Technologies |
| Triqua International |
| Pilus Energy |
| Others |
Supply Flow & Price Mechanics
Platinum-group metal price volatility cascades through membrane-electrode assembly procurement, bifurcating MFC system pricing into REACH-compliant carbon-electrode tiers and legacy precious-metal configurations. German municipal utilities and U.S. food-processing operators face divergent input cost structures as East Asian membrane suppliers concentrate pricing power over ionomer supply.
Pricing Analysis
Volume placements concentrate in standard-tier membrane-less configurations while premium dual-chamber systems capture margin in municipal pilot contracts. Price differentiation rests on membrane durability guarantees and electrode fouling resistance specifications. Cost compression in the standard tier intensifies as carbon-based substitutes achieve competitive electron transfer rates. Industrial effluent operators exhibit highest price sensitivity; research institutions accept premium calibration service bundling.
Supply Chain Analysis
Dual-sourcing mandates from German utilities and U.S. EPA-regulated facilities are forcing membrane-electrode assemblers to qualify secondary carbon electrode suppliers in Japan and South Korea. Critical inputs draw from East Asian proton-exchange membrane foundries, activated carbon processors in Germany, and graphene composite specialists in China. Single-source ionomer vulnerability exposes project developers to lead-time risk. Distribution runs through wastewater treatment EPC contractors and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microbial fuel cell market functions as a cost-of-compliance arena where REACH platinum-group restrictions and EPA effluent mandates erect regulatory moats favoring carbon-electrode qualified incumbents.
For Market Incumbents: To counter membrane-less architecture commoditization, anchor procurement relationships with German municipal utilities through dual-carbon demonstration zone participation. Pursue backward integration into activated carbon felt production to decouple from precious metal coating volatility. Lock in multi-year electrode supply agreements with Bavarian treatment operators before standardized performance benchmarks emerge. For New Entrants and Emerging Players: Enter via educational equipment channels where MICROrganic Technologies has validated miniaturized air-cathode demand without competing on wastewater treatment scale economics. Target remote sensor network operators in Japan and India treating MFC units as disposable power modules. Lead with field-replaceable unit value propositions unbundled from maintenance contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor continuous-flow reactor specialists with EPA-validated deployments in U.S. brewery and food-processing sectors. Monitor MEE dual-carbon demonstration zone procurement announcements as inflection signals for domestic membrane-electrode assembly capacity buildout. Long-term viability hinges on qualification timelines for carbon-based electrode supply chains displacing platinum-group dependencies.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Electrode Supply Qualification | REACH compliance redirects R&D toward activated carbon and graphene composites, decoupling from precious metal volatility. |
| Dual-Carbon Demonstration Zone Integration | China's MEE pilots accelerate domestic membrane-electrode assembly capacity in Yangtze River Delta municipalities. |
| Membrane-Less Architecture Scale-Up | Simplified fabrication eliminates proton-exchange membrane overhead, compressing capital costs for brewery effluent operators. |
| Remote Sensor Network Partnership | Miniaturized air-cathode designs penetrate environmental monitoring agencies treating units as field-replaceable power modules. |
| Electrochemist Talent Pipeline Development | Standardized training pathways at Kanto region universities address deployment velocity constraints for commercial projects. |
Methodological Framework
Trade flow databases, EPA enforcement records, and ECHA REACH submission filings formed the secondary backbone, cross-referenced with primary interviews involving wastewater treatment plant engineers, membrane-electrode assembly procurement leads, brewery sustainability directors, municipal utility planning officers, and carbon electrode R&D specialists. Bottom-up installation tracking and top-down regulatory mandate sizing were triangulated against capital expenditure disclosures from German municipal utilities and China's MEE pilot announcements.
Historical deployment trajectories in brewery effluent treatment and municipal wastewater pilots anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include electrochemical configuration, deployment scale, organic load strength, and regional regulatory cluster. CAGRs were derived from installation run-rate extrapolation and membrane replacement cycle analysis. Forecast inputs incorporated REACH platinum-group restriction timelines and EPA effluent limit enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under membrane supply disruption scenarios or electrochemist talent scarcity acceleration. Deviation in China's dual-carbon demonstration zone procurement pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Bipolar Plate Coatings Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
PEM Electrolyzer Market