
 Asia-Pacific Fuel Cell Market | 2026-2036
Asia-Pacific Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fuel Cell Market Analysis
Japan's METI hydrogen roadmap and South Korea's Hydrogen Economy Implementation Plan is rebalancing procurement priorities across industrial power buyers. Toyota Motor Corporation leverages its integrated fuel cell stack manufacturing to anchor supply for heavy-duty transport. Doosan Fuel Cell dominates stationary power installations through alkaline and phosphoric acid platforms. Ballard Power Systems Inc. navigates China's bus and truck electrification mandates with membrane electrode assembly specialization.
A fuel cell electrochemically combines hydrogen and oxygen to generate electricity, with proton exchange membrane systems operating at 60-80°C and solid oxide variants reaching 800-1000°C for industrial cogeneration. The technology serves as a zero-emission power source where battery weight or charging duration constrains operational viability. Proton exchange membrane technology leads transportation applications due to rapid cold-start capability and power density advantages. Solid oxide technology captures margin pools in stationary industrial settings where waste heat recovery improves total system efficiency. Stationary power applications sustain the largest revenue share through grid-scale installations and on-site industrial generation.
Japan's METI enforces JIS standards for hydrogen infrastructure safety, while China's MIIT coordinates GB standards for fuel cell electric vehicle performance verification. South Korea's KGS certification governs high-pressure hydrogen storage and dispensing equipment. India's BIS is developing hydrogen fuel quality specifications under its National Hydrogen Mission. Stakeholders must monitor regulatory divergence in hydrogen purity standards and carbon intensity accounting rules to align product certification across national markets.
Market Dynamics
Japan's METI hydrogen roadmap and South Korea's Hydrogen Economy Implementation Plan are restructuring procurement priorities across Asia-Pacific industrial power buyers, forcing fleet operators and petrochemical clusters to accelerate hydrogen offtake commitments.
Growth Catalysts
- Japan's METI hydrogen roadmap:Tightening emission benchmarks for industrial power users in Kanto industrial corridor are mandating zero-emission baseload alternatives.
- Heavy-duty trucking fleets:Expanding hydrogen procurement contracts across Japan and South Korea are creating predictable demand anchors for fuel cell system suppliers.
- China's dual carbon goals:MIIT-coordinated GB standards for fuel cell electric vehicle performance verification are accelerating domestic manufacturing scale.
Market Restraints
- Platinum catalyst dependency:Proton exchange membrane stack manufacturing remains tethered to volatile precious metal input costs concentrated in South African mining operations.
- High-pressure hydrogen storage certification:South Korea's KGS certification timeline for dispensing equipment extends deployment schedules by 18-24 months.
- Battery electric vehicle substitution:Lithium-ion powered urban bus fleets in Chinese megacities are capturing intra-city routes where charging infrastructure density favors batteries.
Strategic Opportunities
- India's National Hydrogen Mission:BIS hydrogen fuel quality specifications under development will unlock demand from fertilizer and refinery sectors in Gujarat-Maharashtra industrial belt.
- Solid oxide-industrial heat convergence:Waste heat recovery integration with steel and cement processes in China's coastal provinces opens high-temperature cogeneration applications.
- Direct hydrogen procurement platforms:Long-term offtake contracting is emerging as preferred channel, displacing spot-market equipment sales for stationary power buyers.
Industry Challenges
- Membrane electrode assembly technical talent:Shortage of electrochemists and stack integration engineers constrains manufacturing expansion in South Korea and Japan.
- JIS-GB-KGS multi-certification complexity:Divergent hydrogen purity standards and carbon intensity accounting rules force redundant testing protocols for cross-border equipment suppliers.
- Legacy industrial power asset integration:Fuel cell retrofit compatibility with existing steam turbine infrastructure in Ulsan petrochemical hub requires custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fuel Cell Market |
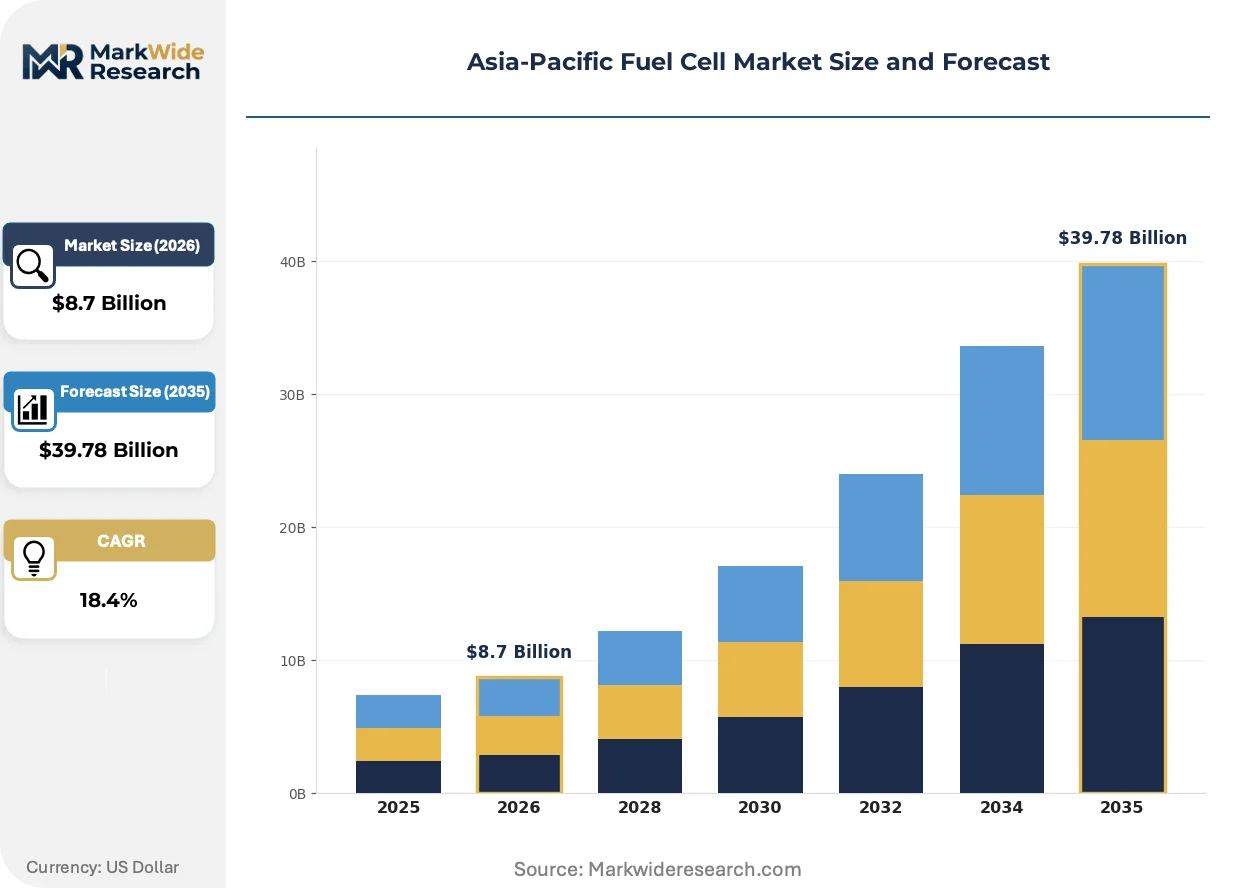
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Membrane Electrode Assembly, Fuel Processor, Power Conditioning Unit, Balance of Plant Technology: Proton Exchange Membrane, Solid Oxide, Phosphoric Acid, Alkaline Application: Transportation, Stationary Power, Portable Power, Backup Power End User: Automotive, Industrial, Residential, Commercial |
| Companies Covered | Toyota Motor Corporation, Ballard Power Systems Inc., Toshiba Fuel Cell Power Systems Corporation, Doosan Fuel Cell, FuelCell Energy Inc., Mitsubishi Hitachi Power Systems Ltd, Bloom Energy, Fuji Electric Co Ltd, Panasonic Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fuel Cell Market Emerging Trajectories
Electrolyzer-to-fuel cell supply chain coupling and modular system architectures are compressing deployment timelines across Asia-Pacific hydrogen valleys, with technology convergence accelerating in industrial corridor applications.
Proton exchange membrane technology is decentralizing stationary power deployment by enabling containerized megawatt-scale systems that bypass transmission interconnection queues. Japanese data center operators in Osaka-Tokyo corridor are adopting these modular units for baseload reliability. The technology is decentralizing grid planning authority toward industrial end-users who self-provision rather than await utility infrastructure.
South Korea's Hydrogen Economy Implementation Plan mandates 15% hydrogen blending in city gas networks by 2030, forcing gas utilities to retrofit pipeline infrastructure and metering systems. This regulatory pressure is spawning dedicated hydrogen quality testing protocols. Stationary fuel cell suppliers serving apartment complexes and commercial districts face the most compressed compliance timelines.
Fleet operators in Japan and South Korea are consolidating hydrogen procurement through multi-year supply agreements rather than equipment ownership, transferring operational risk to fuel suppliers. This contractual shift is restructuring vendor revenue models toward hydrogen-as-a-service frameworks. The pattern is most visible in heavy-duty trucking corridors connecting Tokyo-Nagoya and Seoul-Busan freight routes.
Asia-Pacific Fuel Cell Market Segmentation
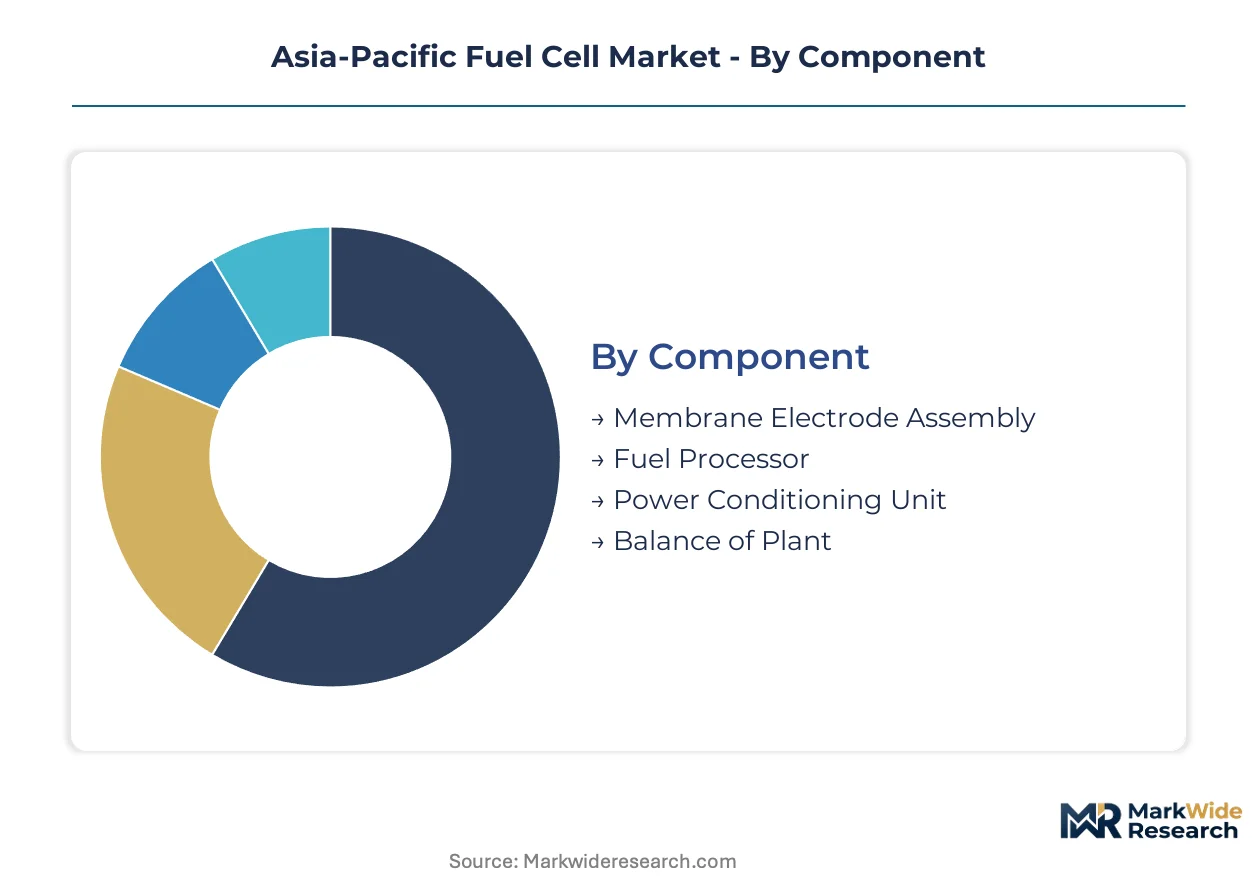
Segmentation reveals how fuel cell value pools concentrate across technology maturity curves and procurement risk profiles. Component sourcing strategies diverge sharply between integrated stack manufacturers and modular system assemblers.
Component:
Supply concentration in membrane electrode assembly production anchors procurement costs for Japanese and South Korean stack manufacturers.
- Membrane Electrode Assembly:The electrochemical core combines platinum-loaded catalyst layers with proton-conducting membranes. Toyota Motor Corporation and Hyundai Motor Group captive-produce MEA volumes for heavy-duty transport fleets across the Tokyo-Nagoya corridor. Platinum loading reduction roadmaps target 0.1 grams per kilowatt to break cost barriers.
- Fuel Processor:Reforming hardware converts natural gas or methanol into hydrogen-rich feedstock for stationary installations. Doosan Fuel Cell integrates alkaline stack platforms with on-site fuel processing for Ulsan petrochemical hub baseload contracts. Reformate purity specifications constrain catalyst longevity in phosphoric acid systems.
- Power Conditioning Unit:Inverters and DC-DC converters manage electrical output stability for grid interconnection.
- Balance of Plant:Thermal management, humidification, and auxiliary systems complete system integration.
Membrane electrode assembly absorbs the bulk of installed capacity; balance of plant is expanding most quickly as modular architectures standardize auxiliary packaging.
Technology:
Cost tier stratification separates premium proton exchange membrane systems from economy alkaline platforms in procurement portfolios.
- Proton Exchange Membrane:Low-temperature operation at 60-80°C enables rapid cold-start for transportation duty cycles. Ballard Power Systems Inc. specializes in membrane electrode assembly integration for China's bus and truck electrification mandates under MIIT-coordinated GB standards. Power density advantages dominate heavy-duty trucking specifications.
- Solid Oxide:High-temperature operation at 800-1000°C enables waste heat recovery for industrial cogeneration. Steel and cement processes in China's coastal provinces integrate solid oxide systems for combined heat and power efficiency above 80 percent. Ceramic cell manufacturing requires sintering furnaces with limited regional supplier bases.
- Phosphoric Acid:Mature technology serves stationary baseload with established field durability records.
- Alkaline:Lower capital cost platforms dominate electrolyzer coupling and early-stage hydrogen valley deployments.
Proton exchange membrane captures premium pricing in transportation; solid oxide is climbing the fastest as industrial heat integration requirements tighten.
Application:
Volume concentration in stationary power reflects grid-scale procurement timelines and industrial self-generation economics.
- Stationary Power:Grid-scale installations and on-site industrial generation sustain the largest revenue share. Japanese data center operators in the Osaka-Tokyo corridor deploy containerized megawatt-scale systems to bypass transmission interconnection queues. METI hydrogen roadmap compliance deadlines compress deployment schedules for Kanto industrial corridor power buyers.
- Transportation:Heavy-duty trucking fleets across Japan and South Korea consolidate hydrogen procurement through multi-year supply agreements. Fleet operators transfer operational risk to fuel suppliers under hydrogen-as-a-service frameworks. The Tokyo-Nagoya and Seoul-Busan freight routes anchor predictable demand volumes.
- Portable Power:Remote site applications and disaster relief equipment drive niche procurement.
- Backup Power:Critical facility resilience requirements support stationary fuel cell adoption alongside battery systems.
Stationary power absorbs the bulk of installed capacity; transportation is gaining share fastest as fleet electrification mandates harden.
End User:
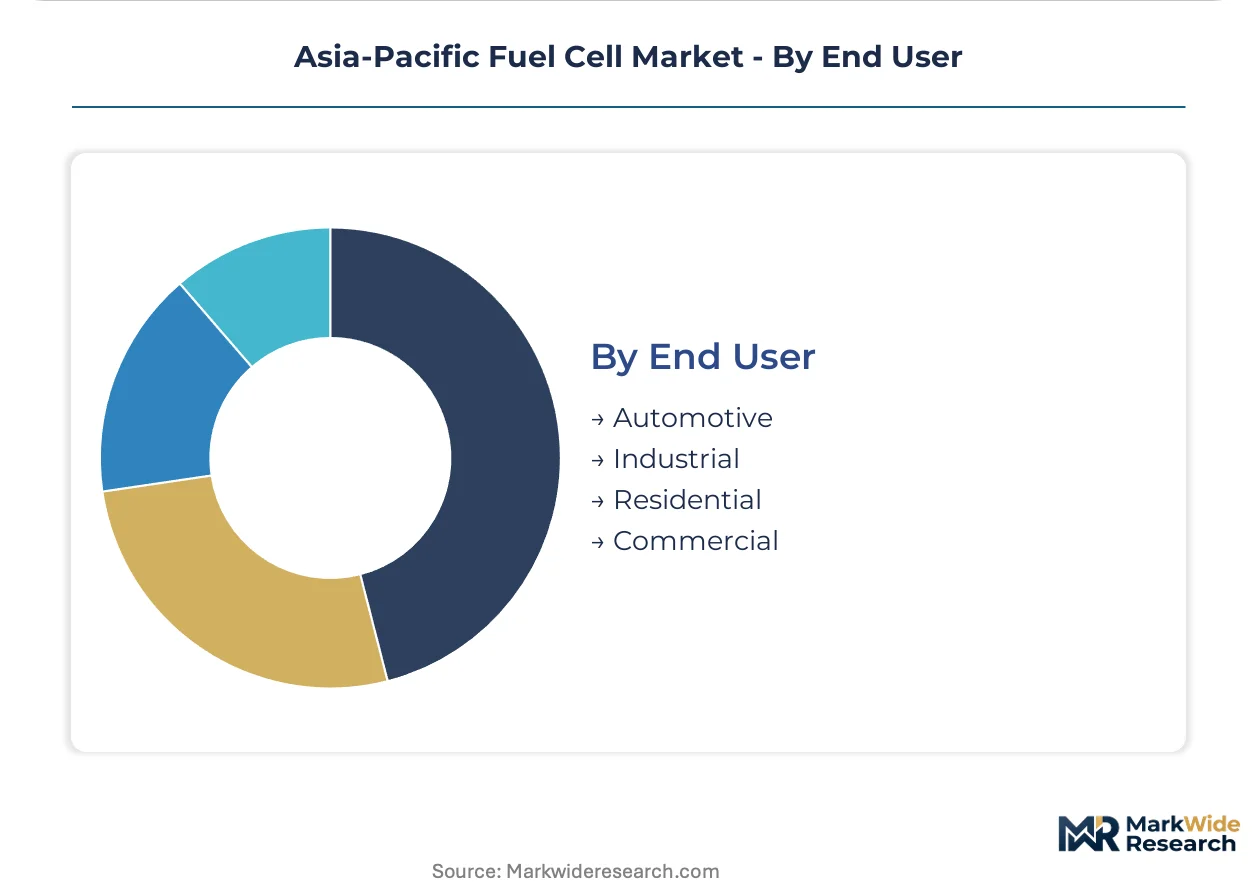
Customer type differentiation separates industrial procurement scale from residential unit economics in distribution channel design.
- Industrial:Petrochemical clusters and manufacturing facilities anchor megawatt-scale deployments. South Korea's Ulsan petrochemical hub requires custom engineering for fuel cell retrofit compatibility with existing steam turbine infrastructure. Hydrogen procurement contracts extend 10-15 years to match asset depreciation schedules.
- Automotive:Heavy-duty truck and bus manufacturers integrate fuel cell powertrains under China's dual carbon goals and Japan's METI emission benchmarks. MIIT performance verification standards accelerate domestic manufacturing scale for fuel cell electric vehicle platforms.
- Residential:Cogeneration systems serve single-family and multi-unit buildings in hydrogen-blended gas networks.
- Commercial:Retail, hospitality, and office installations follow industrial adoption curves with smaller unit scales.
Industrial end users absorb the bulk of installed capacity; automotive is expanding most quickly as OEM platform commitments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ulsan petrochemical hub anchors hydrogen demand concentration in South Korea, while Japan's Kanto industrial corridor drives stationary power procurement. China's coastal provinces integrate solid oxide systems with steel and cement processes. Industrial clusters across these three markets absorb the bulk of fuel cell deployment capacity.
Japan
Heavy-duty trucking fleets along the Tokyo-Nagoya freight corridor consolidate hydrogen procurement through multi-year supply agreements. METI enforces JIS standards for hydrogen infrastructure safety and tightens emission benchmarks for Kanto industrial corridor power buyers. Data center operators in the Osaka-Tokyo corridor deploy containerized megawatt-scale proton exchange membrane systems to bypass transmission interconnection queues.
South Korea
Busan-Ulsan petrochemical hub requires custom engineering for fuel cell retrofit compatibility with existing steam turbine infrastructure. The Hydrogen Economy Implementation Plan mandates 15% hydrogen blending in city gas networks by 2030, forcing gas utilities to retrofit pipeline infrastructure. KGS certification governs high-pressure hydrogen storage and dispensing equipment with 18-24 month deployment timelines.
China
Steel and cement processes in coastal provinces integrate solid oxide systems for combined heat and power efficiency above 80 percent. MIIT coordinates GB standards for fuel cell electric vehicle performance verification under dual carbon goals. Domestic manufacturing scale accelerates for membrane electrode assembly integration in bus and truck electrification mandates.
India
Fertilizer and refinery sectors in the Gujarat-Maharashtra industrial belt await BIS hydrogen fuel quality specifications under the National Hydrogen Mission. The country's national hydrogen regulator is developing purity standards to unlock demand from industrial power users. Procurement priorities restructure as emission benchmarks tighten for manufacturing facilities in western industrial corridors.
Australia
Remote site applications and disaster relief equipment drive niche portable power procurement across mining and resource extraction operations. The country's national energy regulator coordinates grid interconnection standards for stationary fuel cell installations. Industrial self-generation economics favor modular system architectures in isolated resource corridors lacking transmission infrastructure.
Asia-Pacific Fuel Cell Market Vendor Landscape
The competitive structure tilts toward integrated automotive conglomerates with captive fuel cell stack manufacturing. Three tiers separate premium proton exchange membrane specialists from economy alkaline platform providers and industrial solid oxide fabricators. Market consolidation concentrates around membrane electrode assembly supply control and balance of plant standardization. Dominant competitive moves include strategic partnerships for hydrogen procurement contracting and capacity expansion in ceramic cell manufacturing for high-temperature applications.
Among Japan-based automotive and electronics conglomerates, Toyota Motor Corporation and Panasonic Corporation occupy positions anchoring integrated stack-to-system supply chains. Ballard Power Systems Inc. represents the membrane electrode assembly specialization archetype for transportation applications. Doosan Fuel Cell exemplifies stationary power concentration through alkaline and phosphoric acid platform dominance in South Korean industrial installations.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Ballard Power Systems Inc. |
| Toshiba Fuel Cell Power Systems Corporation |
| Doosan Fuel Cell |
| FuelCell Energy Inc. |
| Mitsubishi Hitachi Power Systems Ltd |
| Bloom Energy |
| Fuji Electric Co Ltd |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Electrochemist and stack integration engineer shortages in South Korea and Japan widen labor-cost spreads between premium proton exchange membrane systems and economy alkaline platforms. METI hydrogen roadmap compliance deadlines compress procurement timelines for Kanto industrial corridor power buyers, forcing accelerated certification investments that tier pricing across JIS-compliant and non-certified equipment.
Pricing Analysis
Uptime-guarantee contracting anchors value-based pricing for stationary fuel cell installations serving Japanese data center operators in the Osaka-Tokyo corridor. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified proton exchange membrane systems from KGS-compliant phosphoric acid platforms and uncertified alkaline units. Price differentiation hinges on membrane electrode assembly platinum loading and balance of plant standardization. Cost compression in economy alkaline tiers is intensifying because electrolyzer-to-fuel cell supply chain coupling reduces reformate processing overhead. Industrial end users in South Korea's Ulsan petrochemical hub exhibit lowest price sensitivity due to long-term hydrogen procurement contracts, while remote site operators in Australia face acute budget constraints.
Supply Chain Analysis
Certification complexity across JIS-GB-KGS multi-standard regimes gates supplier qualification timelines and fragments procurement pools. Manufacturing concentration rests on Japan, South Korea, and China for membrane electrode assembly production, ceramic cell sintering furnaces, and balance of plant modular packaging. Platinum catalyst layers, proton-conducting membranes, and high-pressure hydrogen storage vessels constitute critical input dependencies. Single-source vulnerability in South African platinum mining operations exposes stack manufacturers to commodity price volatility. Distribution runs through direct hydrogen procurement platforms and equipment-as-a-service frameworks displacing traditional spot-market sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific fuel cell market sits in a technology-transition phase where solid oxide systems displace legacy phosphoric acid installations in industrial cogeneration applications. Proton exchange membrane platforms are simultaneously unseating alkaline technology in transportation duty cycles.
For Market Incumbents: Anchor manufacturing capacity in ceramic cell sintering for solid oxide platforms to defend against emerging Chinese competitors in high-temperature cogeneration. Deepen backward integration into membrane electrode assembly production to offset platinum catalyst volatility threatening proton exchange membrane margins. Prioritize JIS-KGS dual certification investments to preempt regulatory fragmentation locking out cross-border equipment sales. For New Entrants and Emerging Players: The premium-to-economy price-point gap in alkaline stationary power opens white-space targeting for India's Gujarat-Maharashtra fertilizer sector awaiting BIS hydrogen fuel quality specifications. Solid oxide waste heat recovery integration for China's coastal steel and cement processes represents the most penetrable application segment. Pursue hydrogen-as-a-service contracting models to bypass capital-intensive equipment ownership barriers for fleet operators. For Investors and Strategic Acquirers: Re-rating potential sits with integrated stack-to-system manufacturers given METI hydrogen roadmap enforcement tightening emission benchmarks for Kanto industrial corridor power buyers. Long-term viability favors captive membrane electrode assembly producers with proven JIS certification track records. Watch hydrogen procurement contract announcement velocity across Tokyo-Nagoya and Seoul-Busan freight corridors as inflection indicator for transportation segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Capacity Expansion | Toyota Motor Corporation's captive platinum loading reduction secures heavy-duty transport supply for Tokyo-Nagoya corridor fleets. |
| Solid Oxide Ceramic Cell Manufacturing Scale-Up | Doosan Fuel Cell's sintering furnace investments target Ulsan petrochemical hub combined heat and power retrofits. |
| Hydrogen Procurement Platform Development | Long-term offtake contracting displaces spot-market equipment sales for Kanto industrial corridor stationary power buyers. |
| JIS-GB-KGS Multi-Certification Investment | Cross-border equipment suppliers reduce redundant testing protocols for hydrogen purity standard alignment. |
| Electrolyzer-to-Fuel Cell Supply Chain Coupling | Modular system architectures compress deployment timelines across Asia-Pacific hydrogen valley industrial corridor applications. |
Methodological Framework
Trade statistics from Japan Customs, South Korean Ministry of Trade Industry and Energy filings, and China MIIT GB standard documentation formed the secondary backbone for supply-side sizing. Primary interviews with fuel cell stack manufacturing engineers, hydrogen procurement officers at heavy-duty trucking fleets, METI regulatory affairs specialists, and ceramic cell sintering equipment suppliers cross-validated secondary data points. Bottom-up installed capacity tallies triangulated against top-down industrial power demand projections across the analysis window.
Historical deployment trendlines for proton exchange membrane, solid oxide, phosphoric acid, and alkaline platforms informed technology-specific adoption curves over the projection horizon. Segmentation modeling incorporated component type, technology maturity tier, application duty cycle, and end-user procurement scale dimensions. CAGRs were derived from regression analysis against industrial emission benchmark enforcement schedules and hydrogen infrastructure investment disclosures. Platinum price volatility bands and JIS certification timeline assumptions fed sensitivity testing.
Inputs from METI hydrogen roadmap progress reports and South Korea Hydrogen Economy Implementation Plan updates were available through the study window; gaps in real-time hydrogen procurement contract pricing introduce uncertainty bands around fleet operator demand forecasts. A model refresh is warranted upon material change in BIS hydrogen fuel quality specification finalization for India's National Hydrogen Mission.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Fuel Cell for Data Center Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market