
 North America Microbial Fuel Cell Market | 2026-2036
North America Microbial Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
North America Microbial Fuel Cell Market Insights
Membrane electrode assembly architecture is fragmenting across single-chamber, dual-chamber, and membrane-less configurations as developers optimize for specific wastewater chemistries and scale targets. Cambrian Innovation anchors the commercial deployment frontier with packaged systems targeting food and beverage processing facilities. Electro-Active Technologies specializes in electrode material innovation, leveraging conductive polymer composites to lower activation losses. Sainergy Tech competes on reactor modularity, offering containerized units that reduce site-specific engineering overhead for municipal buyers.
Microbial fuel cells harness electrochemically active bacteria to transfer electrons from organic substrate oxidation to an external circuit, generating direct current while degrading contaminants; typical systems operate at 0.3-0.7 V per cell and require stacked configurations to reach practical power thresholds for sensor networks or pump loads. Wastewater treatment dominates application-level deployment, absorbing the majority of installed capacity as operators seek compliance pathways that offset aeration energy costs. Dual-chamber technology leads where substrate specificity matters, though membrane-less designs are gaining traction in cost-sensitive agricultural and remote monitoring contexts where simplified maintenance outweighs efficiency penalties.
The U.S. EPA enforces Clean Water Act discharge permits that increasingly incorporate energy-performance metrics, while Canada's Environment and Climate Change Canada administers parallel wastewater system regulations under the Fisheries Act; both frameworks indirectly incentivize MFC adoption by rewarding facilities that achieve nutrient removal with net energy reduction. State-level renewable energy credits in California and New York further improve project economics for utilities pursuing carbon-neutral operations. Stakeholders must track how emerging PFAS destruction requirements reshape substrate compatibility specifications and whether federal infrastructure funding channels prioritize novel biological treatment platforms over incremental activated sludge upgrades.
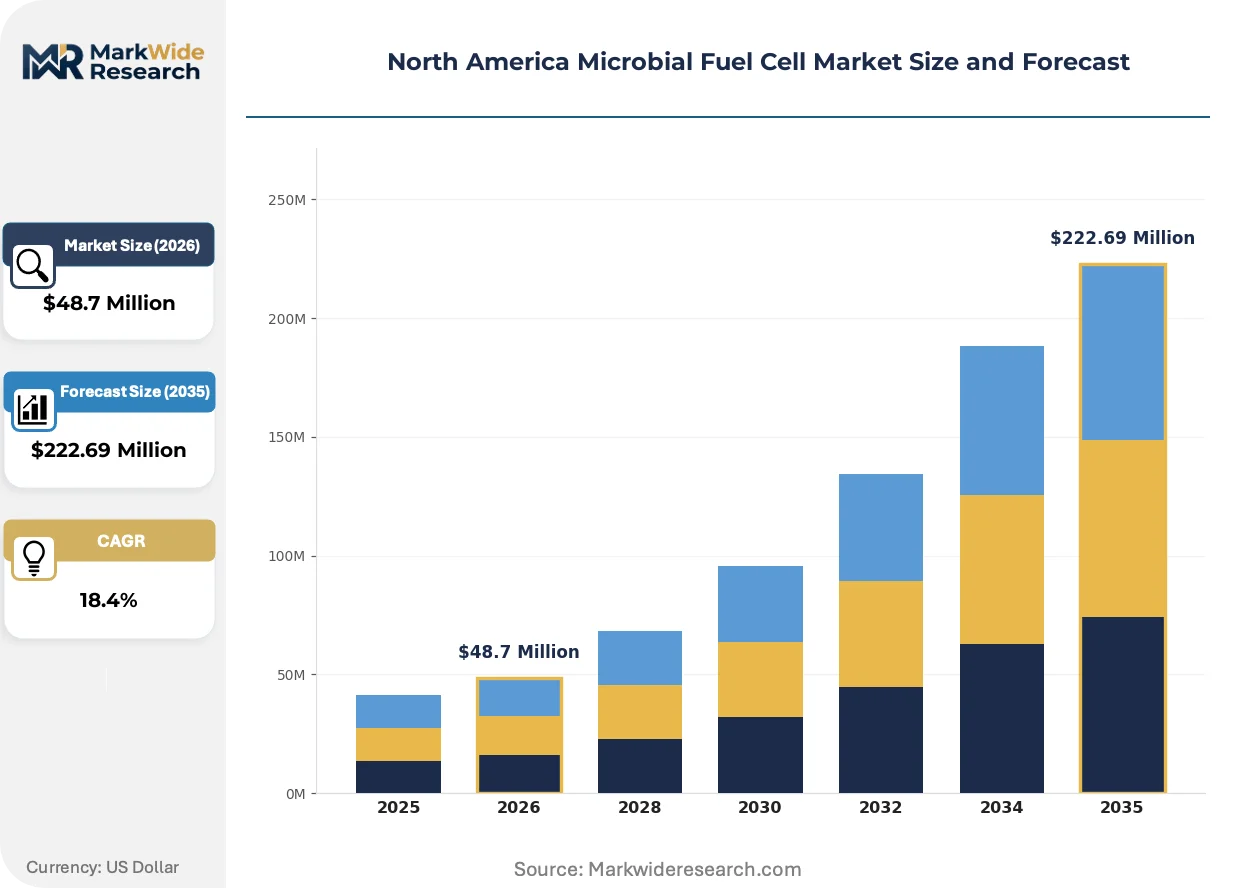
Market Dynamics
The U.S. EPA's tightening energy-neutrality mandates for municipal wastewater infrastructure are forcing treatment operators to evaluate self-powered biological platforms that simultaneously reduce aeration loads and generate on-site electricity. This regulatory compression is accelerating pilot-to-deployment transitions across the Great Lakes industrial corridor and California's Central Valley agricultural processing zones.
Growth Catalysts
- Clean Water Act Permit Evolution:The U.S. EPA's integration of energy-performance metrics into National Pollutant Discharge Elimination System permits rewards facilities achieving nutrient removal with net energy reduction, creating direct financial incentives for MFC adoption in municipal systems.
- Combined Sewer Overflow Mandates:Legacy manufacturing cities across the Great Lakes face federal consent decrees requiring distributed treatment capacity, positioning containerized MFC units as compliance pathways that avoid centralized infrastructure expansion.
- Conductive Polymer Electrodes:Advances in carbon-based composite materials are lowering activation losses and extending electrode operational lifespans, improving the levelized cost of electricity for continuous-flow wastewater applications.
Market Restraints
- Membrane Cost Concentration:Proton exchange membrane supply chains concentrate among specialty chemical producers in Germany and Japan, exposing North American system integrators to currency volatility and elongated procurement timelines for dual-chamber configurations.
- Power Density Limitations:Single-cell voltage outputs of 0.3-0.7 V necessitate complex series-parallel stacking architectures to reach practical thresholds for pump loads, increasing balance-of-system costs and electrical engineering complexity.
- Activated Sludge Incumbency:Established biological treatment infrastructure with decades of operational familiarity and maintenance ecosystems creates switching friction for municipal procurement committees evaluating novel electrochemical platforms.
Strategic Opportunities
- Remote Monitoring Applications:Low-power sensor networks in Canada's oil sands tailings ponds and Alaska's isolated mining operations present deployment contexts where membrane-less MFC designs' simplified maintenance outweighs efficiency penalties.
- California Renewable Energy Credits:State-level incentives for carbon-neutral water infrastructure operations improve project economics for utilities pursuing net-zero commitments, creating premium pricing environments for bioelectricity-generating treatment systems.
- Food and Beverage Processing Integration:High-organic-strength effluent streams from breweries and dairy operations in Wisconsin and Vermont offer substrate-rich environments where MFC power recovery accelerates payback periods against conventional anaerobic digestion.
Industry Challenges
- Electrochemist Talent Scarcity:The intersection of microbiology and electrical engineering required for MFC system optimization exceeds the training profiles of conventional wastewater operations staff, forcing utilities to recruit from academic research programs or fund specialized certification pipelines.
- Legacy SCADA Integration:Municipal treatment plants operate decades-old supervisory control architectures with proprietary communication protocols, complicating real-time monitoring of electrochemical reactor performance and electron transfer rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Microbial Fuel Cell Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $222.69 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Wastewater Treatment, Bioenergy Production, Environmental Monitoring, Soil Remediation Technology: Single Chamber, Dual Chamber, Membrane-less, Microbial Electrode End User: Municipalities, Industries, Research Institutes, Agricultural Facilities Component: Electrode, Membrane, Reactor, Power Management System |
| Companies Covered | MicrOrganic Technologies, Prongineer, Cambrian Innovation, Sainergy Tech, Electrochem Solutions, Emefcy Ltd, Cascade Clean Energy, Electro-Active Technologies, Protonex Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Microbial Fuel Cell Market Trends and Innovations
Electrochemical treatment architectures are fragmenting across membrane configurations as developers optimize reactor geometries for specific wastewater chemistries and scale targets. This specialization is compressing the gap between laboratory power densities and field-deployable system outputs.
Membrane electrode assemblies utilizing graphene-enhanced anode substrates are digitizing reactor performance monitoring through embedded conductivity sensors that transmit real-time biofilm health metrics. Food and beverage processors in California and New York are piloting these instrumented configurations to optimize organic loading rates. The technology is digitizing maintenance scheduling from reactive breakdown response to predictive intervention based on impedance signature analysis.
The U.S. EPA's forthcoming revisions to effluent limitation guidelines for nutrient pollution are mandating simultaneous nitrogen and phosphorus removal at facilities above defined flow thresholds. This regulatory compression favors biological electrochemical systems capable of directing electron flows toward specific reduction pathways. Municipal utilities in the Chesapeake Bay watershed and Florida's sensitive spring basins are pre-qualifying MFC vendors for upcoming permit renewals.
Performance-based service contracting is displacing capital procurement for distributed treatment assets among industrial effluent generators. Chemical manufacturers along the Texas Gulf Coast and Ontario's petrochemical corridor are contracting reactor uptime rather than purchasing hardware, transferring operational risk to technology providers. This shift concentrates most visibly in sectors facing variable production schedules and episodic high-strength discharge events.
North America Microbial Fuel Cell Market Segmentation
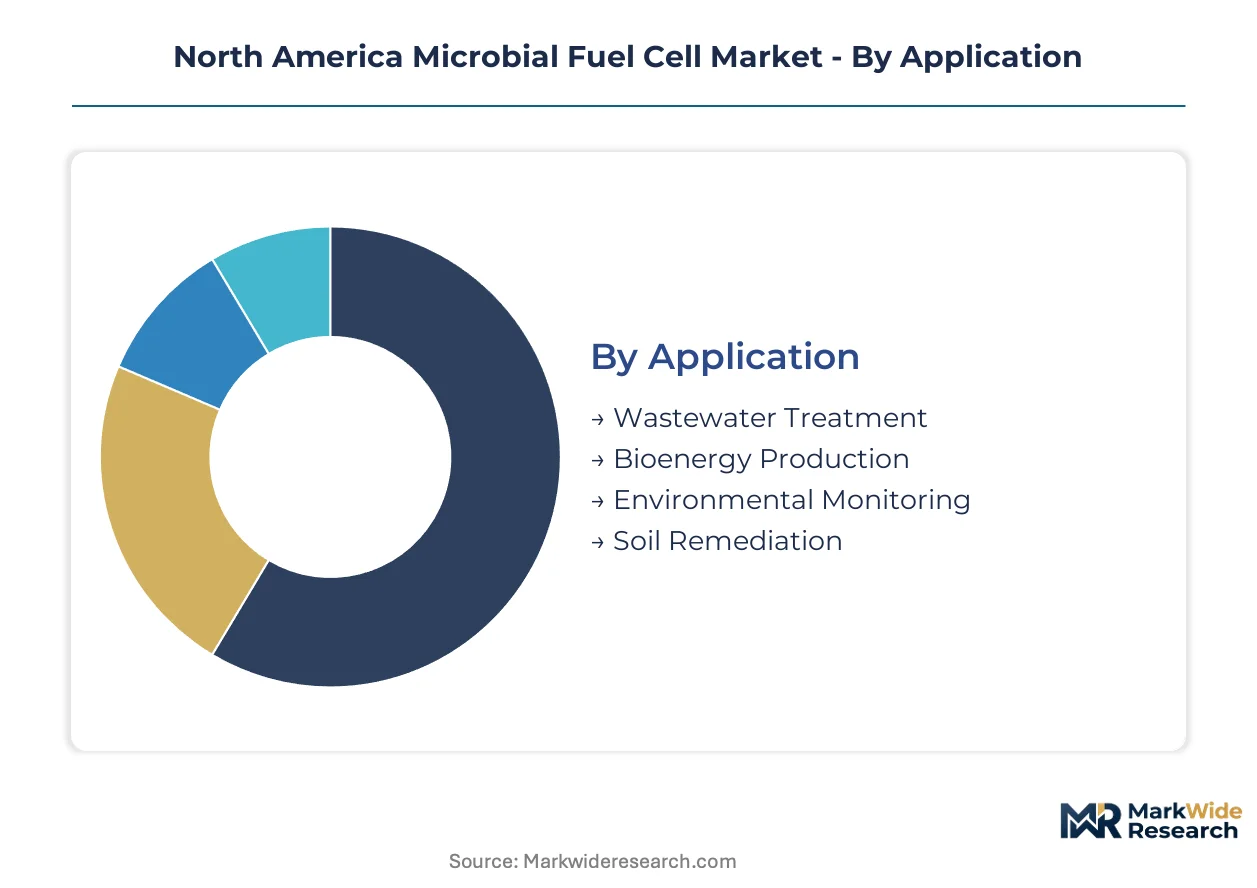
Segmentation in the North American microbial fuel cell market reveals distinct technology-application pairings that determine deployment economics. Each category maps specific reactor configurations to buyer capabilities and regulatory exposure across the United States and Canada.
Application:
Mature industrial effluent processing coexists with emerging environmental sensing deployments across the maturity spectrum.
- Wastewater Treatment:Municipal and food processing facilities deploy stacked MFC configurations to offset aeration energy while meeting Clean Water Act discharge permits. The Great Lakes industrial corridor concentrates demand as legacy cities face combined sewer overflow consent decrees requiring distributed biological treatment capacity.
- Bioenergy Production:High-organic-strength streams from breweries and dairy operations in Wisconsin and Vermont generate recoverable power densities that accelerate capital payback against conventional anaerobic digestion. California's renewable energy credit framework improves project economics for utilities pursuing carbon-neutral operations.
- Environmental Monitoring:Low-power sensor networks in Alaska's remote mining sites and Canada's oil sands tailings ponds utilize membrane-less designs where simplified maintenance outweighs efficiency trade-offs.
- Soil Remediation:Electrochemically active biofilms degrade petroleum hydrocarbons at former manufacturing sites across the U.S. Midwest, with electrode configurations optimized for clay-heavy substrates.
Wastewater Treatment retains volume leadership; Environmental Monitoring holds the steepest expansion curve.
Technology:
Cost tier stratification separates membrane-intensive designs from simplified field-deployable architectures.
- Dual Chamber:Proton exchange membrane separation enables precise substrate control and higher columbic efficiency for municipal utilities with skilled electrochemical operations staff. The U.S. EPA's tightening nutrient removal mandates favor these configurations in the Chesapeake Bay watershed where simultaneous nitrogen and phosphorus reduction determines permit compliance.
- Membrane-less:Eliminated membrane costs and reduced fouling sensitivity position these systems for agricultural runoff treatment and remote monitoring where technical maintenance access is limited. Simplified reactor geometries trade power density for operational reliability in Canada's distributed agricultural processing zones.
- Single Chamber:Compact integrated designs reduce footprint requirements for space-constrained industrial facilities along the Texas Gulf Coast petrochemical corridor.
- Microbial Electrode:Conductive polymer composite substrates lower activation losses and extend operational lifespan in continuous-flow configurations.
Dual Chamber commands premium pricing for compliance-critical applications; Membrane-less configurations are expanding most quickly in cost-sensitive remote deployments.
End User:
Customer type determines procurement complexity and service contracting preferences across the value chain.
- Municipalities:Public utilities in the Great Lakes region and California's Central Valley evaluate MFC platforms against activated sludge incumbency, with procurement committees weighing decades of operational familiarity against energy-neutrality mandates. Federal infrastructure funding channels increasingly prioritize novel biological treatment platforms.
- Industries:Food and beverage processors in New York and Vermont pilot instrumented configurations with embedded conductivity sensors for predictive maintenance scheduling.
- Research Institutes:Academic programs across the United States and Canada advance electrode material science and biofilm engineering for subsequent technology transfer to commercial system integrators.
- Agricultural Facilities:Dairy operations and crop processing cooperatives in the U.S. Midwest deploy containerized units for high-strength organic waste streams.
Municipalities dominate installed capacity; Agricultural Facilities show the steepest adoption trajectory as distributed treatment economics improve.
Component:
Supply concentration varies sharply between commodity electrodes and specialized membrane chemistries.
- Electrode:Carbon-based composite materials with graphene enhancement dominate anode substrates, with conductivity sensors enabling real-time biofilm health monitoring. Electro-Active Technologies and similar developers optimize conductive polymer formulations to reduce activation losses.
- Membrane:Proton exchange membrane supply chains concentrate among specialty chemical producers in Germany and Japan, exposing North American integrators to currency volatility and elongated procurement timelines for dual-chamber system builds.
- Reactor:Cambrian Innovation and Sainergy Tech compete on modularity, offering packaged and containerized units that reduce site-specific engineering overhead.
- Power Management System:Stacked cell architectures require complex series-parallel electrical engineering to reach practical voltage thresholds for pump loads and sensor networks.
Electrode components retain volume leadership; Power Management Systems hold the steepest innovation curve as balance-of-system costs compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal utilities and food processors anchor procurement decisions across the continent, with regulatory pressure from the U.S. EPA and Environment and Climate Change Canada dictating deployment timelines for electrochemical treatment platforms.
United States
The Great Lakes industrial corridor and California's Central Valley concentrate pilot-to-deployment transitions for MFC systems. The U.S. EPA's integration of energy-performance metrics into National Pollutant Discharge Elimination System permits rewards facilities achieving nutrient removal with net energy reduction. Legacy manufacturing cities in Michigan and Ohio face combined sewer overflow consent decrees requiring distributed treatment capacity.
Canada
Oil sands tailings ponds in Alberta and remote mining operations in the territories drive demand for membrane-less designs where simplified maintenance outweighs efficiency penalties. Environment and Climate Change Canada administers wastewater system regulations under the Fisheries Act, indirectly incentivizing bioelectricity-generating treatment platforms. Agricultural processing cooperatives in Saskatchewan and Manitoba deploy containerized units for high-strength organic waste streams.
Mexico
Breweries and dairy operations in Baja California and the central highlands generate substrate-rich environments where MFC power recovery accelerates payback periods. The country's national water commission has tightened discharge standards for industrial effluent, creating compliance pressure for food and beverage processors. Chemical manufacturers along the Gulf Coast petrochemical corridor evaluate performance-based service contracting for distributed treatment assets.
North America Microbial Fuel Cell Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single entity commands dominant market share. System integrators with packaged reactor offerings face pressure from electrode material developers and membrane technology suppliers. The competitive terrain separates into three archetypes: packaged system providers, component specialists, and research-to-commercial transfer entities. Strategic moves concentrate on technology licensing arrangements and strategic partnerships with municipal engineering firms.
Within the packaged system tier, Cambrian Innovation and Sainergy Tech exemplify contrasting approaches to modularity and site-specific engineering reduction. Electro-Active Technologies occupies a position among electrode material specialists, representing the conductive polymer composite segment. These three entities anchor the competitive landscape across distinct value chain positions without overlapping core competencies.
| Leading Market Players |
|---|
| MicrOrganic Technologies |
| Prongineer |
| Cambrian Innovation |
| Sainergy Tech |
| Electrochem Solutions |
| Emefcy Ltd |
| Cascade Clean Energy |
| Electro-Active Technologies |
| Protonex Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure between Germany and Japan for proton exchange membrane imports compresses margin structures for dual-chamber system integrators while widening pricing tier spreads between membrane-intensive and membrane-less configurations. This single-source dependency forces North American buyers into long-term offtake contracts indexed to specialty chemical feedstock benchmarks, reshaping procurement economics across municipal and industrial deployment contexts.
Pricing Analysis
Cost-plus contracts indexed to carbon composite and conductive polymer feedstock benchmarks dominate electrode component transactions, with membrane suppliers commanding premium pricing tied to yen-denominated resin costs. Three-tier pricing structure across premium, standard, and economy levels separates EPA-compliant nutrient removal systems from agricultural runoff units and remote monitoring configurations. Pricing pressure stems from activated sludge incumbency in municipal procurement committees, where decades of operational familiarity drive aggressive total-cost-of-ownership comparisons. Agricultural cooperatives exhibit highest price sensitivity due to seasonal cash flow constraints, while California utilities pursuing renewable energy credits show lowest sensitivity to capital expenditure premiums.
Supply Chain Analysis
Tariff exposure between Germany and Japan for fluoropolymer resin shipments concentrates supply risk for dual-chamber membrane electrode assemblies, exposing North American integrators to currency volatility and elongated procurement timelines. Electrode manufacturing draws from domestic carbon composite producers and South Korean graphene suppliers, with reactor fabrication anchoring in U.S. Great Lakes industrial corridor machine shops. Single-source vulnerability for proton exchange membrane chemistries forces utilities into strategic inventory positions or accelerated qualification of alternative membrane-less designs. Distribution runs through municipal engineering consultants and food processing EPC contractors rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement committee consolidation across the Great Lakes industrial corridor is shifting buyer power toward utilities capable of multi-site deployment commitments, fragmenting vendor access for single-project system integrators.
For Market Incumbents: Harden electrode material supply positions through backward integration into conductive polymer formulation or captive supply agreements with graphene-enhanced carbon substrate producers. Defend against membrane-less design encroachment by embedding real-time biofilm health monitoring as a bundled service layer that raises switching costs for municipal operators. Prioritize certification investment for simultaneous nitrogen-phosphorus removal configurations ahead of EPA effluent limitation guideline revisions. For New Entrants and Emerging Players: Pursue membrane-less reactor deployments in Canada's oil sands tailings ponds and Alaska's remote mining operations, where technical maintenance access constraints create penetrable whitespace absent from saturated municipal wastewater markets. Target agricultural processing cooperatives in Saskatchewan and Manitoba with containerized units priced against anaerobic digestion payback periods. Anchor go-to-market strategy through performance-based service contracting that transfers operational risk from capital-constrained buyers. For Investors and Strategic Acquirers: The market sits at a pilot-to-deployment transition phase that favors electrode material specialists with scalable conductive polymer formulations over packaged system integrators facing municipal procurement friction. Long-term viability across the analysis window rests on biofilm engineering capabilities that compress the laboratory-to-field power density gap. Acquisition target archetype: mid-cap developers with graphene-enhanced anode substrates and embedded sensor integration. The signal to watch is EPA infrastructure funding channel prioritization for novel biological treatment platforms versus incremental activated sludge upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Electrode Material Backward Integration | Captive supply of conductive polymer composites insulates margins from carbon feedstock volatility. |
| Membrane-less Design Qualification | Simplified reactor geometries unlock remote deployment contexts where maintenance access is constrained. |
| Real-time Biofilm Monitoring Integration | Embedded conductivity sensors transform maintenance scheduling from reactive to predictive intervention. |
| Performance-based Service Contracting | Uptime guarantees transfer operational risk to technology providers in variable discharge environments. |
| EPA Compliance Certification Investment | Pre-qualification for nutrient removal mandates secures position in Chesapeake Bay watershed procurements. |
Research Methodology
Desk research of EPA enforcement databases, Environment and Climate Change Canada regulatory filings, and municipal wastewater utility capital improvement plans preceded structured interviews with electrochemical reactor engineering directors, municipal procurement committee chairs, food processing plant managers, and conductive polymer material scientists. Primary fieldwork validated laboratory power density claims against field-deployed system outputs across Great Lakes and California Central Valley installations. Secondary triangulation incorporated customs data for proton exchange membrane imports, SEC filings from water infrastructure technology providers, and patent landscape analysis for graphene-enhanced electrode substrates. Bottom-up unit economics for stacked cell configurations were cross-checked against top-down market sizing from utility capital expenditure disclosures.
Forecast assumptions held fixed the EPA's trajectory toward energy-neutrality mandates and the current tariff structure for Japanese and German membrane imports, while varying municipal bond financing costs and renewable energy credit pricing across state jurisdictions. Segmentation modeling spanned reactor configuration, application context, end-user procurement sophistication, and regional regulatory stringency. CAGRs were derived from deployment pipeline analysis and payback period sensitivity to aeration energy cost inflation. Industry-specific inputs included biofilm acclimation timelines for high-strength organic substrates and electrode degradation curves under continuous-flow operation.
Macroeconomic conditions sit as an overlay; deviation in municipal infrastructure bond yields or yen-euro exchange rates for membrane feedstock procurement would shift the trajectory of dual-chamber versus membrane-less adoption curves. Forecasts reflect documented assumptions regarding EPA effluent guideline revision timing and federal infrastructure funding channel allocations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Global Micro Fuel Cells Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Germany Fuel Cell Market