
 High Voltage Air-cooled Battery Compartment Market | 2026-2036
High Voltage Air-cooled Battery Compartment Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Air-cooled Battery Compartment Market Insights
Aluminum alloy housings are hardening as the preferred structural material over steel in high voltage air-cooled battery compartments, cutting weight while improving thermal conductivity. Contemporary Amperex Technology leverages its captive die-casting capacity to control alloy sourcing costs across its Jiangsu production base. BYD anchors vertical integration from cell to compartment assembly, sustaining margin capture that competitors struggle to match. Shenzhen Envicool Technology specializes in modular forced-air architectures for industrial and marine applications, occupying a niche between automotive volume and custom project scale.
A high voltage air-cooled battery compartment is a sealed enclosure housing lithium-ion cell arrays at nominal voltages exceeding 60V, using ambient or forced airflow to maintain cell temperatures within 15°C to 35°C operating windows and prevent thermal runaway propagation. The assembly typically integrates flame-retardant polycarbonate or aluminum-composite barriers, IP67-rated sealing, and redundant fan or heat-pipe subsystems to enable passive-to-active cooling modulation. Modular compartments lead unit volume due to scalable retrofit compatibility with existing energy storage cabinets and electric bus platforms. Forced air cooling captures the fastest expansion trajectory as OEMs prioritize cost-efficient active thermal management over liquid-cooled alternatives in commercial vehicle segments. Custom compartments command the deepest margin pools where marine classification societies and mining equipment operators impose non-standard dimensional and ingress-protection requirements.
FDA and NHTSA guidelines in the United States, alongside China's NMPA and revised GB standards, are mandating compartment-level fire containment and thermal-event isolation testing before platform homologation. The EU's CE marking and RoHS directives constrain material composition choices for compartments exported into European electric bus and industrial storage supply chains. Stakeholders must monitor how divergent thermal-test protocols across regulators reshape engineering resource allocation and platform-variant proliferation.
Market Dynamics
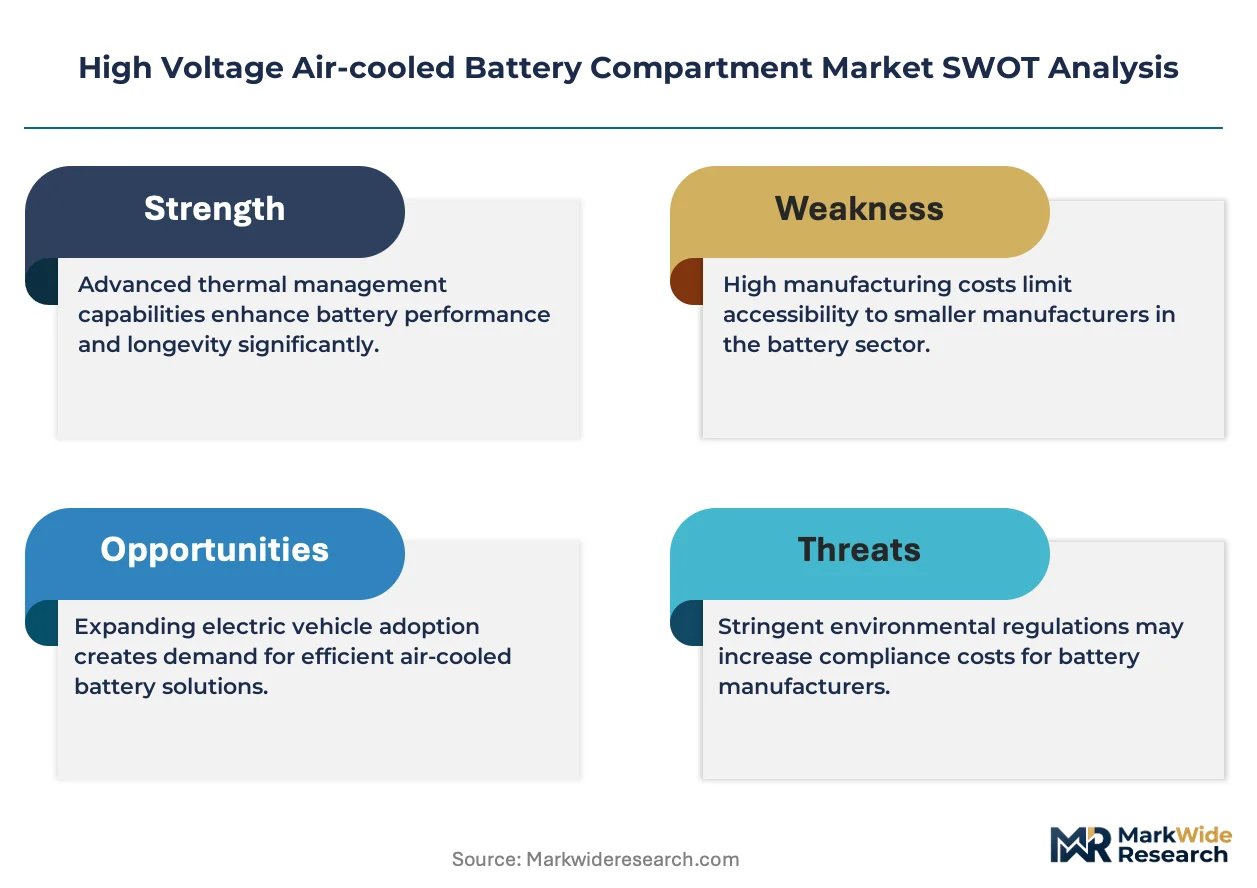
Forced-air thermal management architectures are compressing liquid-cooled alternatives in commercial electric vehicle procurement as battery energy densities climb and OEMs prioritize cost containment over peak thermal performance.
Growth Catalysts
- GB Standard Revisions:China's NMPA and MIIT are tightening compartment fire-resistance mandates under updated GB standards, compelling OEMs to upgrade thermal isolation systems and driving replacement demand across existing bus and truck fleets.
- Aluminum Alloy Adoption:Die-cast aluminum housings are displacing steel across Jiangsu and Zhejiang production corridors, cutting structural weight while improving heat dissipation coefficients for high-density cell configurations.
- Marine Classification Requirements:Non-standard IP-rating and dimensional specifications from classification societies are creating premium custom compartment demand outside automotive volume segments.
Market Restraints
- Aluminum Price Volatility:Primary aluminum ingot costs fluctuate with energy pricing, compressing margins for die-casting-dependent suppliers locked into fixed-price OEM contracts.
- Jiangsu-Zhejiang Supply Concentration:CATL and BYD ecosystems anchor over 70% of Asian compartment fabrication, creating single-source vulnerability for tier-two integrators without backward alloy sourcing.
- Thermal Performance Ceiling:Forced-air systems hit asymptotic cooling limits around 4C discharge rates, excluding high-performance passenger EV segments from addressable market expansion.
Strategic Opportunities
- Retrofit Energy Storage Cabinets:Modular compartment architectures enable scalable integration into existing grid-scale battery installations without full system replacement, opening aftermarket revenue streams.
- India PLI Scheme Alignment:India's production-linked incentive scheme for advanced chemistry cell manufacturing is attracting compartment suppliers to Gujarat and Tamil Nadu industrial corridors.
- Heat-Pipe Convergence:Hybrid forced-air and phase-change heat-pipe configurations are emerging for mining equipment applications where ambient temperatures exceed passive cooling thresholds.
Industry Challenges
- Thermal Simulation Talent Scarcity:Computational fluid dynamics specialists with battery-specific expertise command premium compensation, constraining mid-tier engineering teams from accelerating design cycles.
- Homologation Timeline Compression:Divergent fire-containment test protocols across NHTSA, NMPA, and EU type-approval frameworks force parallel certification tracks, draining R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Air-cooled Battery Compartment Market |
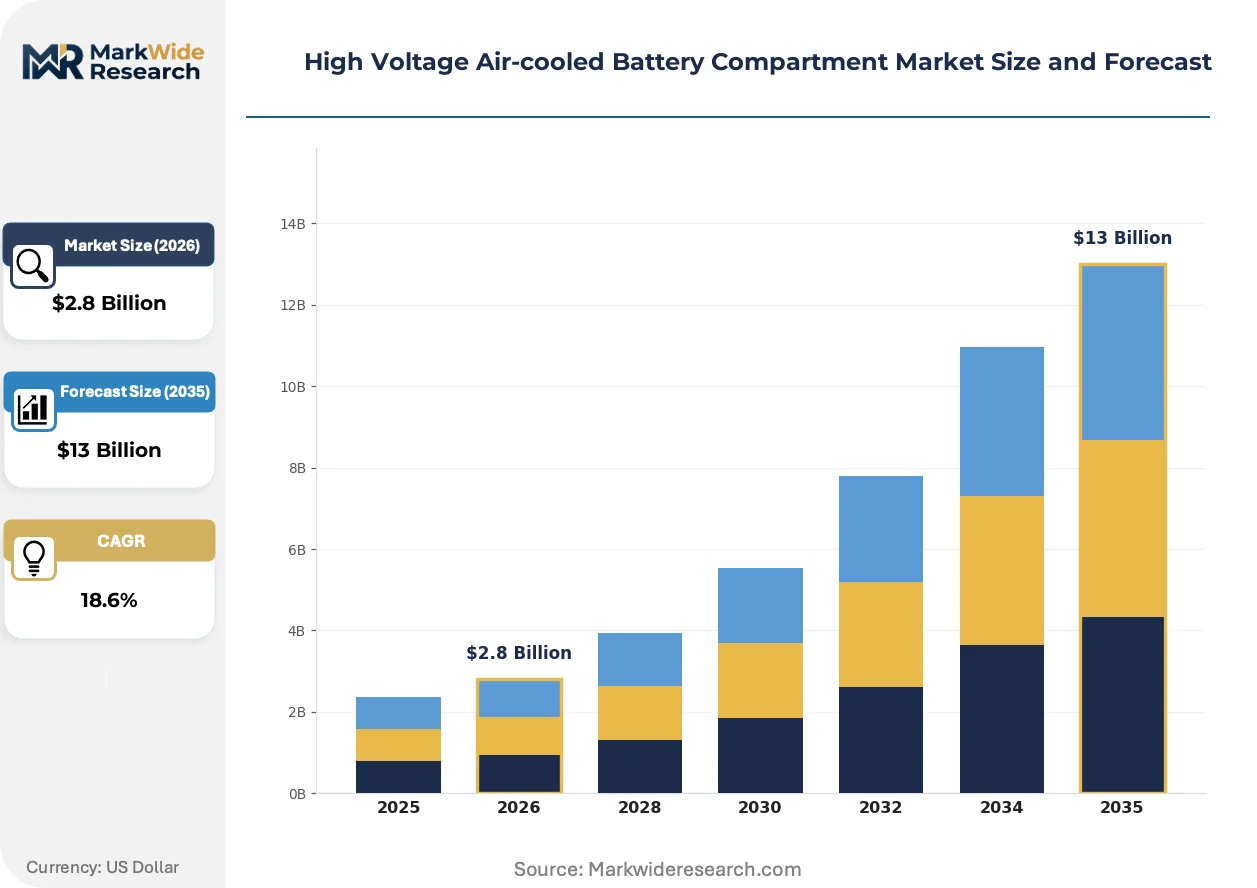
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Compartments, Integrated Compartments, Custom Compartments, Standard Compartments Cooling Technology: Passive Cooling, Forced Air Cooling, Heat Pipe Cooling, Fan-Assisted Cooling Application: Electric Vehicles, Industrial Equipment, Renewable Energy Storage, Marine Vessels End User: OEM Manufacturers, Tier-1 Suppliers, Fleet Operators, Research Institutions |
| Companies Covered | Contemporary Amperex Technology, BYD, EVE Energy, Huawei Digital Power, Sungrow Power Supply, TBEA, Shenzhen Envicool Technology, Jiangsu Linyang Energy, Zhejiang Narada Power Source, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Air-cooled Battery Compartment Market Trends and Innovations
Active thermal management architectures are fragmenting procurement patterns as buyers prioritize modularity over integrated liquid systems, while regulatory fire-isolation mandates reshape engineering priorities.
Phase-change material inserts are decentralizing thermal load distribution within aluminum-composite housings. Commercial bus operators in Zhejiang are specifying PCM-enhanced compartments for routes with frequent stop-start cycling. This decentralizing thermal architecture is compressing fan redundancy requirements and enabling lighter subsystem configurations.
REACH and RoHS directives are constraining flame-retardant polycarbonate formulations for EU-bound electric bus supply chains. Compounders must reformulate halogen-free barrier materials without sacrificing UL94 V-0 ratings. Industrial storage OEMs exporting to European markets are absorbing 12-18 month material qualification cycles to maintain CE marking compliance.
Fleet operators are unbundling compartment procurement from full battery system contracts, engaging directly with Jiangsu die-casters for aftermarket retrofits. This disintermediation is compressing integrator margins while expanding addressable market for modular suppliers with standalone IP67 sealing capabilities. Mining equipment lessors in Western Australia are driving this pattern through specification of field-replaceable thermal subassemblies.
High Voltage Air-cooled Battery Compartment Market Segmentation
Segmentation in the High Voltage Air-cooled Battery Compartment Market reveals how procurement patterns split between automotive volume buyers and specialized industrial operators with divergent thermal specifications. Each dimension exposes distinct margin structures and engineering resource requirements that reshape competitive positioning across supplier tiers.
Product Type:
Buyers select compartment architectures based on integration depth with existing platform designs and retrofit flexibility requirements.
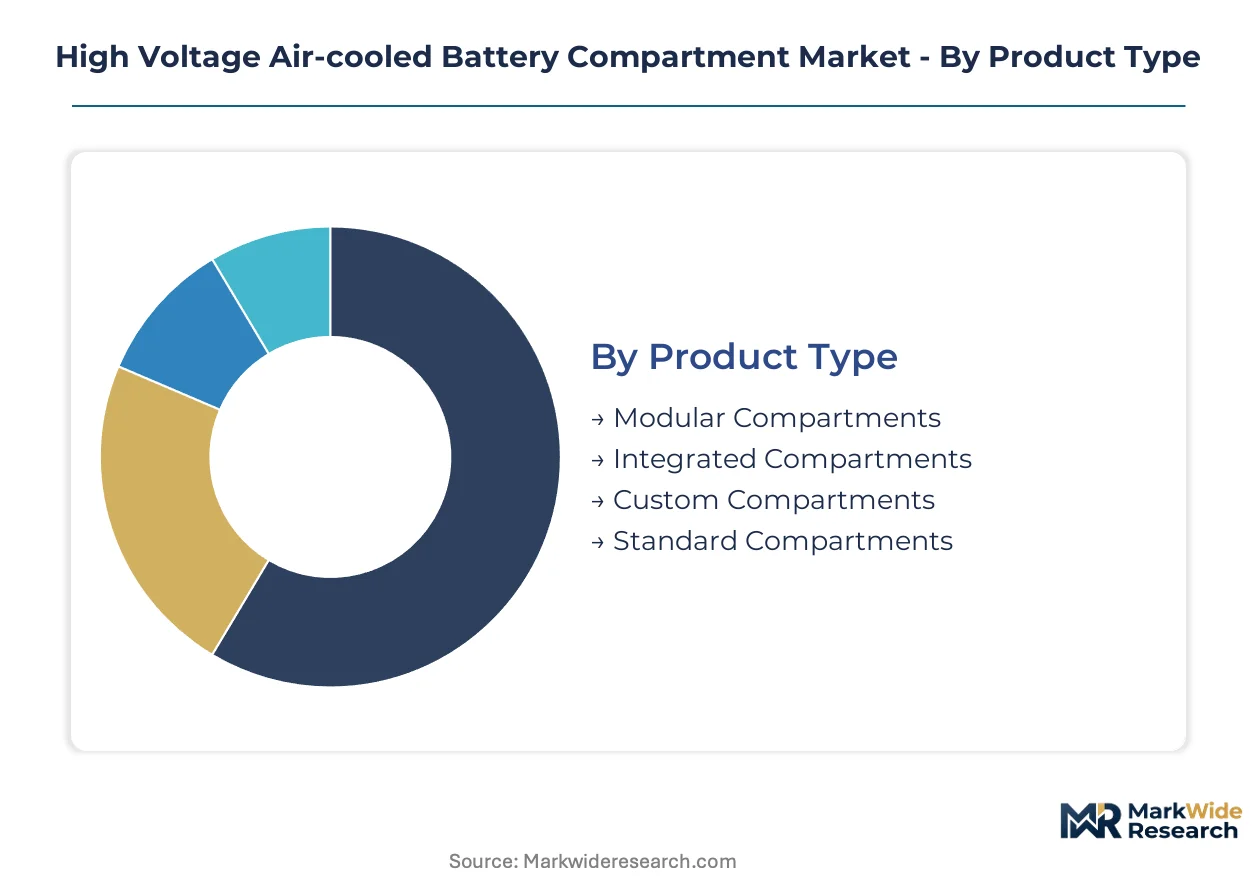
- Modular Compartments:These assemblies feature standardized IP67-rated sealing and field-replaceable fan subsystems that enable scalable retrofit compatibility with existing energy storage cabinets and electric bus platforms. Fleet operators in China's Jiangsu province are specifying these for aftermarket thermal upgrades as GB standard revisions mandate enhanced fire isolation.
- Custom Compartments:Non-standard dimensional and ingress-protection configurations designed to marine classification society specifications or mining equipment operator requirements command substantial engineering premiums. Western Australian mining lessors are driving demand through specification of field-replaceable thermal subassemblies.
- Integrated Compartments:Cell-to-housing assemblies with captive die-cast aluminum sourcing and pre-validated thermal interfaces.
- Standard Compartments:Fixed-dimension enclosures targeting homogeneous electric bus and light commercial vehicle platforms.
Volume sits with Modular Compartments; growth tilts toward Custom Compartments.
Cooling Technology:
Technology selection trades off capital expenditure against thermal performance ceilings and maintenance complexity.
- Forced Air Cooling:Active thermal management using redundant fan arrays and ducted airflow channels maintains cell temperatures within 15°C to 35°C operating windows at discharge rates up to 4C. Electric vehicle OEM manufacturers are scaling procurement of these systems as battery energy densities climb and cost containment priorities displace liquid-cooled alternatives in commercial vehicle segments.
- Passive Cooling:Convection-dependent architectures with aluminum-composite heat spreaders and no moving parts.
- Heat Pipe Cooling:Phase-change thermal transfer systems enabling passive-to-active modulation for mining equipment applications where ambient temperatures exceed conventional forced-air thresholds.
- Fan-Assisted Cooling:Hybrid configurations combining low-speed ambient circulation with supplemental active management.
Forced Air Cooling dominates current procurement; Heat Pipe Cooling is climbing the fastest as hybrid architectures penetrate industrial applications.
Application:
End-use thermal loads and duty cycles determine compartment specification stringency and certification requirements.
- Electric Vehicles:High-volume automotive platforms with standardized GB and NHTSA fire-containment testing protocols.
- Industrial Equipment:Mining and material handling machinery requiring extreme-ingress protection and shock-resistant aluminum housings.
- Renewable Energy Storage:Grid-scale battery installations leveraging modular retrofit compatibility to extend existing cabinet service life without full system replacement.
- Marine Vessels:Classification society-mandated dimensional and IP-rating specifications creating premium custom compartment demand outside automotive volume economics.
Electric Vehicles anchor current volume; Marine Vessels is gaining share fastest as classification requirements tighten.
End User:
Procurement authority concentration determines pricing leverage and technical specification influence.
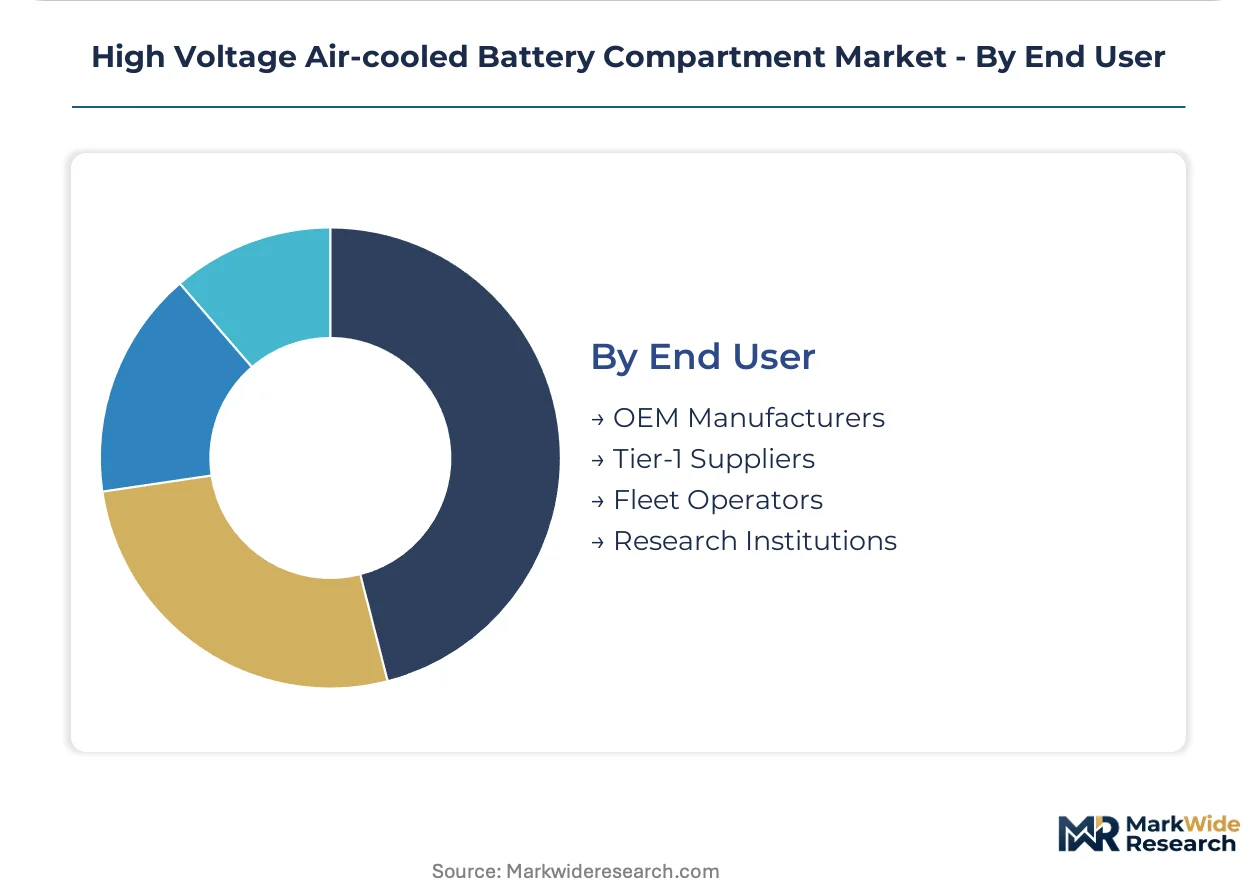
- OEM Manufacturers:Vertically integrated battery system producers with captive die-casting capacity and backward alloy sourcing control.
- Tier-1 Suppliers:Intermediate integrators facing margin compression as fleet operators disintermediate compartment procurement from full battery system contracts.
- Fleet Operators:Commercial bus and industrial equipment lessors engaging directly with Jiangsu die-casters for aftermarket retrofits and standalone IP67 sealing capabilities.
- Research Institutions:Low-volume buyers prioritizing thermal simulation validation and non-standard cell configurations.
OEM Manufacturers capture current volume; Fleet Operators is expanding most quickly as disintermediation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate die-casting capacity and battery system integration, anchoring procurement corridors for forced-air thermal management components across Asia-Pacific and export markets.
China
Jiangsu and Zhejiang provinces host CATL and BYD supplier ecosystems fabricating over seventy percent of Asian compartment output. NMPA and MIIT revised GB standards mandate enhanced fire-resistance and IP-rating compliance, compelling fleet-wide thermal upgrades. Ningbo and Suzhou industrial clusters specialize in aluminum die-casting for modular retrofit architectures serving electric bus operators.
Germany
Commercial vehicle OEMs in Baden-Württemberg and Bavaria specify forced-air compartments for municipal bus electrification programs. KBA type-approval frameworks enforce thermal-event isolation testing parallel to EU CE marking requirements. Stuttgart-area engineering consultancies supply computational fluid dynamics validation for hybrid heat-pipe configurations entering mining equipment applications.
United States
NHTSA guidelines and California Air Resources Board mandates drive compartment-level fire containment certification for electric school and transit bus procurements. Michigan and Ohio industrial corridors host tier-one integrators sourcing aluminum housings from Yangtze River Delta die-casters. Fleet operators in Texas and Florida engage directly with compartment fabricators for aftermarket thermal retrofits.
India
PLI scheme incentives for advanced chemistry cell manufacturing attract compartment suppliers to Gujarat and Tamil Nadu industrial corridors. BIS standards for battery enclosure safety are converging with NHTSA thermal-test protocols, accelerating design cycle investments. Chennai and Ahmedabad production bases target modular architectures for grid-scale energy storage retrofits.
Australia
Western Australian mining lessors specify custom IP-rated compartments with field-replaceable thermal subassemblies for extreme-ambient operations. The country's national mining safety regulator mandates flame-retardant barrier compliance for underground battery-electric vehicle deployments. Perth-based engineering firms coordinate with Zhejiang fabricators on non-standard dimensional specifications.
High Voltage Air-cooled Battery Compartment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive die-casting operations commanding structural advantages in automotive volume while independent fabricators capture custom industrial premiums. The supplier base concentrates around three archetypes: vertically integrated battery OEMs with in-house housing production, modular subsystem specialists serving aftermarket retrofit demand, and custom engineering houses addressing marine and mining classification requirements. M&A activity targets computational fluid dynamics talent acquisition, and capacity expansion focuses on aluminum alloy die-casting lines in Jiangsu and Zhejiang corridors.
Among China-based integrated producers, Contemporary Amperex Technology and BYD exemplify the captive-supply archetype, controlling alloy sourcing and compartment fabrication within unified cell-to-system operations. Shenzhen Envicool Technology occupies a position between automotive volume and custom project scale, representing the modular specialist tier serving industrial and marine applications outside standard EV platform economics.
| Leading Market Players |
|---|
| Contemporary Amperex Technology |
| BYD |
| EVE Energy |
| Huawei Digital Power |
| Sungrow Power Supply |
| TBEA |
| Shenzhen Envicool Technology |
| Jiangsu Linyang Energy |
| Zhejiang Narada Power Source |
| Others |
Pricing and Supply Chain Analysis
China's NMPA fire-resistance mandates under revised GB standards gate qualified supply access and premium-tier pricing for compliant compartment fabricators serving electric bus OEMs. Jiangsu die-casters with validated thermal isolation certifications command structural premiums while uncertified suppliers face exclusion from fleet procurement tenders.
Pricing Analysis
Lead-time compression drives pricing stratification across Jiangsu and Zhejiang production corridors, with spot inventory discounts running against premium quotes for expedited GB-compliant deliveries. Project-based contract structures dominate, with price differentiation hinging on IP-rating certification tier and volume scale commitments. Pricing pressure stems from aluminum ingot cost volatility squeezing die-casting margins under fixed-price OEM agreements. Fleet operators exhibit highest price sensitivity, while marine classification societies demonstrate lowest sensitivity due to non-standard specification requirements.
Supply Chain Analysis
GB standard qualification gates supplier participation, with certified Jiangsu and Zhejiang fabricators anchoring over seventy percent of Asian compartment output. Primary aluminum ingot, flame-retardant polycarbonate formulations, and redundant fan subsystems constitute critical input dependencies. Single-source vulnerability concentrates risk around CATL and BYD captive supply ecosystems. Distribution runs through tier-one integrators to OEM manufacturers, with direct fleet operator procurement emerging as a disintermediation channel for aftermarket retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where China's NMPA GB standard revisions erect regulatory moats favoring incumbents with pre-qualified thermal isolation architectures.
For Market Incumbents: Anticipate margin compression from aluminum price volatility by securing backward alloy sourcing agreements with Jiangsu smelters. Deepen certification investment in hybrid heat-pipe configurations to defend against emerging modular specialists targeting mining equipment applications. For New Entrants and Emerging Players: Begin with India's Gujarat and Tamil Nadu industrial corridors under PLI scheme incentives, where BIS standards convergence creates lower qualification barriers than China's GB regime. Target grid-scale energy storage retrofits as the most penetrable segment, leveraging modular IP67 architectures for aftermarket cabinet integration. For Investors and Strategic Acquirers: M&A activity targeting computational fluid dynamics talent pools is the leading indicator that thermal simulation scarcity will persist as a structural bottleneck. Long-term viability favors acquisition of Jiangsu die-casters with captive alloy sourcing and validated GB compliance, positioning for fleet-wide thermal upgrade cycles. Watch for marine classification society specification releases as inflection signals for custom compartment premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Sourcing | Jiangsu smelter partnerships insulate die-casters from LME price volatility under fixed OEM contracts. |
| GB Standard Certification Investment | NMPA thermal isolation validation unlocks electric bus procurement tenders excluding uncertified competitors. |
| Computational Fluid Dynamics Talent Acquisition | Battery-specific CFD specialists compress design cycles for hybrid heat-pipe configurations in mining applications. |
| Modular Retrofit Architecture Development | Field-replaceable IP67 subassemblies capture fleet operator disintermediation demand outside tier-one integrator channels. |
| Marine Classification Society Partnership | Non-standard dimensional specifications from DNV or Lloyd's Register open premium custom compartment revenue pools. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with battery system procurement leads, thermal management engineering directors, die-casting plant managers, and fleet operator maintenance heads. NMPA GB standard documentation, MIIT industry bulletins, aluminum trade flow statistics, and OEM tender disclosures supplied validation layers. Bottom-up compartment shipment tallies reconciled with top-down electric bus and energy storage deployment forecasts.
Data-stream reconciliation across the projection horizon employed multi-dimensional segmentation modeling across cooling technology tier, compartment architecture type, application end-use, and regional production cluster. CAGRs derived from fitted growth curves incorporating battery energy density trajectories, regulatory mandate implementation schedules, and aluminum price scenario bands. Industry-specific inputs included GB standard revision timelines and marine classification society specification release patterns.
Underlying measurement precision varies by segment; modular electric vehicle applications carry tighter precision than custom marine configurations due to standardized platform volumes. Forecasts embed assumptions regarding NMPA enforcement consistency and aluminum supply chain stability. A model refresh is warranted upon material change in GB standard thermal-test protocol adoption rates or primary aluminum ingot cost regime shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Inverter Battery Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Europe SLI Battery Market
Batteries
Portable Battery Powered Products Market
Batteries
Myanmar Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
US Solar Battery Market
Batteries
Lithium Starters Market
Batteries
Stationary Lead-Acid Battery Market
Batteries
Electric Battery Market
Batteries
DMC for Battery Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
Portable Battery Market
Batteries
PVT Battery Panel Market