
 Graphene Solar Cell Market | 2026-2036
Graphene Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Solar Cell Market Intelligence
The qualification cycle for IEC 61215 certification is collapsing the time required for new material validation, accelerating market entry for novel cell designs. Samsung Advanced Institute of Technology leverages its deep research capabilities in advanced materials. Versarien plc specializes in producing high-quality graphene materials suitable for photovoltaic applications. NanoXplore Inc. competes on manufacturing scalability for its graphene powder products.
A graphene solar cell is a photovoltaic device that incorporates graphene, a single atomic layer of carbon, to enhance performance. Its exceptional optical transparency and high charge carrier mobility are leveraged to create more efficient and flexible solar energy converters. Graphene-based perovskite cells represent a high-growth product category due to their potential for superior power conversion efficiency. The Chemical Vapor Deposition technology segment is critical for producing the high-purity graphene required for advanced applications like building integrated photovoltaics.
Regulatory compliance is shaped by multiple international frameworks. The EU's REACH regulation governs the registration of graphene as a chemical substance, while the US EPA sets standards for its production emissions. In China, GB standards dictate the quality and safety requirements for new energy materials. Stakeholders must now decide whether to pursue proprietary material synthesis or secure long-term supply agreements for high-purity graphene.
Market Dynamics
The acceleration of material validation, driven by the collapsing qualification cycle for IEC 61215 certification, is the central force shaping the market. This dynamic allows novel cell designs incorporating advanced materials like graphene to move from laboratory to commercial production faster than ever before.
Growth Catalysts
- Perovskite Cell Efficiency:Graphene-based perovskite solar cells demonstrate the potential for superior power conversion efficiency, attracting significant research and development investment aimed at overcoming stability challenges and achieving commercial viability.
- Wearable Electronics Demand:The need for lightweight, flexible, and transparent power sources for wearable devices and smart textiles provides a dedicated demand stream for graphene solar cells, which outperform rigid alternatives in these applications. *Manufacturing Advancements: Improvements in Chemical Vapor Deposition (CVD) technology, particularly in research hubs in South Korea and Germany, are enabling the production of larger, higher-quality graphene sheets, which is critical for scaling up cell manufacturing.
Market Restraints
- High Production Costs:The synthesis of high-purity, defect-free graphene suitable for photovoltaic applications remains an expensive and energy-intensive process, limiting cost-competitiveness against established silicon-based solar technologies.
- Material Degradation:Perovskite materials, often used in conjunction with graphene for high-efficiency cells, are notoriously unstable and degrade quickly when exposed to moisture and oxygen, posing a significant barrier to long-term operational reliability.
- Substitution by Alternatives:Other transparent conductive materials, such as silver nanowires and conductive polymers, present a viable substitution threat in certain flexible electronic applications, competing directly with graphene on cost and ease of integration.
Strategic Opportunities
- Building-Integrated Photovoltaics:The unique transparency and flexibility of graphene solar cells create significant opportunities in the BIPV market, allowing for the creation of power-generating windows, facades, and skylights.
- Automotive Sector Integration:The automotive industry's push for electric vehicles and enhanced in-cabin electronics opens a new application frontier, with potential uses in panoramic sunroofs, dashboards, and other surfaces to power auxiliary systems.
- Flexible Consumer Electronics:Beyond wearables, there is a substantial opportunity in powering a new generation of flexible and foldable consumer electronics, such as rollable displays and e-paper, where integrated, unobtrusive power sources are essential.
Industry Challenges
- Standardization Gaps:A lack of universally accepted standards for graphene material characterization, as governed by bodies like ISO and IEC, creates inconsistency in the supply chain and complicates quality control for cell manufacturers.
- Integration Complexity:Integrating graphene deposition and transfer processes into existing, high-volume silicon photovoltaic manufacturing lines presents significant technical and capital expenditure challenges, slowing adoption by incumbent producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Solar Cell Market |
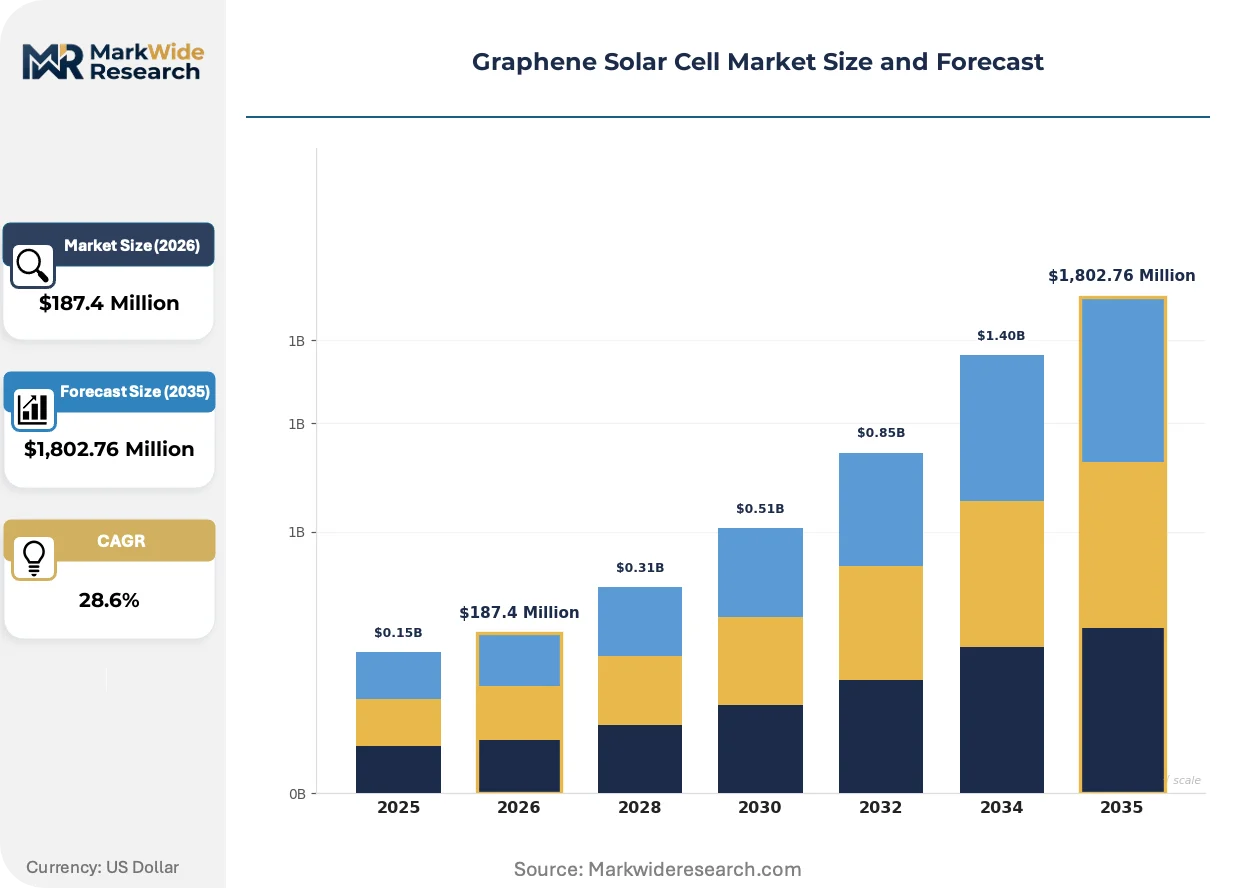
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-layer Graphene Cells, Multi-layer Graphene Cells, Graphene-based Perovskite Cells, Hybrid Graphene Cells, Thin-film Graphene Cells Technology: Chemical Vapor Deposition, Liquid Phase Exfoliation, Molecular Beam Epitaxy, Electrochemical Deposition, Physical Vapor Deposition Application: Building Integrated Photovoltaics, Wearable Electronics, Power Generators, Telecommunication Equipment, Off-grid Power Systems End User: Electric Vehicle Manufacturers, Aerospace Corporation, Consumer Electronics Firms, Utility Providers, Defense Contractors |
| Companies Covered | Versarien plc, Graphene Manufacturing Group, Samsung Advanced Institute of Technology, HydroGraph Clean Power, First Graphene, Dongxu Optoelectronic Technology, NanoXplore Inc., Directa Plus, Global Graphene Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Solar Cell Market Strategic Shifts & Innovations
Material science breakthroughs are enabling new solar cell form factors and applications. This evolution prompts regulatory frameworks like the EU's REACH to adapt, creating a new compliance landscape for producers of novel materials like graphene.
Graphene-based perovskite solar cells utilize the material's transparency and conductivity to boost photovoltaic performance. The flexible electronics and building-integrated photovoltaics sectors are key early adopters of this technology. This advanced cell design is supplanting traditional rigid silicon in applications where light weight, flexibility, and transparency are non-negotiable design requirements.
The EU's REACH regulation directly impacts the market by governing the registration and evaluation of graphene as a chemical substance. This framework mandates that producers provide extensive data on material properties and safety, which adds a significant compliance burden. Cell manufacturers operating within or exporting to the EU are most affected, as they must ensure their graphene suppliers meet these stringent requirements.
A distinct shift in purchasing behavior toward establishing long-term supply agreements for high-purity graphene is evident. This model replaces older, transactional spot-market buys, providing cell developers with critical consistency in material quality and supply chain predictability. This trend is most pronounced in research-intensive hubs like Germany and South Korea, where consistent inputs are vital for advanced R&D.
Graphene Solar Cell Market Segmentation
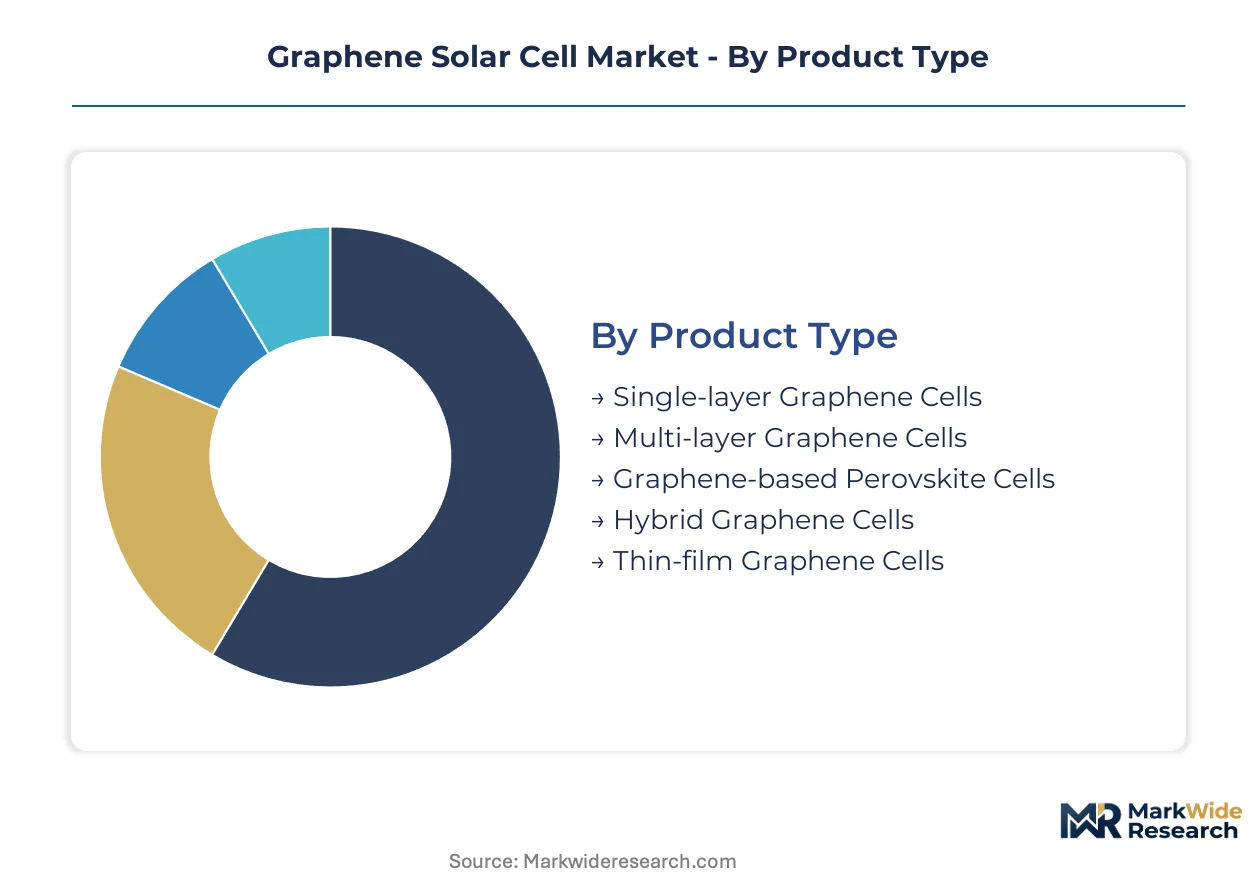
Market segmentation provides a granular understanding of the Graphene Solar Cell market's structure, highlighting distinct product offerings, technological approaches, application areas, and end-user demands. This breakdown is crucial for identifying targeted growth opportunities and developing tailored market strategies across the value chain.
Product Type:
Margin pools within the product type category delineate profitability across different graphene solar cell designs, reflecting material costs, manufacturing complexity, and performance advantages.
- Graphene-based Perovskite Cells:These cells integrate graphene with perovskite materials, leveraging graphene's transparency and conductivity to achieve superior power conversion efficiency. Demand is concentrating in research-intensive hubs in South Korea and Germany, driven by the pursuit of next-generation high-performance photovoltaics.
- Hybrid Graphene Cells:Combining graphene with other advanced materials, these cells are engineered for specific performance enhancements such as improved stability or flexibility. The automotive sector and specialized consumer electronics applications are driving demand for these customized solutions.
- Single-layer Graphene Cells:Comprising a single atomic layer of carbon, these cells offer exceptional optical transparency for niche applications.
- Multi-layer Graphene Cells:These cells use several layers of graphene, balancing conductivity and cost-effectiveness for broader industrial adoption.
- Thin-film Graphene Cells:Characterized by their minimal thickness, these cells are suitable for flexible and lightweight power solutions.
Multi-layer Graphene Cells hold installed capacity. Graphene-based Perovskite Cells are rotating up the share rankings.
Technology:
Cost tiers in technology segments reflect the investment required for equipment, precursors, and operational expertise, directly influencing the final product's economic viability.
- Chemical Vapor Deposition:This technique is critical for producing high-purity, large-area graphene sheets with precise control over layer thickness and quality. Research and development in South Korea and Germany focus on scaling CVD for advanced applications like building integrated photovoltaics.
- Liquid Phase Exfoliation:A more cost-effective method for graphene production, LPE yields graphene flakes suitable for various photovoltaic applications, particularly where high throughput is prioritized over ultra-high purity. Demand for LPE-produced graphene is expanding in flexible electronics manufacturing.
- Molecular Beam Epitaxy:MBE offers atomic-level precision for graphene growth but remains a high-cost, low-throughput method primarily for advanced research.
- Electrochemical Deposition:This method provides a versatile and scalable approach for depositing graphene films onto various substrates.
- Physical Vapor Deposition:PVD techniques are employed for depositing thin graphene films, offering control over material properties for specific device architectures.
The Chemical Vapor Deposition technique leads in adoption. Liquid Phase Exfoliation is rapidly expanding its commercial footprint.
Application:
Volume considerations within application areas highlight the scale of deployment and the specific market needs driving the integration of graphene solar cells.
- Wearable Electronics:This segment demands lightweight, flexible, and transparent power sources, making graphene solar cells an ideal fit for smartwatches, fitness trackers, and smart textiles. The need for unobtrusive power solutions in consumer devices drives significant volume.
- Building Integrated Photovoltaics:BIPV applications leverage the unique transparency and flexibility of graphene cells to create power-generating windows, facades, and skylights. Architectural innovation and green building initiatives in Europe are accelerating adoption in this segment.
- Power Generators:Graphene solar cells can contribute to portable and distributed power generation solutions.
- Telecommunication Equipment:Integration into remote sensors and communication devices benefits from the cell's low weight and durability.
- Off-grid Power Systems:These systems utilize graphene solar cells for reliable energy supply in remote or underserved areas.
Demand for Wearable Electronics applications continues to grow. Building Integrated Photovoltaics applications are seeing accelerated integration.
End User:
Customer type dynamics reveal the specific requirements, purchasing behaviors, and integration challenges faced by different industries adopting graphene solar cell technology.
- Consumer Electronics Firms:These firms require compact, flexible, and aesthetically pleasing power solutions for devices like smartphones, tablets, and wearable gadgets. Rapid product cycles and a focus on miniaturization define their engagement with graphene solar cell suppliers.
- Electric Vehicle Manufacturers:The automotive industry seeks lightweight, efficient power sources for auxiliary systems, panoramic sunroofs, and interior components in electric vehicles. Integration challenges and long qualification cycles characterize demand from this sector.
- Aerospace Corporation:Aerospace applications demand ultra-lightweight and highly durable power solutions for satellites and unmanned aerial vehicles.
- Utility Providers:Utilities explore graphene solar cells for distributed generation and grid-support applications.
- Defense Contractors:Military applications value robust, portable, and reliable power for field equipment and specialized vehicles.
The Consumer Electronics Firms sector is a foundational market. Electric Vehicle Manufacturers end-users are exploring novel integration pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global shipping lanes underwrite the distribution of specialized materials for graphene solar cells. This infrastructure facilitates the movement of high-purity graphene precursors and finished components across continents. Key manufacturing and research centers depend on efficient logistics to support advanced material development and commercialization.
South Korea
Demand from consumer electronics firms and advanced display manufacturers drives innovation in South Korea. The MFDS oversees safety standards for advanced materials, impacting new product introductions. Seoul's research clusters, including university labs, focus on leveraging graphene for flexible display integration and energy storage solutions.
Germany
The automotive sector seeks lightweight power solutions for electric vehicles. The EU's REACH regulation governs graphene as a chemical substance, influencing material sourcing. Research hubs in Dresden and Aachen concentrate on scaling Chemical Vapor Deposition for high-quality graphene sheets.
China
Wearable electronics demand drives high-volume production for compact power sources in China. GB standards dictate stringent quality and safety requirements for new energy materials, influencing market entry. The Yangtze River Delta region hosts numerous manufacturers accelerating graphene solar cell adoption in consumer devices.
United States
The aerospace industry seeks ultra-lightweight and durable power solutions for specialized equipment. The US EPA sets standards for production emissions, affecting graphene manufacturing processes. Silicon Valley's tech ecosystem fosters startups developing flexible power solutions for next-generation devices.
India
The growing consumer electronics market creates demand for flexible power solutions. India's PLI scheme encourages domestic manufacturing of advanced electronics components. Bengaluru's innovation hubs are exploring graphene applications for smart textiles and portable energy.
Graphene Solar Cell Market Key Industry Players
Listed leaders compete with private specialists across material synthesis and cell integration capabilities. The market structure exhibits a tiered approach, with large electronics conglomerates alongside specialized graphene producers. Strategic archetypes include vertically integrated material suppliers, R&D-focused innovators, and niche application developers. Dominant competitive moves involve strategic partnerships for technology co-development and aggressive capacity expansion in high-purity graphene production.
Among companies driving material innovation, Versarien plc and Samsung Advanced Institute of Technology exemplify distinct approaches. Versarien plc, a UK-based entity, represents the specialized material provider archetype, focusing on high-quality graphene production for photovoltaic applications. Samsung Advanced Institute of Technology, operating within a large South Korean conglomerate, anchors the research-intensive segment, leveraging deep R&D capabilities in advanced materials science. NanoXplore Inc., a Canadian firm, sits within the scalable manufacturing archetype for graphene powder products, aiming for broader industrial adoption and cost-effectiveness. These players collectively shape the supply dynamics for advanced graphene materials.
| Leading Market Players |
|---|
| Versarien plc |
| Graphene Manufacturing Group |
| Samsung Advanced Institute of Technology |
| HydroGraph Clean Power |
| First Graphene |
| Dongxu Optoelectronic Technology |
| NanoXplore Inc. |
| Directa Plus |
| Global Graphene Group |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements, particularly for high-purity graphene, lock in both supply access and price visibility for cell manufacturers. This stability is crucial for planning production runs and investing in advanced manufacturing capabilities.
Pricing Analysis
Certification level (IEC 61215 compliance) creates the primary spread in graphene solar cell pricing, reflecting validated performance and reliability. Pricing models often involve contract-based long-term offtake agreements, especially for specialized materials like graphene-based perovskite cells. Price differentiation stems from the purity of graphene and the manufacturing technique employed, such as Chemical Vapor Deposition. Pricing pressure from established silicon-based solar technologies intensifies due to the high production costs of advanced graphene. Consumer electronics firms exhibit high price sensitivity, while the aerospace industry prioritizes performance and durability over cost.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized graphene precursors, significantly influence the final material price due to global shipping lane dependencies. The supply chain for graphene solar cells concentrates heavily in South Korea, Germany, and China, reflecting key research and manufacturing hubs. Raw material dependencies include high-purity graphene precursors and specialized perovskite compounds. Single-source vulnerability for advanced Chemical Vapor Deposition equipment represents a structural supply chain risk. Distribution runs through direct sales channels and strategic partnerships with original equipment manufacturers in key application segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a substitution defense challenge, as incumbents must navigate threats from alternatives like silver nanowires and conductive polymers. These alternatives compete directly on cost and ease of integration in certain flexible electronic applications.
For Market Incumbents:
Fortify core competencies in Chemical Vapor Deposition technology to reduce graphene production costs and enhance material quality. Secure long-term supply agreements for high-purity graphene to ensure consistent material inputs against volatile spot markets. Invest in research and development to overcome perovskite material degradation, a significant stability challenge for high-efficiency cells. Pursue rapid IEC 61215 certification for novel cell designs to accelerate market entry and validate performance claims.
For New Entrants and Emerging Players:
Differentiate on specialized application performance, targeting niche markets where graphene's unique properties are indispensable. Focus on flexible consumer electronics, particularly rollable displays and smart textiles, as a penetrable segment due to demand for unobtrusive power sources. Develop integrated, custom power solutions for specific original equipment manufacturer partners to establish early market presence. Leverage Liquid Phase Exfoliation for cost-effective graphene production in high-throughput flexible electronics manufacturing.
For Investors and Strategic Acquirers:
The market sits at an early-growth phase that favors specialized material producers and advanced cell developers with strong intellectual property portfolios. Long-term viability hinges on overcoming current material stability and high production cost challenges. Target acquisition archetypes include firms with proprietary graphene synthesis techniques or breakthroughs in perovskite cell stabilization. The signal to watch is a significant reduction in graphene production costs or a validated increase in perovskite cell longevity under real-world conditions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in advanced CVD scaling | This initiative reduces production costs for large-area, high-quality graphene sheets, critical for building integrated photovoltaics. |
| Form long-term graphene supply agreements | These agreements secure consistent access to high-purity graphene, stabilizing input costs for cell manufacturers in South Korea. |
| R&D into perovskite stability | This research aims to overcome material degradation, enhancing the long-term operational reliability of graphene-based perovskite cells. |
| Strategic partnerships with EV manufacturers | These collaborations integrate graphene solar cells into automotive surfaces, powering auxiliary systems for electric vehicles. |
| Expand LPE production capacity | This expansion supports the growing demand for cost-effective graphene flakes in flexible electronics manufacturing. |
Research Approach
Findings reconcile primary fieldwork against secondary review of IEC 61215 standards, EU REACH regulations, GB standards, and corporate filings of graphene producers. Primary interviews included R&D directors at material science firms, procurement leads at solar cell manufacturers, material scientists specializing in 2D materials, and product managers in wearable electronics. This approach ensured a robust understanding of market dynamics through both bottom-up and top-down triangulation.
The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional R&D investment across the analysis window. Compound annual growth rates were derived from historical growth trends, projected technology advancements, and anticipated shifts in material adoption. Key forecast inputs included R&D spending in South Korea and Germany, alongside wearable electronics shipment forecasts and building integrated photovoltaics project pipelines.
Material uncertainties — unexpected regulatory shifts in graphene classification, unforeseen material science breakthroughs, or significant geopolitical trade disruptions — sit outside the modeled envelope of this analysis. Forecasts reflect documented assumptions regarding technological progression and market adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
South America Solar Photovoltaic Market