
 Fuel Vending Machines Market | 2026-2036
Fuel Vending Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Vending Machines Market Foresight
Asset-light leasing and pay-per-use financing is rewriting competitive entry barriers for fuel vending infrastructure. Censtar Science and Technology leverages manufacturing scale to dominate electronic dispenser shipments across Asia. Gilbarco Veeder-Root anchors its position through deep integration of contactless payment modules and fleet telemetry software. Dover Fueling Solutions competes by extending service networks into marine and agricultural refueling niches.
Fuel vending machines are self-service dispensing systems engineered to meter and deliver liquid fuels, compressed gases, or electric charge to vehicles through calibrated flow meters, vapor recovery hardware, and encrypted payment terminals. Units range from single-hose mechanical pumps to multi-product smart dispensers with integrated IoT sensors for remote diagnostics and inventory management. Diesel dispensers lead unit volume in fleet and industrial applications where high-throughput metering and automated billing reduce labor overhead. Smart IoT-enabled technology captures the fastest expansion as operators demand real-time consumption tracking, predictive maintenance alerts, and seamless fleet card integration. Contactless payment systems concentrate margin pools at urban retail stations where consumer convenience commands premium pricing.
EPA vapor recovery regulations and NHTSA dispenser safety standards shape product design and retrofit demand across the United States. The EU F-Gas Regulation and CE marking requirements govern LPG and alternative fuel dispenser imports into Europe, raising compliance costs for non-certified manufacturers. Stakeholders must monitor how fleet electrification timelines and evolving payment security protocols reshape capital allocation between conventional fuel hardware and electric vehicle charging infrastructure.
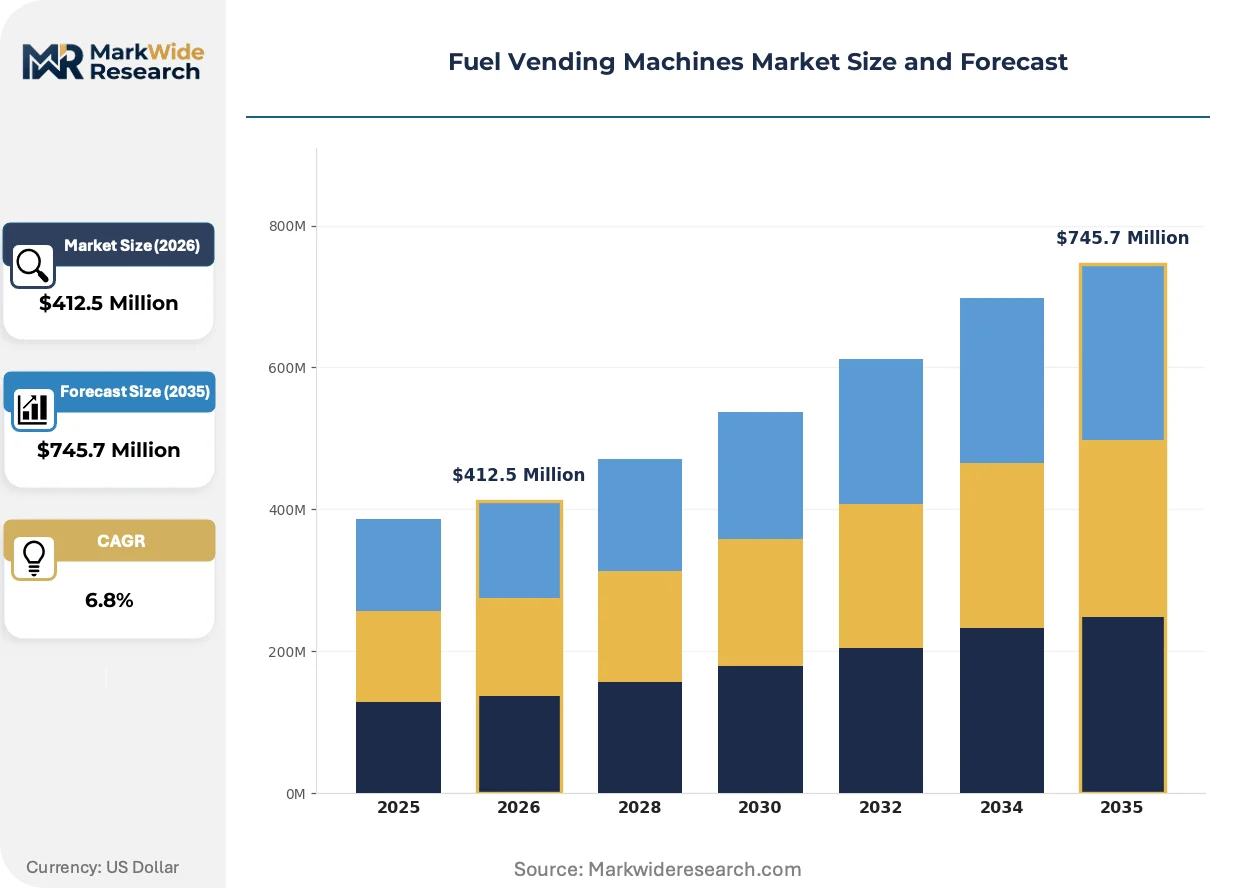
Market Dynamics
Fleet electrification timelines and EPA vapor recovery mandates are compressing capital allocation cycles between conventional fuel infrastructure and electric vehicle charging hardware. Operators now face parallel retrofit obligations across emission-compliant dispensers and emerging alternative fuel formats.
Growth Catalysts
- EPA Phase II Vapor Recovery:Gasoline stations in ozone non-attainment zones must upgrade to enhanced vapor recovery systems, forcing dispenser replacement cycles across California, Texas, and northeastern logistics corridors.
- Fleet Telematics Integration:Logistics operators demand automated fuel procurement linked to route optimization software, pulling smart dispenser installations at distribution centers and truck terminals.
- Compressed Natural Gas Infrastructure:Heavy-duty freight corridors along the I-10 and I-95 interstate systems are expanding CNG vending capacity to serve dual-fuel Class 8 truck deployments.
Market Restraints
- Stainless Steel and Electronics Input Volatility:Flow meter housings and payment terminal chipsets face price instability from concentrated Asian foundry supply, squeezing gross margins on mid-tier dispenser lines.
- California Air Resources Board Certification Lag:New dispenser models require 12-18 month CARB approval timelines, freezing product launches and favoring incumbents with established certification portfolios.
- DC Fast Charging Substitution:Fleet electrification roadmaps at major logistics operators are redirecting capex from diesel dispensers toward 350kW charging hardware at depot locations.
Strategic Opportunities
- Marine and Agricultural Niches:Off-road fueling at commercial fishing ports and Midwest grain elevators remains underpenetrated by automated vending, offering first-mover positioning for corrosion-resistant dispenser designs.
- Contactless Payment Mandates:PCI DSS compliance deadlines for EMV chip acceptance at fuel pumps create upgrade windows for integrated tap-to-pay and mobile wallet modules.
- Hydrogen Dispensing Convergence:California H2Hub deployment schedules and DOE hydrogen corridor funding are opening dual-product dispenser specifications serving both compressed hydrogen and conventional fuels.
Industry Challenges
- Embedded Systems Cybersecurity Certification:NHTSA and FBI guidance on fuel pump network vulnerabilities demands hardened payment terminal architectures, extending engineering cycles and testing budgets.
- Legacy POS Integration Complexity:Petroleum marketers operate fragmented back-office systems from decades of acquisitions, complicating API standardization for real-time inventory and pricing data exchange with new dispenser platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Vending Machines Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Petrol Dispenser, Diesel Dispenser, LPG Dispenser, Electric Vehicle Charger, CNG Dispenser Technology: Mechanical, Electronic, Automated, Smart IoT-enabled, Contactless Payment Application: Retail Fuel Stations, Fleet Management, Industrial Facilities, Agricultural Sites, Marine Refueling End User: Vehicle Fleet Operators, Logistics Companies, Construction Sites, Mining Operations, Public Transport Providers |
| Companies Covered | Tatsuno Corporation, Censtar Science and Technology, Gilbarco Veeder-Root, Bennett Pump Company, Scheidt & Bachmann, Wayne Fueling Systems, Tokheim, Eaglestar Energy Technology Co., Ltd., Dover Fueling Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Vending Machines Market Shifts & Advancements
Payment security protocols and predictive maintenance architectures are converging to redefine dispenser hardware specifications. Vendors now compete on software integration depth rather than mechanical reliability alone.
Edge computing modules installed directly within fuel dispensers are hybridizing transaction processing with real-time nozzle monitoring. Fleet operators in Texas and California are deploying these units to enable offline authorization during network outages while capturing flow rate anomalies for predictive seal replacement. This architecture compresses service response times from days to hours while reducing field technician dispatch frequency.
The EU F-Gas Regulation and its phasedown of hydrofluorocarbon refrigerants are reshaping LPG dispenser import requirements into European markets. Non-CE-certified Asian manufacturers face exclusion from tender processes, consolidating procurement pools around established European and North American suppliers. German and French fuel retail chains are accelerating supplier qualification audits to lock in compliant sourcing before 2027 quota reductions tighten.
Buying committees at logistics operators now unbundle dispenser hardware from long-term service contracts, compressing vendor switching cycles. Third-party maintenance networks in the southeastern United States are capturing aftermarket service revenue previously retained by original equipment manufacturers. This disintermediation forces dispenser suppliers to compete on transparent parts pricing and remote diagnostic capability rather than exclusive service lock-in.
Fuel Vending Machines Market Segmentation
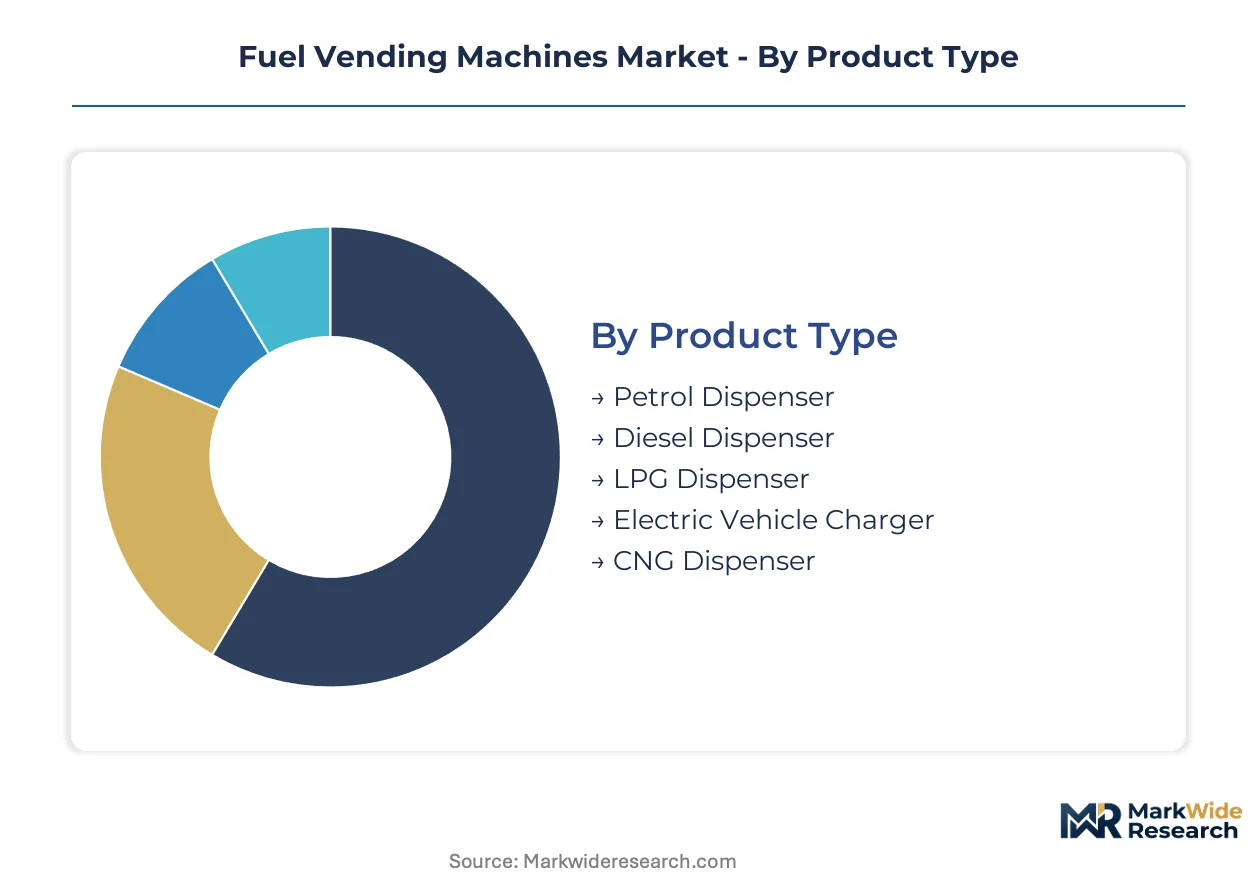
Segmentation in fuel vending machines reflects divergent capital cycles across conventional fuel infrastructure and alternative energy formats. Product specifications vary sharply between high-throughput fleet applications and consumer retail environments, while technology tiers separate legacy mechanical systems from connected platforms requiring ongoing software investment.
Product Type:
Fuel type specialization spans liquid hydrocarbons, compressed gases, and electric charge delivery, each demanding distinct flow control architectures and safety certifications.
- Diesel Dispenser:High-capacity positive displacement meters and hardened nozzle assemblies handle viscous fuel at elevated flow rates. Fleet terminals across Texas and California logistics corridors specify these units for automated procurement integration, though electrification roadmaps at major operators are compressing long-term deployment timelines.
- Electric Vehicle Charger:DC fast charging hardware with 350kW output capability and ISO 15118 vehicle-to-grid communication protocols. Depot locations at distribution centers are prioritizing these installations over diesel dispenser retrofits as fleet electrification accelerates.
- Petrol Dispenser:Vapor recovery-equipped units with Stage II compatibility for EPA compliance in ozone non-attainment zones.
- LPG Dispenser:Pressure-rated systems with overfill prevention valves serving dual-fuel vehicle fleets and off-road equipment.
- CNG Dispenser:High-pressure storage cascade integration for 3,600 psi fast-fill protocols along heavy-duty freight corridors.
Established volume favors Diesel Dispenser; emerging adoption favors Electric Vehicle Charger.
Technology:
Technology tiers separate capital-light mechanical refurbishment from software-dependent smart platforms requiring continuous security patching.
- Smart IoT-enabled:Edge computing modules with predictive maintenance algorithms and real-time flow anomaly detection. Fleet operators deploy these units to enable offline transaction authorization during network outages while reducing field technician dispatch frequency.
- Contactless Payment:EMV chip and NFC tap-to-pay terminals with PCI DSS compliance for petroleum retail. Urban stations command pricing premiums where consumer convenience drives site selection.
- Electronic:Microprocessor-controlled metering with temperature compensation and encrypted audit trails.
- Automated:Unattended operation with driver identification via fleet card or RFID for commercial fueling islands.
- Mechanical:Legacy gear-driven meters with mechanical totalizers, still deployed in cost-sensitive agricultural and remote mining contexts.
Replacement cycles concentrate in Contactless Payment; capability expansion centers on Smart IoT-enabled.
Application:
Site-specific requirements range from high-frequency retail throughput to intermittent off-road access in corrosive environments.
- Fleet Management:Multi-product dispensers with automated billing integration and telemetry connectivity for route optimization software. Distribution centers and truck terminals specify these configurations to eliminate manual fuel reconciliation.
- Marine Refueling:Corrosion-resistant stainless steel housings and explosion-proof electrical enclosures for salt-air exposure. Commercial fishing ports and coastal freight terminals represent underpenetrated automated vending opportunity.
- Retail Fuel Stations:Consumer-facing islands with vapor recovery and convenience store POS integration.
- Industrial Facilities:High-volume custody transfer systems with weights-and-measures certification for plant vehicle fleets.
- Agricultural Sites:Portable or fixed skid-mounted units serving seasonal equipment with minimal infrastructure investment.
Procurement automation drives Fleet Management; first-mover positioning favors Marine Refueling.
End User:
Buyer sophistication varies from centralized fleet procurement departments to fragmented construction site operators with limited technical staff.
- Vehicle Fleet Operators:Large-scale logistics and delivery fleets with dedicated fueling infrastructure and telematics integration requirements. These buyers unbundle hardware from service contracts, compressing vendor switching cycles.
- Logistics Companies:Third-party freight and last-mile delivery operators optimizing fuel costs across distributed terminal networks.
- Public Transport Providers:Municipal bus and rail operators with alternative fuel mandates and federal funding access for CNG or electric infrastructure.
- Construction Sites:Project-based fuel consumption with temporary dispensing needs and limited connectivity infrastructure.
- Mining Operations:Remote high-volume consumption with extreme duty cycle requirements and limited maintenance access.
Contract restructuring favors Vehicle Fleet Operators; federal funding access shapes Public Transport Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing in China and South Korea supplies dispenser hardware to North American and European retrofit cycles, while import-dependent markets in Southeast Asia and the Middle East absorb second-tier electronic components for localized assembly.
United States
Fleet electrification roadmaps at logistics operators are compressing diesel dispenser deployment timelines across Texas and California distribution corridors. EPA Phase II vapor recovery mandates force gasoline station upgrades in ozone non-attainment zones. Dallas-Fort Worth and Los Angeles Basin logistics clusters specify smart dispensers with telematics integration for automated fuel procurement.
Germany
EU F-Gas Regulation phasedown of hydrofluorocarbon refrigerants is reshaping LPG dispenser import requirements and supplier qualification audits. CE marking compliance and REACH chemical safety protocols govern alternative fuel hardware certification. Rhine-Ruhr and Bavarian industrial corridors deploy multi-product dispensers serving compressed natural gas and conventional fuel fleets.
China
Domestic manufacturing scale for electronic dispenser components supplies retrofit demand across Asia-Pacific logistics networks. MIIT industrial standards and GB certification protocols shape product specifications for domestic and export markets. Yangtze River Delta manufacturing clusters around Shanghai produce flow meter housings and payment terminal chipsets for regional vending machine assembly.
Japan
Precision metering technology development supports high-accuracy dispenser exports to Southeast Asian fleet markets. METI energy efficiency directives and JIS industrial standards govern alternative fuel infrastructure deployment. Kanto region engineering centers around Tokyo refine predictive maintenance algorithms for IoT-enabled dispenser platforms.
Brazil
Agricultural and off-road fueling demand drives portable dispenser installations across seasonal equipment operations. ANVISA safety protocols and national petroleum agency regulations govern fuel dispensing hardware certification. São Paulo state logistics terminals specify automated billing systems for fleet procurement integration.
Fuel Vending Machines Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: integrated multinationals with full-stack manufacturing and service networks, regional specialists dominating specific fuel formats or geographies, and component suppliers capturing value in flow control and payment terminal subsystems. Strategic archetypes include scale-driven hardware fabricators, software-integrated platform providers, and niche application specialists. Dominant competitive moves encompass geographic expansion through distributor partnerships and portfolio diversification into alternative fuel formats.
Within the integrated multinational tier, Gilbarco Veeder-Root and Dover Fueling Solutions occupy positions anchoring North American and European market presence through deep service network penetration. Censtar Science and Technology represents the scale-driven manufacturing archetype, exemplifying Chinese production capacity serving Asia-Pacific demand clusters. Among precision engineering specialists, Tatsuno Corporation and Scheidt & Bachmann sit within the high-accuracy metering segment, reflecting Japanese and German engineering heritage in flow control technologies.
| Leading Market Players |
|---|
| Tatsuno Corporation |
| Censtar Science and Technology |
| Gilbarco Veeder-Root |
| Bennett Pump Company |
| Scheidt & Bachmann |
| Wayne Fueling Systems |
| Tokheim |
| Eaglestar Energy Technology Co., Ltd. |
| Dover Fueling Solutions |
| Others |
Supply & Pricing Matrix
Foundry concentration in Taiwan and South Korea for payment terminal chipsets and flow meter sensors concentrates margin capture upstream, while downstream margin pools sit with fleet operators unbundling hardware from long-term service contracts. This asymmetry forces dispenser manufacturers to compete on transparent parts pricing and remote diagnostic capability rather than exclusive service lock-in.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the fuel vending machine market. Price differentiation rests on certification grade—UL-listed and NHTSA-compliant units command premiums—and volume scale from fleet procurement aggregation. Cost compression in mid-tier electronic dispenser lines is intensifying because of stainless steel and semiconductor input volatility. Construction site operators exhibit highest price sensitivity due to temporary dispensing needs, while vehicle fleet operators prioritize telemetry integration over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Yangtze River Delta component suppliers are reshaping procurement dynamics for North American dispenser assemblers. Manufacturing gravity centers on China, South Korea, and Japan for flow control subsystems, payment terminal chipsets, and precision metering components. Raw material dependencies include stainless steel for corrosion-resistant housings, epoxy resins for electronic encapsulation, and high-grade aluminum for nozzle assemblies. Single-source vulnerability concentrates in Asian foundry supply for microcontroller units. Distribution runs through authorized distributor networks and direct OEM procurement channels serving petroleum marketers and fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fuel vending machine market functions as a service-attach opportunity where predictive maintenance software and remote diagnostic subscriptions are expanding faster than hardware unit sales. Recurring revenue from fleet telemetry integration and automated billing platforms now exceeds margin contribution from dispenser shipments alone.
For Market Incumbents: Build certification moats through accelerated CARB and EPA approval pipelines to freeze out challengers facing 12-18 month regulatory lag. Deepen backward integration into flow meter manufacturing to offset Asian foundry price volatility. Prioritize API standardization investments to capture legacy POS integration complexity as a switching cost against third-party maintenance networks. For New Entrants and Emerging Players: Establish a beachhead in marine refueling applications where corrosion-resistant dispenser designs face limited automated vending penetration. Target agricultural sites with portable skid-mounted units for seasonal equipment operations. Lead with PCI DSS-compliant contactless payment modules to exploit EMV chip mandate upgrade windows at independent retail stations. For Investors and Strategic Acquirers: Capital is best deployed toward precision engineering specialists with established CE marking portfolios ahead of EU F-Gas Regulation quota tightening. Long-term viability hinges on software-integrated platform providers capable of hybridizing conventional fuel and hydrogen dispensing specifications. Monitor California H2Hub deployment schedules as inflection indicator for dual-product dispenser demand.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Telematics Integration | Wayne Fueling Systems and Gilbarco Veeder-Root are embedding route optimization software APIs to automate fuel procurement reconciliation. |
| Hydrogen Dispensing Convergence | Dover Fueling Solutions is developing dual-product specifications serving compressed hydrogen and conventional fuels for California H2Hub corridors. |
| Contactless Payment Mandate Compliance | Bennett Pump Company is accelerating EMV chip and NFC tap-to-pay module deployment ahead of PCI DSS deadlines. |
| Marine and Agricultural Niche Expansion | Scheidt & Bachmann is qualifying corrosion-resistant stainless steel housings for commercial fishing port installations. |
| Predictive Maintenance Platform Development | Tatsuno Corporation is refining edge computing algorithms for real-time flow anomaly detection and seal replacement alerts. |
Research Methodology
Cross-validation between fleet procurement director interviews and EPA regulatory filing databases anchors the qualitative findings in this study. Primary fieldwork engaged dispenser OEM product managers, petroleum marketer operations executives, third-party maintenance network operators, and logistics fleet telematics directors. Secondary validation drew from NHTSA safety standard dockets, CARB certification records, SEC 10-K equipment disclosures, and EU F-Gas Regulation implementation reports. Bottom-up unit shipment modeling and top-down fuel infrastructure capex analysis were triangulated against distributor channel checks.
Calibration against historical retrofit cycle patterns and fleet electrification roadmap disclosures shaped the projection framework across the analysis window. Segmentation dimensions modeled include fuel type specialization, technology tier, application environment, and end-user procurement sophistication. CAGRs were derived from slope analysis of replacement cycle compression and alternative fuel infrastructure deployment trajectories. Forecast inputs incorporated EPA vapor recovery mandate timelines and MIIT industrial standard evolution for electronic dispenser exports.
Sensitivities concentrate around fleet electrification acceleration, semiconductor supply disruption, and cybersecurity certification timeline extensions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and logistics operator capex prioritization. Macroeconomic contraction, NHTSA embedded systems security guidance expansion, or DOE hydrogen corridor funding suspension would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market