
 Global Fuel Cell Balance of Plant (BOP) Market | 2026-2036
Global Fuel Cell Balance of Plant (BOP) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fuel Cell Balance of Plant (BOP) Market Intelligence
The adoption of energy-as-a-service (EaaS) models is reshaping competitive positioning by lowering upfront capital barriers for end users. This shift allows specialists like Bloom Energy to offer integrated power solutions rather than just hardware. Meanwhile, Ballard Power Systems focuses on heavy-duty motive applications, differentiating through its proton exchange membrane technology. Cummins leverages its extensive distribution network to integrate fuel cell systems into broader power generation portfolios.
Fuel cell balance of plant (BOP) refers to the auxiliary components that support the operation of the fuel cell stack. These subsystems, including air compressors, coolant pumps, and hydrogen humidifiers, manage fuel delivery, thermal regulation, and power conditioning. Within the component segment, high-performance air compressors represent a critical cost and efficiency driver. Proton exchange membrane technology applications dominate the market, particularly in mobility, while solid oxide fuel cells are gaining traction in stationary power generation.
Global hydrogen strategies, including the EU Green Deal and China's dual carbon goals, create direct incentives for fuel cell deployment. Concurrently, ISO standards for hydrogen fuel quality and safety protocols from bodies like the IEC are standardizing system requirements across international markets. Navigating the evolving landscape of component-level certifications and regional content requirements will be critical for supply chain planning.
Market Dynamics
The global push for green hydrogen infrastructure, accelerated by national industrial policies, is the central force shaping BOP component specifications. This dynamic dictates investment flows and technological priorities for subsystems like compressors and humidifiers.
Growth Catalysts
- National Hydrogen Strategies:Policies including the EU Green Deal and China's dual carbon goals create direct incentives for fuel cell deployment across industrial and mobility sectors, pulling through demand for BOP components.
- Data Center Backup Power:Requirement from hyperscale data centers for reliable, low-emission backup power drives adoption of stationary solid oxide fuel cell systems and their specialized thermal management components.
- Proton Exchange Membrane Advances:Material science improvements in PEM technology enhance durability and power density, expanding BOP system applications in demanding heavy-duty transport and logistics.
Market Restraints
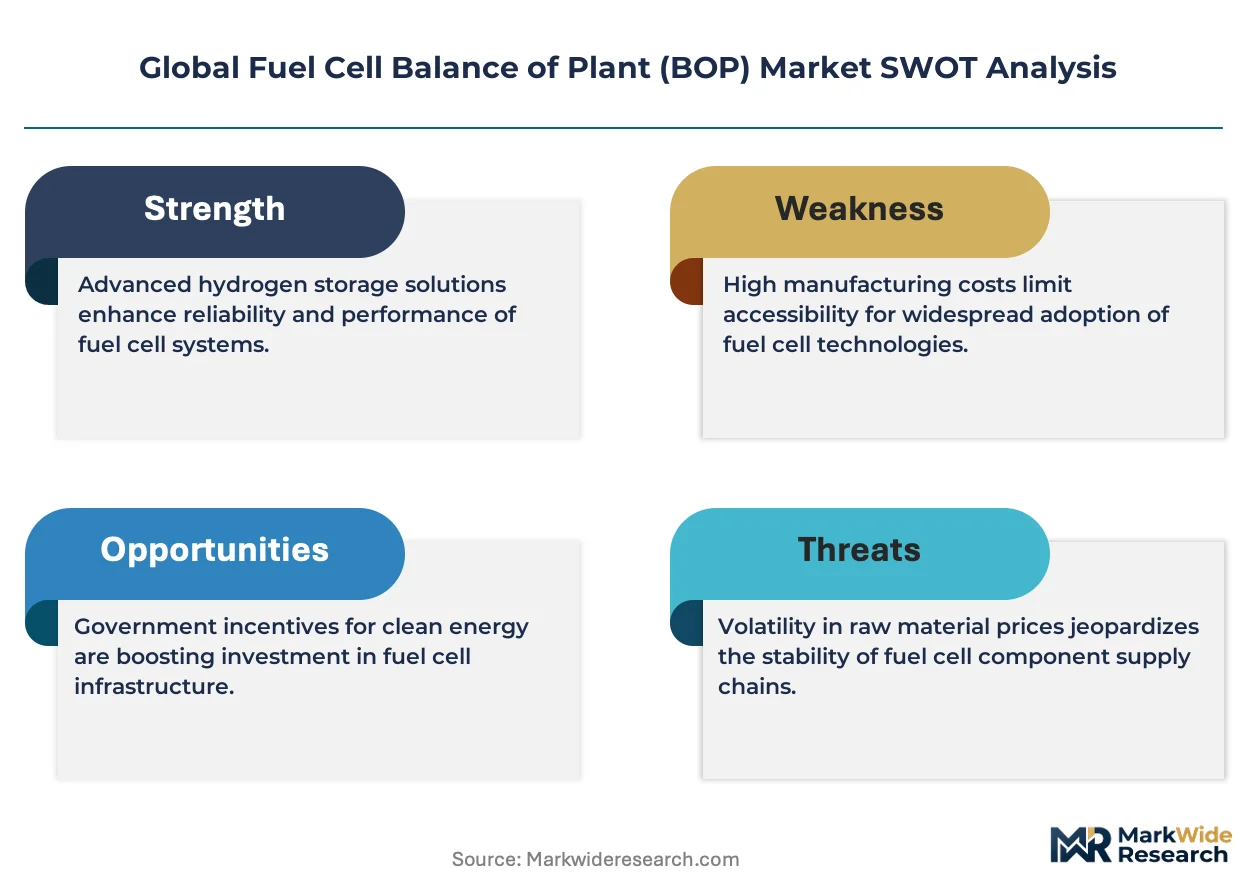
- Air Compressor Cost:High-performance, oil-free air compressors remain a significant cost and power consumption pain point, representing a large portion of total BOP system expense and complexity.
- Green Hydrogen Availability:The limited supply and high cost of green hydrogen, despite subsidies like the US IRA, constrains the business case for large-scale fuel cell deployments in certain regions.
- Component Standardization Gaps:A lack of full standardization for critical components like humidifiers and DC/DC converters across different stack manufacturers complicates supply chains and system integration.
Strategic Opportunities
- Marine and Aviation Applications:Developing BOP components for high-power fuel cell systems presents a new frontier for marine propulsion and auxiliary power units in aviation, requiring novel thermal and fuel management solutions.
- Energy-as-a-Service Integration:Integrating BOP components into EaaS offerings lowers adoption barriers for commercial and industrial users by converting upfront capital expenditures into predictable operational expenses.
- South American Market Entry:Untapped markets in countries like Brazil and Chile, with abundant renewable energy potential for green hydrogen production, offer long-term growth prospects for stationary and motive applications.
Industry Challenges
- System Integration Expertise:A shortage of engineers skilled in integrating complex BOP subsystems with fuel cell stacks and end-user power systems creates project delays and performance risks.
- Navigating Certification Pathways:Managing disparate regional certification requirements, such as CE marking in Europe and specific UL standards in the US for electrical components, extends product development timelines.
- High-Volume Manufacturing Investment:Establishing automated, high-volume production lines for BOP components like coolant pumps requires substantial capital investment to achieve the cost targets necessary for mass-market adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fuel Cell Balance of Plant (BOP) Market |
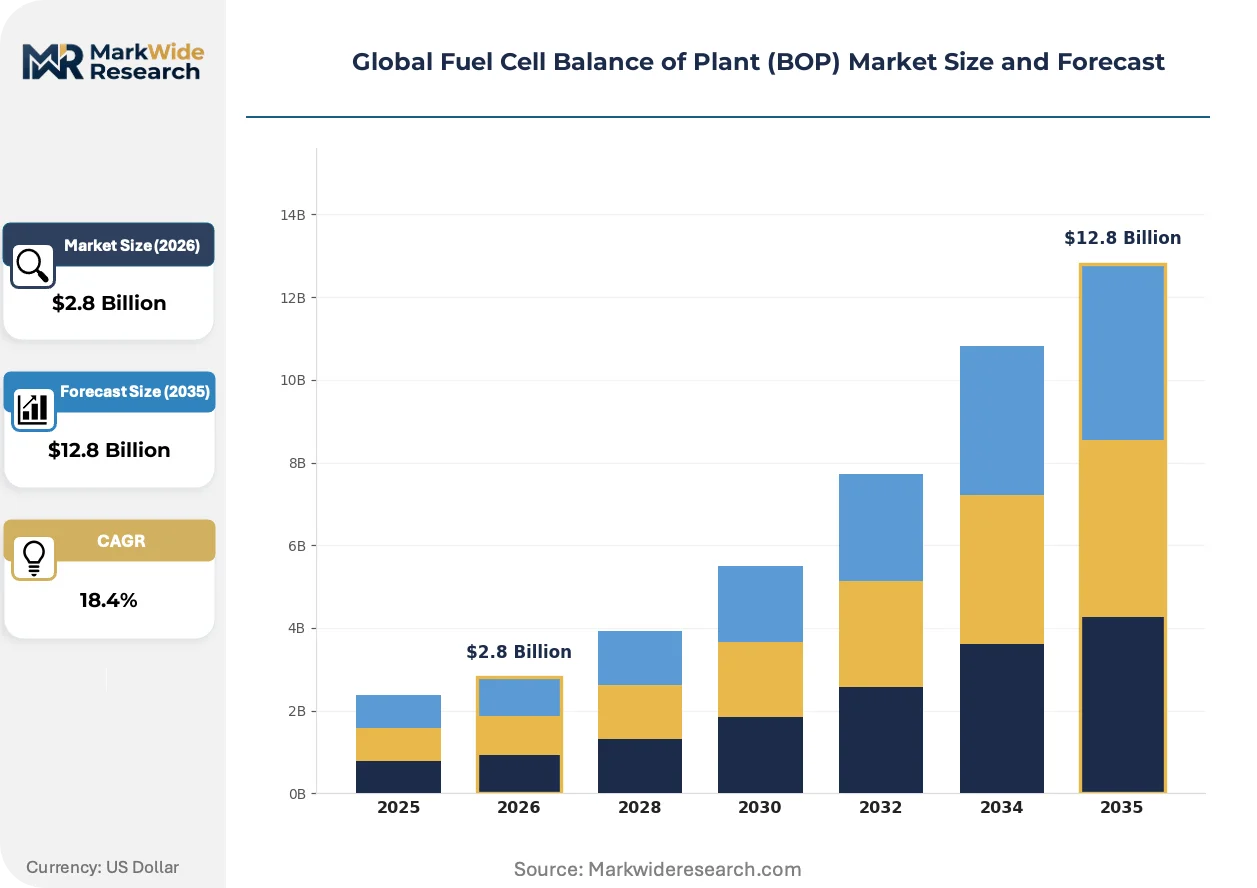
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Pumps, Valves, Compressors, Heat Exchangers, Sensors, Controllers Technology: Proton Exchange Membrane, Solid Oxide, Phosphoric Acid, Alkaline, Molten Carbonate Application: Stationary Power Generation, Backup Power Systems, Material Handling Equipment, Portable Power Packs, Telecom Power Supply End User: Power Utilities, Data Centers, Warehousing, Emergency Services, Telecommunications Providers |
| Companies Covered | Bloom Energy, Doosan Fuel Cell Co., Ltd., Ballard Power Systems, Sunfire, Nel Hydrogen, Plug Power, Cummins, Linde AG, FuelCell Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fuel Cell Balance of Plant (BOP) Market Strategic Shifts & Innovations
Component evolution within the BOP is now defined by digitalization and modularity. These shifts enable greater system intelligence and adaptability across applications, from stationary power to heavy-duty mobility.
Digital twin technology creates a virtual model of the BOP system, including compressors and pumps. System integrators and fleet operators adopt this for predictive maintenance and performance optimization. This technology is virtualizing physical testing, reducing development time and operational costs for new fuel cell deployments.
The US Inflation Reduction Act (IRA) provides significant production tax credits for clean hydrogen, directly lowering fuel costs. This policy incentivizes hydrogen infrastructure build-out for industrial and heavy-duty transport applications. Consequently, the stationary power segment is designing BOP systems optimized for domestically produced green hydrogen.
A shift towards modular and scalable BOP designs is gaining traction. Instead of procuring bespoke systems, customers in logistics and public transit prefer standardized modules that can be scaled as fleets expand. This trend is most visible in Germany and France, where municipal bus fleets are incrementally transitioning to hydrogen.
Global Fuel Cell Balance of Plant (BOP) Market Segmentation
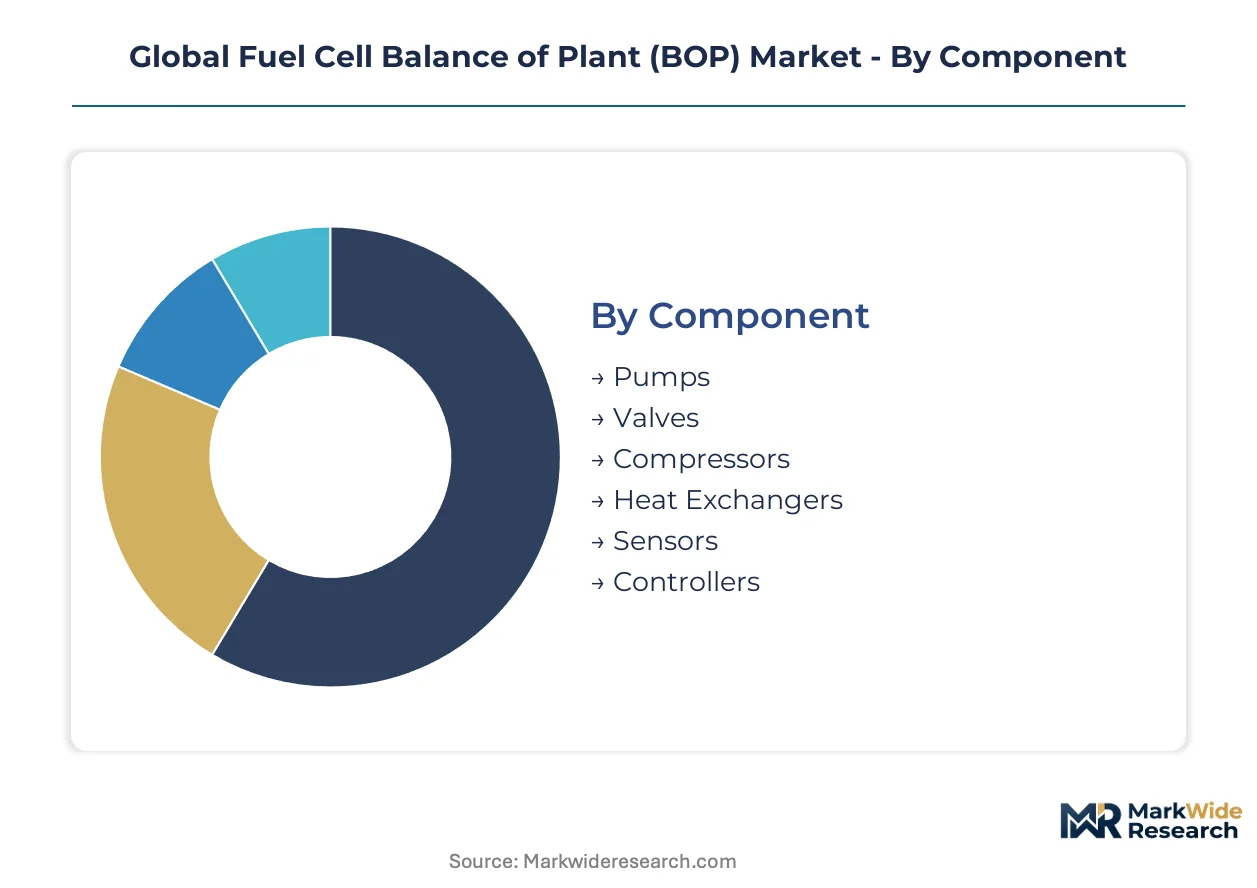
Understanding the distinct segments within the fuel cell balance of plant market is critical for identifying specific demand drivers and technological priorities. Each category highlights how different components, technologies, applications, and end-users contribute to the overall market dynamics. This granular view assists stakeholders in strategic planning and product development.
Component:
The functional elements of BOP systems define component demand.
- Compressors:High-performance, oil-free air compressors manage air supply to the fuel cell stack, representing a significant cost and power consumption driver. Demand concentrates in heavy-duty transport applications requiring robust and efficient air management.
- Heat Exchangers:These components are essential for thermal regulation, managing waste heat, and maintaining optimal operating temperatures for fuel cell stacks. Data centers deploying solid oxide fuel cells drive demand for specialized thermal management solutions.
- Pumps:Coolant pumps circulate thermal fluids to maintain optimal operating temperatures within the fuel cell system.
- Valves:Control the flow of hydrogen, air, and coolant within the BOP system, ensuring safe and efficient operation.
- Sensors:Monitor critical parameters such as temperature, pressure, and gas flow, providing data for system control and diagnostics.
- Controllers:Electronic control units manage and optimize the performance of various BOP components, integrating them with the fuel cell stack.
Compressors hold installed capacity. Heat Exchangers are rotating up the share rankings.
Technology:
Differentiation by operating principle shapes fuel cell technology adoption.
- Proton Exchange Membrane:This technology utilizes a polymer membrane to conduct protons, operating at lower temperatures and offering high power density for mobility applications. Mobility sectors in Germany and South Korea show strong adoption due to national hydrogen strategies.
- Solid Oxide:Operating at high temperatures, solid oxide fuel cells are highly efficient and can utilize various fuels, making them suitable for stationary power generation. Hyperscale data centers require specialized solid oxide systems for reliable backup power.
- Phosphoric Acid:These fuel cells use liquid phosphoric acid as an electrolyte, offering good efficiency and durability for stationary power.
- Alkaline:Operating at low temperatures, alkaline fuel cells use a liquid electrolyte and are known for high efficiency but are susceptible to CO2 poisoning.
- Molten Carbonate:These high-temperature fuel cells use a molten carbonate salt mixture as an electrolyte, suitable for large-scale stationary power generation.
Proton Exchange Membrane technology maintains market leadership. Solid Oxide systems exhibit the steepest expansion trajectory.
Application:
The operational context for fuel cell deployment dictates application-specific BOP designs.
- Stationary Power Generation:Fuel cells provide continuous or backup power for industrial, commercial, and residential uses, often integrating with grid infrastructure. The EU Green Deal incentivizes stationary fuel cell deployment for decarbonization targets.
- Backup Power Systems:These applications provide reliable, uninterrupted power during grid outages, critical for sensitive operations like data centers and hospitals. Data centers in the US are adopting fuel cell backup power due to IRA incentives.
- Material Handling Equipment:Fuel cells power forklifts and other industrial vehicles, offering extended run times and quick refueling compared to batteries.
- Portable Power Packs:Compact fuel cell systems provide mobile power for remote sites, military applications, and recreational activities.
- Telecom Power Supply:Fuel cells offer reliable, low-emission power for remote cell towers and communication infrastructure.
Stationary Power Generation commands significant volume. Backup Power Systems are gaining share fastest.
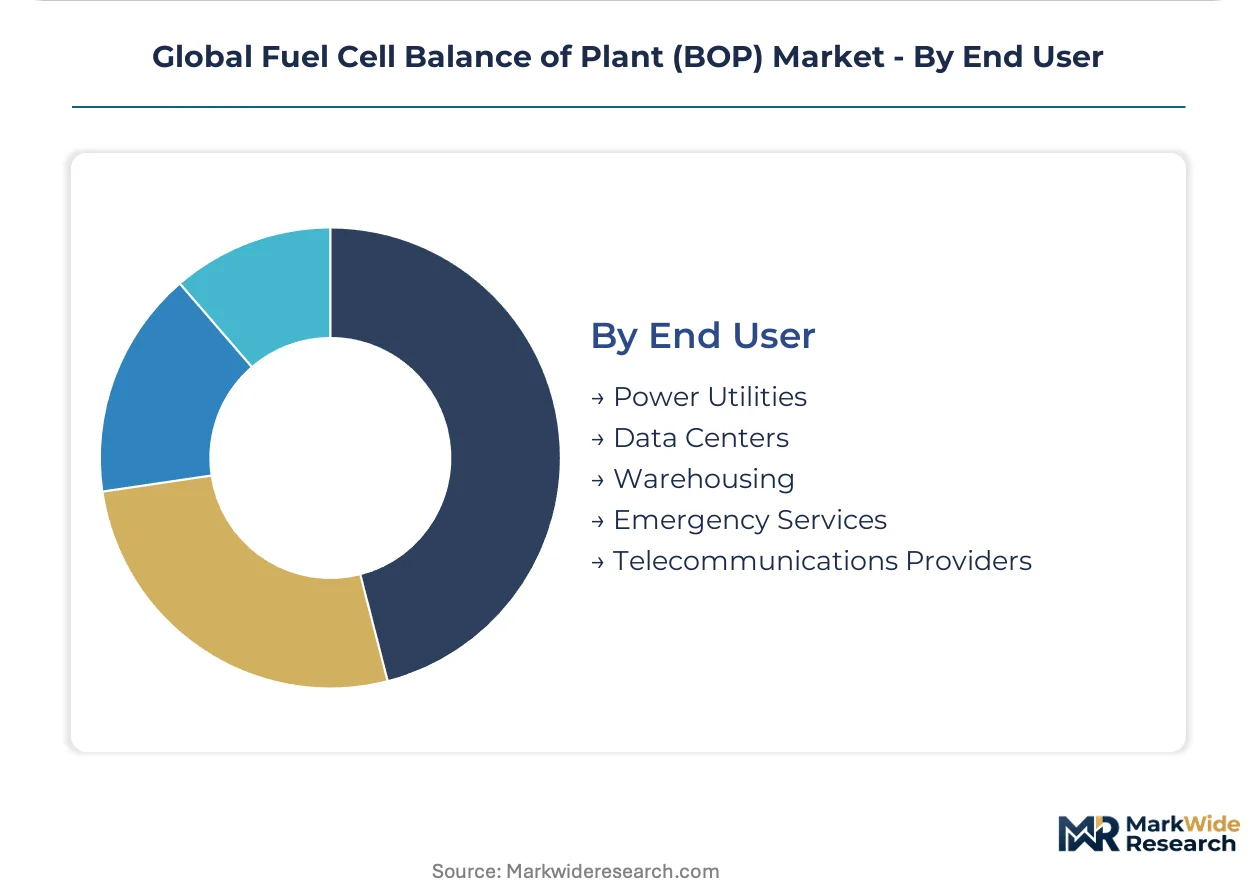
End User:
Specific industry requirements drive end-user adoption patterns for fuel cell BOP.
- Data Centers:These facilities require highly reliable, low-emission backup power solutions to ensure continuous operation and data integrity. US data centers are increasingly investing in fuel cell systems due to energy security concerns.
- Power Utilities:Utility companies integrate fuel cell systems for grid stabilization, distributed power generation, and peak shaving applications. China's dual carbon goals encourage utilities to explore cleaner power sources.
- Warehousing:Logistics and warehousing operations utilize fuel cell-powered material handling equipment for efficiency and reduced emissions.
- Emergency Services:Fuel cell systems provide critical backup power for hospitals, police stations, and other essential services during emergencies.
- Telecommunications Providers:These companies deploy fuel cells to power remote base stations and network infrastructure, ensuring service continuity.
Power Utilities represent a foundational customer base. Data Centers are climbing the fastest in adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act (IRA) significantly lowers green hydrogen costs, accelerating fuel cell deployment. This policy, alongside global decarbonization initiatives, directs investment flows into critical BOP components. Consequently, demand for advanced fuel cell systems is rising across diverse industrial and mobility applications worldwide.
United States
Demand for reliable backup power from hyperscale data centers drives significant fuel cell BOP adoption in the United States. The US Inflation Reduction Act (IRA) provides substantial tax credits, lowering green hydrogen costs for industrial users. Consequently, data centers in states like California are integrating solid oxide fuel cell systems for energy security.
Germany
Germany exhibits strong demand for fuel cell BOP components, particularly in heavy-duty transport and industrial sectors. The EU Green Deal and national hydrogen strategies incentivize fuel cell deployment across various applications. Municipal bus fleets in cities like Hamburg are adopting modular BOP designs for hydrogen-powered vehicles.
South Korea
South Korea drives demand for proton exchange membrane (PEM) technology applications, especially in mobility. The country's national hydrogen strategies actively promote fuel cell adoption for both transport and stationary power generation. Significant investment is concentrating within industrial clusters near Ulsan, developing advanced BOP systems.
China
China's dual carbon goals provide significant incentives for fuel cell deployment in utility-scale power and heavy-duty transport. National energy policies prioritize cleaner power sources, stimulating BOP component demand. Industrial parks in regions such as Guangdong are rapidly building out hydrogen refueling and fuel cell system integration capabilities.
Brazil
Brazil presents emerging demand for fuel cell BOP, driven by its abundant renewable energy potential for green hydrogen production. Government initiatives for renewable energy and decarbonization are attracting investment into hydrogen infrastructure. States such as Ceará are positioning themselves as key hubs for green hydrogen production and export.
Global Fuel Cell Balance of Plant (BOP) Market Key Industry Players
On the supply side, the industry is characterized by a mix of established industrial players and specialized technology developers. The market structure includes vertically integrated system providers offering complete solutions and component specialists focusing on high-performance BOP elements. Strategic archetypes include integrated power solution providers, dedicated component manufacturers, and companies specializing in heavy-duty motive applications. Capacity expansion and strategic partnerships across the value chain are dominant competitive moves.
Specialists in integrated power solutions, such as Bloom Energy, exemplify the shift towards energy-as-a-service models, lowering upfront capital barriers for end users. Ballard Power Systems occupies a position among those developing proton exchange membrane technology, particularly for demanding heavy-duty motive applications. Meanwhile, Cummins leverages its extensive global distribution network to integrate fuel cell systems into broader power generation portfolios. These companies collectively represent diverse strategic approaches, from offering comprehensive energy solutions to focusing on specific technology advancements and market access.
| Leading Market Players |
|---|
| Bloom Energy |
| Doosan Fuel Cell Co., Ltd. |
| Ballard Power Systems |
| Sunfire |
| Nel Hydrogen |
| Plug Power |
| Cummins |
| Linde AG |
| FuelCell Energy |
Cost & Logistics Intelligence
Industrial clusters near Ulsan, South Korea, concentrating advanced BOP system production, directly influence global component pricing. This capacity concentration shapes cost structures for fuel cell integrators worldwide.
Pricing Analysis
Certification level (ISO/IEC/UL/CE-grade) creates the primary spread in fuel cell BOP component pricing, alongside performance specifications for items like high-efficiency air compressors. Project-based models dominate for integrated systems, while per-unit transactional pricing applies to standard components. Pricing softness stems from increasing manufacturing automation investments. Heavy-duty transport operators exhibit higher price sensitivity than data centers, which prioritize long-term operational reliability.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support capital-intensive BOP component manufacturing, which concentrates in Germany, South Korea, and China. The supply chain draws from critical inputs like high-performance air compressors and specialized thermal management components. Component standardization gaps across different stack manufacturers present a structural risk, complicating system integration. Distribution runs primarily through direct sales to fuel cell system integrators and OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fuel cell balance of plant market represents a high-growth disruption, driven by global decarbonization initiatives and the US Inflation Reduction Act. This policy landscape accelerates investment across industrial and mobility applications.
For Market Incumbents: Insulate core market share by deepening vertical integration into high-cost BOP components like air compressors. Invest in R&D for modular and digital twin technologies to counter emerging specialized startups. Expanding global service networks reinforces customer relationships against new entrants. Navigating evolving certification requirements also protects market position.
For New Entrants and Emerging Players: Build out specialized BOP solutions for nascent marine and aviation applications, leveraging unique thermal and fuel management requirements. Target South American markets like Brazil and Chile, offering green hydrogen potential for stationary power. EaaS integration for commercial and industrial users presents the most penetrable segment. Partner with renewable energy developers to offer outcome-based power solutions.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized component manufacturers with proprietary BOP solutions. The market offers strong long-term viability over the next decade, driven by sustained decarbonization targets. Acquisition targets include agile developers of digital twin capabilities or modular BOP designs. Watch for significant capital deployment into large-scale green hydrogen production capacity as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing BOP component production in Germany supports heavy-duty transport demand. |
| Green Manufacturing Transition | Adopting renewable energy in South Korean factories lowers component embodied carbon. |
| Strategic Partnership | Collaborating with data center operators in the US ensures tailored backup power solutions. |
| Product Launch | Introducing modular BOP designs accelerates adoption in municipal bus fleets. |
| Geographic Expansion | Entering Brazilian markets capitalizes on abundant renewable energy for green hydrogen. |
Research Approach
The analysis maps fuel cell BOP components, including compressors, heat exchangers, and control systems, each validated through primary interviews with industry stakeholders. We engaged fuel cell system integrators, component engineers, procurement managers, and energy utility planners. Secondary validation utilized national hydrogen strategies, ISO/IEC standards, corporate financial filings, and patent databases. This combined bottom-up data collection with top-down market sizing triangulation.
The forecast assumes continued policy support for green hydrogen and fuel cell deployment, while varying technological advancements and market adoption rates. The analytical framework modeled market dynamics across the projection horizon, segmented by component type, technology, application, end-user, and regional policy environments. Compound annual growth rates were derived from historical trends and projected technology adoption. Green hydrogen production costs and fuel cell system efficiency served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated players or new technology disruptors would shift outcomes. Forecasts reflect assumptions regarding green hydrogen availability and infrastructure build-out. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market