
 Domestic Booster Pump Market | 2026-2036
Domestic Booster Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Domestic Booster Pump Market Intelligence
Multi-source component procurement is decoupling from traditional captive manufacturing in the domestic booster pump sector. Grundfos Holding A/S leverages its vertically integrated motor production to control cost volatility across European supply chains. Xylem Inc. sustains competitive positioning through advanced variable frequency drive integration. Wilo SE anchors its Asia-Pacific presence with localized assembly operations in China and India.
A domestic booster pump is a mechanically driven hydraulic device designed to increase water pressure in distribution systems, typically operating at flow rates between 0.5 and 12 cubic meters per hour and discharge heads from 15 to 80 meters, serving residential, commercial, and light industrial buildings where municipal supply pressure proves inadequate. Multistage pumps dominate value capture in high-rise residential applications where stacked pressure zones demand sequential impeller stages. Variable frequency drive technology leads growth trajectories as building codes mandate energy efficiency thresholds. Inline pumps occupy mature replacement cycles across existing commercial building stock.
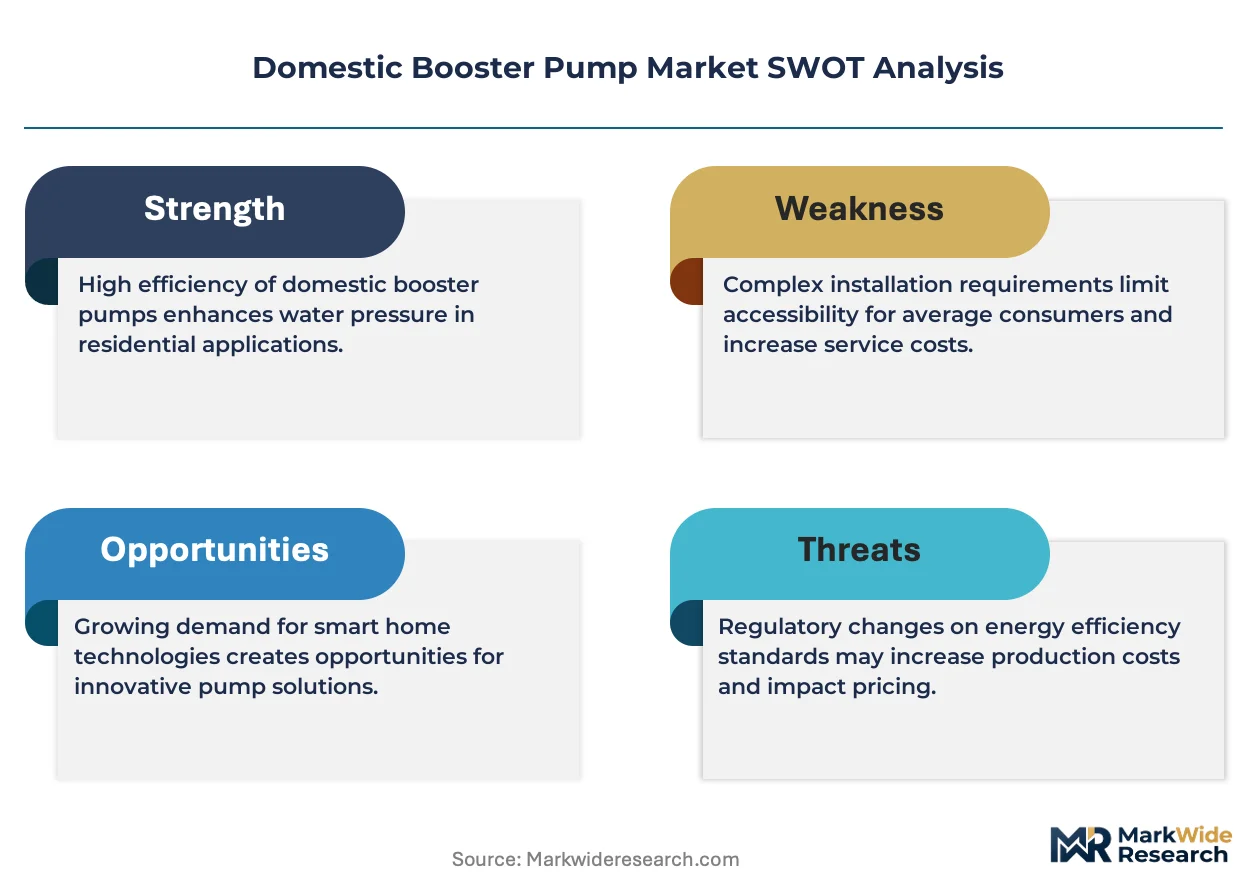
The US Department of Energy (DOE) pump efficiency standards and the EU Ecodesign Directive constrain minimum performance thresholds for circulating and clean water pumps, forcing manufacturers to redesign hydraulic geometries and motor configurations. India's BIS certification and China's GB standards for electrical safety and energy labeling create divergent compliance pathways that fragment product platform strategies. Stakeholders must monitor regulatory calibration cycles across North America, Europe, and Asia-Pacific to anticipate redesign investments and certification lead times.
Market Dynamics
Variable frequency drive technology is compressing energy consumption benchmarks across residential and commercial installations, forcing incumbent manufacturers to reengineer motor-hydraulic interfaces or surrender specification slots to more efficient competitors.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency mandates for clean water pumps are phasing out single-speed induction motors, redirecting replacement demand toward electronically commutated and VFD-equipped units across European building stock.
- High-rise residential construction:Stacked pressure zones in towers exceeding 15 stories require multistage configurations with sequential impeller arrays, expanding specification requirements in China's Yangtze River Delta and India's tier-two cities.
- Copper rotor die-casting:Advanced motor manufacturing techniques are reducing winding losses and extending operating lifespans, improving total cost of ownership calculations for property developers and facility managers.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet synchronous motors depend on neodymium-dysprosium supply chains centered in China's Inner Mongolia and Jiangxi processing corridors, exposing cost volatility to export quota fluctuations.
- Stagnant municipal infrastructure investment:Aging distribution networks in legacy European cities delay pressure-boosting retrofits as utilities defer capital allocation to pipeline replacement rather than endpoint supplementation.
- Electromechanical reliability thresholds:VFD-induced bearing currents and shaft voltage discharge accelerate premature failure in installations lacking proper grounding and filtering, constraining warranty terms and service coverage.
Strategic Opportunities
- India's Bureau of Indian Standards certification tightening:Electrical safety and energy labeling requirements are creating compliance barriers for unorganized regional assemblers, opening specification channels for certified manufacturers in residential complexes across Pune, Hyderabad, and Ahmedabad.
- Smart building integration:IoT-enabled pressure monitoring and predictive maintenance algorithms are converging with building management systems, enabling subscription-based service models for commercial property operators.
- Retrofit-focused inline configurations:Compact footprint designs are penetrating existing commercial building replacement cycles where space constraints previously blocked multistage installations.
Industry Challenges
- VFD commissioning expertise scarcity:Proper parameter configuration for varying load profiles requires specialized field technicians, creating service bottlenecks in distributed installation networks across secondary cities.
- Dual certification timeline compression:Simultaneous pursuit of India's BIS marking and China's GB standards extends product validation cycles, delaying platform launches in adjacent Asia-Pacific markets.
- Hydraulic geometry IP fragmentation:Proprietary impeller vane designs and diffuser configurations are subject to overlapping patent claims, complicating clean-sheet development for mid-tier competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Domestic Booster Pump Market |
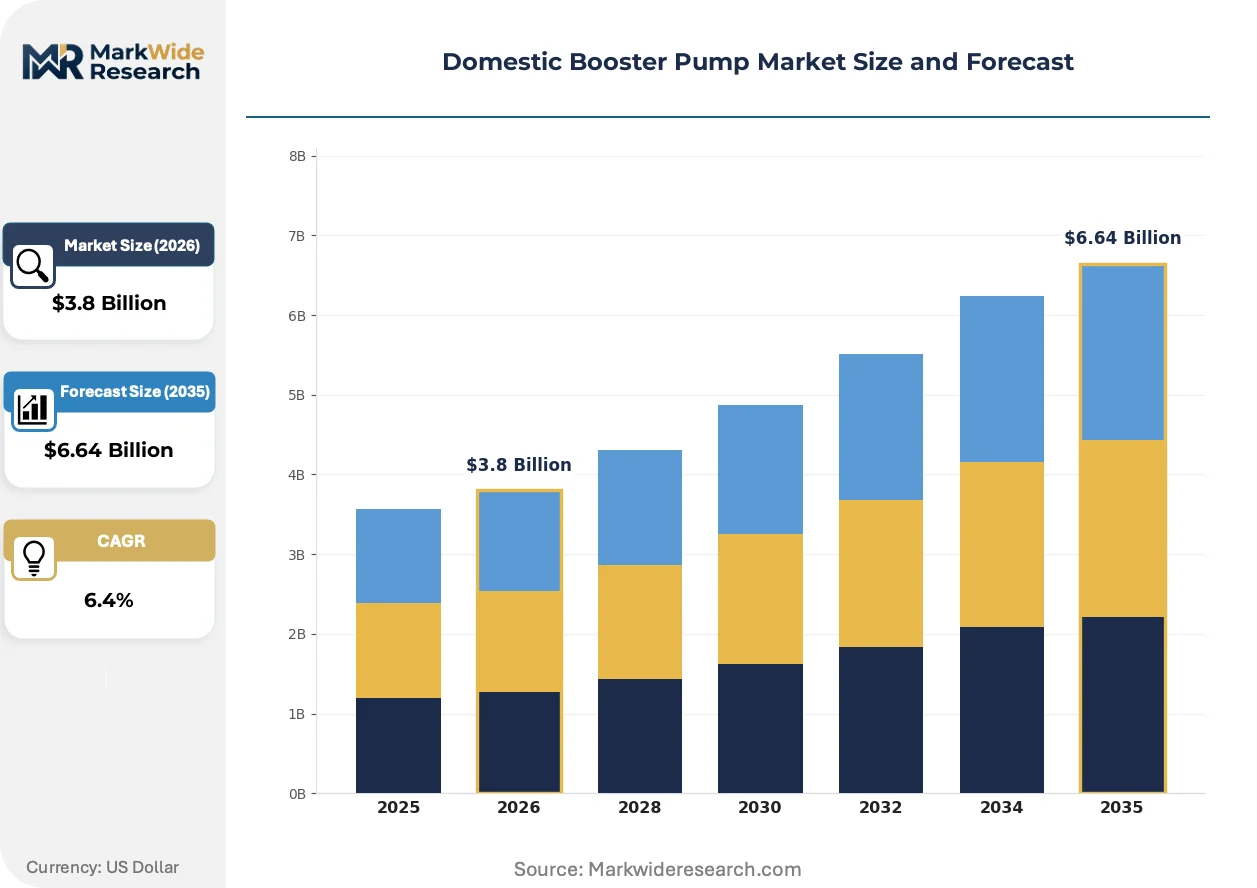
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Pumps, Multistage Pumps, Jet Pumps, Centrifugal Pumps Technology: Energy Efficient, Variable Frequency Drive, Split Case, Submersible Application: Residential Complexes, Commercial Buildings, Municipal Supply, Irrigation Systems, Fire Fighting Systems End User: Property Developers, Facility Managers, Water Treatment Firms, Irrigation Contractors |
| Companies Covered | KSB SE & Co. KGaA, Pentair plc, Grundfos Holding A/S, DAB Pumps S.p.A., Franklin Electric Co., Inc., Xylem Inc., Ebara Corporation, Pedrollo S.p.A., Wilo SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Domestic Booster Pump Market Strategic Shifts & Innovations
Permanent magnet synchronous motor technology is displacing conventional induction architectures across premium product tiers, while regulatory calibration cycles in major economies are compressing design refresh timelines. Procurement behaviors are fragmenting as large property developers internalize specification authority previously held by mechanical contractors.
Variable frequency drive control logic is integrating adaptive pressure-sensing algorithms that modulate pump speed against real-time demand curves rather than fixed setpoints. High-rise residential developers in Shanghai and Mumbai are specifying these configurations to meet stringent energy budgets. The technology is integrating predictive load-balancing capabilities that reduce simultaneous peak demand charges for building operators.
The US Department of Energy pump efficiency standards are tightening minimum hydraulic efficiency thresholds for circulators and clean water pumps, forcing redesigns of volute geometries and impeller blade angles. Manufacturers serving the North American market are consolidating product platforms to reduce certification burden duplication. The regulation most acutely affects fractional horsepower residential units where margin compression limits redesign investment recovery.
Specification authority is migrating from mechanical contractors to centralized procurement functions within large property development groups, compressing vendor negotiation cycles and unbundling after-sales service from equipment supply. Direct manufacturer relationships are displacing traditional distribution intermediaries in commercial segments above 50-unit annual volume. This shift concentrates most visibly in Germany's residential construction sector where institutional developers dominate new build pipelines.
Domestic Booster Pump Market Segmentation
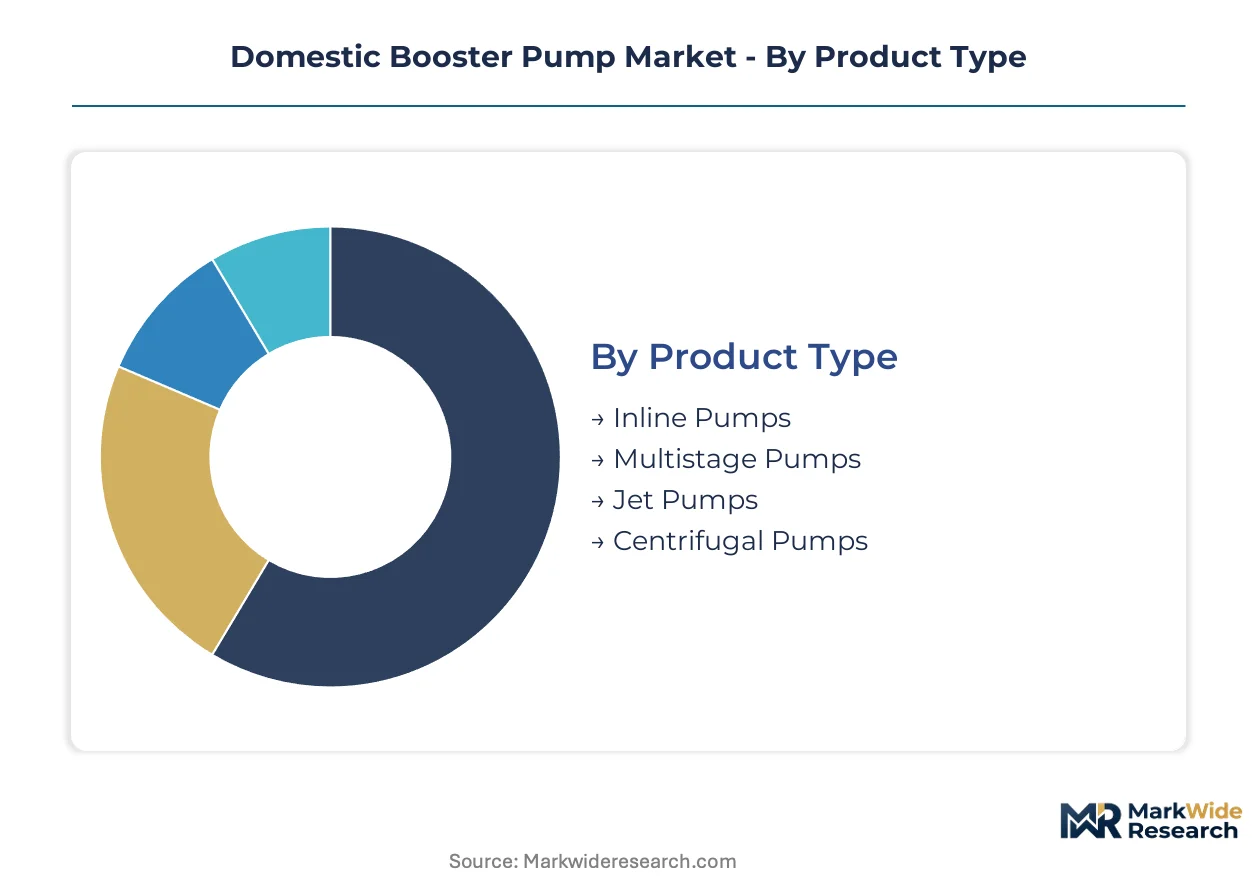
Domestic booster pump purchasing decisions split sharply between first-cost minimization in volume residential construction and lifecycle optimization in premium commercial installations. Specification authority migration from mechanical contractors to developer procurement desks compresses vendor lists while fragmenting technical requirements across building typologies.
Product Type:
Volume deployment favors standardized configurations with minimal customization, while premium installations demand engineered pressure-zone matching.
- Inline Pumps:Compact axial-flow designs mount directly within piping runs, eliminating footprint penalties in mechanical rooms. Demand concentrates in Germany's existing commercial building replacement cycles where space constraints previously blocked multistage retrofits. Installation simplicity drives specification among facility managers lacking specialized pump technicians.
- Multistage Pumps:Stacked impeller arrays generate discharge heads exceeding 60 meters through sequential pressure amplification. China's Yangtze River Delta high-rise residential towers above 20 stories specify these configurations to overcome municipal pressure deficits at upper zones. Copper rotor die-casting in motor assemblies extends bearing life under continuous duty cycles.
- Jet Pumps:Ejector-assisted suction lifts water from shallow wells or cisterns in rural Indian residential clusters outside Pune and Hyderabad municipal grids.
- Centrifugal Pumps:Single-stage volute designs dominate irrigation contractor procurement for agricultural pressure-boosting across India's Maharashtra and Gujarat farming belts.
Mature deployment sits with Inline Pumps in European commercial retrofit. Newer deployment is concentrated in Multistage Pumps across Asia-Pacific high-rise construction.
Technology:
Regulatory efficiency mandates are bifurcating the installed base between legacy induction motor stock and electronically commutated replacements.
- Energy Efficient:Electronically commutated motors with permanent magnet rotors cut input power by 30-50% versus conventional induction designs. EU Ecodesign Directive thresholds are phasing out non-compliant units across French and Italian residential building stock. India's BIS energy labeling requirements create parallel compliance pressure in Mumbai and Bangalore developer specifications.
- Variable Frequency Drive:Adaptive speed control modulates pump output against real-time pressure sensors rather than fixed setpoints. China's GB standards for motor efficiency and Shanghai municipal green building codes accelerate adoption in Yangtze River Delta residential towers. Predictive load-balancing algorithms reduce simultaneous peak demand charges for commercial property operators.
- Split Case:Double-suction impeller configurations handle flow rates above 50 cubic meters per hour in municipal water treatment firm installations.
- Submersible:Immersed motor-pump units serve deep borewell applications for irrigation contractors across Saudi Arabia's central agricultural regions.
Split Case technology anchors municipal-scale infrastructure with decade-long replacement cycles. Variable Frequency Drive is gaining share fastest in residential and commercial new-build specifications.
Application:
End-use concentration determines pressure-zone complexity, duty cycle intensity, and regulatory exposure.
- Residential Complexes:Stacked pressure zones in towers exceeding 15 stories demand zone-specific pump arrays with independent controls. India's tier-two cities including Ahmedabad and Chandigarh drive volume as municipal pressure inconsistency forces developer-installed supplementation. BIS electrical safety certification requirements tighten product compliance thresholds for organized sector suppliers.
- Commercial Buildings:Continuous-duty requirements and energy benchmarking mandates favor VFD-equipped multistage configurations. Germany's institutional developer sector specifies these units in Düsseldorf and Frankfurt office construction to meet EnEV thermal building code energy budgets. Predictive maintenance contracts are unbundling from equipment supply in direct manufacturer relationships.
- Municipal Supply:Distribution network endpoint boosting in legacy European cities faces capital allocation competition from pipeline replacement programs.
- Irrigation Systems:Seasonal duty cycles and first-cost sensitivity dominate procurement across Indian agricultural pump markets.
- Fire Fighting Systems:UL/FM certification requirements and standby reliability mandates create specification barriers distinct from general service pumps.
Municipal Supply represents the most mature replacement cycle with deferred capital commitments. Residential Complexes show the steepest expansion trajectory across Asia-Pacific urbanization corridors.
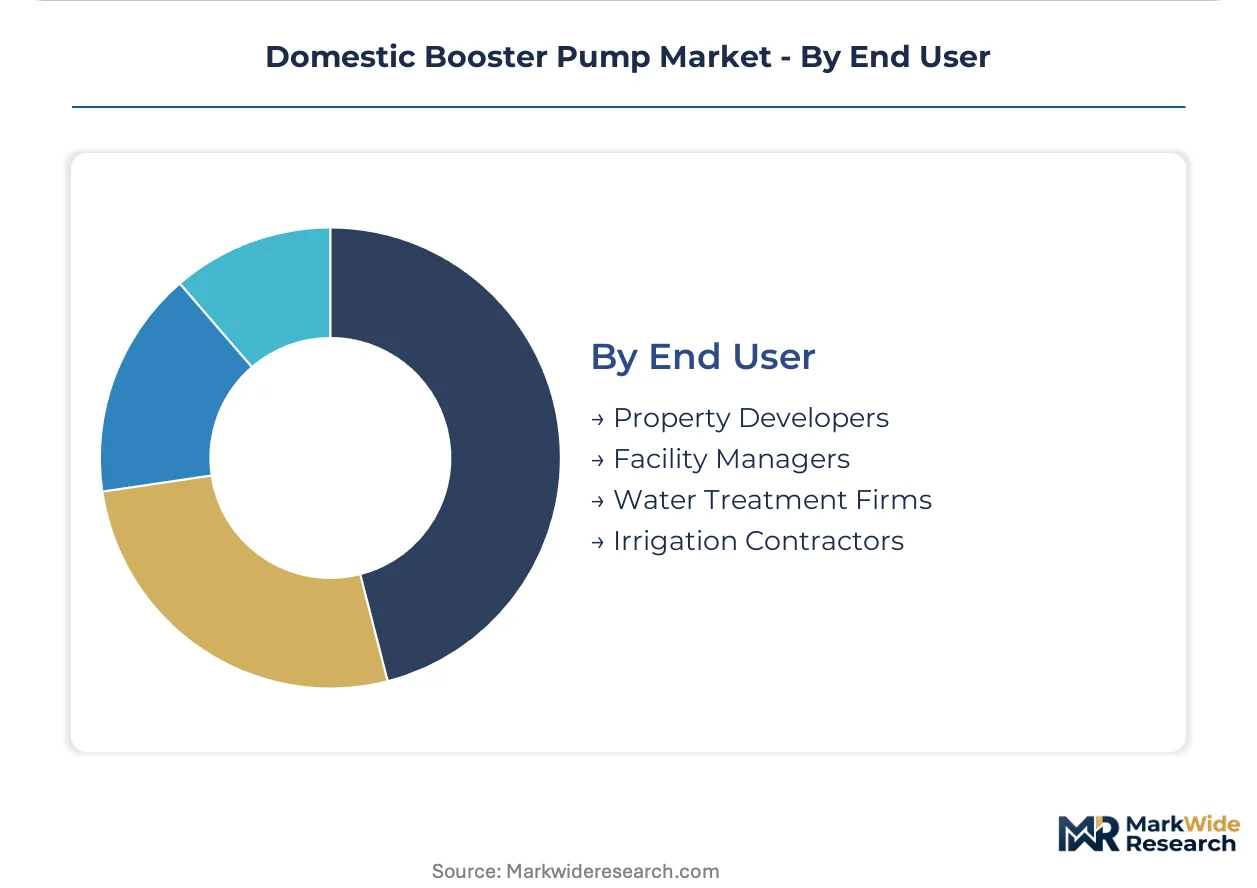
End User:
Procurement sophistication varies sharply between centralized developer purchasing and distributed contractor specification.
- Property Developers:Large residential construction groups in China and India internalize specification authority previously held by mechanical contractors. Direct manufacturer relationships compress negotiation cycles and unbundle after-sales service from equipment supply. Annual volumes above 50 units trigger centralized procurement desk involvement.
- Facility Managers:Operating expenditure accountability drives total cost of ownership calculations favoring extended-warranty VFD configurations. Germany's commercial building sector exhibits this pattern most visibly where energy benchmarking disclosure requirements expose pump efficiency performance.
- Water Treatment Firms:Municipal contract operators prioritize mean-time-between-failure metrics over first-cost minimization in plant auxiliary systems.
- Irrigation Contractors:Price-sensitive procurement across Indian agricultural markets favors standardized centrifugal configurations with minimal control complexity.
Irrigation Contractors represent the most price-elastic demand segment with minimal technology differentiation. Property Developers are concentrating specification authority fastest through procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration clusters in Asia-Pacific high-rise corridors and European retrofit markets, with municipal pressure deficits and energy efficiency mandates driving specification divergence across geographies.
China
High-rise residential towers above 20 stories in Shanghai and the Yangtze River Delta require multistage pump configurations with sequential impeller arrays. GB standards for motor efficiency and Shanghai municipal green building codes accelerate VFD adoption. Suzhou and Hangzhou construction clusters specify zone-specific pump arrays with independent controls for stacked pressure zones.
India
Tier-two cities including Pune, Hyderabad, and Ahmedabad drive volume as municipal water pressure inconsistency forces developer-installed supplementation. BIS certification requirements for electrical safety and energy labeling tighten compliance thresholds for organized sector suppliers. Residential complexes across Maharashtra and Gujarat farming belts specify copper rotor die-cast motors for extended bearing life under continuous duty.
Germany
Existing commercial building replacement cycles favor compact inline pump configurations where space constraints previously blocked multistage retrofits. The EU Ecodesign Directive phases out single-speed induction motors, redirecting demand toward electronically commutated units. Institutional developers in Düsseldorf and Frankfurt specify VFD-equipped multistage configurations to meet EnEV thermal building code energy budgets.
United States
Fractional horsepower residential units face acute margin compression as DOE pump efficiency standards tighten minimum hydraulic efficiency thresholds. Circulator redesigns concentrate volute geometry optimization and impeller blade angle refinement. California and Texas construction clusters drive specification authority migration from mechanical contractors to centralized developer procurement functions.
Italy
Commercial building energy benchmarking disclosure requirements expose pump efficiency performance, driving total cost of ownership calculations among facility managers. French and Italian residential building stock replacement cycles favor electronically commutated motors cutting input power versus conventional induction designs. Lombardy and Veneto industrial clusters supply hydraulic components for European OEM integration.
Domestic Booster Pump Market Key Industry Players
Technology licensing dominates the current landscape as manufacturers seek VFD control logic and permanent magnet motor architectures without captive R&D investment. The vendor base stratifies across three tiers: integrated hydraulic-motor specialists, component assemblers sourcing drives and motors from third parties, and regional fabricators serving price-sensitive agricultural and rural residential segments. Two strategic archetypes anchor competitive positioning: backward-integrated motor producers controlling cost volatility, and system integrators bundling predictive maintenance algorithms with hardware supply. M&A activity concentrates on VFD software capabilities and regional distribution networks.
Among European-based integrated specialists, KSB SE & Co. KGaA and Grundfos Holding A/S exemplify the backward-integrated archetype with in-house motor production, while Wilo SE occupies a position emphasizing localized assembly operations. Xylem Inc. represents the system-integrator vector with advanced drive integration capabilities. These three entities anchor the premium tier where specification authority migration toward developer procurement desks concentrates vendor selection.
| Leading Market Players |
|---|
| KSB SE & Co. KGaA |
| Pentair plc |
| Grundfos Holding A/S |
| DAB Pumps S.p.A. |
| Franklin Electric Co., Inc. |
| Xylem Inc. |
| Ebara Corporation |
| Pedrollo S.p.A. |
| Wilo SE |
| Others |
Cost & Logistics Intelligence
EU Ecodesign Directive mandates on motor efficiency are forcing manufacturers toward copper rotor die-casting and permanent magnet synchronous architectures, compressing margins on legacy induction motor inventories while elevating certified product premiums. This specification shift concentrates pricing power with backward-integrated motor producers who control rare earth magnet and precision casting supply.
Pricing Analysis
Volume deployment in Indian tier-two cities runs on per-unit transactional pricing with minimal after-sales bundling, while premium commercial installations in Germany and China command project-based structures incorporating predictive maintenance subscriptions. Price differentiation rests on BIS certification tier and VFD control sophistication, with copper rotor die-cast motors capturing 15-20% premiums over standard induction units. Cost compression in fractional horsepower residential segments stems from DOE efficiency standard compliance investments. Irrigation contractors across Maharashtra and Gujarat exhibit maximal price sensitivity, whereas institutional developers in Shanghai specify lifecycle-optimized configurations with minimal first-cost weighting.
Supply Chain Analysis
Neodymium-dysprosium magnet supply rests on Chinese Inner Mongolia and Jiangxi processing corridors, tethering permanent magnet synchronous motor cost structures to export quota volatility. Copper winding wire draws from Chilean and Indonesian smelter output, while precision die-casting capacity concentrates in German and Italian automotive supplier networks. Single-source vulnerability in rare earth separation exposes margin stability to geopolitical calibration. Distribution runs through regional pump distributors in fragmented Indian markets, shifting toward direct manufacturer relationships in European developer procurement above 50-unit annual volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rare earth magnet supply concentration props pricing for certified efficient motors, constraining volume expansion by unorganized assemblers lacking magnet procurement scale.
For Market Incumbents: Lock in copper rotor die-casting capacity through equipment supplier partnerships in Lombardy and Veneto industrial clusters. Deepen captive magnet sourcing relationships with Jiangxi processors before quota tightening accelerates. Certification investment in simultaneous BIS and GB marking compresses platform launch timelines against mid-tier competitors lacking compliance infrastructure. For New Entrants and Emerging Players: India's BIS certification tightening in electrical safety opens a window for organized sector specification in Pune and Hyderabad residential complexes. Target retrofit-focused inline configurations in Germany's existing commercial building stock where space constraints previously excluded multistage competitors. Pursue direct facility manager relationships unbundling predictive maintenance from equipment supply. For Investors and Strategic Acquirers: Re-rating potential sits with VFD software specialists given smart building integration mandates across Shanghai and Mumbai green building codes. Acquisition focus should center on control logic developers with adaptive pressure-sensing algorithms and IoT platform integration. Watch for BIS certification timeline compression as inflection signal for organized sector share capture acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Copper Rotor Die-Casting Capacity Expansion | Grundfos and KSB backward integration into motor production controls cost volatility across European supply chains. |
| VFD Control Logic Acquisition | Xylem's advanced drive integration capabilities enable subscription-based service models for commercial property operators. |
| Dual Certification Investment | Simultaneous BIS and GB marking reduces platform launch delays in adjacent Asia-Pacific markets. |
| Localized Assembly Operations | Wilo's China and India manufacturing footprint compresses logistics costs and import duty exposure. |
| Predictive Maintenance Platform Development | IoT-enabled pressure monitoring converges with building management systems in German EnEV-compliant construction. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pump OEM procurement directors, facility managers at German institutional developers, and irrigation contractors across Maharashtra. BIS certification databases, EU Ecodesign Directive implementation reports, and Chinese customs export records provided volume calibration. Bottom-up triangulation against top-down construction spend data validated segment-level projections.
Data-stream reconciliation across product type, technology architecture, application intensity, and end-user procurement sophistication informed the analytical framework. CAGRs derived from installed base turnover modeling and new-build specification penetration curves. Rare earth magnet price volatility assumptions and municipal infrastructure investment deferral patterns shaped scenario boundaries.
The model assumes a particular technology adoption path; alternative pathways for permanent magnet synchronous motor displacement of induction architectures would alter the outlook. Forecasts reflect assumptions on BIS enforcement intensity and EU Ecodesign phase-out timelines. Regulatory calibration cycles, copper price volatility, and rare earth export quota shifts warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
End Suction Pump Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Flow Back Equipment Market