
 Hydrogen Fuel Cell Drone Market | 2026-2036
Hydrogen Fuel Cell Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Fuel Cell Drone Market Insights
The EU AI Act is broadening the compliance burden for autonomous flight systems across European airspace. Intelligent Energy leverages its air-cooled fuel cell stack architecture to sustain endurance advantages in commercial surveillance contracts. PowerCell Sweden AB anchors Nordic defense procurement through its modular power platform designed for sub-zero operations. Heven AeroTech competes in Israeli precision-agriculture deployments with hydrogen drones rated for extended loiter times.
A hydrogen fuel cell drone converts pressurized hydrogen gas into electrical energy via a proton exchange membrane, producing water vapor as exhaust while delivering 3-5 times the energy density of lithium-ion batteries for multi-hour flight missions. Rotary-wing configurations dominate current procurement because vertical takeoff eliminates runway infrastructure at remote agricultural and environmental monitoring sites. PEM fuel cells lead technology adoption due to their cold-start reliability and power-to-weight ratios, while solid oxide variants remain confined to experimental high-altitude platforms where thermal efficiency outweighs mass penalties. Defense agencies represent the deepest margin pool among end users, though logistics companies show the fastest contract velocity for last-mile hydrogen delivery trials.
The FAA in the United States imposes type-certification barriers that delay hydrogen storage tank approvals for commercial drone operations, while EASA in Europe advances dedicated hydrogen propulsion airworthiness standards that accelerate market access for compliant manufacturers. ISO 14687 hydrogen fuel quality specifications shape component sourcing decisions for stack suppliers targeting international distribution. Stakeholders must monitor which regulator first resolves cryogenic tank crashworthiness protocols, as that jurisdiction will attract disproportionate fleet deployment commitments.
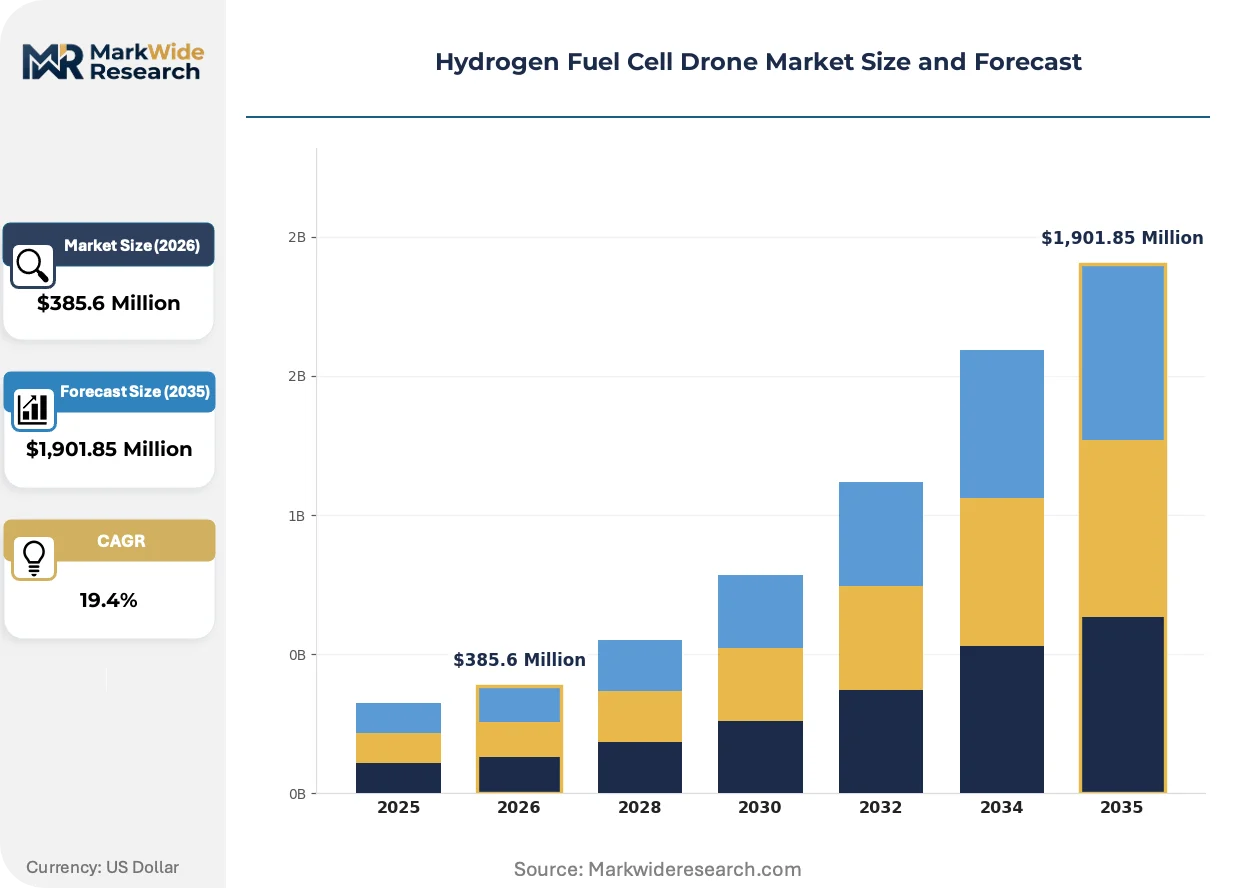
Market Dynamics
The EU AI Act is forcing autonomous flight system redesigns across European airspace, while PEM fuel cell supply chain concentration in East Asian manufacturing clusters compresses component lead times and pricing power for Western assemblers.
Growth Catalysts
- EU Green Deal emissions mandates:German logistics operators are scaling hydrogen-powered delivery fleets to meet binding carbon reduction targets for urban freight corridors.
- PEM fuel cell cost breakthroughs:Manufacturing clusters in South Korea and Japan have achieved stack production efficiencies that lower unit economics for commercial drone procurement.
- Defense surveillance contracts:Nordic military agencies are issuing multi-year tenders for sub-zero capable hydrogen drones, creating anchor demand for extended-endurance platforms.
Market Restraints
- FAA type-certification barriers:Hydrogen storage tank approvals for commercial drone operations face extended review timelines that delay US market entry.
- Platinum catalyst supply concentration:Stack manufacturers depend on South African and Russian platinum group metal refining, exposing production to geopolitical input volatility.
- Lithium-ion substitution threat:Solid-state battery prototypes from Chinese cell suppliers are approaching energy density parity for sub-two-hour missions.
Strategic Opportunities
- Israeli precision-agriculture expansion:Extended loiter hydrogen drones are penetrating orchard mapping and irrigation monitoring contracts in water-stressed growing regions.
- EASA hydrogen propulsion standards:Dedicated airworthiness frameworks for fuel cell systems are accelerating certification pathways for compliant European manufacturers.
- Cryogenic tank crashworthiness resolution:The first jurisdiction to validate liquid hydrogen storage safety protocols will attract disproportionate fleet deployment commitments from logistics operators.
Industry Challenges
- Hydrogen infrastructure technician scarcity:Fleet operators face recruitment bottlenecks for personnel certified in high-pressure gas handling and fuel cell stack maintenance.
- ISO 14687 compliance complexity:Fuel quality specification testing adds certification overhead for stack suppliers targeting international distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Fuel Cell Drone Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,901.85 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, VTOL Technology: PEM Fuel Cells, Solid Oxide Fuel Cells, Alkaline Fuel Cells, Phosphoric Acid Fuel Cells Application: Surveillance, Delivery Services, Agricultural Monitoring, Environmental Research, Mapping End User: Defense Agencies, Logistics Companies, Agricultural Firms, Scientific Institutions |
| Companies Covered | Intelligent Energy, PowerCell Sweden AB, Heven AeroTech, Delair, AFC Energy, H3 Dynamics, Ballard Power Systems, Doosan Fuel Cell, Crinum Clean Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Fuel Cell Drone Market Trends and Innovations
Air-cooled fuel cell architectures are compressing thermal management mass, enabling payload trade-offs that reshape competitive positioning in surveillance and logistics segments.
PEM fuel cell systems are overtaking liquid-cooled alternatives in commercial procurement because air-cooled stacks eliminate radiator weight and plumbing complexity. Agricultural operators in Australia and environmental monitoring agencies in Canada are specifying air-cooled platforms for remote deployments lacking maintenance infrastructure. The technology is overtaking legacy thermal designs in contracts where every gram of saved mass translates to extended flight time or additional sensor payload.
EASA's dedicated hydrogen propulsion airworthiness standards are creating regulatory clarity that the FAA has yet to match. European manufacturers are filing type certificates under accelerated pathways while US competitors await hydrogen storage tank crashworthiness protocols. Israeli precision-agriculture deployers are routing procurement through EASA-compliant suppliers to avoid FAA certification delays.
Buyers are unbundling after-sales service from hardware procurement, forcing stack suppliers to price maintenance contracts separately from initial platform sales. Defense agencies in the Nordics are leading this shift, issuing performance-based logistics contracts that penalize downtime rather than rewarding spare parts volume. German logistics operators are adopting similar structures for last-mile delivery trials, transferring operational risk to hydrogen system integrators.
Hydrogen Fuel Cell Drone Market Segmentation
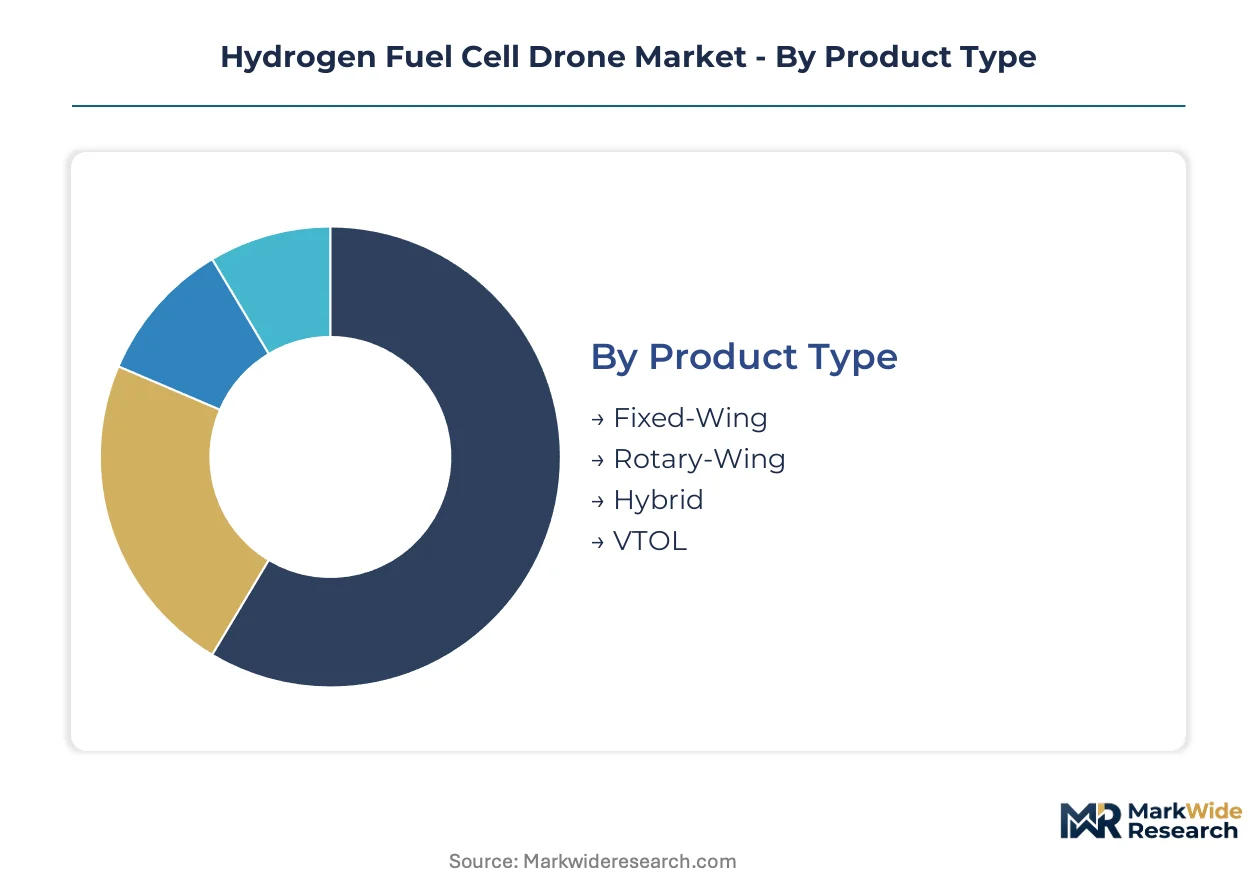
Hydrogen fuel cell drone procurement varies sharply by operational profile, with capital requirements and certification complexity driving divergent buyer behaviors across configurations and use cases. Segment boundaries are hardening as EASA and FAA standards force technology-specific compliance investments that reshape vendor economics.
Product Type:
Capital intensity peaks with hybrid architectures requiring dual propulsion certification, while rotary-wing platforms concentrate volume through simpler airworthiness pathways.
- Fixed-Wing:Long-endurance platforms with optimized lift-to-drag ratios excel in corridor surveillance and pipeline inspection contracts across Australian outback and Canadian boreal zones. German logistics operators favor fixed-wing hydrogen drones for inter-city freight routes where runway access exists, though infrastructure scarcity limits deployment in remote agricultural regions.
- Rotary-Wing:Vertical takeoff capability eliminates runway dependency, making these the default specification for Israeli precision-agriculture deployments and Nordic environmental monitoring stations. South Korean manufacturing clusters supply the PEM stacks that power most rotary-wing procurement, compressing lead times for commercial buyers.
- Hybrid:Dual-mode systems combining fixed-wing cruise efficiency with rotary-wing landing precision command premium pricing for specialized defense surveillance tenders.
- VTOL:Tilt-rotor configurations are penetrating urban delivery trials in German cities where EU Green Deal emissions mandates restrict conventional logistics fleets.
Most installed capacity flows through Rotary-Wing. Expansion is steepest in VTOL.
Technology:
Stack architecture determines thermal management mass, payload trade-offs, and cold-start reliability across divergent operating environments.
- PEM Fuel Cells:Proton exchange membrane systems deliver superior power-to-weight ratios and sub-zero startup reliability that anchors Nordic defense procurement. South Korean and Japanese manufacturing clusters have achieved production efficiencies that lower unit economics for commercial drone assemblers targeting agricultural and logistics segments.
- Solid Oxide Fuel Cells:High-temperature operation yields thermal efficiency advantages for experimental high-altitude platforms where mass penalties are acceptable. Japanese research institutions are testing solid oxide variants for stratospheric communications relay missions exceeding 20-hour endurance targets.
- Alkaline Fuel Cells:Lower catalyst costs attract price-sensitive buyers in emerging markets, though water management complexity restricts adoption in sub-zero climates.
- Phosphoric Acid Fuel Cells:Mature stationary technology is finding limited drone application in heavy-lift cargo prototypes where tolerance for system mass exists.
PEM Fuel Cells dominate procurement volumes. Solid Oxide Fuel Cells are gaining share fastest in experimental high-altitude programs.
Application:
Flight-hour intensity and sensor payload requirements create divergent total-cost-of-ownership profiles across use cases.
- Surveillance:Extended loiter missions for border patrol and critical infrastructure protection generate the deepest margin pools among hydrogen drone applications. Israeli defense contractors specify air-cooled PEM stacks for orchard perimeter monitoring contracts in water-stressed growing regions.
- Delivery Services:Last-mile urban freight trials in German cities under EU Green Deal mandates are driving contract velocity for hydrogen-powered logistics fleets. Fleet operators face recruitment bottlenecks for technicians certified in high-pressure hydrogen handling and fuel cell stack maintenance.
- Agricultural Monitoring:Precision irrigation and crop health mapping in Australian and Israeli growing regions favors rotary-wing platforms with sub-hour refueling cycles.
- Environmental Research:Arctic and alpine monitoring agencies in Canada and the Nordics require cold-start reliability that PEM systems deliver.
- Mapping:Photogrammetry and LiDAR survey contracts demand stable power output for sensor-heavy payloads in remote terrain lacking grid access.
Surveillance commands the highest platform pricing. Delivery Services are climbing the fastest as logistics operators scale trial fleets.
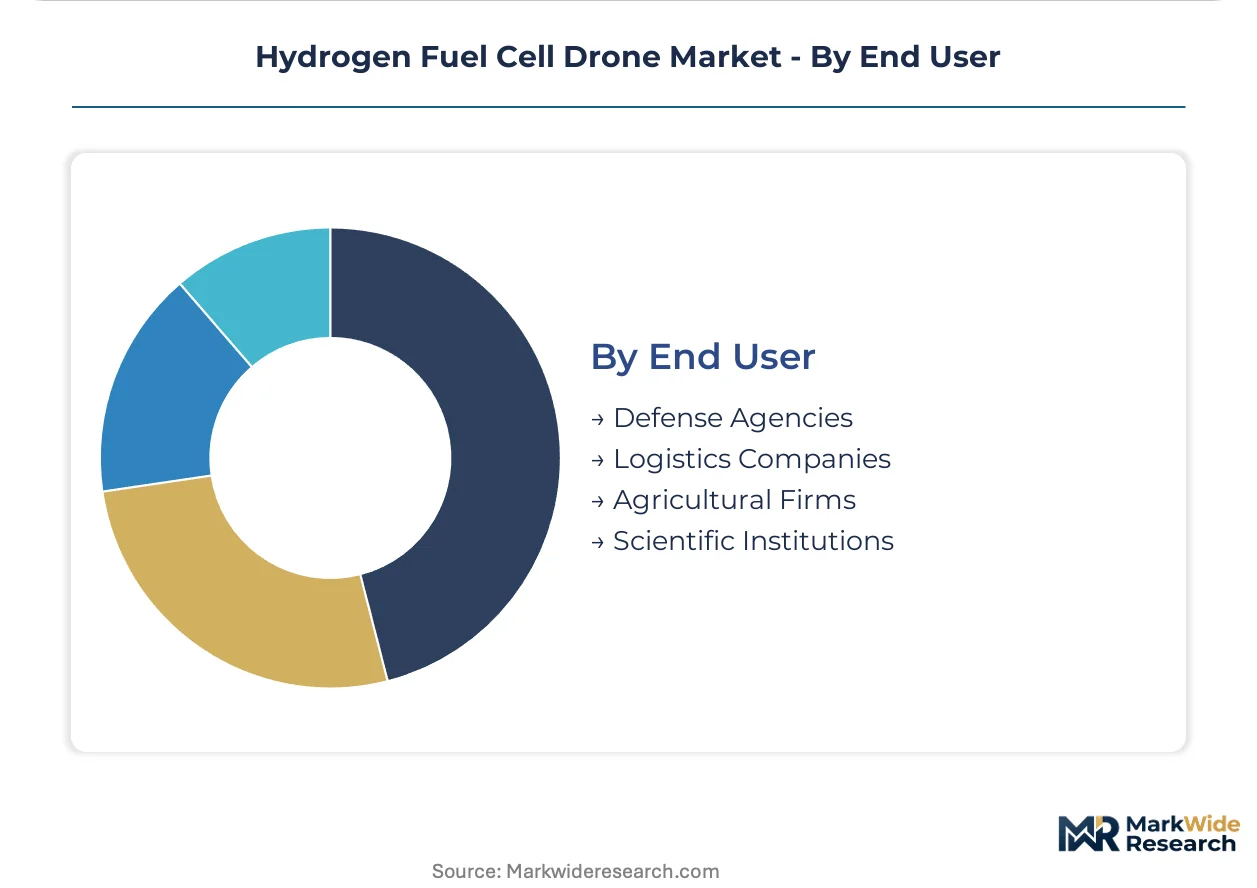
End User:
Procurement sophistication and contract structure vary sharply between risk-tolerant defense agencies and margin-constrained commercial operators.
- Defense Agencies:Nordic military tenders for sub-zero capable platforms create anchor demand with multi-year performance-based logistics contracts that penalize downtime. PowerCell Sweden AB anchors this segment through modular power platforms designed for Arctic operations.
- Logistics Companies:German operators are unbundling after-sales service from hardware procurement, transferring operational risk to hydrogen system integrators through outcome-based maintenance agreements.
- Agricultural Firms:Israeli and Australian growers prioritize acquisition cost over lifecycle economics, slowing adoption of premium fuel cell platforms.
- Scientific Institutions:Research funding cycles and grant dependency create lumpy procurement patterns for environmental monitoring and atmospheric sampling missions.
Defense Agencies concentrate the highest-value contracts. Logistics Companies are expanding procurement most aggressively as EU emissions mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German logistics operators are recruiting hydrogen-certified technicians at rates outpacing available training pipelines, anchoring European workforce development for fuel cell aviation.
United States
Defense surveillance contracts in Arizona and New Mexico drive demand for extended-loiter platforms. FAA type-certification barriers for hydrogen storage tanks delay commercial rollout, forcing developers toward experimental airworthiness certificates. The Mojave Desert test corridor concentrates validation activity for high-altitude fuel cell prototypes.
Germany
Urban freight operators in Berlin and Hamburg are scaling hydrogen delivery fleets under binding EU Green Deal emissions targets. EASA hydrogen propulsion standards accelerate certification timelines for compliant manufacturers. The Bavarian aerospace cluster around Munich hosts stack integration facilities serving Nordic defense procurement.
South Korea
PEM fuel cell manufacturing gravity centers on Gyeonggi-do and Incheon, where production efficiencies compress stack pricing for export markets. METI-aligned research funding supports dual-use civilian-military drone development. Seoul-based system integrators supply rotary-wing platforms to Australian agricultural monitoring contracts.
Japan
Stratospheric communications relay programs in Nagoya and Tokyo test solid oxide variants for 20-hour endurance missions. JIS standards alignment shapes component sourcing for stack suppliers targeting international distribution. The Chubu region anchors high-temperature fuel cell research absent from commercial procurement volumes.
Israel
Precision-agriculture deployers in the Negev and Galilee regions specify extended-loiter hydrogen drones for orchard mapping in water-stressed growing zones. Defense surveillance tenders create anchor demand for air-cooled PEM architectures. Tel Aviv-area integrators route procurement through EASA-compliant channels to bypass FAA certification delays.
Hydrogen Fuel Cell Drone Market Competitive Landscape
The competitive structure tilts toward technology-anchored specialists rather than diversified industrial conglomerates. Stack manufacturers and airframe integrators occupy distinct tiers with limited vertical overlap. Two archetypes dominate: air-cooled PEM stack specialists and full-system integrators bundling fuel cell power with flight platforms. Capacity expansion in East Asian manufacturing clusters and strategic partnerships for EASA certification acceleration represent the primary competitive moves reshaping vendor positioning.
Within the European specialist tier, Intelligent Energy and PowerCell Sweden AB exemplify divergent thermal management approaches, while Heven AeroTech occupies a position among Israel-based precision-agriculture platform developers. These three entities represent distinct geographic and technological anchoring strategies without implying specific market share or revenue scale.
| Leading Market Players |
|---|
| Intelligent Energy |
| PowerCell Sweden AB |
| Heven AeroTech |
| Delair |
| AFC Energy |
| H3 Dynamics |
| Ballard Power Systems |
| Doosan Fuel Cell |
| Crinum Clean Power |
| Others |
Pricing and Supply Chain Analysis
Platinum group metal costs cascade from South African and Russian refineries through PEM fuel cell stack pricing tiers, compressing margins for Western assemblers while East Asian manufacturing clusters exploit captive catalyst sourcing to anchor economy-tier positioning for agricultural drone buyers.
Pricing Analysis
Bundled hardware-plus-service contracts are unbundling as Nordic defense agencies and German logistics operators separate after-sales maintenance from initial platform procurement. Price differentiation rests on EASA certification status and air-cooled versus liquid-cooled thermal architecture grades. Cost compression in the standard tier intensifies because South Korean stack suppliers are exporting at production-parity pricing. Agricultural firms in Australia and Israel exhibit the sharpest price sensitivity, while defense surveillance contractors absorb premium positioning for sub-zero reliability specifications.
Supply Chain Analysis
Freight costs for pressurized hydrogen storage tanks and cryogenic containment systems concentrate procurement leverage with South Korean, Japanese, and German manufacturing clusters. Stack production draws from platinum catalyst feedstock anchored in South African refining and Japanese membrane electrode assembly expertise. Single-source vulnerability in platinum group metal supply exposes production schedules to geopolitical disruption. Distribution runs through EASA-certified system integrators for European defense and logistics contracts, with Israeli precision-agriculture deployers routing through compliant channels to bypass FAA delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EASA certification acceleration in Germany contrasts with FAA hydrogen tank approval delays in the United States, creating divergent cost structures for fleet deployment timelines.
For Market Incumbents: Deepen backward integration into platinum catalyst sourcing or captive membrane electrode assembly capacity to offset South African supply volatility. Secure EASA type-certification pathways ahead of FAA hydrogen storage crashworthiness resolution to anchor European defense procurement. Air-cooled stack specialists must defend against solid-state battery substitution threats in sub-two-hour mission profiles by emphasizing multi-hour endurance payloads.
For New Entrants and Emerging Players: Agricultural cooperatives in water-stressed growing regions represent an underserved buyer archetype with unmet demand for extended-loiter orchard mapping platforms. Israeli precision-agriculture contractors and Australian environmental monitoring agencies offer the most penetrable entry points. A go-to-market angle through EASA-compliant certification bypasses FAA barriers that delay US commercial rollout.
For Investors and Strategic Acquirers: Consolidation pressure builds where stack manufacturers lack captive fuel cell system integration capabilities or EASA certification expertise. Long-term viability over the next decade hinges on regulatory alignment with hydrogen aviation standards rather than battery energy density parity. Acquisition targets should display air-cooled PEM specialization and established Nordic defense contract flow. The signal to watch is which jurisdiction first validates liquid hydrogen tank crashworthiness protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| EASA Certification Acceleration | European manufacturers gain first-mover access to German urban freight trials under EU Green Deal mandates. |
| Air-Cooled Stack R&D Investment | Thermal mass reduction enables payload trade-offs that reshape competitive positioning in surveillance contracts. |
| Platinum Catalyst Supply Agreement | Long-term offtake contracts with South African refiners hedge against geopolitical input volatility. |
| Hydrogen Infrastructure Training Program | Certified technician pipelines resolve recruitment bottlenecks for German logistics fleet operators. |
| Precision-Agriculture Platform Launch | Extended-loiter specifications target Israeli orchard mapping contracts in water-stressed Negev regions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fuel cell stack engineering directors, EASA certification specialists, German logistics fleet procurement managers, and Israeli precision-agriculture system integrators with secondary validation against FAA docket filings, EASA airworthiness standards documentation, ISO 14687 fuel quality specifications, and customs trade data for hydrogen aviation components. Bottom-up stack production estimates and top-down fleet deployment projections were cross-referenced for triangulation.
Comparable-period anchoring linked historical PEM fuel cell cost curves and lithium-ion energy density improvements to the projection horizon across product type, technology architecture, application mission profile, and end-user procurement sophistication dimensions. CAGRs were derived from segment-specific adoption curves and regulatory milestone timing. Forecast inputs incorporated EASA hydrogen propulsion standard advancement rates and platinum group metal supply stability assumptions.
Underlying measurement precision varies by segment; surveillance and defense procurement carry tighter precision than emerging agricultural monitoring applications. Forecasts reflect documented assumptions about regulatory certification timelines and raw material supply continuity. Hydrogen infrastructure technician availability and solid-state battery prototype performance present specific revision risks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Fuel Cell for Data Center Market
Fuel Cell Technology
Global Micro Fuel Cells Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Bipolar Plate Coatings Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Hydrogen Recirculation Blower for Fuel Cell Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
North America Fuel Cell Technology Market