
 Thermal Power Market | 2026-2036
Thermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Power Market Analysis
Multi-source equipment procurement is expanding across the thermal power sector as utilities diversify turbine and boiler supply chains beyond single-vendor dependence. China Huaneng Group leverages its captive manufacturing base to control costs across coal and gas turbine installations. Enel S.p.A. competes through technology leadership in combined cycle efficiency upgrades across European and Latin American fleets. Duke Energy Corporation anchors its regional position through integrated fuel procurement and long-term utility-scale generation contracts in the southeastern United States.
Thermal power denotes electricity generation through the combustion of fossil or biomass fuels to produce steam or hot gases that drive turbine-generator sets, typically operating at steam temperatures exceeding 540 degrees Celsius and pressures above 24 megapascals in supercritical configurations. The primary industrial purpose is reliable baseload and dispatchable intermediate power supply to stabilize grids against renewable intermittency. Steam turbines occupy the largest installed base globally due to decades of coal and nuclear deployment, though gas turbines represent the fastest-growing product category as utilities favor lower-carbon natural gas units. Combined cycle technology captures expanding margin pools by extracting additional energy from waste heat, while coal-fired condensing plants face structural decline under carbon pricing and emissions performance standards.
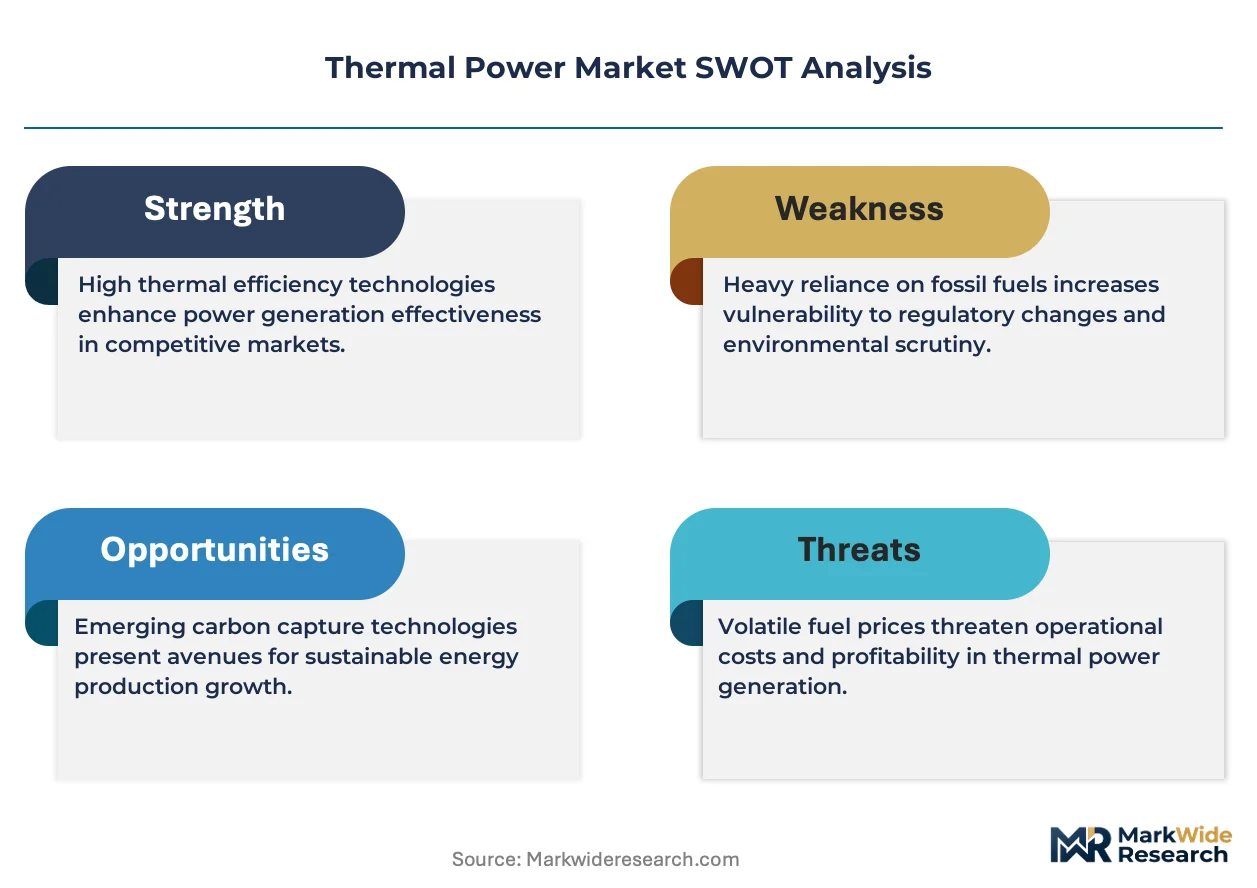
The EPA enforces greenhouse gas performance standards under the Clean Air Act that compel coal plant retirements or carbon capture retrofits, while India's Central Electricity Authority mandates emission norms for particulate matter and sulfur oxides that drive flue-gas desulfurization investments. FERC regulates wholesale power markets and grid interconnection standards that shape thermal plant dispatch economics and revenue models across the United States. Stakeholders must monitor evolving carbon border adjustment mechanisms and technology-neutral capacity market designs that will determine whether thermal assets retain cost competitiveness against battery storage and renewable hybrids.
Market Dynamics
Natural gas combined cycle technology is displacing legacy coal-fired baseload capacity as utilities respond to tightened EPA emissions performance standards and carbon pricing mechanisms across multiple jurisdictions.
Growth Catalysts
- EPA Clean Air Act Standards:Greenhouse gas performance standards compel coal plant retirements and carbon capture retrofits, accelerating gas turbine procurement across United States utilities.
- India CEA Emission Norms:Mandates for particulate matter and sulfur oxides drive flue-gas desulfurization investments and supercritical coal upgrades at state generation companies.
- Industrial Baseload Expansion:Heavy manufacturing and chemical processing sectors expand long-term power purchase agreements for dispatchable thermal electricity.
Market Restraints
- Carbon Pricing Compression:Emissions trading schemes and carbon border adjustment mechanisms erode operating margins for unabated coal-fired assets in European and Asian markets.
- Steam Turbine Supply Concentration:Manufacturing of large-frame gas turbines concentrates among three dominant OEMs, limiting procurement leverage for project developers.
- Intermittency Bridging Costs:Renewable integration requirements impose cycling stress and efficiency penalties on thermal units designed for baseload operation.
Strategic Opportunities
- Hydrogen-Ready Turbine Retrofits:Gas turbine OEMs develop combustion systems compatible with blended hydrogen fuel streams, positioning fleets for low-carbon fuel transitions.
- Waste Heat Recovery Expansion:Combined cycle configurations capture margin pools from industrial cogeneration applications in pulp, paper, and refining sectors.
- India State-Level Procurement:National Thermal Power Corporation and state generators add supercritical capacity to bridge renewable intermittency in Maharashtra, Gujarat, and Tamil Nadu.
Industry Challenges
- Carbon Capture Integration Complexity:Post-combustion capture retrofits require substantial footprint expansion and steam extraction, degrading net plant output and dispatch economics.
- Specialized Welding and Materials Expertise:Supercritical and ultra-supercritical boiler fabrication demands scarce alloy welding certifications and quality assurance capabilities.
- Legacy Control System Obsolescence:Analog turbine control platforms face parts availability constraints, forcing expensive distributed control system migrations at mid-life plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Power Market |
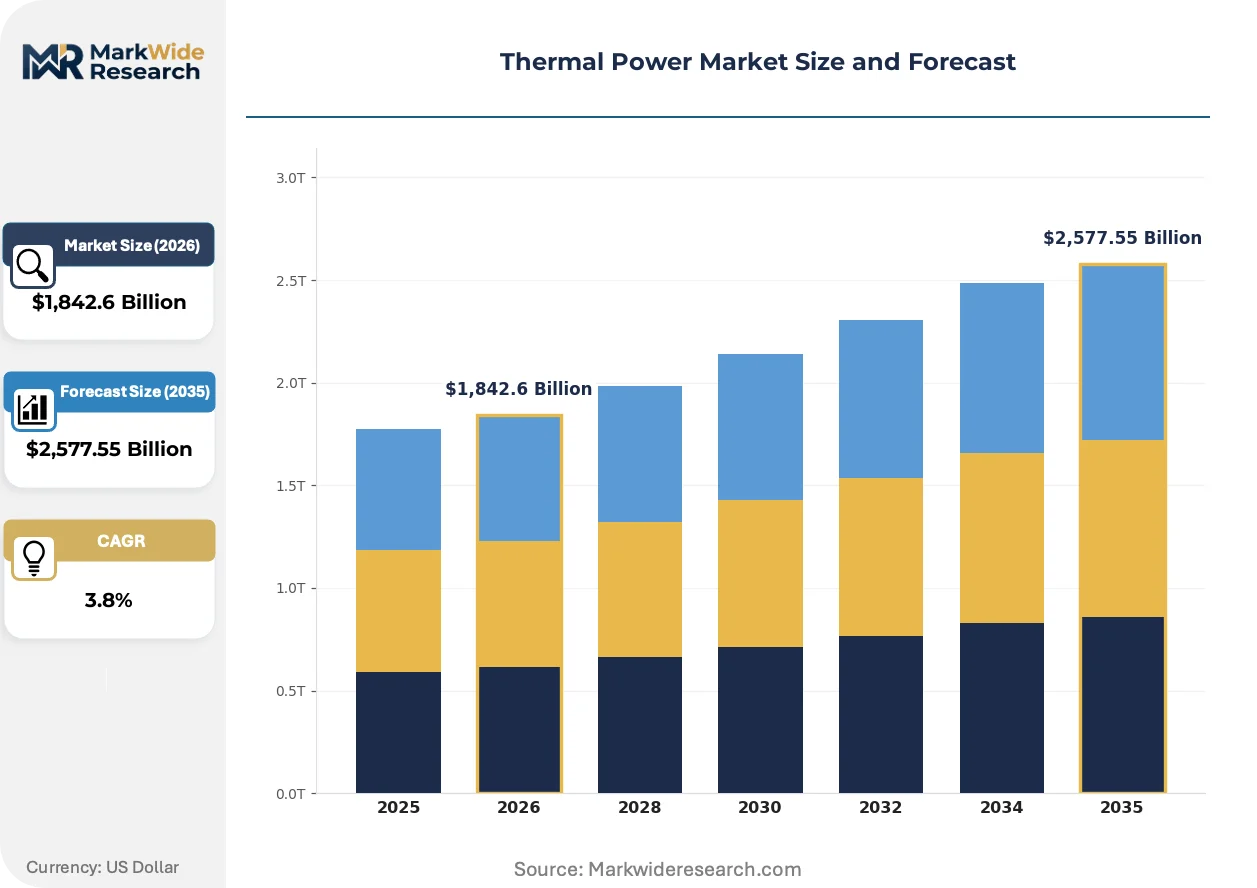
| Market Size in 2026 | $1,842.6 Billion |
| Market Size in 2035 | $2,577.55 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Turbines, Steam Turbines, Heat Recovery Steam Generators, Boilers Technology: Combined Cycle, Open Cycle, Cogeneration, Condensing End User: Utilities, Industrial Consumers, Commercial Systems, Residential Applications Fuel Type: Natural Gas, Coal, Biomass, Oil |
| Companies Covered | American Electric Power Company, Dominion Energy, National Thermal Power Corporation Limited, Enel S.p.A., Southern Company, China Huaneng Group, Tata Power, Adani Power Limited, Duke Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Power Market Emerging Trajectories
Digital twin modeling and advanced combustion monitoring are compressing maintenance intervals and enabling predictive interventions across thermal fleets. Equipment suppliers embed sensor networks and machine learning diagnostics to differentiate service contracts.
Artificial intelligence-based combustion optimization is converging with real-time emissions monitoring to enable automated load-following without manual operator intervention. Duke Energy Corporation deploys these systems across southeastern combined cycle plants to capture ancillary service revenues. The technology is compressing the penalty traditionally assigned to thermal units in renewable-heavy dispatch stacks.
The EPA enforces greenhouse gas performance standards under Section 111 of the Clean Air Act that mandate carbon capture retrofits or retirement for existing coal-fired units. United States utilities face compliance deadlines that compress project development timelines and concentrate engineering resources. Coal-dependent generators in West Virginia and Wyoming respond by evaluating carbon capture feasibility studies and sequestration site acquisitions.
Long-term utility-scale generation contracts are fragmenting into shorter-duration capacity and energy products as independent system operators redesign market structures. Southeastern United States utilities unbundle traditional all-in tariffs into separate capacity, energy, and ancillary service components. This shift concentrates procurement decision-making among commercial trading desks rather than traditional fuel planning departments.
Thermal Power Market Segmentation
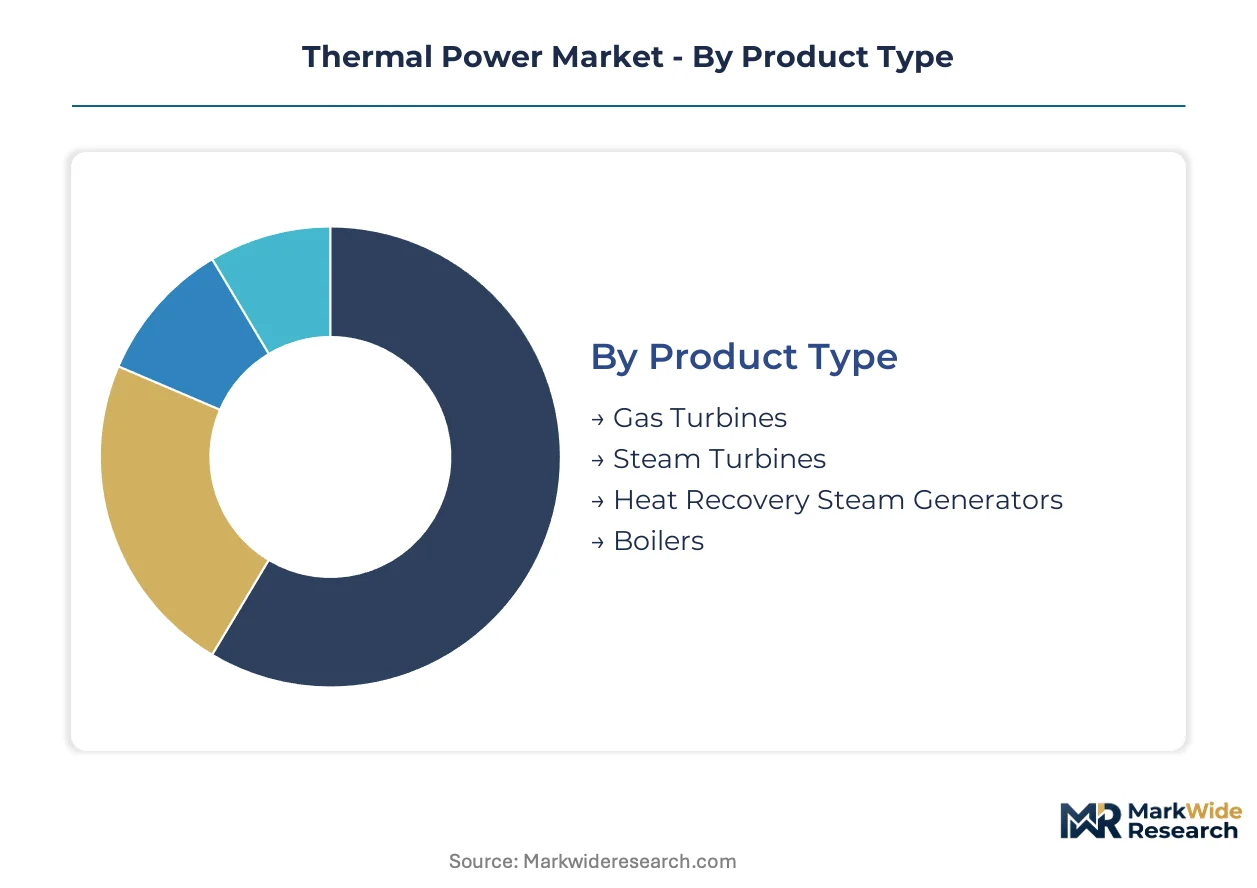
Thermal power equipment procurement hinges on technology certification pathways that determine project approval timelines and interconnection eligibility. Segment boundaries reflect divergent regulatory burdens across EPA, CEA, and EU emissions frameworks.
Product Type:
Gas turbines and steam turbines carry distinct certification requirements under EPA New Source Performance Standards and India's CEA technical specifications for grid synchronization.
- Gas Turbines:Aeroderivative and heavy-frame designs combust natural gas or liquid fuels to drive axial compressors and power turbines at rotational speeds exceeding 3,000 RPM. Demand concentrates in United States combined cycle repowering projects where FERC interconnection standards favor fast-ramping gas turbine flexibility over coal baseload.
- Steam Turbines:Multi-stage impulse-reaction turbines extract energy from high-pressure steam generated by boilers or heat recovery systems, typically operating at 540°C and 24 MPa in supercritical configurations. Indian state generators at NTPC and Maharashtra State Power Generation Company prioritize steam turbine procurement for supercritical coal upgrades mandated under CEA emission norms.
- Heat Recovery Steam Generators:Unfired pressure vessels capture exhaust gas thermal energy from gas turbines to produce steam for secondary power generation or industrial process heat.
- Boilers:Water-tube and fire-tube designs generate steam through fossil fuel or biomass combustion, requiring ASME Section I certification and country-specific pressure vessel codes.
Steam turbines sit at the top of the volume ranking, with gas turbines climbing the fastest.
Technology:
Technology selection determines capital intensity and dispatch economics across baseload, intermediate, and peaking service tiers.
- Combined Cycle:Integrated gas turbine and steam turbine configurations achieve thermal efficiencies exceeding 60% by recovering waste heat from exhaust gases. United States utilities in the Southeast deploy combined cycle plants to capture capacity and ancillary service revenues under FERC-jurisdictional market redesigns.
- Open Cycle:Simple gas turbine arrangements sacrifice efficiency for rapid startup and lower capital cost, serving peak shaving and grid stabilization roles.
- Cogeneration:Simultaneous electricity and useful thermal output serve industrial campuses and district heating networks, qualifying for regulatory incentives in EU member states.
- Condensing:Traditional steam turbine configurations optimized for maximum electrical output rather than thermal utilization dominate legacy coal and nuclear fleets facing retirement pressure.
Combined cycle holds the dominant revenue position, while cogeneration gains share fastest in European industrial applications.
End User:
Customer type shapes contracting structures, from regulated cost-of-service recovery to competitive wholesale market exposure.
- Utilities:Vertically integrated and independent power producers operating under cost-of-service regulation or competitive market rules procure multi-hundred-megawatt installations with 30-year economic lifetimes.
- Industrial Consumers:Heavy manufacturing, chemical processing, and refining sectors secure captive generation or long-term power purchase agreements for process steam and reliable electricity supply.
- Commercial Systems:Hospitals, universities, and data centers deploy smaller-scale cogeneration or backup generation for resilience and demand charge management.
- Residential Applications:Micro-cogeneration and district heating connections represent marginal thermal power demand concentrated in Northern European and Northeast Asian urban centers.
Utilities anchor the installed base, with industrial consumers expanding procurement most aggressively.
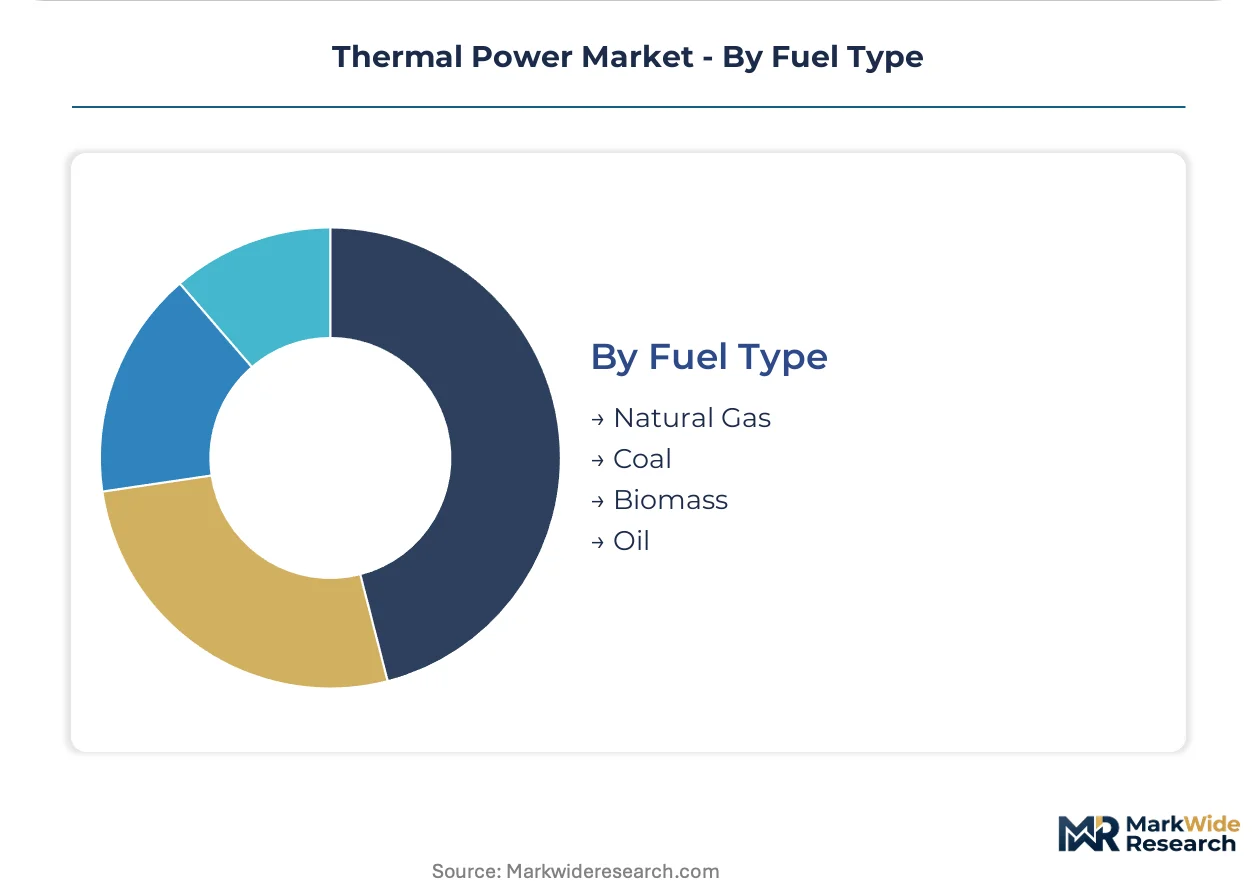
Fuel Type:
Fuel choice determines emissions profile, supply security requirements, and exposure to carbon pricing mechanisms.
- Natural Gas:Methane-fired generation delivers the lowest carbon intensity among fossil thermal options, with combined cycle plants achieving sub-350 gCO2/kWh. United States shale supply growth and LNG infrastructure expansion support gas turbine deployment across Texas, Pennsylvania, and Louisiana generation markets.
- Coal:Pulverized coal and supercritical designs face structural decline under EPA Section 111 performance standards and EU carbon border adjustment mechanisms, though Indian state generators continue supercritical additions for renewable bridging.
- Biomass:Agricultural residues, forestry waste, and energy crops qualify for renewable energy credits in select jurisdictions despite combustion emissions.
- Oil:Distillate and residual fuel oils serve peaking and backup roles where gas infrastructure is unavailable, concentrated in island grids and remote industrial sites.
Natural gas dominates new capacity additions, with biomass carving niche positions in policy-supported markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's industrial corridor anchors thermal power deployment as heavy manufacturing clusters expand baseload procurement. State-level capacity auctions in India, the United States, China, and Germany concentrate procurement decisions among integrated utilities and independent power producers. Regulatory fragmentation across EPA, CEA, and EU emissions frameworks shapes technology certification pathways and project approval timelines.
United States
Southeastern utilities accelerate natural gas combined cycle deployments to replace retiring coal baseload under EPA Section 111 standards. FERC market redesigns unbundle traditional tariffs into capacity, energy, and ancillary service products. Duke Energy Corporation operates across the Carolinas and Florida where dispatchable generation secures grid stability against renewable intermittency.
India
National Thermal Power Corporation and state generators add supercritical coal and gas-fired capacity to bridge renewable gaps in Maharashtra, Gujarat, and Tamil Nadu. Central Electricity Authority emission norms for particulate matter and sulfur oxides drive flue-gas desulfurization investments. Maharashtra State Power Generation Company prioritizes steam turbine procurement for compliance-driven upgrades.
China
Provincial grid operators integrate ultra-supercritical coal units to maintain dispatch reliability amid renewable expansion targets. MIIT efficiency mandates and MEE emissions standards accelerate retirements of subcritical capacity. Yangtze River Delta manufacturing clusters sustain captive thermal generation demand for chemical processing and heavy industry.
Germany
Industrial cogeneration operators navigate EU carbon border adjustment mechanisms and national coal phase-out deadlines. Combined heat and power installations in North Rhine-Westphalia and Bavaria qualify for regulatory incentives under EU Green Deal implementation. ECHA chemical sector regulations influence fuel switching timelines for process steam applications.
Japan
Utilities retrofit existing combined cycle fleets for hydrogen blending compatibility under METI decarbonization roadmaps. Kanto and Kansai industrial corridors maintain gas turbine procurement for grid stabilization. JIS certification requirements and earthquake resilience standards shape equipment specification protocols for coastal installations.
Thermal Power Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hydrogen-ready turbine retrofits and digital service contracts. The market structures around three dominant OEMs controlling large-frame gas turbine manufacturing, constraining procurement leverage for project developers. Strategic archetypes include integrated fuel-procurement utilities, technology-leadership European operators, and captive-manufacturing Chinese state enterprises. Competitive moves concentrate on M&A for regional market access and strategic partnerships for carbon capture integration.
Among Asia-Pacific-based generators, National Thermal Power Corporation Limited and China Huaneng Group exemplify state-backed vertical integration strategies controlling costs across coal and gas installations. Enel S.p.A. occupies a position representing technology-leadership archetypes focused on combined cycle efficiency upgrades across European and Latin American fleets. Duke Energy Corporation anchors the integrated utility model through southeastern United States regional concentration and long-term generation contracting.
| Leading Market Players |
|---|
| American Electric Power Company |
| Dominion Energy |
| National Thermal Power Corporation Limited |
| Enel S.p.A. |
| Southern Company |
| China Huaneng Group |
| Tata Power |
| Adani Power Limited |
| Duke Energy Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed generators and integrated utilities anchor procurement discipline across the thermal power sector, translating fuel cost volatility into pass-through tariff structures while concentrating equipment purchasing power among state enterprises in China and India. This ownership pattern compresses margin pools for independent OEMs and forces pricing transparency through multi-source tendering.
Pricing Analysis
Input-cost pass-through mechanisms dominate thermal power contracting, with fuel-linked escalation clauses in long-term power purchase agreements shielding generators from commodity swings while exposing OEMs to raw material volatility. Pricing stratifies across supercritical certification tiers, ASME Section I compliance grades, and bundled aftermarket service levels. Cost compression in standard-efficiency gas turbines is intensifying because Chinese captive manufacturers undercut Western OEMs on comparable specifications. Industrial captive generators exhibit highest price sensitivity due to direct competition with grid tariffs, while regulated utilities absorb premiums for dispatch flexibility.
Supply Chain Analysis
Direct-to-utility channels handle baseload procurement for integrated generators, bypassing distributor markups on turbine and boiler packages. Manufacturing concentrates in China, Germany, and Japan for precision castings and high-temperature alloys. Supply chains draw from nickel superalloy foundries, precision forging operations, and specialized welding certification centers. Single-source vulnerability persists in large-frame gas turbine rotor forging capacity. Distribution runs through EPC consortiums for turnkey projects and direct OEM relationships for component upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermal power market compounds steadily as grid stabilization requirements against renewable intermittency sustain baseload procurement across industrializing economies.
For Market Incumbents: Lock in service contract renewals at existing coal and gas fleets before carbon capture retrofit mandates accelerate, and anchor regional market position through integrated fuel procurement partnerships that emerging hydrogen-ready turbine specialists cannot replicate. Vertical integration into carbon capture engineering capabilities protects against regulatory-driven asset stranding. For New Entrants and Emerging Players: Industrial cogeneration operators in European chemical corridors represent an underserved buyer archetype seeking heat-power optimization beyond standard utility offerings. White-space exists in hydrogen-blend retrofit combustion systems for mid-life combined cycle fleets, and in digital twin diagnostics for legacy control system migrations. A go-to-market angle targeting pulp and paper sector waste heat recovery projects bypasses saturated utility procurement channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional EPC contractors holding captive welding certifications and pressure vessel fabrication licenses. Long-term viability frames around technology transition optionality rather than pure-play fossil exposure. Acquisition targets should demonstrate carbon capture integration capabilities or hydrogen-ready engineering pipelines. The signal to watch is FERC capacity market redesign timing, which determines dispatch revenue stability for gas turbine assets.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Retrofit | Positions gas fleets for METI and EU hydrogen blending mandates without greenfield capital. |
| Carbon Capture Integration Partnership | Combines EPC construction expertise with sequestration site geology for EPA compliance. |
| Digital Twin Service Contract | Captures recurring revenue from Duke Energy and NTPC predictive maintenance programs. |
| Supercritical Welding Certification Acquisition | Secures scarce ASME-qualified labor pools for Indian CEA-mandated boiler upgrades. |
| Combined Cycle Cogeneration Expansion | Targets North Rhine-Westphalia chemical sector process steam under EU Green Deal incentives. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining utility planning officer discussions, EPC contractor project assessments, and grid operator dispatch data with secondary validation from EIA generation statistics, IEA power sector reports, FERC interconnection filings, and CEA emission compliance records. Bottom-up capacity addition tracking and top-down fuel consumption analysis provided cross-verification.
Comparable-period anchoring tied projection assumptions to historical capacity deployment patterns across supercritical coal, combined cycle gas, and cogeneration segments. The modeling period incorporated fuel source, generation capacity tier, regulatory framework, and regional grid type as segmentation dimensions. CAGRs were derived from installed base turnover rates and replacement cycle analysis, with EPA Section 111 compliance deadlines and Indian renewable integration targets serving as demand-side inflection inputs.
Underlying measurement precision varies by segment; combined cycle gas turbine data carries tighter precision than emerging hydrogen-ready retrofit categories due to established reporting protocols. Forecasts reflect assumptions about carbon pricing trajectory and renewable storage cost curves that could shift with technology breakthroughs or policy reversals. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Iraq Power EPC Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
India Gensets Market
Power Generation
Residential Solar Generator Market
Power Generation
Canada Power EPC Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Global Power Generation Market
Power Generation
Japan Thermal Power Plant Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
East Africa Power Market
Power Generation
India Gas Generator Market
Power Generation
India Thermal Power Plant Market
Power Generation
Industrial Solar Generator Market
Power Generation
South America Thermal Power Market
Power Generation
Gas Gensets Market