
 North America Automated Demand Response Management System Market | 2026-2036
North America Automated Demand Response Management System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automated Demand Response Management System Market Analytics
Market Context
The United States is fragmenting across competing ADRMS architectures as utilities deploy divergent communication protocols and control standards. Siemens AG leverages its building automation heritage to anchor enterprise-scale deployments across commercial portfolios. Honeywell International Inc. sustains channel dominance through its established distributor relationships with mechanical contractors. Johnson Controls International differentiates via deep integration with its HVAC equipment installed base, creating sticky retrofit opportunities.
Technical Definition and Structural Segments
Automated Demand Response Management Systems are software-controlled platforms that receive grid signals through OpenADR or proprietary utility APIs and execute pre-programmed load reduction sequences across building systems without manual intervention. These systems modulate HVAC setpoints, lighting levels, and industrial process loads to balance grid frequency while preserving occupant comfort and operational continuity. Software solutions command the dominant margin pool as recurring SaaS licenses replace perpetual on-premise deployments. Cloud-Based offerings represent the fastest-expanding delivery mode, though Integrated Solutions retain structural importance for industrial facilities requiring on-site control redundancy. IoT-enabled hardware endpoints constitute a mature, cost-pressured segment where commoditization limits pricing power.
Regulatory Framework
FERC Order 2222 and the US Inflation Reduction Act reshape competitive access by enabling distributed energy resources to participate in wholesale markets, directly expanding ADRMS addressable demand. California Title 24 building codes and Texas PUC interconnection standards mandate automated response capabilities for new commercial construction above specified load thresholds. Stakeholders must monitor evolving state-level grid modernization roadmaps and utility rate design proceedings to anticipate where automated demand response transitions from incentive-driven adoption to compliance-mandated installation.
Market Dynamics
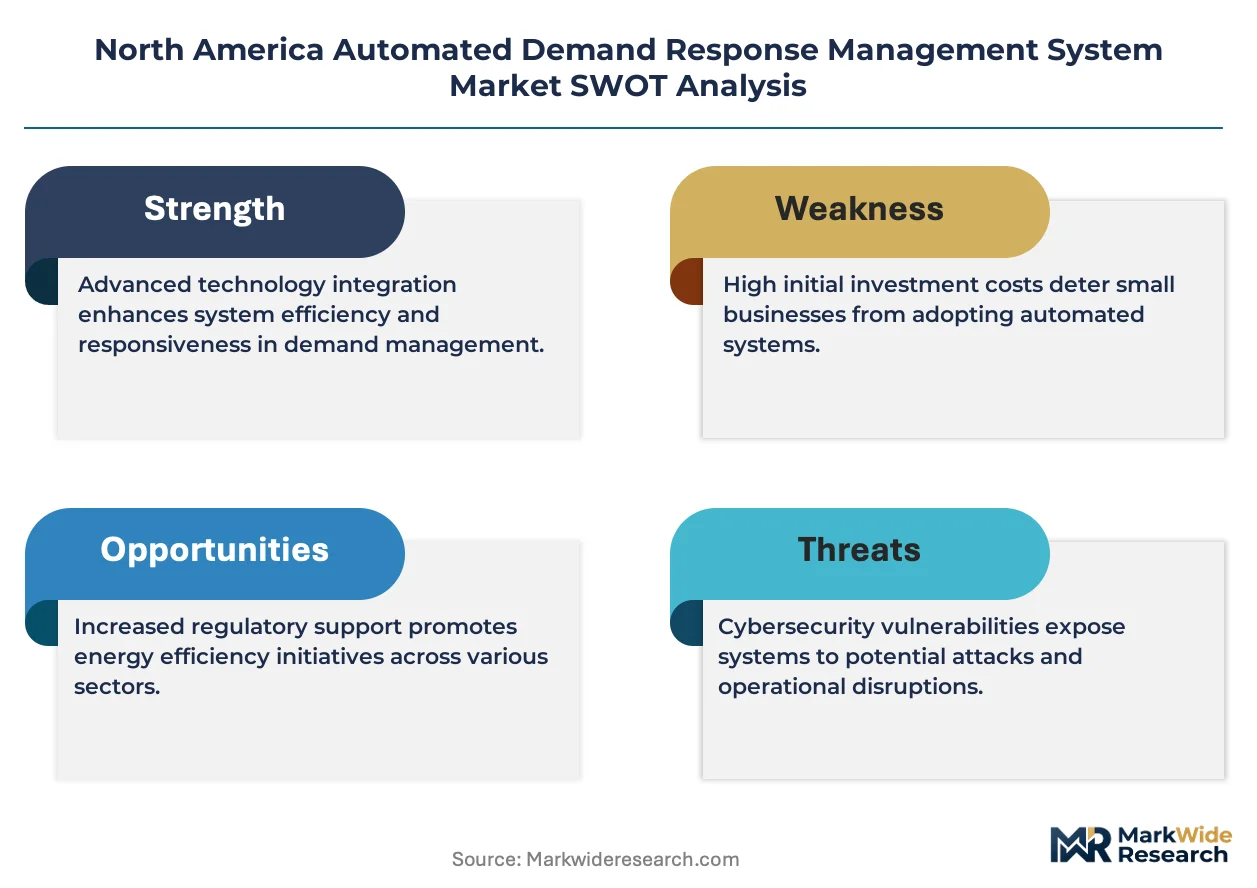
The US Inflation Reduction Act and California Title 24 mandates are compressing adoption timelines, forcing building operators to select automated demand response platforms before technical standards fully stabilize. This regulatory pressure is fragmenting procurement across competing utility protocols.
Growth Catalysts
- California Title 24 mandates:Automated response capabilities are now required for new commercial construction above 200 kW load thresholds, creating immediate compliance-driven demand.
- Texas grid instability:ERCOT's emergency pricing events and interconnection standards are accelerating automated load curtailment investments across industrial facilities.
- OpenADR 2.0b protocol:Standardized utility communication interfaces are reducing integration friction and expanding addressable building stock for automated response platforms.
Market Restraints
- Silicon supply concentration:IoT-enabled control hardware remains exposed to Taiwan semiconductor foundry bottlenecks, constraining endpoint deployment velocity.
- Utility protocol fragmentation:Divergent proprietary APIs across ISO-NE, CAISO, and ERCOT territories force redundant software development and raise integration costs.
- Legacy building stock inertia:Pre-2010 HVAC systems lack digital control interfaces, limiting retrofit penetration in older commercial portfolios without full equipment replacement.
Strategic Opportunities
- Texas industrial microgrids:Petrochemical and data center clusters in the Permian Basin and Dallas-Fort Worth corridor remain underpenetrated for automated demand response aggregation.
- FERC Order 2222 implementation:Wholesale market access for distributed energy resources creates new revenue streams for building-scale automated response providers.
- Edge-AI convergence:On-premise machine learning inference combined with cloud orchestration enables sub-second load modulation without latency-dependent internet connectivity.
Industry Challenges
- Cybersecurity certification timelines:NERC CIP compliance for grid-connected building systems extends deployment schedules by 8-14 months.
- Controls engineering talent scarcity:Shortage of technicians proficient in both building automation and utility market operations constrains implementation capacity.
- Multi-vendor integration complexity:Pre-existing Siemens, Honeywell, and Johnson Controls installations require custom middleware development for unified automated response orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automated Demand Response Management System Market |
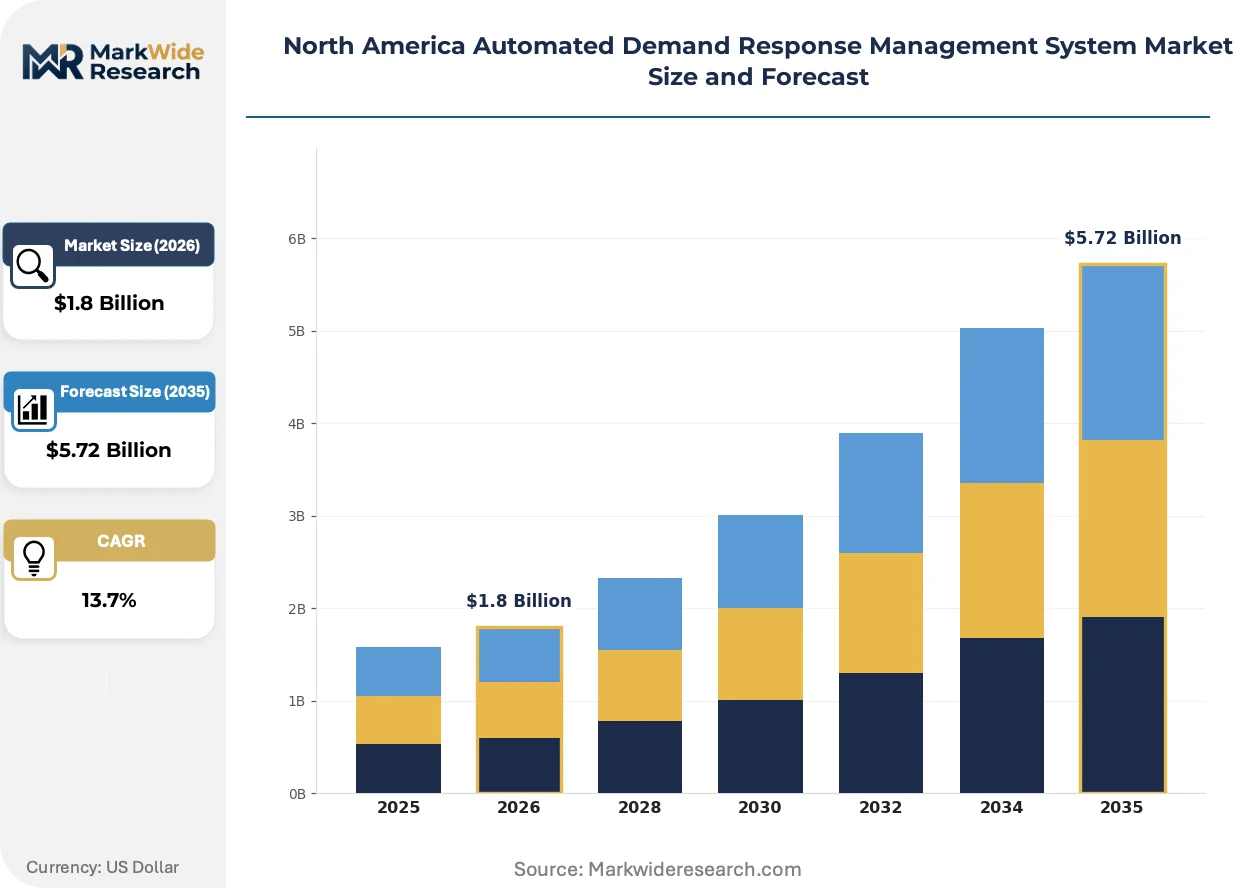
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Integrated Solutions, Cloud-Based End User: Utilities, Commercial Buildings, Industrial Facilities, Residential Consumers Technology: IoT, AI, Machine Learning, Data Analytics Solution: Real-Time Monitoring, Load Forecasting, Energy Management, Reporting |
| Companies Covered | ABB Ltd, Siemens AG, Honeywell International Inc., Enel SpA, General Electric Company, Eaton Corporation, Johnson Controls International, Itron Inc., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automated Demand Response Management System Market Evolving Landscape
Cloud-native software architectures are displacing on-premise demand response platforms, compressing deployment timelines and enabling continuous algorithmic refinement without hardware replacement cycles.
Digital twin technology is digitizing building thermal mass and occupancy patterns into predictive load models. Large commercial portfolios in California are adopting these virtual replicas to pre-validate curtailment sequences. This capability is digitizing the traditional manual commissioning process and compressing payback periods for automated response investments.
The US Inflation Reduction Act's 179D tax deduction expansion is reshaping capital allocation toward automated demand response retrofits. Commercial real estate investment trusts are now bundling ADRMS installations with HVAC upgrades to maximize incentive capture. Industrial facilities in Texas are responding fastest, driven by exposure to real-time pricing volatility.
Building operators are consolidating vendor relationships to reduce interoperability friction. Single-source procurement of automated response software, controls hardware, and ongoing optimization services is displacing multi-vendor assemblies. This concentration is most pronounced in Class A office buildings across Chicago and Toronto, where facilities managers prioritize operational simplicity over component-level cost minimization.
North America Automated Demand Response Management System Market Segmentation
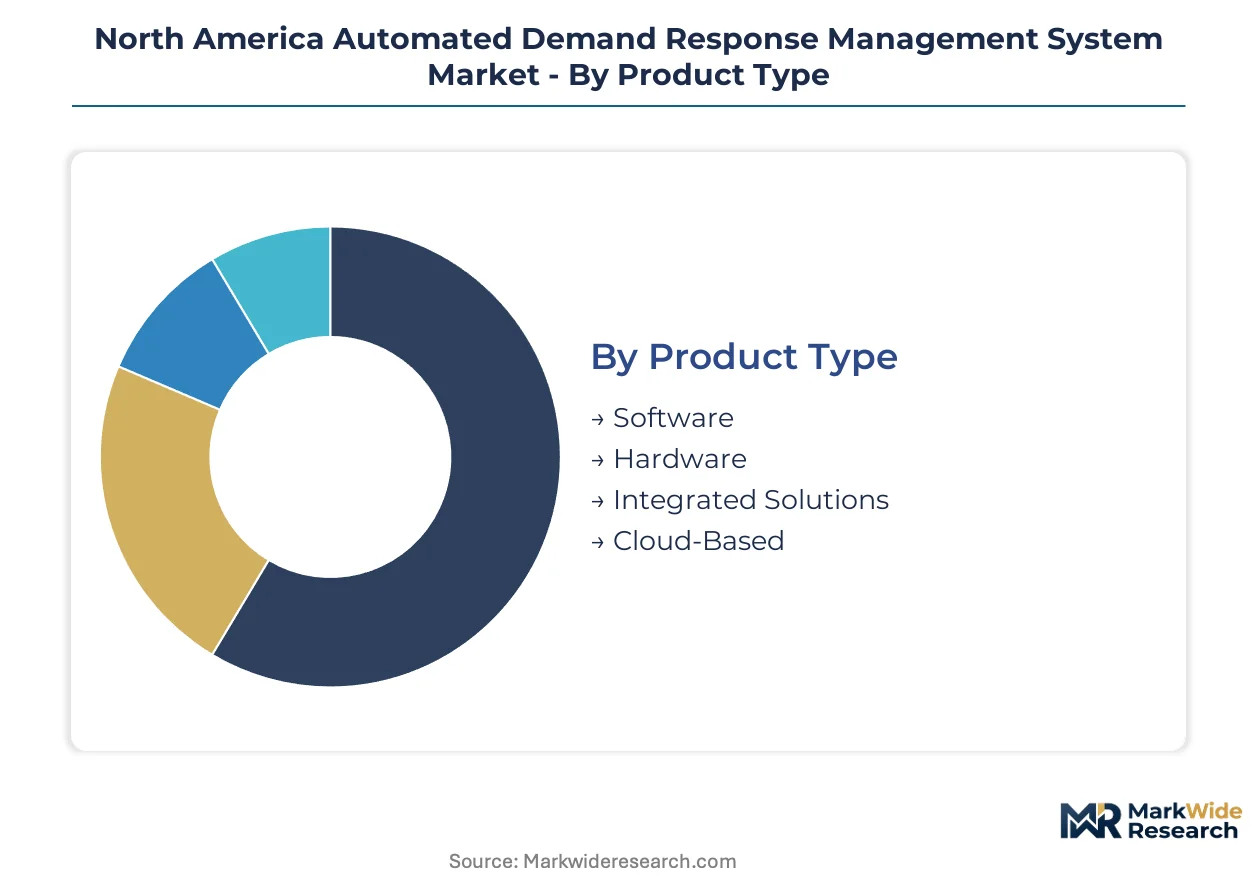
Automated demand response platforms serve divergent operational requirements across software, hardware, and service layers. Segmentation reveals where margin pools concentrate and which technical architectures are displacing legacy deployment models.
Product Type:
Deployment modes span from perpetual on-premise licenses to recurring cloud subscriptions, with integration complexity driving customer selection across the use-case spectrum.
- Software:SaaS platforms orchestrate load curtailment sequences through OpenADR interfaces and utility APIs. Demand concentrates among commercial building operators in California seeking compliance with Title 24 mandates without capital-intensive hardware retrofits.
- Hardware:IoT-enabled controllers and smart thermostats execute physical load modulation across HVAC and lighting circuits. Texas industrial facilities facing ERCOT emergency pricing events are expanding procurement of ruggedized edge devices for sub-second response latency.
- Integrated Solutions:Bundled software-hardware-service packages reduce vendor fragmentation for multi-site portfolios.
- Cloud-Based:Browser-accessible platforms with continuous algorithm updates are expanding fastest among mid-market commercial buildings lacking dedicated IT infrastructure.
The dominant share belongs to Software, while Cloud-Based offerings are gaining share fastest as building operators prioritize operational simplicity over component-level customization.
End User:
Procurement authority varies sharply across customer types, with regulatory pressure and exposure to real-time pricing volatility determining adoption velocity.
- Utilities:Grid operators deploy ADRMS as aggregation platforms to recruit and orchestrate distributed building loads. CAISO and ERCOT are expanding automated demand response procurement to meet resource adequacy requirements without new thermal generation.
- Commercial Buildings:Class A office and retail portfolios in Chicago and Toronto are consolidating vendor relationships to reduce interoperability friction across multi-site operations.
- Industrial Facilities:Petrochemical and data center clusters require on-site control redundancy for process continuity.
- Residential Consumers:Smart thermostat programs and utility-managed load control remain nascent outside California and Texas pilot territories.
Commercial Buildings command the largest addressable base, though Industrial Facilities are expanding most quickly as exposure to wholesale price spikes accelerates capital allocation.
Technology:
Technical differentiation increasingly depends on data processing location and algorithmic sophistication rather than connectivity alone.
- IoT:Sensor networks and connected endpoints provide the physical layer for automated load modulation. Supply concentration in Taiwan semiconductor foundries constrains deployment velocity for control hardware.
- AI:Predictive models anticipate grid events and pre-position building thermal mass before emergency signals arrive. California portfolios are adopting these capabilities to validate curtailment sequences through digital twin environments.
- Machine Learning:Continuous algorithm refinement improves load forecasting accuracy without manual parameter adjustment.
- Data Analytics:Post-event reporting and performance attribution satisfy utility settlement requirements and regulatory compliance documentation.
IoT retains installed base dominance, while AI is climbing the fastest as edge-AI convergence enables sub-second inference without cloud dependency.
Solution:
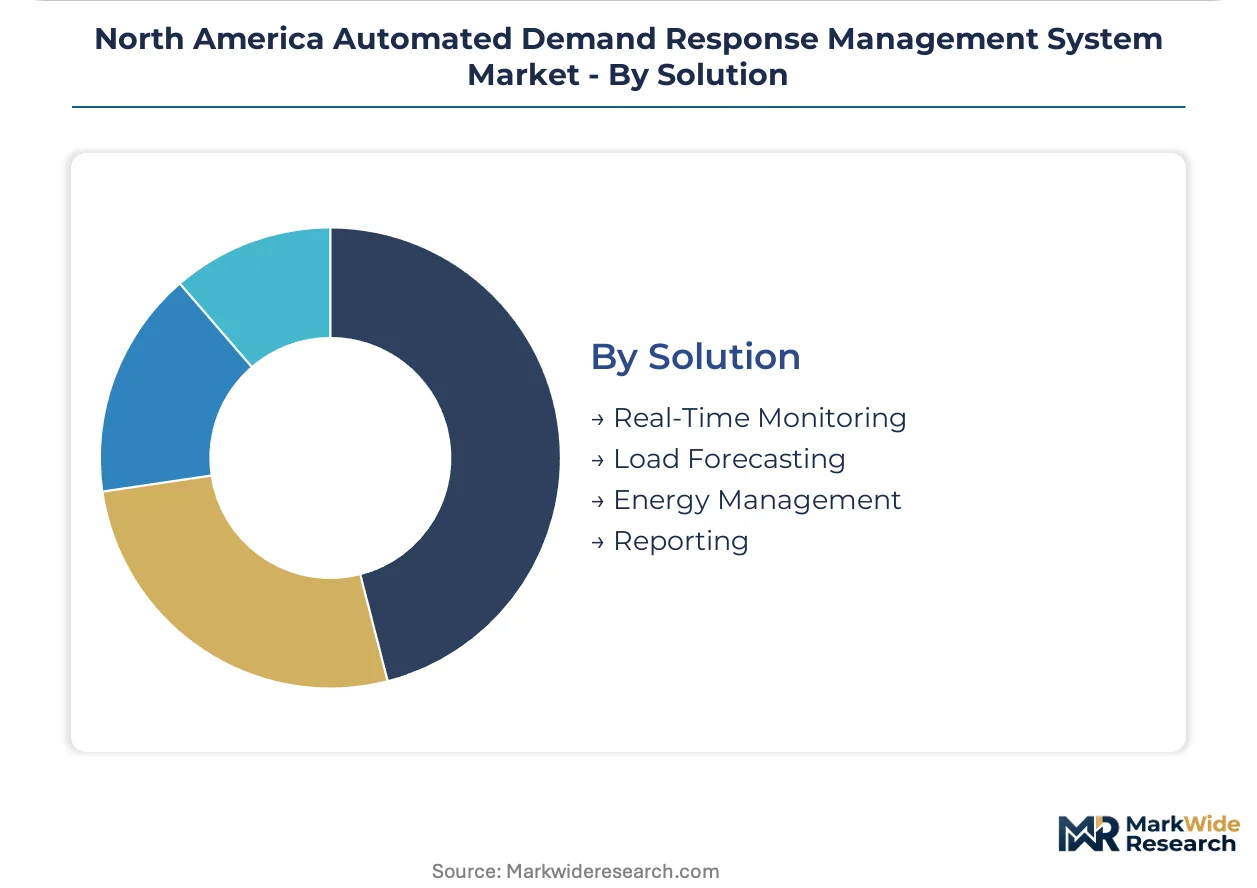
Functional modules align with distinct operational workflows from real-time operations through regulatory documentation.
- Real-Time Monitoring:Dashboards and alert systems track building load status against grid signals and curtailment commitments. Texas industrial operators rely on these capabilities to manage exposure to five-minute pricing intervals.
- Load Forecasting:Predictive algorithms project building demand patterns to pre-validate curtailment feasibility. FERC Order 2222 implementation is expanding wholesale market participation requiring forecast-based bidding.
- Energy Management:Integrated optimization across multiple building systems balances grid responsiveness with occupant comfort.
- Reporting:Automated compliance documentation satisfies California Title 24 verification and utility incentive program settlement.
Energy Management holds structural importance for integrated deployments, while Load Forecasting is expanding most quickly as wholesale market access creates new revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated demand response management system deployment concentrates where grid instability and regulatory mandates intersect. Taiwan semiconductor foundries constrain hardware supply velocity. The United States dominates software innovation and policy-driven procurement.
United States
California and Texas anchor procurement volume through divergent stressors. FERC Order 2222 and the Inflation Reduction Act reshape wholesale market access for distributed building loads. The Permian Basin petrochemical corridor and Dallas-Fort Worth data center clusters are expanding automated load curtailment investments to manage ERCOT emergency pricing exposure.
Canada
Ontario and Quebec utilities are piloting automated demand response to balance hydroelectric generation variability. The Canadian Energy Regulator and provincial energy boards are reviewing grid modernization frameworks to enable building-scale participation in wholesale markets. Toronto's Class A office portfolio is consolidating vendor relationships to reduce multi-site operational complexity.
Mexico
Industrial facilities in Nuevo León and Mexico City are adopting automated response platforms to manage exposure to time-of-use tariffs and grid congestion. The Energy Regulatory Commission is evaluating demand response mechanisms for industrial load participation. Manufacturing clusters near Monterrey are prioritizing sub-second load modulation to protect process continuity.
North America Automated Demand Response Management System Market Competitive Landscape
Building automation incumbents and industrial conglomerates split the market through divergent channel strategies. Siemens AG leverages enterprise-scale building automation heritage across commercial portfolios. Honeywell International Inc. sustains distributor relationships with mechanical contractors. Johnson Controls International differentiates via HVAC equipment integration. Competitive moves concentrate on strategic partnerships with utilities and portfolio diversification into edge-AI capabilities.
Within the building automation archetype, Siemens AG, Honeywell International Inc., and Johnson Controls International exemplify three distinct positioning strategies. Siemens AG represents the European engineering conglomerate model with enterprise software depth. Honeywell International Inc. occupies the North American diversified technology position with established contractor channels. Johnson Controls International anchors the equipment-integrated approach, creating retrofit stickiness through captive HVAC installed bases. These three collectively illustrate how heritage in adjacent building systems shapes automated demand response market entry.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Honeywell International Inc. |
| Enel SpA |
| General Electric Company |
| Eaton Corporation |
| Johnson Controls International |
| Itron Inc. |
| Schneider Electric SE |
| Others |
Value Network & Pricing Analysis
Taiwan semiconductor foundry capacity constraints in Hsinchu and Tainan Science Parks directly compress pricing power for IoT-enabled control hardware, while software margins expand through recurring SaaS subscriptions that decouple revenue from silicon availability.
Pricing Analysis
FERC Order 2222 and state-level mandates dictate the pricing tier structure across deployment models. SaaS platforms command premium positioning through compliance bundling, while perpetual licenses face commoditization. Price differentiation centers on OpenADR certification tier and utility integration depth. Cost compression in hardware endpoints intensifies because Taiwan foundry bottlenecks constrain controller supply velocity. Mid-market commercial buildings exhibit highest price sensitivity, whereas Texas industrial facilities prioritize sub-second latency over unit economics.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment limit foundry capacity expansion across Taiwan, South Korea, and the United States. IoT controllers draw from 28nm and 40nm process nodes, NOR flash memory, and precision analog components. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing capacity allocation. Distribution runs through building automation distributors, mechanical contractor networks, and direct enterprise sales for integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated demand response platforms represent a service-attach opportunity where recurring optimization and compliance monitoring revenues expand faster than hardware replacement cycles, creating durable customer lifetime value.
For Market Incumbents: Insulate installed base relationships through captive HVAC equipment integration and edge-AI capability deployment. Siemens AG and Johnson Controls International face emerging cloud-native entrants attacking mid-market commercial buildings with API-first architectures. Channel control through mechanical contractor exclusivity agreements and backward integration into semiconductor inventory buffers defensive positioning. For New Entrants and Emerging Players: Pursue Texas industrial microgrid aggregation and California Title 24 compliance-as-a-service white spaces. The Permian Basin petrochemical corridor remains underpenetrated for automated demand response orchestration. Utility partnership co-development models accelerate trust acquisition faster than direct sales approaches. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-AI software specialists with OpenADR 2.0b certification and utility API integration depth. Long-term viability hinges on FERC Order 2222 implementation velocity and wholesale market participation expansion. The signal to watch is NERC CIP compliance certification timelines as a capacity constraint indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Capability Acquisition | Sub-second load modulation without cloud dependency addresses Texas ERCOT emergency pricing exposure. |
| OpenADR Certification Investment | Standardized utility interfaces reduce California Title 24 compliance friction and integration costs. |
| Utility Partnership Expansion | CAISO and ERCOT aggregation contracts create recurring revenue visibility and market access barriers. |
| Semiconductor Supply Agreement | Captive controller inventory buffers Taiwan foundry allocation risk for industrial deployment timelines. |
| Cybersecurity Compliance Program | NERC CIP certification accelerates grid interconnection approvals and extends competitive moats. |
Research Methodology
Desk research of FERC interconnection filings, utility rate case proceedings, and OpenADR protocol documentation preceded structured interviews with building automation system integrators, utility demand response program managers, commercial real estate portfolio directors, and industrial facilities engineers. Secondary validation drew from EIA electricity market data, state public utility commission dockets, and equipment manufacturer SEC disclosures. Bottom-up deployment estimates triangulated against top-down utility procurement targets.
The analytical framework held regulatory implementation timelines and semiconductor supply constraints as fixed boundary conditions across the projection horizon. Segmentation modeling spanned deployment mode, end-user vertical, technology architecture, and regional regulatory cluster. CAGRs derived from utility capital expenditure trajectories and building code adoption curves. Forecast inputs incorporated ERCOT emergency pricing event frequency and California Title 24 compliance deadlines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers entering building automation would shift outcomes. Material shifts in Taiwan semiconductor export restrictions or FERC Order 2222 implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Microgrid Controller Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
Europe Microgrid Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
Smart Grid Data Management Market