
 North America Micro CHP Market | 2026-2036
North America Micro CHP Market Size, Share, and Industry Trends Forecast 2026-2036
North America Micro CHP Market Analysis
Modular system bundling is pivoting how buyers evaluate Micro CHP investments across North America. General Electric leverages its turbine engineering heritage to offer integrated thermal-electric packages that reduce installation complexity. Yanmar anchors its position through compact gas engine designs purpose-built for commercial building footprints. Siemens competes with control-system intelligence that optimizes heat-to-power ratios in real time.
Micro combined heat and power refers to distributed generation systems typically rated below 50 kWe that simultaneously produce usable thermal energy and electricity from a single fuel source, achieving total system efficiencies of 80-90% through waste heat recovery. Fuel cell segments lead value capture due to superior electrical efficiency and near-zero local emissions profiles, while gas engine configurations dominate installed volume across existing commercial boiler retrofits. Residential end users represent the fastest-growing addressable pool as net-metering policies and time-of-use rate structures improve project economics for single-family and small multi-family dwellings.
The US Environmental Protection Agency and Department of Energy shape equipment certification pathways through CHP-specific emissions benchmarks and technical assistance programs, while state-level public utility commissions determine interconnection standards that directly affect deployment timelines. Canadian provincial regulators, notably in Ontario and British Columbia, maintain parallel incentive structures tied to carbon intensity reductions. Stakeholders must monitor evolving interconnection queue reforms and building electrification mandates that could either accelerate or constrain Micro CHP positioning against heat pump alternatives.
Market Dynamics
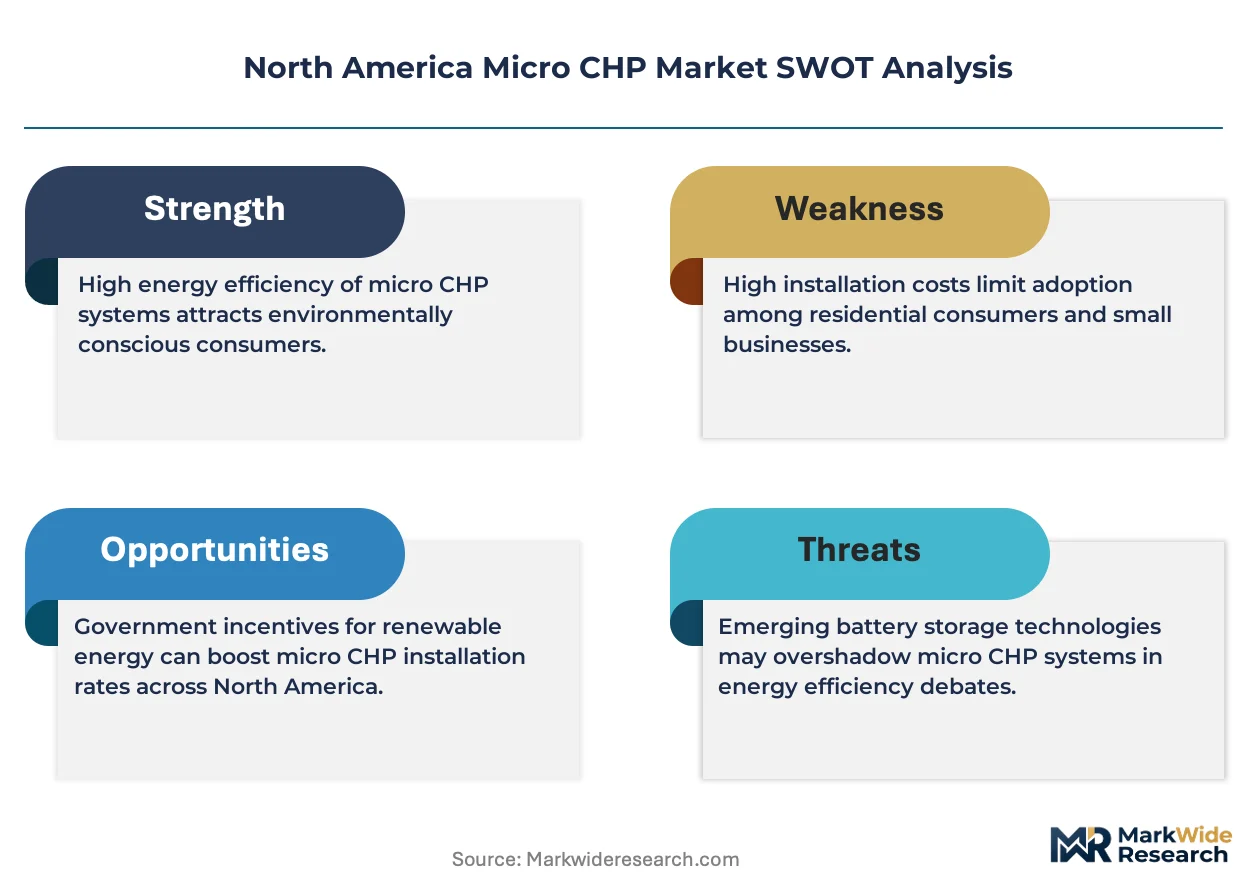
The Inflation Reduction Act's clean energy tax credits are compressing payback periods for distributed generation assets, fundamentally altering how commercial property owners evaluate thermal-electric investments against conventional boiler retrofits.
Growth Catalysts
- New York State Clean Heat Program:Tiered incentives for fuel cell installations in multi-family buildings accelerate developer adoption across the Hudson Valley and Long Island corridors.
- Grid reliability deterioration:Northeast utilities face interconnection queue delays exceeding 18 months, driving property managers toward on-site generation for resilience planning.
- Time-of-use rate restructuring:California and Massachusetts utilities now penalize peak demand charges heavily, improving spark spread economics for sub-50 kWe systems.
Market Restraints
- Platinum group metal cost volatility:Fuel cell stack manufacturing depends on iridium and platinum catalysts subject to South African supply concentration risk.
- Interconnection standard fragmentation:State public utility commissions maintain non-uniform technical requirements that extend commissioning timelines by 4-6 months.
- Heat pump substitution threat:Cold-climate electric heat pumps achieving COP above 3.0 in sub-freezing conditions erode the thermal efficiency advantage of gas-based Micro CHP.
Strategic Opportunities
- Canadian provincial carbon pricing:British Columbia's escalating carbon tax trajectory creates favorable economics for natural gas-fired systems with 80%+ total efficiency.
- Data center thermal loads:Edge computing facilities in Texas and Arizona present novel co-location models where waste heat drives absorption cooling.
- Virtual power plant aggregation:FERC Order 2222 compliance by regional transmission organizations enables capacity revenue stacking for behind-the-meter assets.
Industry Challenges
- Certification timeline compression:EPA CHP Partnership technical assistance programs face backlogs that delay project eligibility verification for 90-120 days.
- Controls integration complexity:Building management system interoperability with third-party Micro CHP units requires custom BACnet programming that strains installer capacity.
- Service technician scarcity:Fuel cell stack replacement and reformer maintenance demand electrochemistry expertise absent from conventional HVAC trade pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Micro CHP Market |
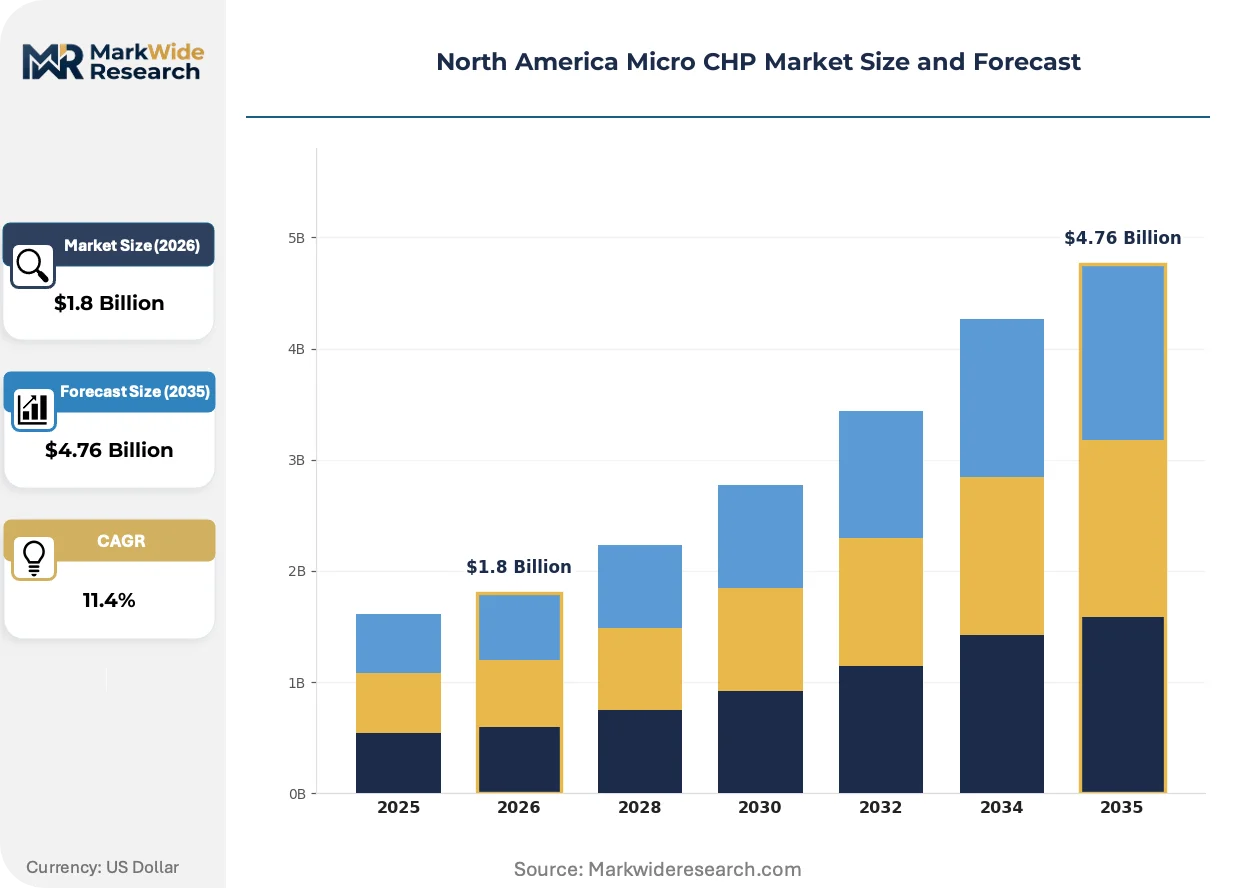
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Cell, Gas Engine, Stirling Engine, Biomass Power Rating: 1 kW, 2 kW, 5 kW, 10 kW End User: Residential, Commercial, Industrial, Institutional Installation: Onsite, Offsite, Retrofit, New Build |
| Companies Covered | 2G Energy Inc., General Electric, Yanmar, Viessmann, BDR Thermea, Siemens, AISIN SEIKI, Marathon Engine Systems, Aegis Energy Services, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Micro CHP Market Emerging Trajectories
Solid oxide fuel cell technology is integrating with building thermal systems in ways that compress the traditional separation between power generation and HVAC infrastructure. Three developments dominate current investment patterns.
Solid oxide fuel cell stacks operating at 700-800°C are integrating with absorption chillers and desiccant dehumidification systems in commercial buildings across California and Massachusetts. Hospital and university campuses lead adoption, deploying 25-50 kWe units that displace both grid electricity and natural gas-fired cooling equipment. This convergence is integrating thermal and electric load management into unified asset control platforms that optimize dispatch against real-time utility rates.
The Inflation Reduction Act's investment tax credit adders for domestic content are reshaping equipment sourcing strategies. Systems qualifying for the full 30% credit plus 10% domestic assembly bonus achieve payback periods under six years in high-utility-rate zones. Northeast multi-family developers and California hospitality operators are restructuring procurement specifications to capture these incentives, prioritizing vendors with North American manufacturing footprints.
Property owners are consolidating vendor relationships around turnkey energy-as-a-service contracts that bundle equipment, maintenance, and fuel procurement. Third-party ownership structures displace traditional capital purchase models for small commercial buildings with limited balance sheet capacity. Massachusetts and New York state incentive programs explicitly favor this arrangement, requiring service agreements of 10+ years for eligibility verification.
North America Micro CHP Market Segmentation
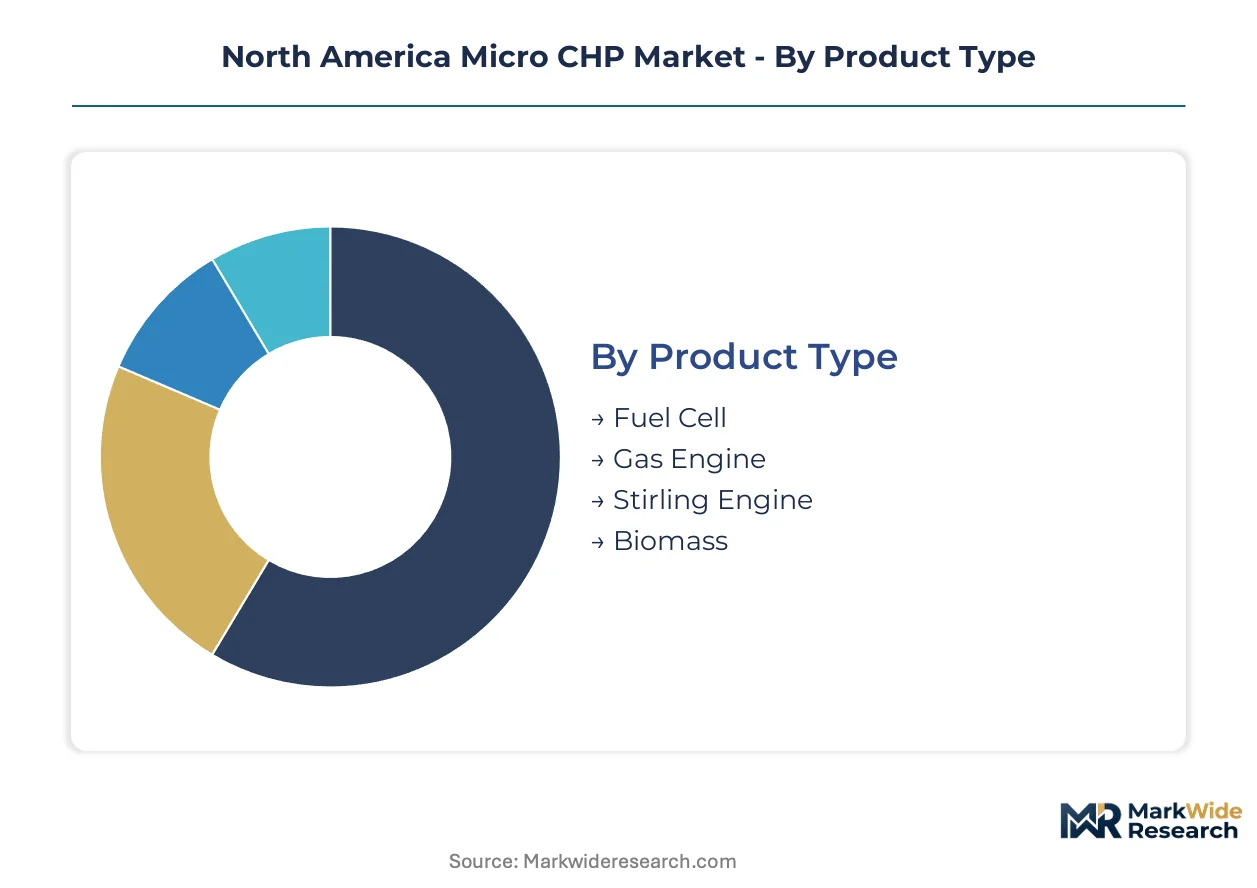
Micro CHP deployment patterns diverge sharply across technology platforms and building types. Understanding these splits clarifies where capital concentrates and which customer segments drive equipment specification trends.
Product Type:
Fuel cell systems command premium positioning while gas engines anchor volume deployment across the region.
- Fuel Cell:Solid oxide and proton exchange membrane stacks achieve 40-60% electrical efficiency through electrochemical conversion without combustion. Northeast multi-family developers in New York and Massachusetts specify these for net-zero building certifications and resilience mandates. Platinum group metal catalyst costs create supply chain exposure to South African mining concentration.
- Gas Engine:Reciprocating internal combustion configurations leverage mature automotive and industrial engine supply chains for sub-50 kWe outputs. Commercial boiler retrofits across existing building stock in California and Texas favor this proven technology for spark spread economics. Maintenance intervals align with conventional HVAC service schedules.
- Stirling Engine:External combustion architecture tolerates varied fuel quality but suffers from lower power density. Niche applications in remote Canadian indigenous communities exploit multi-fuel flexibility.
- Biomass:Wood pellet and agricultural residue gasification systems target rural properties with captive fuel supply. Vermont and Maine state incentive programs specifically carve out eligibility for these configurations.
Mature deployment sits with Gas Engine. Newer deployment is concentrated in Fuel Cell.
Power Rating:
System sizing tracks building thermal load profiles rather than electric demand peaks, inverting conventional generator specification logic.
- 1 kW:Single-family residential units in Massachusetts and New York net-metering territories match this output to baseload electric consumption. Compact footprints enable closet or utility room installation without structural modification.
- 2 kW:Small multi-family buildings and bed-and-breakfast hospitality operations in California's time-of-use rate zones size here for optimal spark spread capture. The Inflation Reduction Act's 30% investment tax credit compresses payback periods below seven years at this scale.
- 5 kW:Mid-size commercial buildings and small institutional facilities cluster demand here. EPA CHP Partnership technical assistance programs prioritize this segment for emissions verification protocols.
- 10 kW:Hospital microgrids and university campus thermal plants deploy these for combined absorption cooling integration. FERC Order 2222 aggregation opportunities favor this capacity tier for wholesale market participation.
Volume concentrates at 2 kW. Margin expansion is steepest at 10 kW.
End User:
Customer sophistication varies dramatically across building ownership structures and energy procurement expertise.
- Residential:Single-family and small multi-family dwellings represent the steepest expansion trajectory as net-metering policies and time-of-use rate structures improve project economics. California and Massachusetts lead state incentive design for this segment.
- Commercial:Hotels, restaurants, and small office buildings exploit thermal-electric load coincidence for maximum efficiency capture. Third-party energy-as-a-service ownership structures dominate here due to limited balance sheet capacity.
- Industrial:Light manufacturing and food processing facilities with continuous thermal demand profile match Micro CHP operating characteristics. Texas and Arizona edge computing co-location models present novel waste heat absorption cooling applications.
- Institutional:Hospital and university campuses in California and Massachusetts lead adoption of 25-50 kWe solid oxide fuel cell units. Unified asset control platforms optimize dispatch against real-time utility rates for these mission-critical loads.
Procurement expertise is deepest in Institutional. Decision velocity is fastest in Commercial.
Installation:
Project delivery mode shapes equipment selection, financing structure, and regulatory pathway complexity.
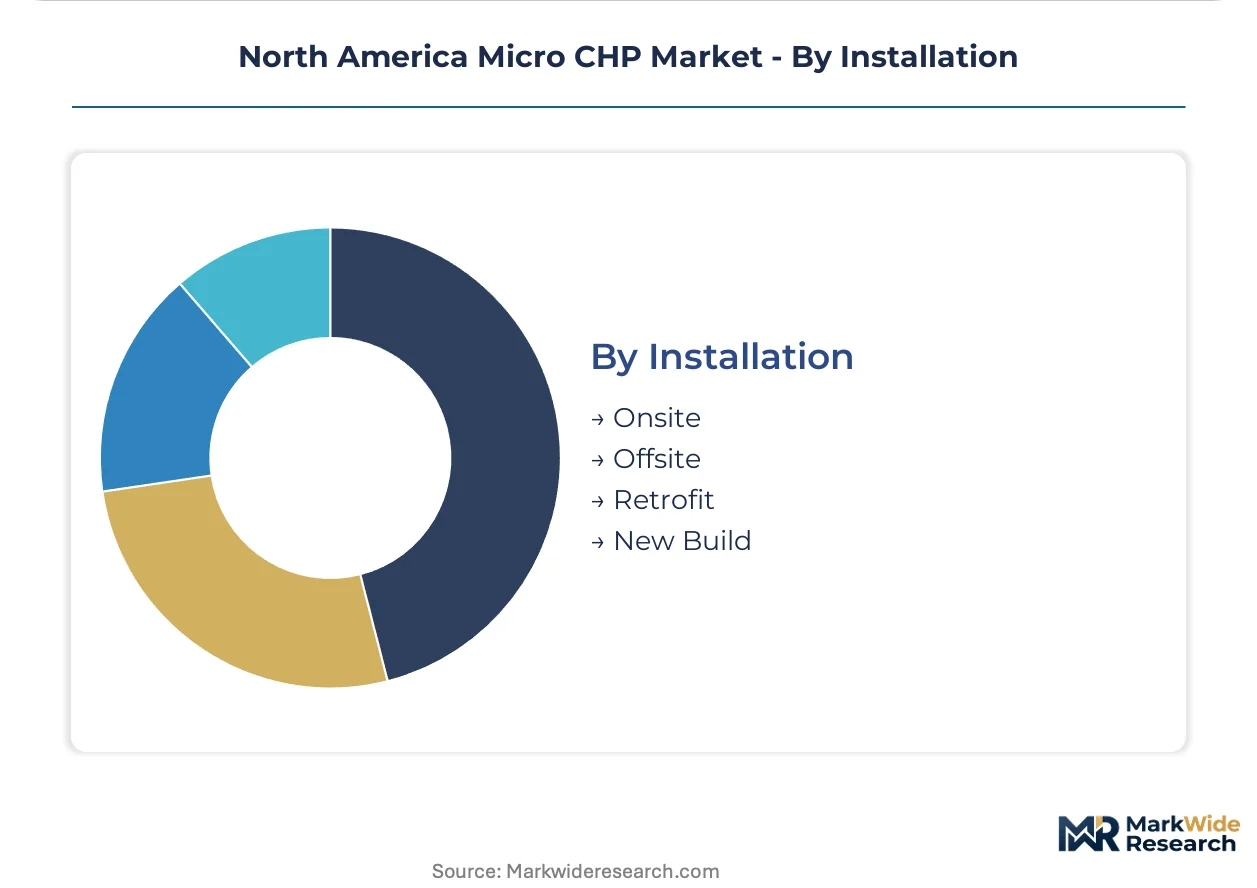
- Onsite:Behind-the-meter generation with thermal distribution through existing building infrastructure dominates current deployment. Interconnection queue delays exceeding 18 months in Northeast utilities accelerate this preference for resilience planning.
- Offsite:District energy and campus-scale thermal networks enable shared Micro CHP assets serving multiple buildings. Canadian provincial carbon pricing in British Columbia favors this model for natural gas-fired systems with 80%+ total efficiency.
- Retrofit:Existing commercial boiler replacement captures the majority of gas engine volume. Custom BACnet programming for building management system interoperability strains installer capacity and extends commissioning timelines.
- New Build:Net-zero building mandates in California and Massachusetts embed Micro CHP specification into construction documentation. Domestic content adders under the Inflation Reduction Act reshape procurement specifications toward North American manufacturing footprints.
Retrofit dominates current volume. New Build is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German and Japanese manufacturing centers while consumption clusters in U.S. coastal states and Canadian provinces with aggressive carbon pricing regimes. This geographic split shapes equipment sourcing strategies and incentive program design across the continent.
United States
Multi-family residential developers in New York and Massachusetts specify fuel cell systems for net-zero building certifications. The Inflation Reduction Act's clean energy tax credits compress payback periods below six years in high-utility-rate zones. The Hudson Valley and Long Island corridors anchor Northeast deployment volume.
Canada
British Columbia's escalating carbon tax trajectory creates favorable economics for natural gas-fired systems achieving 80%+ total efficiency. Ontario maintains parallel incentive structures tied to carbon intensity reductions. Provincial regulators in both jurisdictions determine interconnection standards affecting deployment timelines.
Mexico
Industrial facilities in Nuevo León and the Bajío Region evaluate Micro CHP for combined heat and power applications amid electricity tariff volatility. The national utility regulator shapes distributed generation interconnection protocols. Border manufacturing clusters near Texas explore cross-border equipment sourcing.
California
Time-of-use rate restructuring by state utilities penalizes peak demand charges heavily, improving spark spread economics for sub-50 kWe systems. Hospital and university campuses lead adoption of solid oxide fuel cell units with absorption cooling integration. State building electrification mandates create competitive tension with heat pump alternatives.
Texas
Edge computing facilities in Dallas-Fort Worth and Austin present novel co-location models where waste heat drives absorption cooling. ERCOT grid volatility accelerates on-site generation interest for mission-critical loads. Industrial microgrids in the Gulf Coast petrochemical corridor evaluate thermal-electric load coincidence.
North America Micro CHP Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology platforms and customer segments. Tiered market structure separates premium fuel cell integrators from volume gas engine suppliers. Three archetypes dominate: turbine engineering heritage players leveraging thermal-electric packaging, compact engine specialists optimizing commercial footprints, and control-system vendors optimizing real-time dispatch. Competitive moves concentrate on domestic content qualification for tax credit adders and energy-as-a-service contract bundling.
Within the diversified industrial tier, General Electric and Siemens occupy positions that exemplify integrated system approaches, while Yanmar anchors the compact engine specialist archetype. These three companies represent contrasting strategic bets on how buyers evaluate installation complexity, real-time optimization, and maintenance interoperability.
| Leading Market Players |
|---|
| 2G Energy Inc. |
| General Electric |
| Yanmar |
| Viessmann |
| BDR Thermea |
| Siemens |
| AISIN SEIKI |
| Marathon Engine Systems |
| Aegis Energy Services |
| Others |
Supply Flow & Price Mechanics
Fuel cell stack technicians concentrated in South Carolina and Ohio command 35-40% wage premiums over conventional HVAC trades, compressing margins in premium-tier installations while widening the cost spread against gas engine retrofits.
Pricing Analysis
Margin tightening in fuel cell systems reflects platinum group metal cost volatility and extended commissioning timelines. Project-based contracting dominates, with price differentiation driven by EPA CHP Partnership certification tier and domestic content qualification for Inflation Reduction Act adders. Cost-down pressure on gas engine configurations accelerates as automotive supply chain spillover expands parts availability. Commercial multi-family developers exhibit highest price sensitivity, while institutional hospital campuses prioritize resilience premiums over first cost.
Supply Chain Analysis
Refurbishment flows for solid oxide fuel cell stacks create reverse logistics nodes in Massachusetts and California, extending asset life cycles and secondary parts markets. Manufacturing concentrates in Germany, Japan, and South Korea for fuel cell stacks, with gas engine components drawing from US and Mexican automotive supplier networks. Iridium and platinum catalyst sourcing rests on South African mining concentration risk. Distribution runs through specialized HVAC-mechanical contractors with EPA partnership certification, bypassing conventional electrical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Micro CHP market sits in a technology-transition phase as solid oxide fuel cell systems displace legacy gas engine dominance in premium commercial applications.
For Market Incumbents: Lock in service technician pipelines through community college partnerships in New York and Massachusetts, securing electrochemistry-trained labor before fuel cell maintenance demand outstrips supply. Deepen backward integration into domestic fuel cell stack assembly to capture full 10% domestic content adder under Inflation Reduction Act provisions. Heat pump cold-climate performance improvements threaten thermal efficiency advantages in single-family residential segments. For New Entrants and Emerging Players: Launch via energy-as-a-service contracting models targeting Texas edge computing facilities, where waste heat absorption cooling creates novel value propositions absent from conventional HVAC competition. The 2-5 kW commercial retrofit segment in California time-of-use rate zones offers lowest barriers to specification entry. Partner with BACnet controls integrators to overcome building management system interoperability friction that strains incumbent installer capacity. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play fuel cell specialists possessing EPA CHP Partnership pre-certification and established Massachusetts or New York incentive program eligibility, given interconnection queue reform catalysts accelerating behind-the-meter deployment. Long-term viability hinges on 5-10 year service contract attach rates and platinum group metal hedging discipline. Monitor FERC Order 2222 implementation pace by regional transmission organizations as aggregation revenue inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Scale-Up | Captures full 30% IRA credit plus 10% domestic assembly bonus for Northeast multi-family projects. |
| Energy-as-a-Service Platform Launch | Bundles equipment, maintenance, and fuel procurement for balance-sheet-constrained commercial buildings. |
| EPA CHP Partnership Certification Investment | Unlocks technical assistance eligibility and emissions verification protocols for 5-10 kW institutional deployments. |
| Virtual Power Plant Aggregation Partnership | Enables FERC Order 2222 capacity revenue stacking for behind-the-meter assets in ERCOT and PJM territories. |
| Controls Integration Specialist Acquisition | Addresses BACnet programming scarcity that extends commissioning timelines by 4-6 months in retrofit applications. |
Methodological Framework
Multi-period observation of interconnection queue lengths, state incentive program enrollment trajectories, and fuel cell stack shipment patterns anchored the trend analysis, supplemented by interviews with utility distributed generation planners, commercial HVAC contractors, multi-family property developers, EPA CHP Partnership technical staff, and platinum group metals procurement specialists. Secondary validation drew from FERC interconnection filings, EIA distributed generation surveys, state public utility commission dockets, and IRA implementation guidance documents. Bottom-up equipment deployment estimates triangulated against top-down addressable market sizing by building stock and thermal load profiles.
Segment-weighting applied technology platform splits, power rating tiers, end-user building types, and installation mode categories across the projection horizon. CAGRs derived from logistic diffusion modeling of adoption curves, calibrated to historical penetration rates in Massachusetts and California early-adopter markets. Forecast inputs incorporated carbon tax trajectory assumptions for British Columbia and Ontario, plus utility rate restructuring schedules in California and Massachusetts.
Platinum group metal price spikes, interconnection standard fragmentation delays, and cold-climate heat pump performance breakthroughs are the dominant revision risks to deployment assumptions. Practitioners should monitor South African mining labor actions, state public utility commission rulemakings, and heat pump COP announcements at sub-freezing test conditions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Equatorial Guinea Power Market
Power
Temporary Load Bank Rental Market
Power
Global Ancillary Services Power Market
Power
Middle-East and Africa Power Market
Power
Norway Power Market
Power
Distributed Buoyancy Modules Market
Power
Canada Power Market
Power
Portugal Power Market
Power
Electric Arc Furnaces Market
Power
Flue Gas Desulfurization Unit Market
Power
India Power Market
Power
Resonant Power Converters Market
Power
Power Capacitors Market
Power
Angola Power EPC Market
Power
Solar UPS Market
Power
Brazil Power Market