
 East Africa Power Market | 2026-2036
East Africa Power Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Power Market Foresight
Modular generation procurement is decoupling long-term power purchase agreements from traditional bundled transmission commitments across East Africa. Kenya Electricity Generating Company PLC leverages its geothermal portfolio to anchor dispatchable baseload supply in the Kenyan grid. Ethiopian Electric Power sustains the region's largest hydropower export capacity through interconnection lines into Djibouti and Sudan. Tanzania Electric Supply Company Limited competes for industrial offtake by extending rural electrification co-investment structures with mining operators.
East Africa Power encompasses electricity generation, transmission, and distribution infrastructure spanning voltages from 11 kV distribution to 400 kV interstate transmission, serving a combined population exceeding 300 million across seven nations. Hydropower dominates installed capacity but faces structural constraints from prolonged drought cycles affecting reservoir levels across the Nile basin. Solar generation represents the fastest-expanding type segment, with utility-scale photovoltaic plants achieving sub-$0.05/kWh tariffs that undercut diesel peaking alternatives. Smart Grids technology captures concentrated investment as utilities deploy automated metering infrastructure to reduce technical losses exceeding 20% in some distribution networks.
Kenya's Energy Regulatory Authority and Ethiopia's Ethiopian Energy Authority enforce grid codes and licensing frameworks that determine market access for independent power producers. Uganda's Electricity Regulatory Authority mandates domestic content requirements for rural electrification contractors, shaping procurement patterns for construction and equipment supply. Stakeholders must monitor how regional power pool integration advances under the Eastern Africa Power Pool framework and whether cross-border wheeling tariffs unlock multi-country offtake structures.
Market Dynamics
Modular generation procurement is decoupling long-term power purchase agreements from traditional bundled transmission commitments across East Africa. Kenya Electricity Generating Company PLC leverages its geothermal portfolio to anchor dispatchable baseload supply in the Kenyan grid. Ethiopian Electric Power sustains the region's largest hydropower export capacity through interconnection lines into Djibouti and Sudan. Tanzania Electric Supply Company Limited competes for industrial offtake by extending rural electrification co-investment structures with mining operators.
Growth Catalysts
- Feed-in Tariff Reforms:Ethiopia's revised renewable energy pricing framework accelerates utility-scale solar and wind procurement by independent power producers.
- Industrial Captive Solar:Kenyan manufacturing clusters in the Rift Valley corridor are deploying behind-the-meter photovoltaic systems to offset grid reliability volatility.
- Regional Interconnection:Eastern Africa Power Pool infrastructure expansion enables cross-border wheeling and multi-country offtake structures for surplus Ethiopian hydropower.
Market Restraints
- Reservoir Dependency:Hydropower dominance across the Nile basin exposes generation capacity to prolonged drought cycles affecting reservoir levels at Ethiopian and Ugandan facilities.
- Transmission Bottlenecks:Limited 400 kV interstate line capacity constrains power evacuation from remote geothermal and solar hybrid clusters in Kenya's Rift Valley.
- Diesel Peaking Economics:Sub-$0.05/kWh utility solar tariffs undercut thermal alternatives but leave supply gaps during evening demand peaks requiring liquid fuel backup.
Strategic Opportunities
- Smart Grid Infrastructure:Automated metering deployment targets technical loss reduction in distribution networks exceeding 20% in Tanzania and Uganda.
- Mining Electrification:Tanzania's co-investment frameworks with gold and nickel operators create captive demand for remote generation and dedicated transmission.
- Geothermal-Solar Hybrid:Technology convergence at Kenyan sites near existing transmission infrastructure enables firm renewable supply without separate grid extension.
Industry Challenges
- Grid Code Compliance:Kenya's Energy Regulatory Authority and Ethiopia's Ethiopian Energy Authority enforce divergent interconnection standards that complicate multi-country project development.
- Domestic Content Mandates:Uganda's Electricity Regulatory Authority requires local contractor participation in rural electrification, stretching procurement timelines for international equipment suppliers.
- Technical Loss Management:Distribution utilities lack real-time visibility into non-technical losses from unmetered consumption and infrastructure theft.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Power Market |
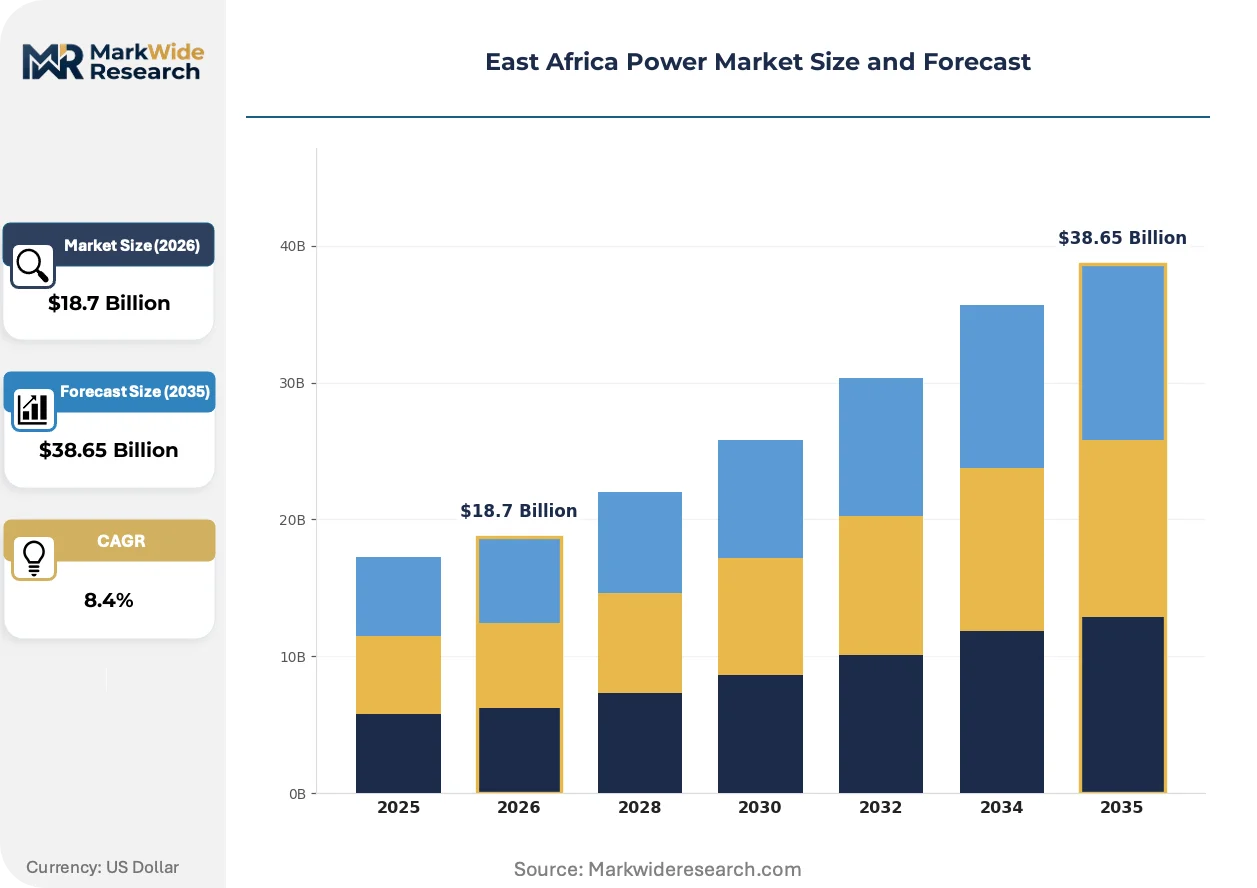
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydropower, Solar, Wind, Biomass Application: Industrial, Residential, Commercial, Agricultural Technology: Smart Grids, Renewable Sources, Energy Storage, Transmission End User: Utilities, Government Agencies, Private Sector, NGOs |
| Companies Covered | Kenya Electricity Generating Company PLC, Kenya Electricity Transmission Company, Kenya Power and Lighting Company PLC, Ethiopian Electric Company, Uganda Electricity Transmission Company Limited, Ethiopian Electric Power, Tanzania Electric Supply Company Limited, Tower Transmission and Distribution Companies, Uganda Electricity Generation Company Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Power Market Shifts & Advancements
Digitalization of grid operations and renewable hybridization are compressing traditional utility business models across East Africa. Battery storage integration is shifting project economics. Regulatory harmonization under regional power pool frameworks is accelerating cross-border investment structures.
Hybrid geothermal-solar generation technology is converging with lithium-ion battery storage at Kenyan Rift Valley sites. Independent power producers are deploying these configurations to provide firm capacity without fossil fuel backup. The technology pairing is enabling 24-hour renewable supply contracts that displace diesel peaking alternatives in industrial offtake negotiations.
Ethiopia's feed-in tariff reforms under the Ethiopian Energy Authority create standardized procurement pathways for utility-scale renewables. The policy framework eliminates bilateral negotiation requirements that previously delayed project financial close. International developers are responding by accelerating pre-development activity in the Afar and Somali regions.
Industrial buyers in Kenya's manufacturing corridor are unbundling energy procurement from distribution service obligations. Large consumers now contract directly with generators for behind-the-meter supply while paying wheeling charges to Kenya Power for backup grid access. This behavioral shift concentrates in the Rift Valley where transmission infrastructure density supports dual-connection arrangements.
East Africa Power Market Segmentation
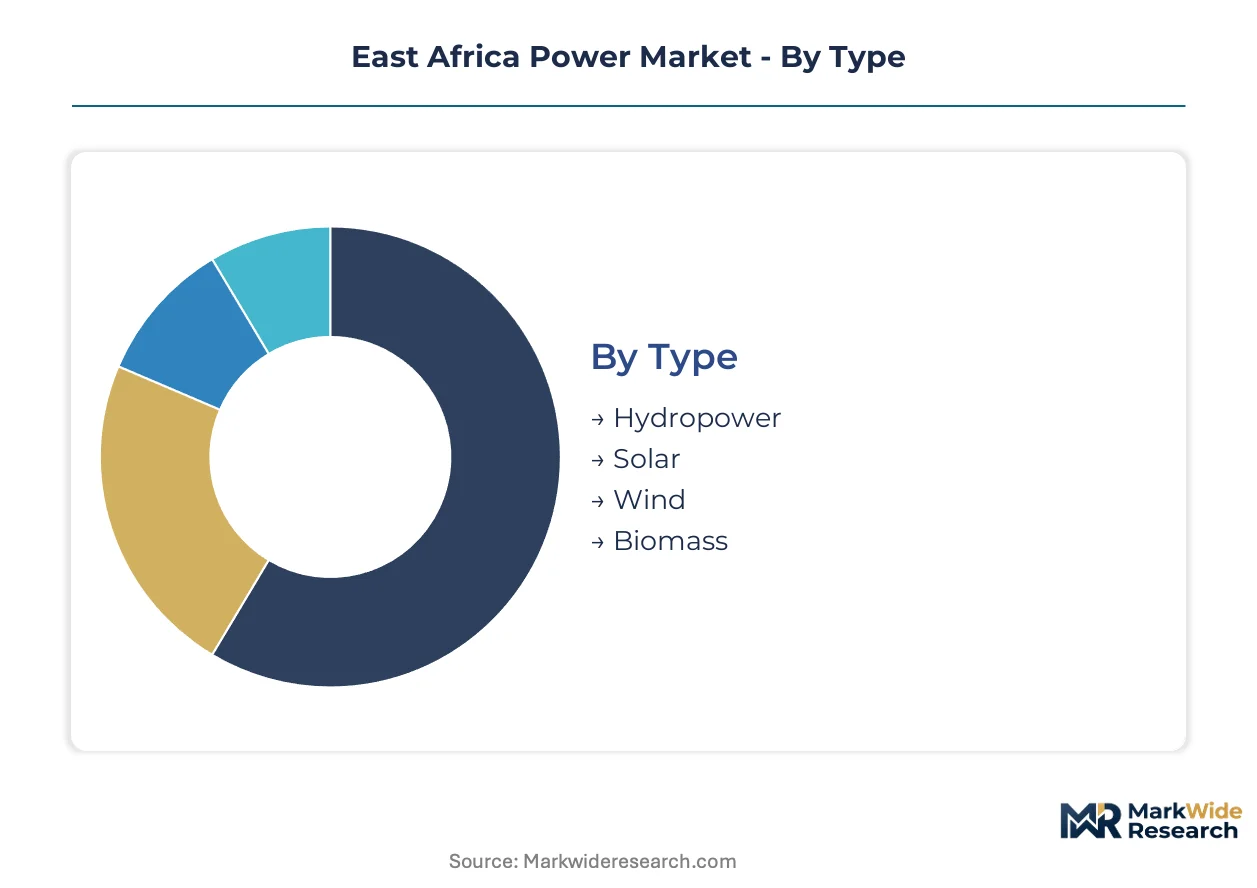
Segmentation reveals how East Africa's power market fragments across generation technologies, demand applications, and institutional buyers. Each dimension carries distinct regulatory burdens, procurement timelines, and infrastructure requirements that shape investment decisions.
Type:
Kenya's Energy Regulatory Authority classifies generation assets by fuel source for licensing purposes, with geothermal and solar receiving expedited environmental approvals compared to hydropower. Ethiopia's Ethiopian Energy Authority applies differentiated feed-in tariffs by technology type.
- Hydropower:Reservoir-based generation dominates installed capacity across the Nile basin. Ethiopian Electric Power operates the region's largest fleet, though prolonged drought cycles constrain output at facilities dependent on Blue Nile and Omo River watersheds.
- Solar:Utility-scale photovoltaic plants achieve sub-$0.05/kWh tariffs that displace diesel peaking alternatives. Kenyan Rift Valley clusters benefit from existing transmission infrastructure and high irradiance levels that compress project development timelines.
- Wind:Lake Turkana corridor in northern Kenya hosts the continent's largest wind farm, feeding into the national grid through dedicated 400 kV lines. Ethiopian highland sites in the Afar region attract pre-development activity under revised procurement frameworks.
- Biomass:Agricultural residue and bagasse co-generation serves sugar estates in western Kenya and southern Ethiopia. Uganda's Electricity Regulatory Authority mandates domestic content requirements for rural biomass electrification contractors.
Leading the category by volume: Hydropower. Growing fastest: Solar.
Application:
Demand patterns split between grid-connected load centers and off-grid settlements, with industrial buyers driving behind-the-meter procurement.
- Industrial:Kenyan manufacturing clusters in the Rift Valley corridor deploy captive solar to offset grid reliability volatility. Mining operators in Tanzania's gold and nickel belts negotiate co-investment structures with Tanzania Electric Supply Company Limited for dedicated transmission.
- Residential:Urban electrification concentrates in Nairobi, Addis Ababa, and Dar es Salaam distribution networks. Rural access programs target last-mile connections through results-based financing mechanisms.
- Commercial:Retail and hospitality loads in East African capitals drive demand for backup power solutions. Shopping malls and data centers procure hybrid solar-storage configurations to manage tariff escalation.
- Agricultural:Irrigation pumping and cold chain facilities require reliable supply in remote locations. Ethiopian horticulture exporters near Modjo and Ziway rely on grid-solar hybrid systems for processing operations.
Industrial offtake commands premium tariffs. Residential connections expand most quickly under national electrification programs.
Technology:
Technology deployment reflects infrastructure maturity and loss-reduction priorities across distribution networks.
- Smart Grids:Automated metering infrastructure targets technical losses exceeding 20% in Tanzania and Uganda. Kenya Power's advanced metering rollout enables time-of-use pricing for large consumers.
- Renewable Sources:Geothermal-solar hybrid configurations at Kenyan Rift Valley sites provide firm capacity without fossil fuel backup. Technology convergence enables 24-hour renewable supply contracts.
- Energy Storage:Lithium-ion battery integration shifts project economics for utility-scale solar. Ethiopian Electric Power evaluates pumped hydro storage to manage hydropower output variability.
- Transmission:400 kV interstate lines under the Eastern Africa Power Pool enable cross-border wheeling. Limited evacuation capacity constrains power export from remote generation clusters.
Smart grid investment leads capital deployment. Energy storage climbs the fastest as battery costs decline.
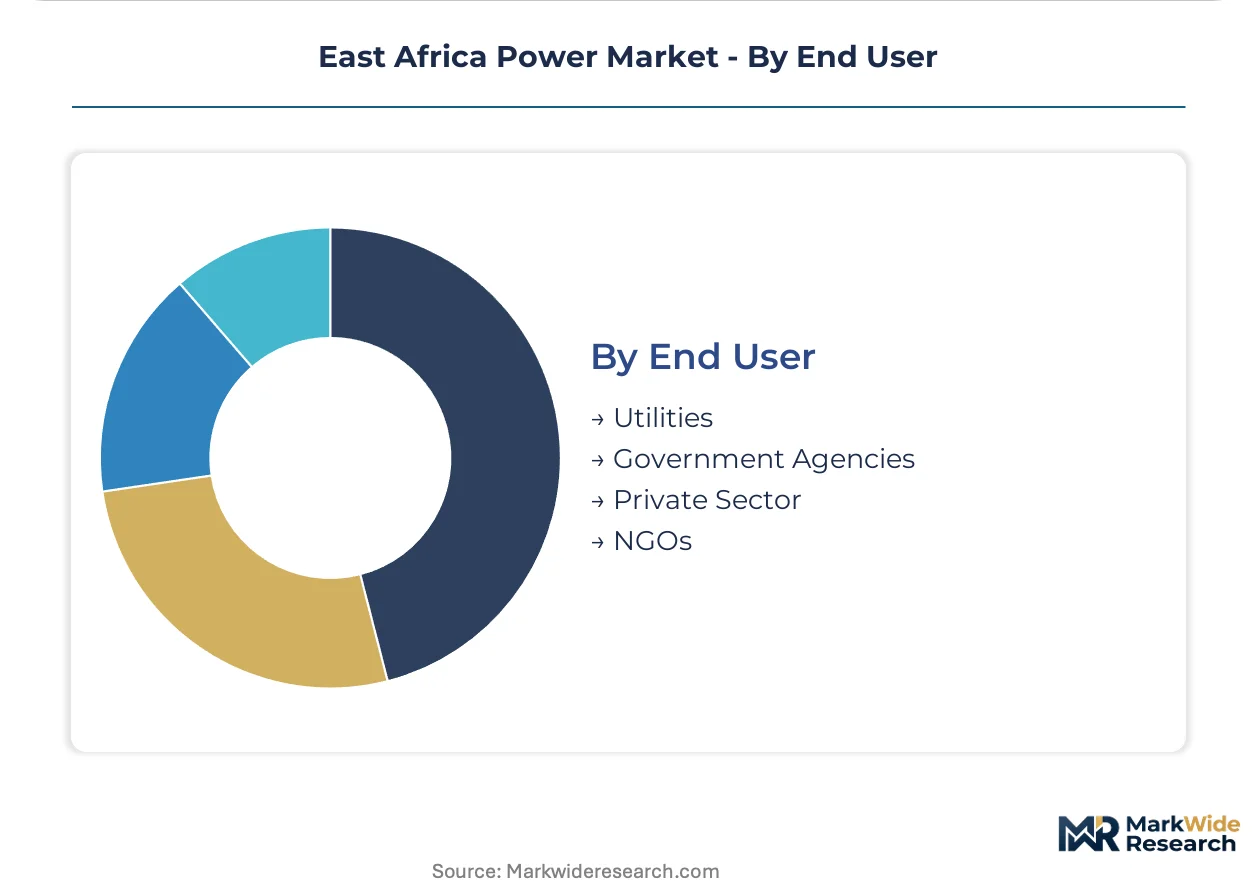
End User:
Institutional buyer categories determine procurement mechanisms, risk allocation, and financing structures.
- Utilities:Kenya Electricity Generating Company PLC and Ethiopian Electric Power anchor long-term power purchase agreements. State-owned buyers dominate transmission and distribution infrastructure ownership.
- Government Agencies:Rural electrification authorities in Uganda and Tanzania administer donor-funded access programs. Procurement follows multilateral lending standards with domestic content mandates.
- Private Sector:Independent power producers develop utility-scale assets under feed-in tariff and competitive tender frameworks. Industrial offtakers unbundle energy procurement from distribution service obligations.
- NGOs:Development finance institutions and climate funds channel concessional capital into mini-grid and off-grid solar. Results-based financing structures tie disbursements to verified connections.
Utilities lead procurement volume. Private sector participation gains share fastest under regulatory reforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Africa's generation capacity exceeds internal consumption in Ethiopia while Kenya and Tanzania face supply deficits that drive cross-border procurement. The Eastern Africa Power Pool infrastructure channels surplus hydropower across national boundaries. Transmission constraints and divergent grid codes fragment what could function as an integrated regional market.
Kenya
Geothermal and solar hybrid projects cluster in the Rift Valley corridor near existing 400 kV transmission infrastructure. Kenya's Energy Regulatory Authority enforces grid codes that determine independent power producer market access. Manufacturing facilities around Naivasha and Nakuru deploy captive solar installations to offset grid reliability volatility.
Ethiopia
Utility-scale solar and wind procurement accelerates under feed-in tariff reforms administered by the Ethiopian Energy Authority. The country's national electrification program targets universal access through grid extension and off-grid solutions. Pre-development activity concentrates in the Afar and Somali regions where solar irradiance levels support competitive project economics.
Tanzania
Mining operators in gold and nickel belts negotiate co-investment structures with the national utility for dedicated transmission infrastructure. Tanzania Electric Supply Company Limited extends rural electrification through partnerships with extractive sector investors. Technical losses exceeding 20% in distribution networks drive smart grid investment priorities.
Uganda
Domestic content requirements mandated by Uganda's Electricity Regulatory Authority shape procurement patterns for rural electrification contractors. Hydropower facilities on the Nile face structural constraints from prolonged drought cycles affecting reservoir levels. Agricultural processing and cold chain facilities in the central region require reliable supply for export-oriented horticulture operations.
Ethiopia-Djibouti-Sudan Interconnection
Cross-border wheeling tariffs enable surplus Ethiopian hydropower exports through interconnection lines into Djibouti and Sudan. The Eastern Africa Power Pool framework governs regional power trade but implementation lags behind infrastructure completion. Industrial load centers in Djibouti's port zone and Sudan's agricultural belt represent concentrated demand for imported firm capacity.
East Africa Power Market Competitive Landscape
The competitive structure tilts toward state-owned integrated utilities that control transmission and distribution infrastructure. Market concentration remains high at the utility tier while independent power producers compete for generation slots under feed-in tariff and competitive tender frameworks. Two strategic archetypes dominate: vertically integrated national champions and specialized renewable developers. Competitive moves center on securing long-term power purchase agreements and navigating regulatory harmonization across national boundaries.
Among state-owned generation and transmission utilities, Kenya Electricity Generating Company PLC and Ethiopian Electric Power occupy positions as anchor suppliers for their respective national grids. Tanzania Electric Supply Company Limited represents the integrated utility archetype combining distribution monopoly with generation procurement authority. These entities exemplify how public ownership of transmission infrastructure constrains market entry for private capital while creating opportunities for independent generation investment.
| Leading Market Players |
|---|
| Kenya Electricity Generating Company PLC |
| Kenya Electricity Transmission Company |
| Kenya Power and Lighting Company PLC |
| Ethiopian Electric Company |
| Uganda Electricity Transmission Company Limited |
| Ethiopian Electric Power |
| Tanzania Electric Supply Company Limited |
| Tower Transmission and Distribution Companies |
| Uganda Electricity Generation Company Limited |
| Others |
Supply & Pricing Matrix
Sovereign-backed utilities across East Africa anchor supply discipline through vertically integrated procurement structures that compress developer margins while securing long-term offtake. State ownership of transmission infrastructure in Kenya and Ethiopia creates asymmetric bargaining power that shapes pricing outcomes across generation tenders.
Pricing Analysis
Margin tightening in utility-scale solar reflects competitive auction mechanisms that displace bilateral negotiations under Ethiopia's feed-in tariff reforms. Three-tier pricing structure across geothermal baseload, solar peaking, and diesel backup segments creates differentiation based on dispatchability and contract duration. Cost-down pressure on independent power producers accelerates as Kenya's Energy Regulatory Authority mandates standardized grid connection charges. Industrial offtakers in the Rift Valley corridor exhibit lowest price sensitivity due to reliability premiums, while rural electrification programs face acute budget constraints.
Supply Chain Analysis
Refurbishment flows for distribution transformers and switchgear create secondary supply channels that compete with original equipment manufacturers in Tanzania and Uganda. Equipment manufacturing concentrates in China, India, and South Africa for turbines, photovoltaic modules, and switchyard components. Lithium-ion battery cells, copper conductors, and steel lattice towers anchor raw material dependencies. Single-source vulnerability for high-voltage transformer cores poses structural risk. Distribution runs through national utility warehouses and international EPC contractor logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa's power sector sits in a technology-transition phase as lithium-ion battery storage displaces diesel peaking infrastructure across industrial and utility applications.
For Market Incumbents: Lock in geothermal-solar hybrid site control through lease extensions and transmission capacity reservations before independent power producers consolidate Rift Valley corridor positions. Kenya Electricity Generating Company PLC should accelerate backward integration into battery storage assembly to defend against technology substitution in firm capacity procurement. Grid code harmonization advocacy across the Eastern Africa Power Pool creates regulatory leverage against fragmented competitor entry. For New Entrants and Emerging Players: Begin with mini-grid development in Tanzania's mining belt where Tanzania Electric Supply Company Limited co-investment structures reduce offtake risk and accelerate revenue recognition. Agricultural processing clusters in Ethiopia's Afar region represent the most penetrable segment due to nascent electrification and high irradiance resource quality. Direct equipment financing partnerships with Chinese module suppliers enable competitive tariff positioning without balance sheet strain. For Investors and Strategic Acquirers: Ethiopian Energy Authority feed-in tariff publication is the leading indicator that utility-scale procurement velocity will accelerate across the Afar and Somali regions. Long-term viability favors developers with hybrid technology capabilities and existing transmission interconnection agreements rather than pure-play solar or wind assets. Acquisition targets should demonstrate operational geothermal assets or secured grid connection points. Monitor drought frequency indices for Nile basin watersheds as the leading supply-side risk signal.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal-Solar Hybrid Development | Kenya's Rift Valley corridor enables 24-hour renewable supply contracts that displace diesel alternatives. |
| Smart Grid Infrastructure Deployment | Automated metering infrastructure targets technical losses exceeding 20% in Tanzania Electric Supply Company Limited networks. |
| Cross-Border Wheeling Agreement | Eastern Africa Power Pool interconnection lines unlock multi-country offtake for surplus Ethiopian hydropower exports. |
| Battery Storage Integration | Lithium-ion systems shift project economics for utility-scale solar in evening peak demand periods. |
| Mining Electrification Partnership | Co-investment frameworks with gold and nickel operators create captive demand for remote generation in Tanzania. |
Research Methodology
Independent corroboration across utility planning officers, independent power producer project developers, EPC contractors, and grid operators underwrites the qualitative findings on procurement structure evolution. Primary interviews with Kenya's Energy Regulatory Authority licensing staff and Ethiopian Energy Authority feed-in tariff administrators combined with secondary validation from Eastern Africa Power Pool framework documents and national electrification program disclosures. Bottom-up project pipeline aggregation and top-down macroeconomic demand modeling provide cross-verification.
Rate-of-change decomposition across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type segments structures the analytical framework. CAGRs derive from capacity addition schedules, demand elasticity assumptions, and tariff trajectory modeling. Hydrological variability indices for Nile basin watersheds and solar irradiance measurement station data inform technology-specific output assumptions.
Prolonged drought cycles, feed-in tariff revision delays, and transmission interconnection bottlenecks are the dominant revision risks to capacity and revenue forecasts. Forecasts reflect documented assumptions on regional power pool integration timelines and national electrification program funding continuity. Practitioners should monitor reservoir level telemetry, regulatory gazette publications, and 400 kV line construction milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
South America Thermal Power Market
Power Generation
Japan Thermal Power Plant Market
Power Generation
Iraq Power EPC Market
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Global Power to Gas Market
Power Generation
Canada Power EPC Market
Power Generation
Oilfield Power Generation Market
Power Generation
Stirling Engine Market
Power Generation
Algeria Power Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Thermal Power Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Air Cooled Turbo Generators Market
Power Generation
Microturbine Market