
 On-Grid Combined Heat and Power Market | 2026-2036
On-Grid Combined Heat and Power Market Size, Share, and Industry Trends Forecast 2026-2036
On-Grid Combined Heat and Power Market Outlook
Specialized turbine technician availability is bifurcating project timelines across the On-Grid Combined Heat and Power landscape. Siemens Energy leverages its apprenticeship pipelines in Central Europe to sustain deployment velocity for large gas-turbine cogeneration packages. GE Vernova anchors North American utility-scale opportunities through controls integration and long-term service agreements. Wärtsilä competes in flexible engine-based systems for grid-balancing applications where rapid ramp rates command premium positioning.
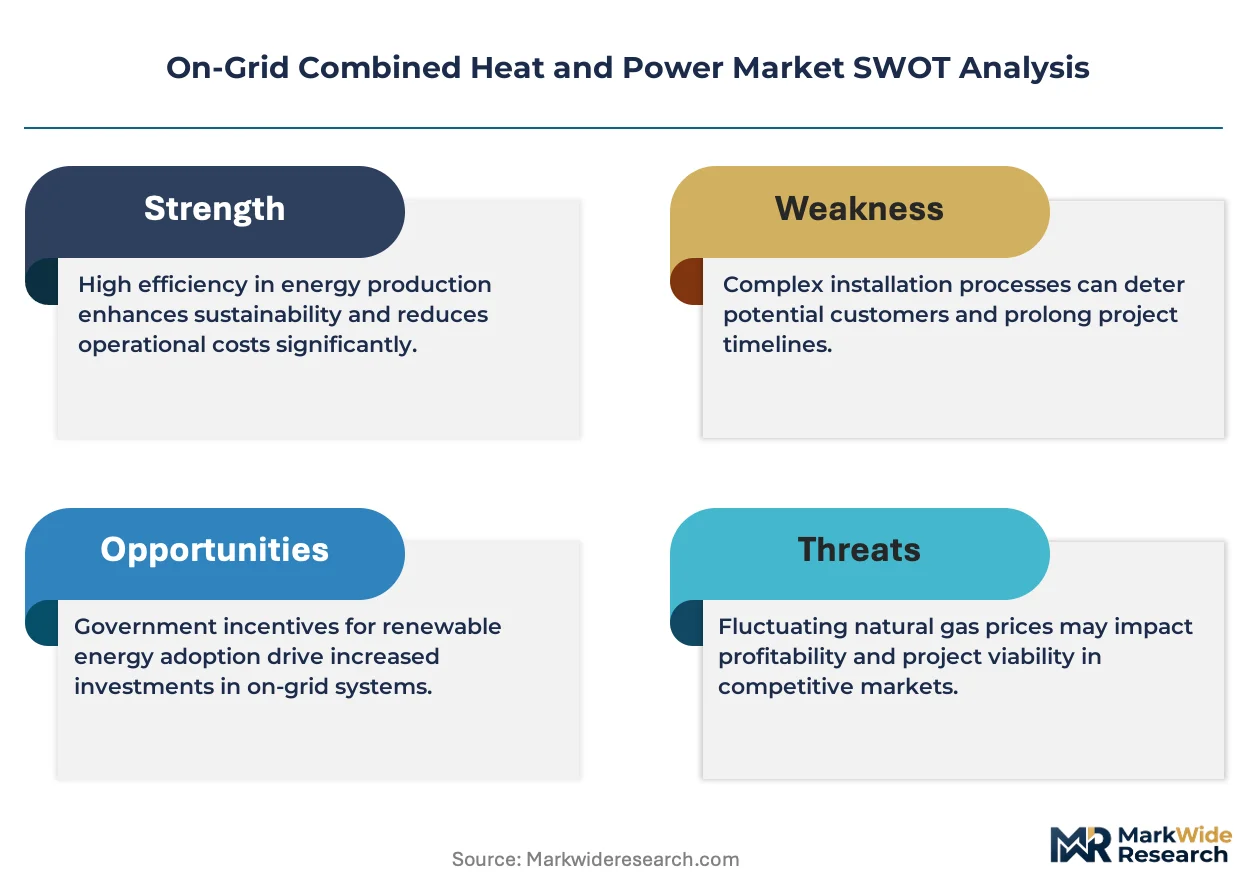
On-Grid Combined Heat and Power denotes integrated generation systems that simultaneously produce electricity and useful thermal energy from a single fuel source, typically achieving total system efficiencies of 60-80% through heat recovery steam generators or absorption chillers. The technology serves industrial facilities, commercial buildings, and institutional campuses seeking baseload reliability with lower marginal emissions than separate heat and power production. Reciprocating engines dominate the technology mix for sub-20 MW installations where modular deployment and fast commissioning offset higher per-kW capital costs. Fuel cells represent the fastest-expanding technology segment as solid-oxide designs approach commercial scale for data center and healthcare microgrids demanding near-zero local emissions. Natural gas retains the largest fuel-type share though biogas qualification under renewable thermal certificates is redrawing margin pools toward anaerobic digester-linked projects.
EPA Clean Air Act standards and FERC interconnection rules govern equipment certification and grid access protocols across United States installations, while EU F-Gas Regulation and Ecodesign Directive constrain refrigerant selection and minimum efficiency thresholds for European deployments. Germany's Federal Network Agency and state building codes enforce priority dispatch and grid tariff treatment that directly shape project finance structures. Stakeholders must monitor evolving carbon border adjustments and hydrogen blending mandates that could reclassify fuel eligibility and reset equipment depreciation schedules without warning.
Market Dynamics
EPA emissions standards and state-level interconnection rules are tightening equipment requirements for on-grid CHP systems, forcing manufacturers to accelerate certification cycles while hospital campuses and industrial facilities simultaneously expand baseload generation to secure resilient power.
Growth Catalysts
- Fuel cell solid-oxide designs:Solid-oxide fuel cells are approaching commercial scale for data center and healthcare microgrids demanding near-zero local emissions, unlocking premium positioning in urban air-quality non-attainment zones.
- Germany's priority dispatch framework:The Federal Network Agency enforces grid tariff treatment that directly shapes project finance structures, accelerating district heating integration in the Rhine-Ruhr industrial corridor.
- Biogas renewable thermal certificates:Anaerobic digester-linked projects qualify under state-level renewable thermal programs, redrawing margin pools toward agricultural and wastewater treatment facility deployments.
Market Restraints
- Specialized turbine technician scarcity:Central European apprenticeship pipelines sustain only limited deployment velocity, creating technician availability bifurcation across project timelines.
- Natural gas price volatility:Fuel cost swings compress project IRR calculations and deter long-term power purchase agreement underwriting for merchant CHP assets.
- EU F-Gas Regulation constraints:Refrigerant selection limitations for absorption chilling systems restrict technology configuration flexibility in European installations.
Strategic Opportunities
- Hydrogen blending mandates:Evolving carbon border adjustments could reclassify fuel eligibility and reset equipment depreciation schedules, creating first-mover advantage for turbine OEMs with H2-ready combustion systems.
- Data center thermal loads:Hyperscale computing facilities present untapped demand for engine-based systems with rapid ramp rates for grid-balancing applications.
- Controls integration unbundling:Utility-scale opportunities favor vendors offering long-term service agreements separate from equipment supply, opening channel innovation for specialized software providers.
Industry Challenges
- Grid interconnection certification timelines:FERC interconnection rules and state-level queue management create multi-year delays between equipment procurement and commercial operation.
- Legacy steam infrastructure incompatibility:Heat recovery steam generator integration with existing district heating networks requires custom engineering that fragments project economics.
- Depreciation schedule uncertainty:Carbon border adjustment mechanisms threaten to reset tax treatment without warning, complicating project finance structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Grid Combined Heat and Power Market |
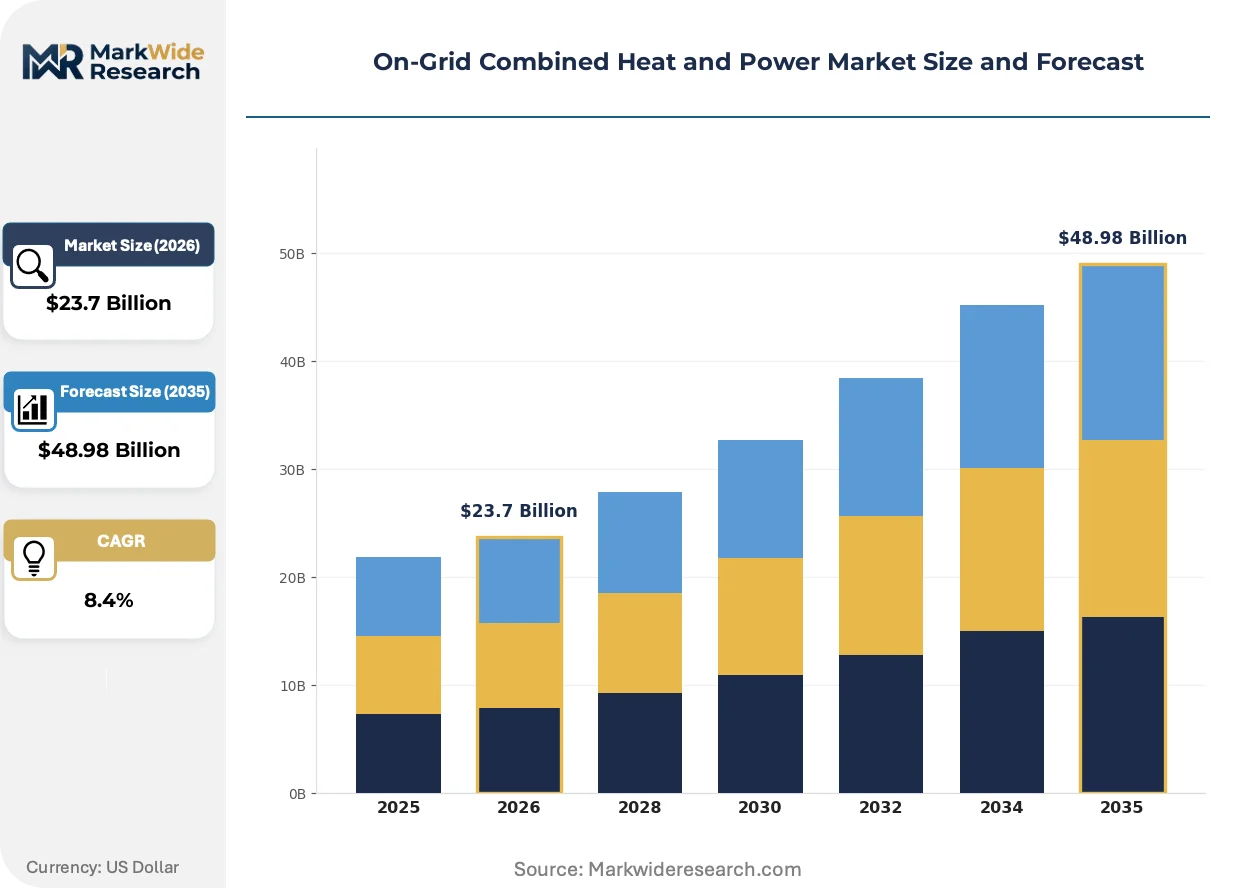
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microturbines, Reciprocating Engines, Fuel Cells, Steam Turbines End User: Industrial Facilities, Commercial Buildings, Universities, Healthcare Institutions Installation Type: New Installation, Retrofitting, Upgrades, Multi-Site Installations Fuel Type: Natural Gas, Biomass, Biogas, Others |
| Companies Covered | Siemens Energy, GE Vernova, Wärtsilä, Mitsubishi Heavy Industries, Veolia, Cummins, Bosch Thermotechnology, 2G Energy, Capstone Turbine Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Grid Combined Heat and Power Market Strategic Shifts
Solid-oxide fuel cell technology is actively reshaping competitive positioning in sub-20 MW installations, while regulatory pressure on refrigerants and thermal efficiency thresholds accelerates equipment refresh cycles across European and North American deployments.
Solid-oxide fuel cell systems simultaneously produce electricity and useful thermal energy through electrochemical conversion rather than combustion, achieving electrical efficiencies above 60% without the mechanical losses inherent to rotating equipment. Data center operators and hospital campuses are adopting these systems at accelerating pace where local air quality restrictions prohibit conventional turbine or engine installations. This technology is supplanting traditional reciprocating engine packages in urban microgrid applications, compressing addressable market share for conventional combustion-based systems in premium emission-control zones.
The EU F-Gas Regulation and Ecodesign Directive constrain refrigerant selection and minimum efficiency thresholds for European CHP deployments, effectively banning high-global-warming-potential working fluids in absorption chilling applications. Industrial facility operators must now specify alternative refrigerant chemistries or abandon thermal cooling integration entirely, raising total installed costs for complete cogeneration packages. German state building codes and the Federal Network Agency's priority dispatch rules are most affected, with project developers responding through heat-pump hybrid configurations that sidestep absorption chiller limitations.
Long-term service agreements are unbundling from equipment supply contracts as utility-scale buyers demand operational risk transfer separate from capital procurement. North American hospital campuses and industrial facilities now procure controls integration and predictive maintenance through multi-year performance contracts rather than bundled EPC arrangements. This pattern is most visible in the United States where FERC interconnection rules and EPA Clean Air Act compliance obligations create sustained demand for outsourced operational expertise across multi-decade asset lifecycles.
On-Grid Combined Heat and Power Market Segmentation
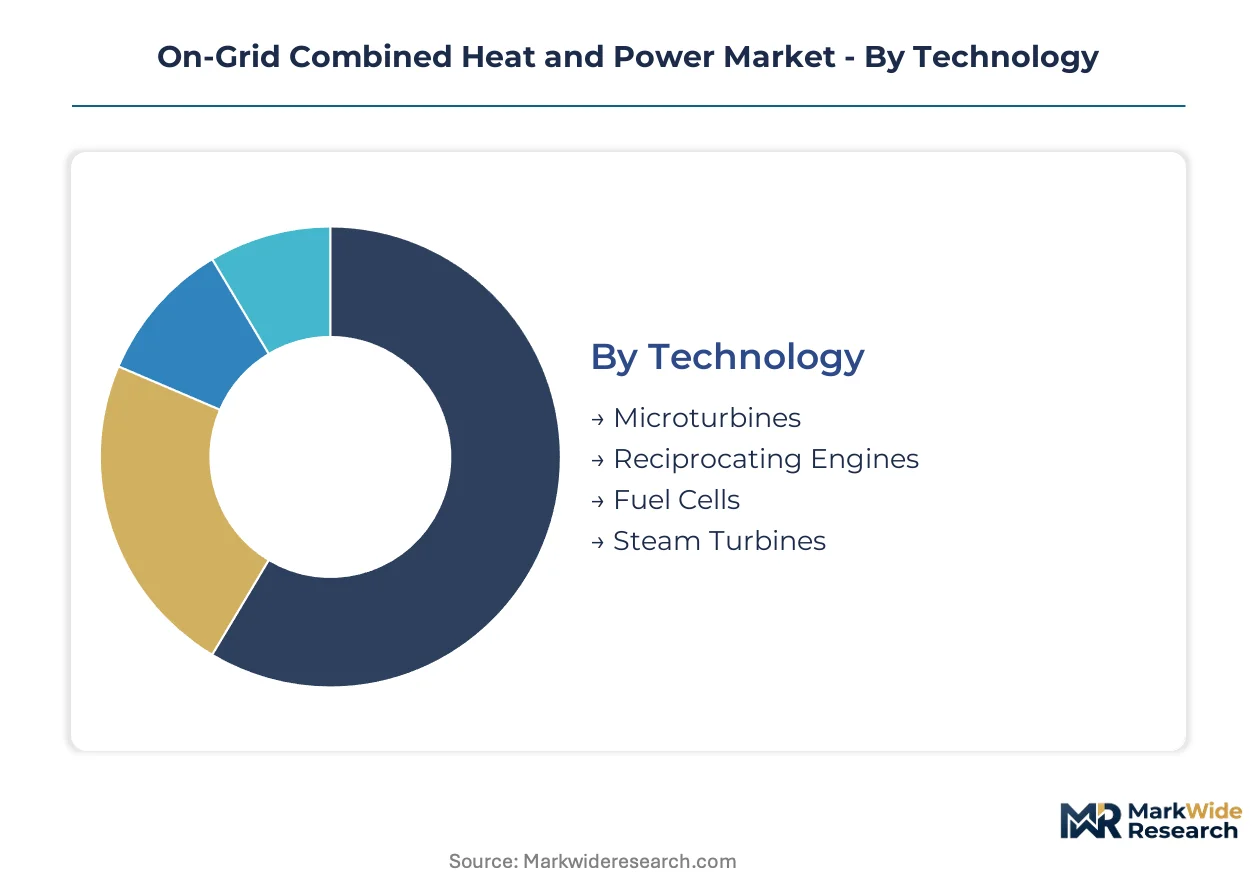
Technology choice dictates capital intensity and operational flexibility for on-grid CHP deployments. End-user characteristics determine thermal load profiles and regulatory exposure. Installation type shapes project timelines and financing structures.
Technology:
Margin pools concentrate in systems offering rapid ramp rates and modular scalability for grid-balancing applications.
- Reciprocating Engines:Compression-ignition and spark-ignition designs dominate sub-20 MW installations through fast commissioning and fuel flexibility. Hospital campuses in Germany specify these packages where priority dispatch rules reward operational responsiveness. The segment commands premium pricing in urban microgrids constrained by local air quality non-attainment zones.
- Fuel Cells:Solid-oxide electrochemical conversion achieves electrical efficiencies above 60% without mechanical losses. Data center operators in the United States deploy these systems where EPA emissions standards prohibit conventional combustion equipment. Near-zero local emissions unlock deployment in premium regulatory jurisdictions.
- Microturbines:Single-shaft gas turbine designs serve distributed generation below 500 kW with minimal maintenance requirements.
- Steam Turbines:Rankine cycle systems integrate with industrial process heat recovery for large baseload configurations.
The dominant share belongs to Reciprocating Engines, while Fuel Cells is closing the gap fastest.
End User:
Application diversity creates divergent procurement patterns across thermal load stability and regulatory scrutiny.
- Healthcare Institutions:Hospital campuses demand 24/7 baseload reliability with absorption chilling for critical infrastructure. North American facilities expand on-site generation under FERC interconnection rules that value resilient power for life-safety systems. Thermal loads from sterilization and climate control sustain year-round capacity factors.
- Industrial Facilities:Manufacturing plants in Germany's Rhine-Ruhr corridor anchor district heating integration through high-grade process heat requirements. Federal Network Agency priority dispatch treatment improves project IRR calculations for cogeneration assets serving chemical and paper production.
- Commercial Buildings:Office and retail complexes pursue CHP for peak shaving under utility demand charge structures.
- Universities:Campus microgrids combine educational facilities with research laboratories requiring uninterrupted power quality.
Industrial Facilities retain the largest installed base, though Healthcare Institutions is expanding most quickly.
Installation Type:
Project delivery models segment by capital deployment timing and operational risk allocation.
- New Installation:Greenfield deployments achieve optimal thermal-electric integration through purpose-engineered heat recovery steam generators. United States hospital campuses specify these configurations where EPA Clean Air Act compliance obligations favor integrated design over retrofit complexity. Long-term service agreements unbundle from equipment supply to transfer operational risk.
- Retrofitting:Existing building integration requires custom engineering to match heat recovery profiles with legacy infrastructure. German industrial facilities pursue these projects where state building codes mandate efficiency upgrades to district heating connections.
- Upgrades:Combustion system and controls modernization extends asset life without full replacement.
- Multi-Site Installations:Standardized equipment packages deployed across corporate or institutional portfolios capture procurement scale.
New Installation holds the majority share, while Retrofitting is gaining momentum fastest.
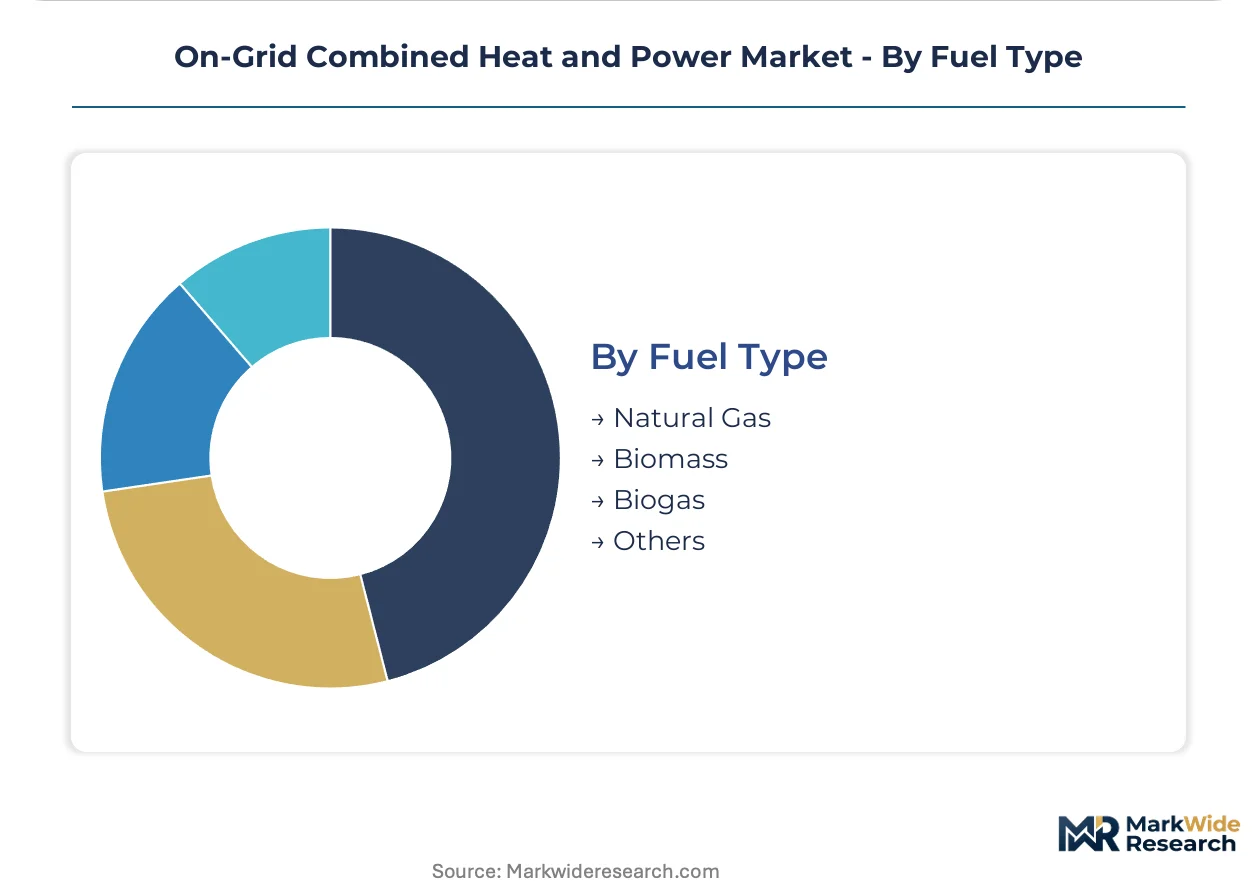
Fuel Type:
Energy transition policies are redrawing fuel eligibility and carbon accounting boundaries.
- Natural Gas:Methane-fired systems retain the largest technology share through established supply infrastructure and turbine OEM service networks. Price volatility compresses merchant CHP project returns and deters long-term power purchase agreement underwriting. Pipeline access constraints in rural industrial zones limit addressable project geography.
- Biogas:Anaerobic digester-derived methane qualifies under state-level renewable thermal certificate programs. Agricultural and wastewater treatment facilities in the United States deploy these systems where biogas capture mandates intersect with electricity revenue streams.
- Biomass:Solid fuel combustion serves industrial process heat applications with established fuel handling infrastructure.
- Others:Hydrogen blending and synthetic fuel trials position for future carbon border adjustment compliance.
Natural Gas maintains the dominant position, though Biogas is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital campuses deploy reciprocating engine systems for baseload resilience, while German industrial facilities favor gas-turbine integration with district heating networks. This consumption-mix differential reflects divergent infrastructure legacies and regulatory incentive structures across Atlantic markets.
United States
Healthcare institutions and data center operators anchor demand for sub-20 MW installations with rapid ramp capabilities. EPA Clean Air Act standards and FERC interconnection rules govern equipment certification and grid access protocols across installations. Hospital campuses in the Northeast Corridor expand on-site generation to secure resilient power for life-safety systems under tightening emissions requirements.
Germany
Chemical and paper production facilities in the Rhine-Ruhr corridor drive district heating integration through high-grade process heat requirements. The Federal Network Agency enforces priority dispatch and grid tariff treatment that directly shapes project finance structures. State building codes in North Rhine-Westphalia mandate efficiency upgrades that accelerate cogeneration retrofits.
China
Industrial parks and manufacturing zones deploy large-scale steam turbine systems for process heat recovery applications. National dual carbon goals and provincial emissions trading schemes constrain fuel eligibility for new installations. The Yangtze River Delta cluster sees accelerating adoption of gas-engine systems for grid-balancing services.
Japan
Commercial buildings and district heating operators pursue compact cogeneration for peak shaving under utility demand charge structures. METI efficiency standards and building energy codes establish minimum performance thresholds for urban deployments. The Kanto region around Tokyo hosts concentrated deployment of fuel cell systems for premium emission-control zones.
United Kingdom
University campuses and healthcare facilities combine CHP with campus microgrids requiring uninterrupted power quality. Building regulations and carbon reduction commitments drive efficiency upgrades to existing thermal infrastructure. The Southeast region including London sees specialized fuel cell adoption where local air quality restrictions prohibit conventional combustion.
On-Grid Combined Heat and Power Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the On-Grid Combined Heat and Power competitive structure. Turbine OEMs with captive service networks command premium positioning in utility-scale deployments, while engine manufacturers compete on modular scalability for distributed applications. Two strategic archetypes dominate: full-system integrators bundling equipment with long-term performance contracts, and component specialists supplying controls or heat recovery subsystems to third-party assemblers. Competitive moves concentrate on unbundling service agreements from equipment supply and expanding hydrogen-ready combustion portfolios.
Among integrated energy technology providers, Siemens Energy and GE Vernova exemplify the full-system archetype through their apprenticeship pipelines and controls integration capabilities. Wärtsilä occupies a distinct position in flexible engine-based systems where rapid ramp rates command premium positioning for grid-balancing applications. These three anchors represent divergent geographic footprints and technology specializations that collectively span gas-turbine, reciprocating engine, and emerging fuel cell segments.
| Leading Market Players |
|---|
| Siemens Energy |
| GE Vernova |
| Wärtsilä |
| Mitsubishi Heavy Industries |
| Veolia |
| Cummins |
| Bosch Thermotechnology |
| 2G Energy |
| Capstone Turbine Corporation |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month lead times for large-frame gas turbine rotors concentrate pricing power with German and Japanese forging houses, compressing margins for EPC contractors while amplifying cost pass-through to hospital campuses and industrial facilities procuring turnkey cogeneration packages. This inventory-to-delivery gap shapes contract structures and supplier selection across the on-grid CHP landscape.
Pricing Analysis
Long-term service agreements dominate commercial structures, unbundling twenty-year operational risk from equipment capital outlays. Premium-mid-economy pricing differentiation separates turbine OEMs with captive technician networks from engine assemblers sourcing controls and heat recovery subsystems. Price erosion runs through the reciprocating engine tier as modular suppliers compete on commissioning speed. Hospital campuses in the United States exhibit lowest price sensitivity due to FERC interconnection compliance obligations, while agricultural biogas developers face acute capital constraints.
Supply Chain Analysis
Strait of Hormuz transit exposure for specialty alloy castings concentrates supply risk in a single logistics corridor serving European and Asian turbine manufacturers. Component sourcing draws from Germany, Japan, and the United States for precision-machined rotors, heat-resistant coatings, and digital control systems. Single-source vulnerability persists for solid-oxide fuel cell electrolyte ceramics. Distribution runs through EPC-led project delivery rather than merchant equipment stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology fragmentation across combustion, electrochemical, and hybrid thermal systems creates specialist niches as data center operators and hospital campuses diverge on emissions tolerance and ramp-rate requirements. This demand-side bifurcation rewards focused positioning over broad portfolio coverage.
For Market Incumbents: Fortify service network density in the Rhine-Ruhr corridor and Northeast Corridor hospital clusters where technician availability constrains competitor entry. Deepen backward integration into hydrogen-ready combustion testing to preempt regulatory reclassification of fuel eligibility. Lock in multi-decade performance contracts with controls integration as the anchor capability. For New Entrants and Emerging Players: EPA certification fast-track for sub-20 MW reciprocating engine packages opens immediate addressable market in United States urban air-quality non-attainment zones. Target anaerobic digester-linked biogas projects where renewable thermal certificate qualification redrew margin pools toward agricultural and wastewater facilities. Lead with modular deployment speed against incumbent EPC timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded CHP service divisions lacking scale for standalone viability. Five-to-ten-year viability hinges on hydrogen blending mandate timing and carbon border adjustment implementation. Watch FERC interconnection queue reform as the signal for project finance availability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Combustion Certification | Positions turbine OEMs for fuel eligibility reclassification under evolving EPA standards. |
| Controls Integration Unbundling | Separates operational risk transfer from capital procurement for utility-scale hospital buyers. |
| District Heating Network Retrofit | Captures German state building code mandates for efficiency upgrades in Rhine-Ruhr corridor. |
| Biogas Supply Agreement Structuring | Links anaerobic digester output to renewable thermal certificate revenue streams. |
| Technician Apprenticeship Pipeline | Sustains deployment velocity where Central European labor scarcity fragments project timelines. |
Study Parameters
A spread of perspectives from IPP project developers, EPC contractors, utility planning officers, and grid operators converged on the working assumptions for deployment velocity and regulatory treatment. Primary interviews triangulated against FERC filings, EIA generation data, IEA technology roadmaps, and project development databases. Bottom-up capacity addition modeling cross-checked with top-down macroeconomic drivers across the analysis window.
Segmentation dimensions modeled include fuel source, generation capacity tier, end-user application, installation type, and regional regulatory framework. CAGRs derived from installed base growth trajectories and replacement cycle timing. Forecast inputs incorporated hydrogen blending mandate schedules and carbon border adjustment mechanism proposals without fixed implementation dates.
The analysis sits within stated boundaries; outcomes outside sustained natural gas price stability or unaltered EPA emissions standards would require recalibration. Practitioners should keep alternative scenarios live as FERC interconnection rulemaking and EU F-Gas Regulation revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Microturbine Market
Power Generation
Residential Solar Generator Market
Power Generation
Global Black Start Generator Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Distributed Generation Market
Power Generation
Global Gas Turbines Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
Distributed Power Generation Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
India Gas Generator Market
Power Generation
Air Cooled Turbo Generators Market
Power Generation
Tunisia Power Market
Power Generation
Variable Speed Generator Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Iraq Power EPC Market
Power Generation
Japan Combined Heat and Power Market