
 North America Distributed Power Generation Market | 2026-2036
North America Distributed Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Distributed Power Generation Market Analytics
The gap between centralized grid reliability and on-site power resilience is narrowing as modular gas turbines, fuel cells, and battery hybrids converge on standardized control platforms. Caterpillar Inc. anchors the reciprocating engine segment through its dealership network and integrated microgrid controls. Siemens Energy competes on hydrogen-ready gas turbine technology for industrial campuses. Bloom Energy specializes in solid-oxide fuel cell systems that sustain baseload operations for data center and manufacturing clients.
Distributed power generation encompasses small-scale electricity production sited near consumption points, typically ranging from kilowatts to tens of megawatts, utilizing reciprocating engines, gas turbines, fuel cells, solar photovoltaics, and energy storage in combined or standalone configurations to serve on-grid, off-grid, or hybrid installations. Solar and microgrid technology segments command the largest share of new capacity additions as module costs decline and inverter interoperability standards mature. The residential and commercial application categories are expanding fastest behind third-party financing structures and virtual power plant aggregation models that pool homeowner and business assets for grid services revenue.
The Federal Energy Regulatory Commission shapes interstate market access for distributed resources through Order 2222 aggregation rules, while EPA emissions standards for stationary reciprocating engines constrain new diesel generator deployments and redirect investment toward natural gas and zero-carbon alternatives. NERC reliability standards impose cybersecurity and operational protocols that raise compliance costs for microgrid controllers and remote monitoring systems. Stakeholders must weigh technology lock-in risks against evolving state-level net metering reforms and interconnection queue reforms that could alter project returns without warning.
Market Dynamics
ERCOT grid volatility in Texas is compressing procurement timelines for commercial and industrial buyers, forcing asset decisions ahead of traditional planning cycles as outage costs exceed capital recovery periods for on-site generation.
Growth Catalysts
- Inflation Reduction Act investment tax credits:The IRA's modified ITC structure now covers standalone battery storage and hydrogen production facilities, redirecting developer capital toward hybrid microgrids.
- Data center load growth:Hyperscale operators in Virginia and Arizona are procuring firm on-site capacity to bypass interconnection queues stretching beyond 36 months.
- FERC Order 2222 implementation:Aggregation rules for distributed energy resources are opening wholesale market revenue streams for commercial solar-plus-storage portfolios.
Market Restraints
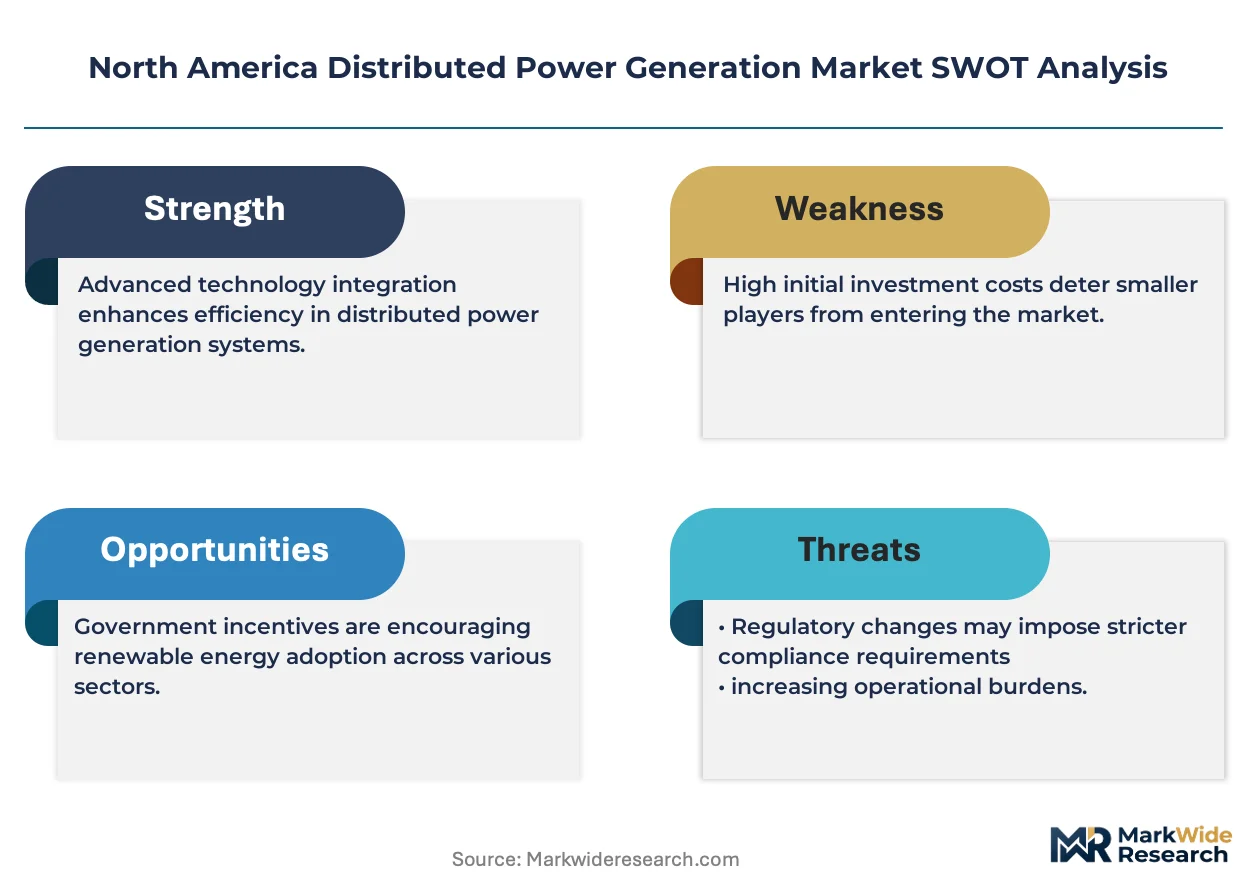
- Lithium-ion supply concentration:Cathode active material processing remains concentrated in China, exposing US project developers to tariff and logistics volatility.
- EPA stationary engine standards:Tier 4 final emission limits for diesel reciprocating engines are eliminating cost advantages for backup-only installations.
- Interconnection reform delays:Queue reform proceedings at regional transmission organizations are freezing project timelines without predictable resolution dates.
Strategic Opportunities
- Mexico industrial corridor electrification:Manufacturing growth in Nuevo León and Baja California is outpacing CFE transmission expansion, creating captive microgrid demand.
- Hydrogen blending in gas turbines:OEMs are certifying turbines for 30% hydrogen co-firing, enabling incremental decarbonization for existing industrial campuses.
- Virtual power plant enrollment:Residential battery aggregation platforms in California are capturing capacity payments previously restricted to utility-scale assets.
Industry Challenges
- NERC CIP-013 supply chain security:Microgrid controllers must now document provenance for all firmware and hardware components, extending procurement cycles.
- Power conversion system integration:Inverter interoperability gaps between legacy reciprocating engine controls and new battery energy storage systems are forcing custom engineering on every hybrid project.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Distributed Power Generation Market |
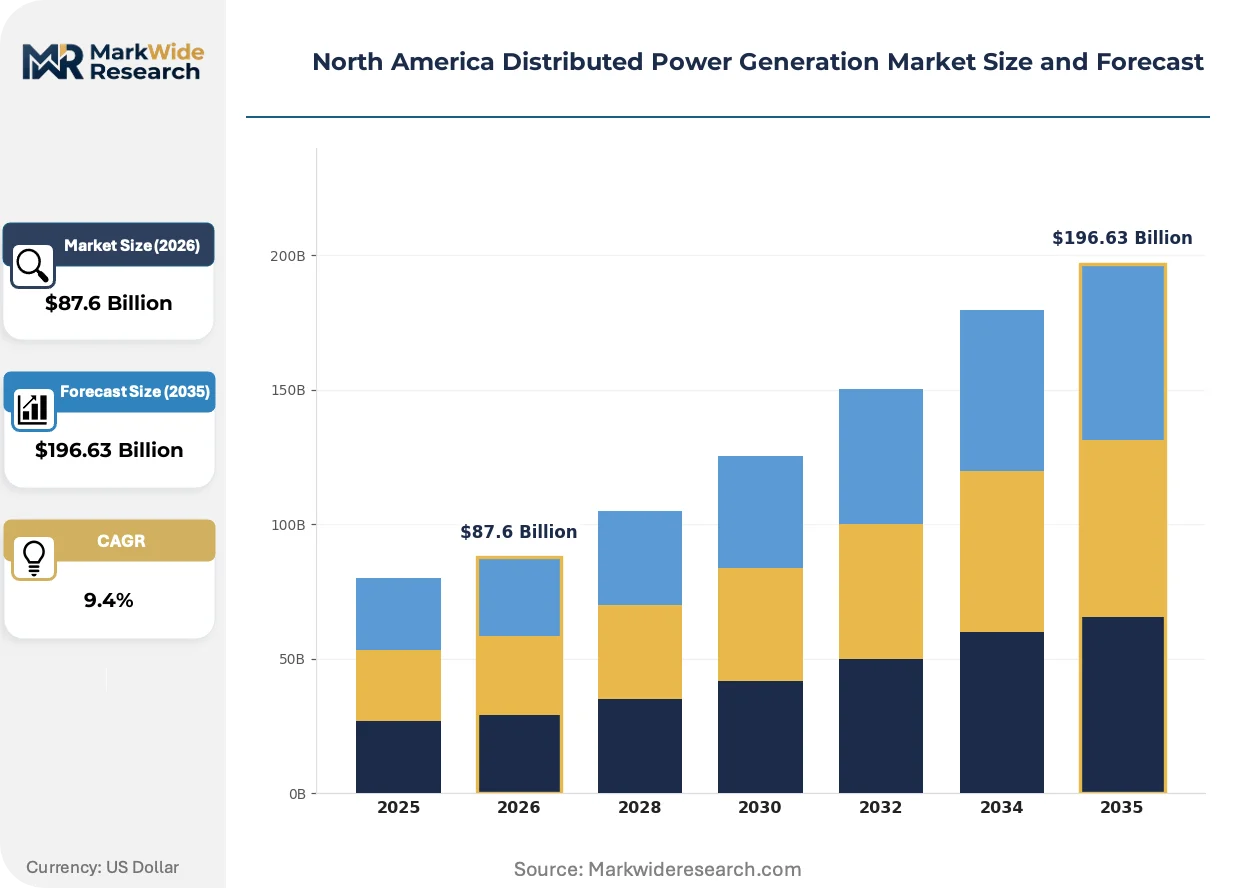
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Microgrid Application: Residential, Commercial, Industrial, Agricultural Installation Type: On-grid, Off-grid, Hybrid, Community End User: Utilities, Energy Providers, Homeowners, Businesses |
| Companies Covered | Caterpillar Inc., Schneider Electric SE, Siemens Energy, Ballard Power Systems Inc., Sunrun Inc., Capstone Turbine Corporation, Cummins Inc., Bloom Energy, NextEra Energy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Distributed Power Generation Market Evolving Landscape
Solid-oxide fuel cell stacks are achieving commercial scale for baseload data center applications, while software-defined microgrid controls are collapsing the integration timeline for multi-asset sites.
Containerized battery energy storage systems paired with modular gas turbines are hybridizing behind-the-meter power architecture for industrial campuses. Food processing and semiconductor fabrication facilities in Texas and Arizona are deploying these configurations to isolate from transmission congestion pricing. The technology is hybridizing procurement categories that utilities previously treated as separate capital programs.
The Inflation Reduction Act's domestic content bonus credits are restructuring supply chain qualification requirements for solar and storage components. Developers must now trace manufacturing origin through tier-three suppliers to capture full incentive value. California and Texas utility-scale solar projects are most affected, with engineering-procurement-construction firms requalifying module and inverter vendors.
Power purchase agreement structures for commercial and industrial offtakers are unbundling energy, capacity, and resilience value streams. Third-party microgrid operators are capturing resilience premiums through fixed-fee contracts while selling energy and ancillary services into wholesale markets. This model is most visible in ERCOT territory, where nodal pricing volatility creates arbitrage opportunities for dispatch-optimized hybrid assets.
North America Distributed Power Generation Market Segmentation
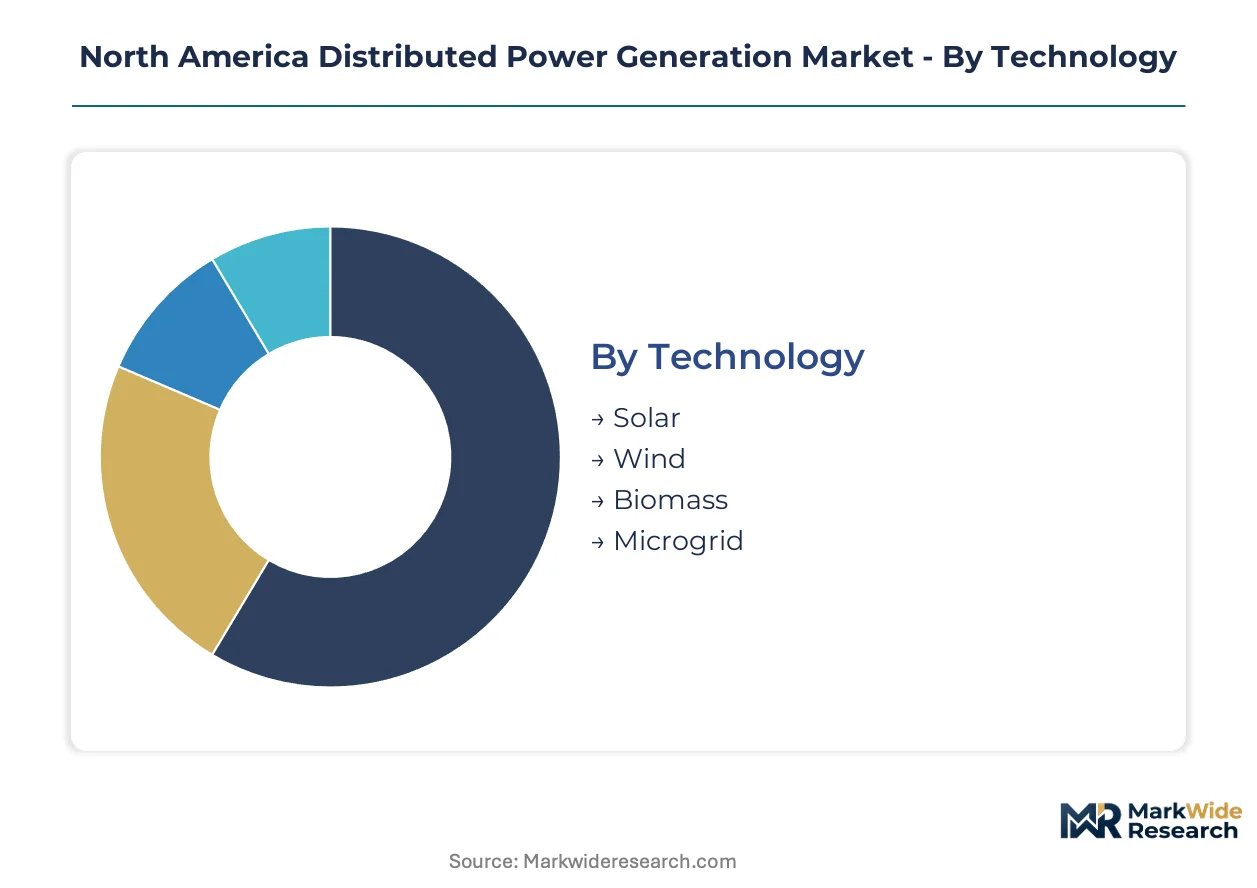
Distributed power generation markets fragment across multiple dimensions that determine equipment specifications, financing structures, and operational complexity. Technology choice dictates maintenance protocols and asset lifecycles, while application type shapes regulatory exposure and revenue model design.
Technology:
After-sales service intensity varies dramatically across technology categories, with fuel cell and microgrid systems requiring specialized technician networks that solar photovoltaic deployments rarely need.
- Solar:Photovoltaic modules paired with string or central inverters dominate new capacity additions across the United States. Residential rooftop installations in California and Texas are aggregating into virtual power plants that bid into wholesale markets through FERC Order 2222-compliant platforms.
- Wind:Small-scale turbines below 100kW serve agricultural and remote industrial sites where grid extension costs exceed capital recovery periods. Texas ranchlands and Great Plains corridors concentrate deployment where wind resource density justifies distributed rather than utility-scale architecture.
- Biomass:Anaerobic digesters and combustion systems process agricultural waste streams into firm baseload capacity for food processing facilities.
- Microgrid:Integrated control platforms coordinating multiple generation assets with islanding capability command premium engineering margins from data center and semiconductor fabrication clients.
Solar holds the largest share; momentum sits with microgrid configurations that bundle resilience premiums with energy arbitrage revenue.
Application:
Customer scale determines project finance availability and interconnection queue priority, with commercial and industrial offtakers accessing institutional capital pools unavailable to residential participants.
- Residential:Third-party ownership models and lease structures have collapsed customer acquisition costs in California, Arizona, and Texas markets. Home battery aggregation platforms are capturing capacity payments previously restricted to utility-scale assets.
- Commercial:Retail chains and office portfolios are standardizing solar-plus-storage specifications across multi-site rollouts to simplify procurement and maintenance contracts. The segment climbs fastest as net metering reforms push toward self-consumption optimization.
- Industrial:Food processing, semiconductor fabrication, and petrochemical facilities deploy firm on-site capacity to isolate from transmission congestion pricing in ERCOT territory.
- Agricultural:Irrigation pumping and cold storage loads in California's Central Valley and Florida's citrus belt match solar generation profiles with minimal storage buffering requirements.
Industrial applications command the highest average project value; commercial deployments are expanding most quickly behind standardized equipment packages.
Installation Type:
Grid interconnection status determines permitting complexity and available revenue streams, with hybrid configurations capturing the broadest set of value stacking opportunities.
- On-grid:Net metering and feed-in tariff structures govern economics, though state-level reform movements are compressing export compensation rates and redirecting design toward self-consumption maximization.
- Off-grid:Remote mining camps, telecommunications towers, and rural residences in Alaska and northern Canada rely on diesel-battery or renewable-hybrid systems where transmission infrastructure is economically prohibitive.
- Hybrid:Solar-plus-storage and turbine-battery configurations are becoming default specifications for commercial and industrial microgrids seeking to arbitrage time-of-use rates and provide backup resilience.
- Community:Shared solar programs in Colorado, Massachusetts, and Minnesota allow renters and unsuitable rooftop owners to subscribe to off-site generation through virtual net metering credits.
Hybrid installations dominate new engineering activity; community models are gaining share fastest where regulatory frameworks enable virtual net metering.
End User:
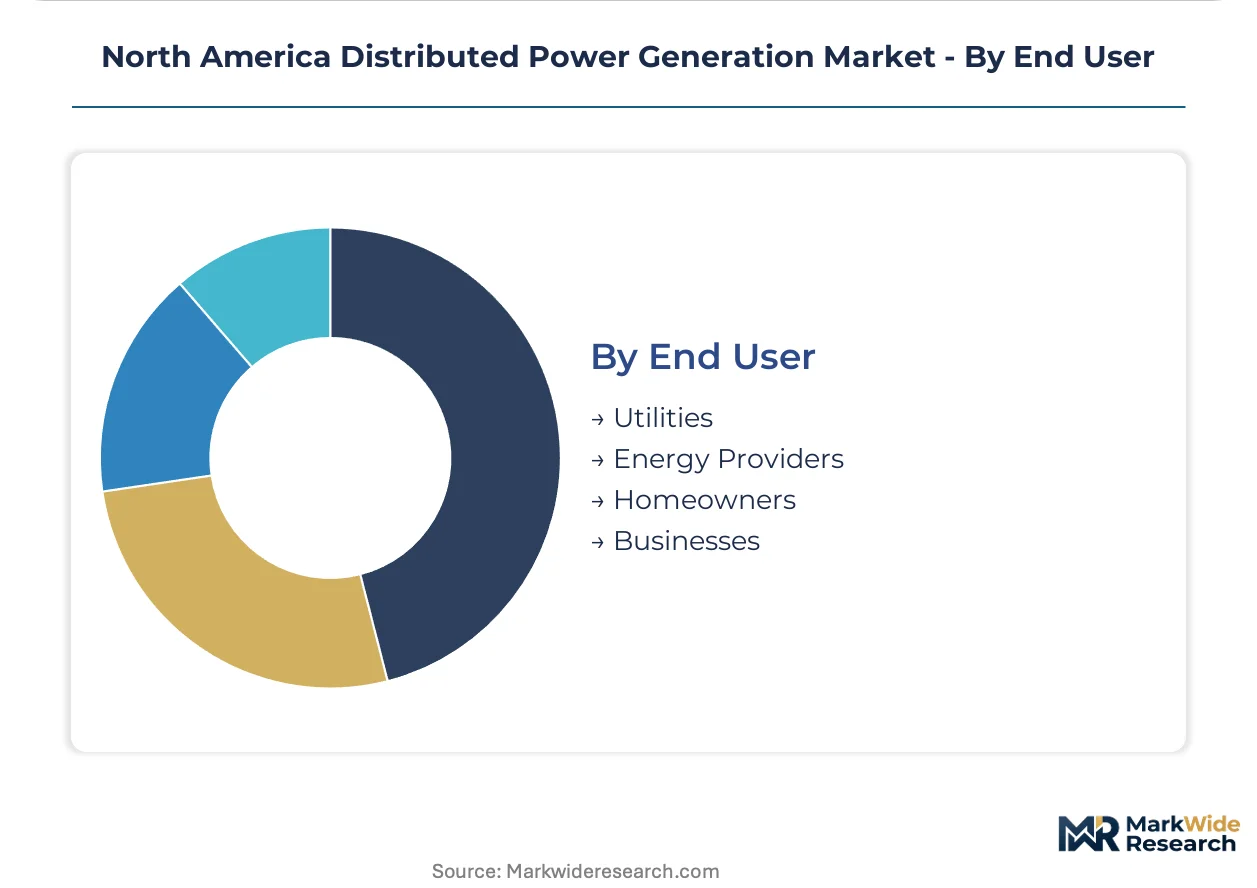
Procurement authority and balance sheet capacity separate utility-scale aggregators from behind-the-meter participants, with energy providers occupying an intermediate position that blends asset ownership with customer origination.
- Utilities:Investor-owned and municipal utilities are deploying distributed resources as non-wires alternatives to defer transmission and distribution capital upgrades, particularly in California and New York where grid congestion is most acute.
- Energy Providers:Competitive retail electricity providers and community choice aggregators are building distributed portfolios to hedge wholesale price exposure and meet renewable portfolio obligations.
- Homeowners:Individual residential adopters respond to equipment cost declines, financing availability, and resilience concerns in hurricane-exposed Gulf Coast and wildfire-prone Western markets.
- Businesses:Commercial and industrial offtakers are unbundling energy, capacity, and resilience value streams through fixed-fee microgrid contracts that transfer operational risk to third-party operators.
Utilities hold the largest share; business procurement is accelerating fastest as interconnection queue delays exceed 36 months in Virginia and Arizona data center corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators and industrial facilities drive procurement concentration across North America. Texas leads in microgrid deployments due to ERCOT grid volatility. California dominates residential solar aggregation through virtual power plant platforms.
United States
Virginia and Arizona hyperscale data centers procure firm on-site capacity to bypass interconnection queues exceeding 36 months. The Inflation Reduction Act's modified investment tax credits now cover standalone battery storage and hydrogen production facilities. ERCOT territory in Texas compresses procurement timelines as commercial buyers face outage costs exceeding capital recovery periods for distributed generation assets.
Canada
Remote mining camps and indigenous communities in northern Alberta and the Northwest Territories deploy diesel-battery hybrid systems where transmission extension proves economically prohibitive. Health Canada and Environment and Climate Change Canada impose emissions standards that redirect investment toward natural gas and renewable alternatives. Ontario's manufacturing corridor around Toronto accelerates industrial microgrid adoption to isolate from provincial grid congestion pricing.
Mexico
Manufacturing growth in Nuevo León and Baja California outpaces CFE transmission expansion, creating captive demand for industrial microgrids serving automotive and electronics assembly plants. The country's national energy regulator shapes market access rules for distributed resources while federal clean energy certificates drive renewable portfolio compliance. Monterrey anchors the northern industrial cluster where private offtakers negotiate directly with independent power producers behind the meter.
North America Distributed Power Generation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across technology categories. The market structures around three tiers: diversified industrial conglomerates with integrated microgrid controls, pure-play fuel cell and battery specialists, and regional EPC firms with project development capabilities. Strategic moves concentrate on hydrogen-ready turbine certifications and software-defined control platform acquisitions that collapse integration timelines for multi-asset sites.
Within the diversified industrial tier, Caterpillar Inc. and Siemens Energy occupy positions anchored by dealership networks and hydrogen-ready gas turbine technology respectively. Bloom Energy exemplifies the pure-play fuel cell specialist archetype with solid-oxide systems for baseload data center applications. These three companies represent the dominant competitive anchors across reciprocating engine, turbine, and fuel cell technology vectors in North American distributed power deployment.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Schneider Electric SE |
| Siemens Energy |
| Ballard Power Systems Inc. |
| Sunrun Inc. |
| Capstone Turbine Corporation |
| Cummins Inc. |
| Bloom Energy |
| NextEra Energy |
| Others |
Value Network & Pricing Analysis
Monterrey's industrial corridor concentrates cathode active material processing capacity that feeds North American battery energy storage deployments, translating upstream concentration into pricing power for cell manufacturers serving ERCOT microgrid developers.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate utility-scale solar-plus-storage procurement. Price differentiation hinges on domestic content certification for IRA bonus credits and after-sales service bundling for microgrid controls. Cost compression in standard containerized battery systems is intensifying because module oversupply from Asian manufacturers is flooding spot markets. Commercial and industrial offtakers show highest price sensitivity, while data center operators prioritize resilience premiums over unit economics.
Supply Chain Analysis
Upstream feedstock for solid-oxide fuel cells draws from nickel mining in Indonesia and rare earth processing in China, creating dual dependencies for Bloom Energy and competing stack manufacturers. Polysilicon ingots for photovoltaic modules source from polysilicon plants in Xinjiang and wafer slicing operations in Malaysia. Tariff exposure on Chinese-made inverters and battery management systems extends procurement cycles for hybrid microgrid integrators. Distribution runs through Caterpillar and Cummins dealership networks for reciprocating engines, while direct OEM relationships dominate fuel cell and turbine deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American distributed power generation functions as a service-attach opportunity where software-defined microgrid controls and predictive maintenance contracts are expanding faster than underlying hardware shipments.
For Market Incumbents: Build switching-cost moats through integrated control platform standardization that locks in multi-asset microgrid sites. Incumbents should deepen backward integration into battery management system firmware to offset inverter interoperability gaps threatening project margins. Channel control through authorized service networks creates defensive positioning against emerging virtual power plant aggregators capturing customer relationships. For New Entrants and Emerging Players: Build out specialized technician certification programs for solid-oxide fuel cell maintenance, targeting data center campuses in Virginia and Arizona where interconnection queue delays exceed three years. White-space concentration sits with hydrogen blending retrofit services for existing gas turbine installations. A direct-to-industrial go-to-market angle bypasses entrenched EPC relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among microgrid operators with fixed-fee resilience contracts and wholesale market dispatch optimization software. Long-term viability favors acquisition targets with FERC Order 2222-compliant aggregation platforms and established nodal pricing arbitrage algorithms. The signal to watch is ERCOT ancillary service price volatility compression indicating saturation of merchant battery deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Certification | Siemens Energy and GE Vernova are certifying 30% hydrogen co-firing to future-proof industrial campus installations. |
| Software-Defined Control Acquisition | Caterpillar's microgrid automation purchases collapse integration timelines for multi-asset hybrid sites. |
| Domestic Content Supply Requalification | Developers are retracing tier-three supplier origins to capture full IRA bonus credit value. |
| Virtual Power Plant Platform Buildout | Sunrun and Tesla are aggregating residential batteries into ERCOT wholesale capacity markets. |
| Fuel Cell Stack Manufacturing Scale-Up | Bloom Energy is expanding solid-oxide production for baseload data center applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, IPP project developers, EPC contractors, microgrid control engineers, and fuel supply specialists. Secondary validation drew from EIA generation statistics, FERC interconnection queue filings, IEA distributed energy outlooks, and ERCOT nodal pricing archives. Bottom-up project pipelines were triangulated against top-down capacity forecasts.
Calibration against historical deployment trajectories anchored growth assumptions across the projection horizon. Segmentation dimensions modeled include fuel source, generation capacity tier, grid interconnection status, and regional regulatory framework. CAGRs were derived from slope analysis of technology cost curves and policy incentive phase-out schedules. IRA domestic content bonus eligibility and NERC CIP-013 compliance timelines served as scenario inputs.
Stress conditions across lithium price volatility, interconnection queue reform delays, and hydrogen infrastructure buildout pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about IRA incentive continuity and ERCOT market design stability. Cross-checking against EIA Annual Energy Outlook capacity projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Thailand Power Generation EPC Market
Power Generation
Cogeneration System Market
Power Generation
Global Turbines Market
Power Generation
Coal Fired Power Generation Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Global Gensets Market
Power Generation
Oilfield Power Generation Market
Power Generation
Air Cooled Turbo Generators Market
Power Generation
India Thermal Power Plant Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Hydrogenerators Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
South East Asia Power Market
Power Generation
Commercial Gensets Market
Power Generation
Indonesia Power Market