
 Poland Renewable Energy Market | 2026-2036
Poland Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Renewable Energy Market Outlook
Market Context with Strategic Players
The capital-intensity divergence between state-backed incumbents and agile private developers is collapsing as offshore wind auctions demand multi-billion-zloty commitments from all bidders. PGE Polska Grupa Energetyczna SA leverages its balance sheet to anchor large-scale Baltic Sea projects, while RWE Renewables Poland sustains aggressive pipeline development through German parent-company technical transfer. Ørsted Poland competes by deploying Danish offshore construction expertise against domestic players with shallower marine experience.
Technical Definition and Structural Segments
Poland renewable energy encompasses electricity and heat generation systems that harness solar irradiance, wind kinetic energy, organic biomass combustion or anaerobic digestion, and run-of-river or reservoir hydropower, with photovoltaic modules typically rated at 400-600 Wp and offshore wind turbines now scaling toward 15 MW rated capacity, serving grid decarbonization and industrial cost hedging objectives. Solar dominates incremental capacity additions due to falling module prices and streamlined prosumer net-billing rules, while offshore wind concentrates long-term capital deployment despite extended permitting timelines. Utility-scale installations attract the deepest financing pools, though distributed generation segments are fragmenting procurement patterns across regional grid operators.
Regulatory Framework and Forward Outlook
Poland's Energy Regulatory Office and the National Centre for Emissions Management administer renewable support mechanisms including auction-based price guarantees and capacity market participation rules that determine project bankability. EU Green Deal alignment through the REPowerEU plan tightens methane leakage standards for biomass and accelerates offshore grid connection timelines. Stakeholders must monitor whether proposed changes to the Ten-Year Network Development Plan resolve substation congestion in Pomerania before committing floating wind investments.
Market Dynamics
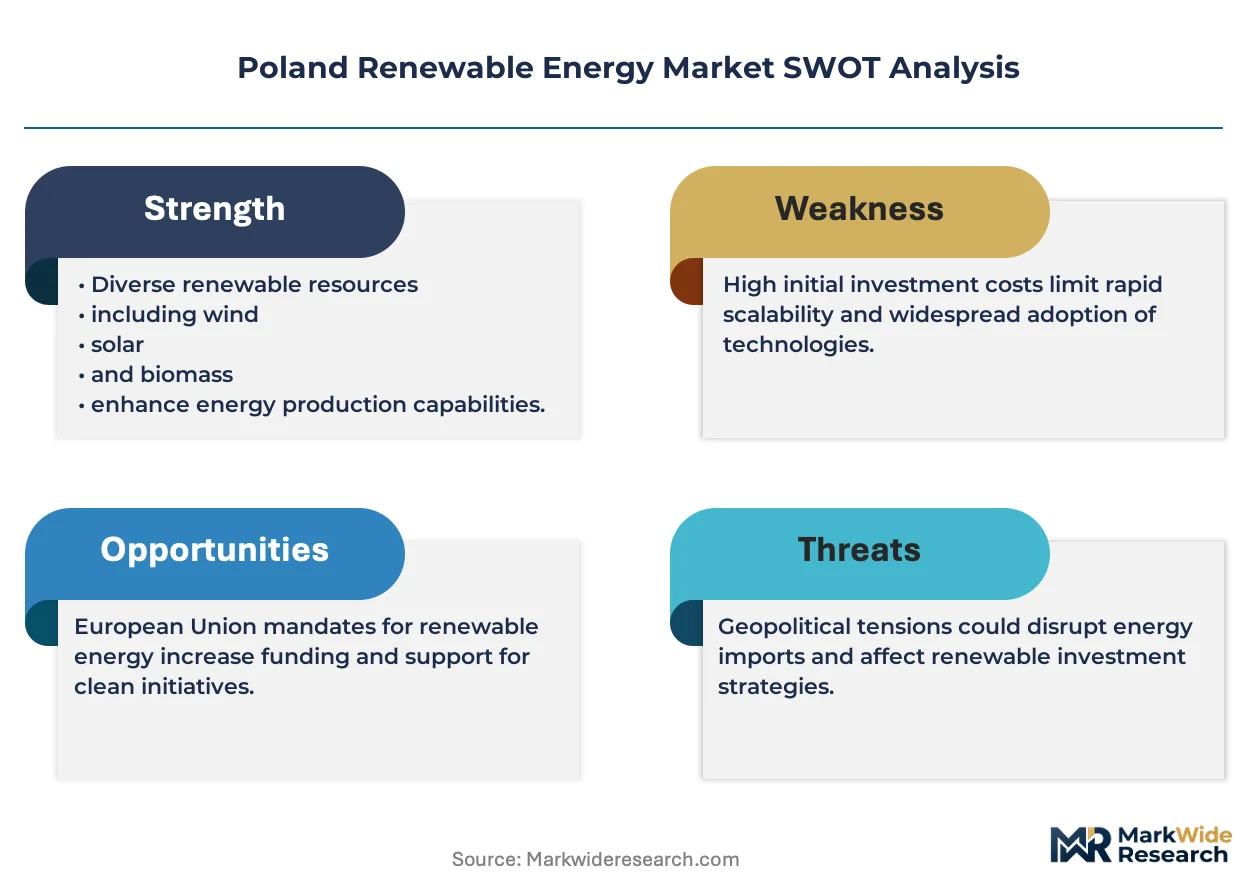
Poland's renewable energy sector is undergoing a capital-structure transformation as offshore wind auctions force domestic utilities and foreign developers to commit multi-billion-zloty equity stakes simultaneously, eroding the traditional balance-sheet advantage of state-backed incumbents.
Growth Catalysts
- Offshore Wind Development Framework:Poland's auction-based price guarantees under the National Centre for Emissions Management create bankable revenue streams for Baltic Sea projects, attracting engineering procurement construction consortia.
- Silesian Solar Cluster:Concentrated developer interest in the Silesian Voivodeship leverages degraded industrial land and existing grid infrastructure to accelerate photovoltaic deployment without greenfield permitting delays.
- Industrial Electrification:Steel and chemical facilities in Upper Silesia are expanding renewable electricity procurement to hedge against EU carbon border adjustment mechanism exposure.
Market Restraints
- Grid Congestion:Substation capacity limits in Pomerania constrain connection timelines for floating wind investments, forcing developers to absorb interconnection upgrade costs.
- Biomass Methane Standards:REPowerEU alignment tightens leakage monitoring requirements for anaerobic digestion facilities, raising operational compliance burdens for agricultural waste projects.
- Turbine Supply Concentration:European nacelle manufacturing capacity bottlenecks extend equipment delivery schedules for 15 MW offshore units beyond original project timelines.
Strategic Opportunities
- Floating Wind in Deep Baltic Waters:Water depths exceeding 60 meters beyond the 25-kilometer coastal zone open acreage for semi-submersible platforms where fixed-bottom foundations prove uneconomical.
- Prosumer Storage Pairing:Net-billing rule refinements enable residential photovoltaic owners to couple battery systems with rooftop generation, shifting evening peak load profiles for distribution system operators.
- Green Hydrogen offtake:Amendments to the Ten-Year Network Development Plan prioritize electrolyzer grid connections, creating anchor demand for curtailed renewable generation in Pomerania and West Pomerania.
Industry Challenges
- Marine Construction Skills Gap:Polish ports lack sufficient jack-up vessel crews and heavy-lift crane operators trained for 15 MW turbine installation sequences, forcing reliance on Danish and German contractors.
- Permitting Timeline Compression:Environmental impact assessments for offshore wind farms face concurrent reviews by maritime administration and regional directorates for environmental protection, creating procedural overlap.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Renewable Energy Market |
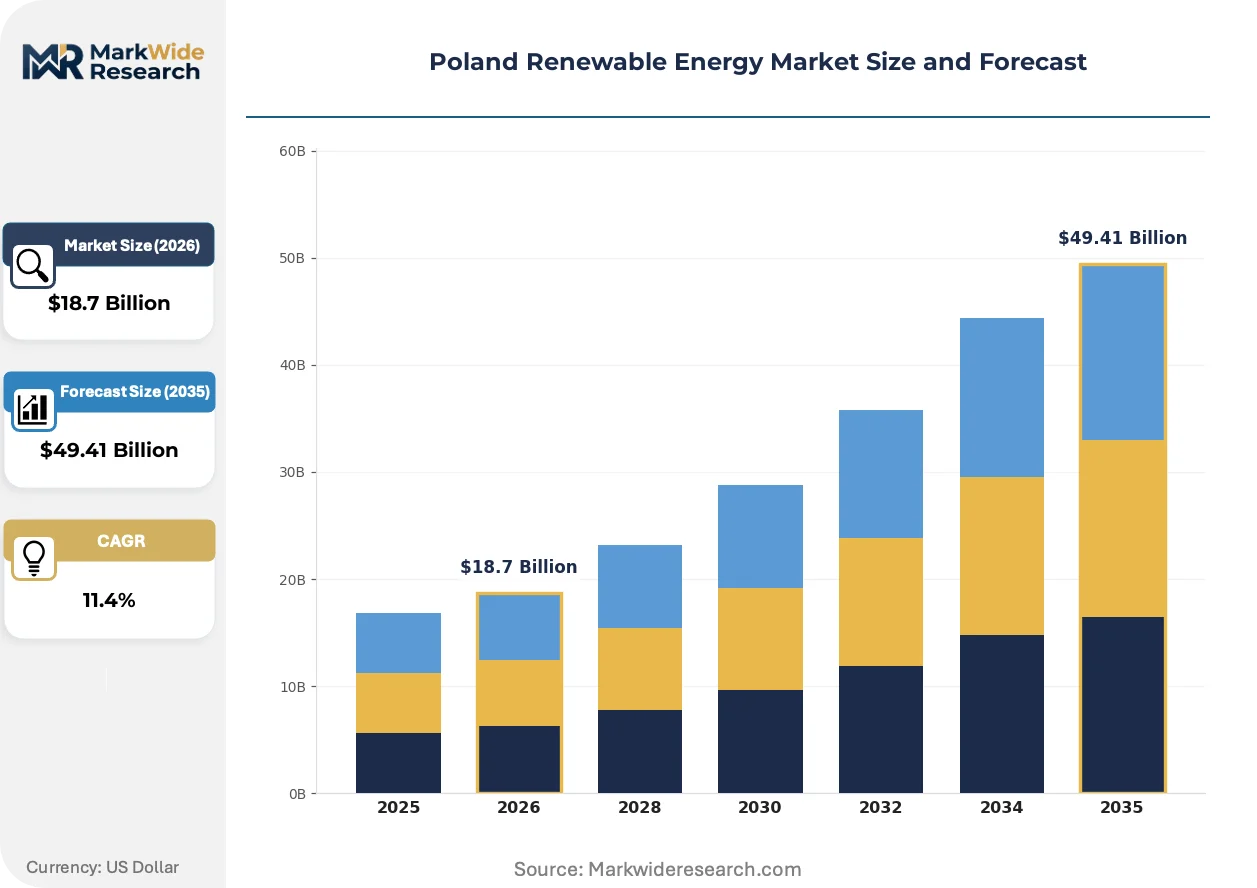
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydro Application: Residential, Commercial, Industrial, Utility End User: Households, Businesses, Government, Agriculture Installation Type: Grid-Tied, Off-Grid, Hybrid, Distributed |
| Companies Covered | PGE Polska Grupa Energetyczna SA, Orlen Synthos Green Energy, Engie SA, Akuo Energy SAS, Tauron Polska Energia SA, RWE Renewables Poland, Ørsted Poland, EDF Renewables Poland, Columbus Energy SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Renewable Energy Market Strategic Shifts
Technology convergence and procurement model evolution are redistributing value capture across Poland's renewable value chain, with distributed generation architectures challenging centralized utility business models.
Bifacial photovoltaic modules with tracking systems are fragmenting project returns across Poland's solar pipeline. Large independent power producers deploy single-axis trackers on agricultural leaseholds in Greater Poland, while industrial self-consumers favor fixed-tilt rooftop systems. This technology divergence is fragmenting engineering procurement construction contract structures and compressing margins for standardized installation crews.
The EU Green Deal's REPowerEU acceleration mechanism is compressing offshore grid connection timelines for Polish Baltic projects. The Energy Regulatory Office must synchronize auction award schedules with transmission system operator build-out programs or face developer penalty claims. Floating substation platforms are emerging as the preferred technical response where seabed conditions delay conventional foundation work.
Corporate power purchase agreements are displacing traditional utility offtake for Polish industrial consumers. Steelmakers in Katowice and chemical processors in Płock now contract directly with renewable developers, bypassing incumbent retail suppliers. This channel disintermediation concentrates credit risk assessment burdens on developer balance sheets and is most visible in the Silesian and Łódź Voivodeships where industrial load density supports bilateral contracting scale.
Poland Renewable Energy Market Segmentation
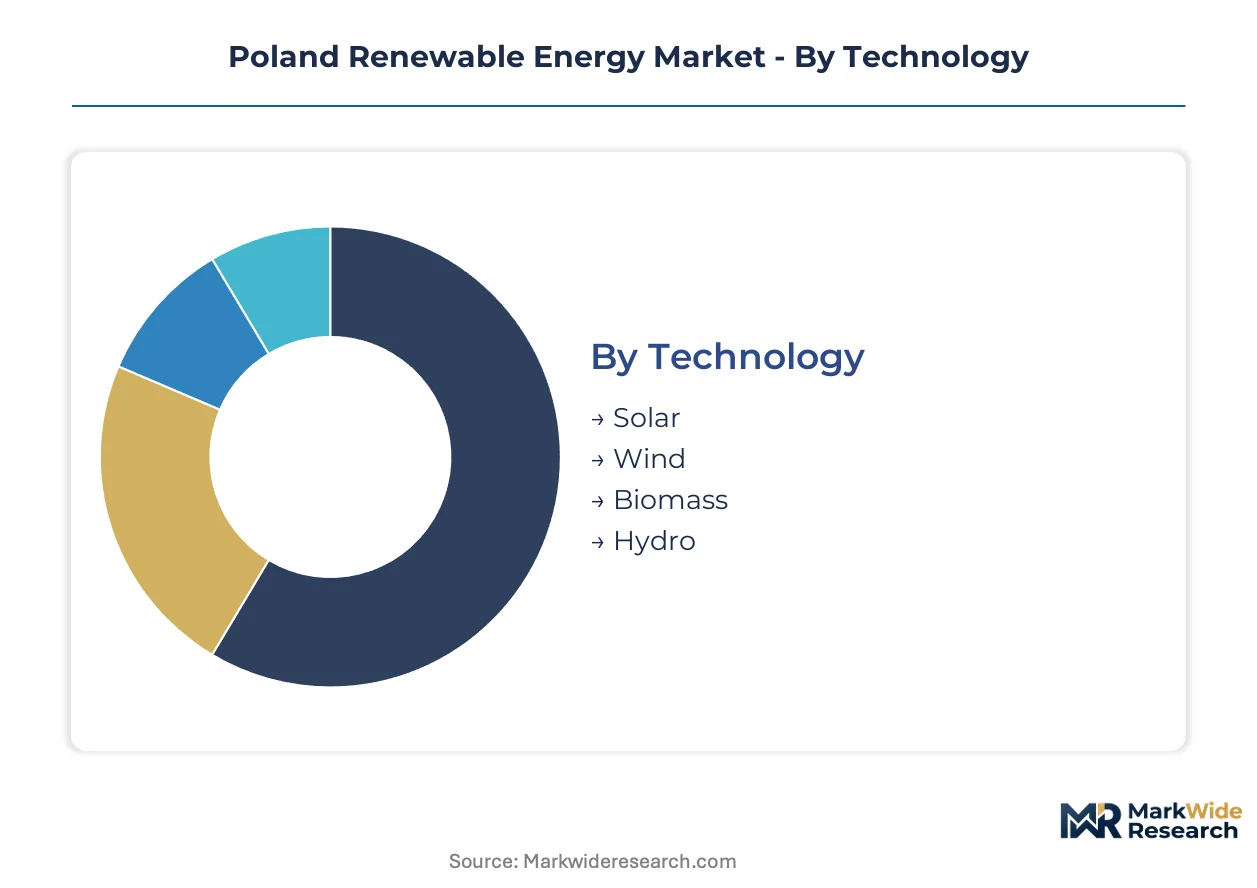
Technology choices in Poland's renewable energy sector determine capital deployment patterns and regulatory exposure across divergent auction mechanisms. Application and end-user segmentation reveals how industrial electrification and prosumer adoption are fragmenting traditional utility procurement channels.
Technology:
Margin pools concentrate in offshore wind development where auction-based price guarantees attract multi-billion-zloty commitments, while solar photovoltaic benefits from collapsing module costs and streamlined permitting.
- Solar:Photovoltaic modules rated at 400-600 Wp dominate incremental capacity additions through falling equipment prices and prosumer net-billing rules. Demand concentrates in the Silesian Voivodeship where degraded industrial land accelerates deployment without greenfield delays.
- Wind:Offshore turbines scaling toward 15 MW rated capacity anchor long-term capital deployment despite extended permitting timelines. Baltic Sea projects attract engineering procurement construction consortia under the National Centre for Emissions Management auction framework.
- Biomass:Organic combustion and anaerobic digestion systems serve agricultural waste streams and district heating networks. REPowerEU alignment tightens methane leakage monitoring requirements, raising compliance burdens for facility operators.
- Hydro:Run-of-river and small reservoir installations provide baseload renewable generation with limited expansion potential due to river basin constraints.
The dominant share belongs to Solar, while Wind is closing the gap fastest through Baltic Sea auction awards.
Application:
Customer scale determines financing access and contract structures, with utility-scale projects commanding institutional capital pools while distributed segments fragment procurement across regional grid operators.
- Industrial:Steel and chemical facilities in Upper Silesia expand renewable electricity procurement to hedge against EU carbon border adjustment mechanism exposure. Corporate power purchase agreements in Katowice and Płock bypass incumbent retail suppliers.
- Utility:Grid-scale installations attract the deepest financing pools through auction-based price guarantees administered by the Energy Regulatory Office. Transmission system operator build-out programs must synchronize with award schedules to avoid developer penalty claims.
- Residential:Prosumer rooftop systems leverage net-billing rule refinements to couple battery storage with photovoltaic generation. Evening peak load profiles shift for distribution system operators as storage pairing expands.
- Commercial:Mid-scale installations on industrial and retail properties balance self-consumption economics with residual grid export revenues.
Utility applications command the largest capital flows, though Industrial procurement is expanding most quickly through direct bilateral contracting.
End User:
Customer type shapes technology preferences and regulatory engagement intensity, with agricultural operators facing distinct biomass compliance burdens compared to urban household adopters.
- Households:Residential adopters drive distributed generation growth through rooftop photovoltaic installations and battery storage pairing enabled by net-billing refinements.
- Businesses:Industrial and commercial enterprises in the Silesian and Łódź Voivodeships leverage load density to support corporate power purchase agreement scale.
- Government:Public sector procurement supports municipal renewable targets and district heating decarbonization through biomass and solar thermal investments.
- Agriculture:Farm operators deploy anaerobic digestion facilities for agricultural waste processing while navigating tightened methane leakage standards under REPowerEU alignment.
Businesses capture the dominant procurement volume, while Agriculture presents the steepest regulatory compliance trajectory.
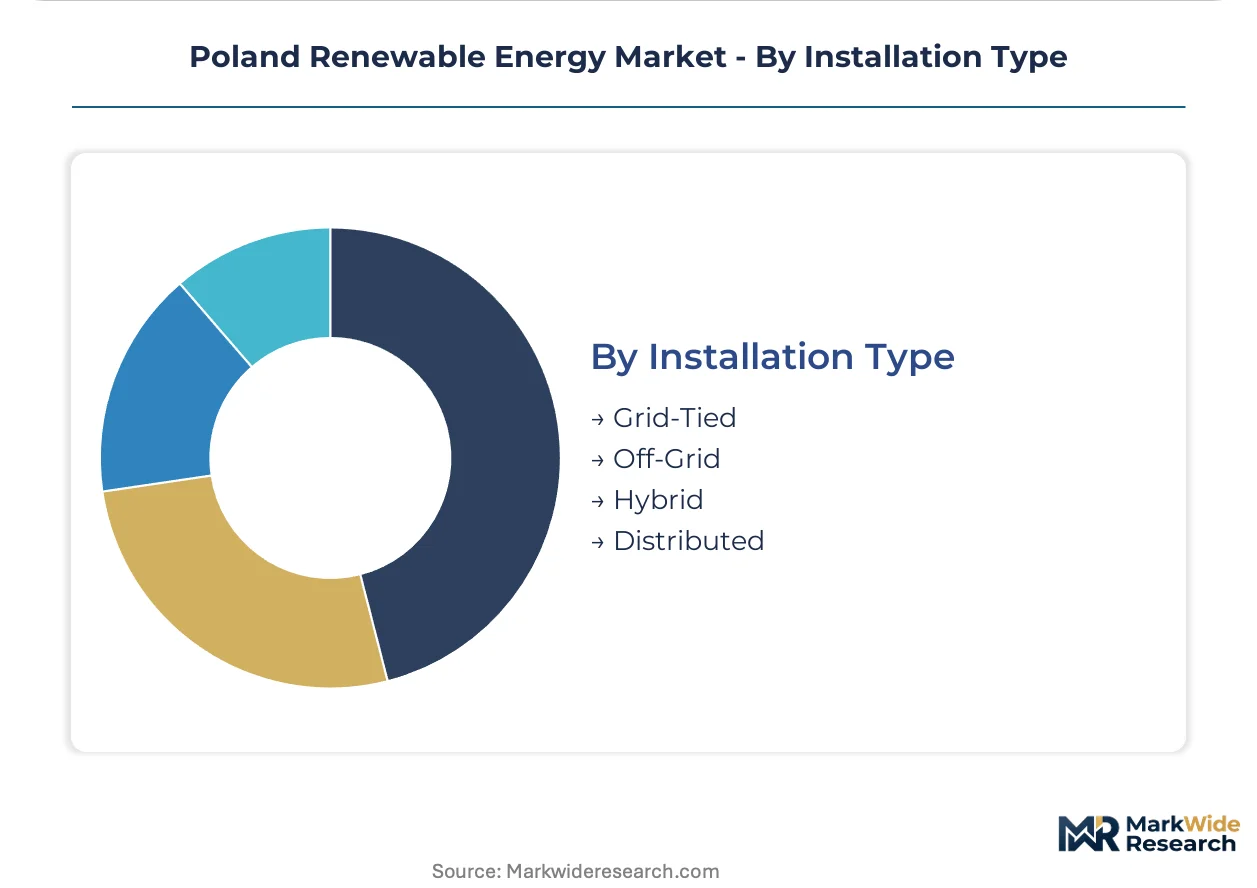
Installation Type:
Grid connection architecture determines revenue streams and operational autonomy, with hybrid and distributed systems challenging centralized utility business models.
- Grid-Tied:Utility-scale and prosumer installations feed electricity into distribution networks under net-billing or auction-based remuneration schemes. Substation congestion in Pomerania constrains connection timelines for floating wind investments.
- Distributed:Behind-the-meter generation fragments procurement patterns across regional grid operators as industrial self-consumers and residential prosumers bypass traditional retail channels.
- Hybrid:Solar-plus-storage and wind-plus-hydrogen configurations prioritize electrolyzer grid connections under amendments to the Ten-Year Network Development Plan.
- Off-Grid:Remote industrial and agricultural installations operate independently where grid extension proves uneconomical.
Grid-Tied installations retain the dominant share, though Distributed generation is gaining share fastest through prosumer adoption and corporate self-consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Upper Silesia demonstrate the highest price elasticity, procuring renewables primarily to hedge carbon border adjustment exposure, while Baltic Sea developers absorb premium costs for grid certainty under state auction guarantees.
Masovian Voivodeship
Warsaw's corporate headquarters concentrate power purchase agreement origination for national industrial portfolios. The Energy Regulatory Office administers auction schedules that synchronize with transmission build-out timelines. National grid operator PSE maintains control room operations in Konstancin-Jeziorna, coordinating offshore connection schedules with Baltic Sea developers.
Silesian Voivodeship
Steel and chemical facilities in Katowice and Gliwice expand direct renewable contracting to manage EU carbon border adjustment mechanism liabilities. Degraded post-industrial land accelerates photovoltaic deployment without greenfield permitting delays. The metropolitan area anchors Poland's highest density of corporate power purchase agreements, bypassing traditional retail suppliers.
Pomeranian Voivodeship
Gdańsk and Gdynia ports host jack-up vessel staging for 15 MW turbine installation sequences across Baltic Sea lease areas. Floating wind investments confront substation congestion constraints that force developers to absorb interconnection upgrade costs. The National Centre for Emissions Management processes environmental impact assessments concurrently with maritime administration reviews.
West Pomeranian Voivodeship
Szczecin anchors supply chain logistics for offshore construction equipment moving into Baltic lease zones. Amendments to the Ten-Year Network Development Plan prioritize electrolyzer grid connections, creating anchor demand for curtailed renewable generation. The voivodeship borders German offshore zones, enabling cross-border contractor mobility for specialized marine construction crews.
Łódź Voivodeship
Textile and automotive component manufacturers in the central industrial corridor leverage load density to support bilateral renewable contracting scale. The region lacks native renewable resources, driving procurement from wind and solar assets in neighboring voivodeships. Industrial electrification investments concentrate in Pabianice and Zgierz manufacturing clusters seeking cost hedging against fossil fuel volatility.
Poland Renewable Energy Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Poland's renewable sector, with offshore wind development demanding Danish and German marine construction expertise while domestic utilities leverage balance sheet scale for auction participation. State-backed incumbents and agile private developers now face equivalent capital intensity requirements as multi-billion-zloty commitments erode traditional financing advantages. Three archetypes dominate: integrated utilities anchoring large-scale Baltic projects, foreign developers transferring parent-company technical capabilities, and specialized photovoltaic installers capturing distributed generation margins. Competitive moves concentrate on strategic partnerships for engineering procurement construction consortia and portfolio diversification into hybrid storage configurations.
Within the integrated utility tier, PGE Polska Grupa Energetyczna SA and Tauron Polska Energia SA represent state-backed incumbents leveraging balance sheet capacity to anchor auction-backed offshore developments. Among foreign developers with parent-company technical transfer, RWE Renewables Poland and Ørsted Poland exemplify the archetype of deploying German and Danish offshore construction expertise against domestic players with shallower marine experience. Columbus Energy SA occupies a position among specialized photovoltaic developers capturing distributed generation opportunities in the Silesian solar cluster.
| Leading Market Players |
|---|
| PGE Polska Grupa Energetyczna SA |
| Orlen Synthos Green Energy |
| Engie SA |
| Akuo Energy SAS |
| Tauron Polska Energia SA |
| RWE Renewables Poland |
| Ørsted Poland |
| EDF Renewables Poland |
| Columbus Energy SA |
| Others |
Value Chain & Pricing Dynamics
15 MW turbine manufacturing scale economies concentrate nacelle assembly in Denmark and Germany, compressing price floors for Polish Baltic projects while elevating balance-sheet thresholds for auction participation. This scale dynamic concentrates supply-side leverage among parent-company technical transfer players and fragments margin capture for domestic developers lacking captive component sourcing.
Pricing Analysis
After-sales service contracts and extended O&M agreements drive lifetime value for offshore wind assets, with revenue stratifying across premium-mid-economy tiers based on turbine availability guarantees and component replacement coverage. Price differentiation hinges on certification grade from DNV and Germanischer Lloyd plus geographic delivery cost from Baltic port staging. Cost compression in utility-scale solar intensifies because collapsing module prices from Chinese manufacturers erode developer margins. Industrial offtakers in Upper Silesia demonstrate highest price sensitivity through corporate power purchase agreement negotiations, while state-backed utilities absorb premium pricing for auction-backed revenue certainty.
Supply Chain Analysis
Just-in-time inventory strategies dominate photovoltaic deployment where module price volatility discourages strategic stockpiling, contrasting with offshore wind's strategic-stockpile preference for foundation steel and array cables given 18-month manufacturing lead times. Component sourcing draws from China for photovoltaic modules, Denmark and Germany for offshore nacelles, and Poland for balance-of-system electrical infrastructure. Raw material dependencies encompass polysilicon ingots, rare-earth permanent magnets, and high-voltage submarine cable copper. Single-source vulnerability concentrates in European jack-up vessel availability for turbine installation sequences. Distribution runs through Gdańsk and Szczecin port logistics hubs serving Baltic Sea lease zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's renewable energy sector represents a high-growth disruption as offshore wind auctions force capital-structure parity between state incumbents and foreign developers, with REPowerEU acceleration compressing grid connection timelines as the critical regulatory inflection.
For Market Incumbents: Shield auction-backed project pipelines by securing early-mover grid connection reservations in Pomerania before floating wind substation congestion intensifies. Consolidate balance-sheet capacity through joint venture structures with Danish marine construction contractors to close the jack-up vessel crew gap. Vertical integration into electrolyzer offtake agreements anchors demand for curtailed generation and defends against corporate power purchase agreement channel disintermediation. For New Entrants and Emerging Players: Lead with prosumer storage pairing solutions in the Silesian Voivodeship where net-billing rule refinements create immediate addressable market expansion. Target degraded industrial land solar development to bypass greenfield permitting delays that constrain utility-scale competitors. Deploy direct sales channels to residential adopters rather than competing for utility auction slots where multi-billion-zloty commitments erect barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized photovoltaic developers with distributed generation footprints over capital-intensive offshore wind pure-plays facing supply chain bottlenecks. Long-term viability concentrates in hybrid configuration capabilities spanning solar-plus-storage and wind-plus-hydrogen architectures. Acquisition targets should demonstrate operational electrolyzer grid connection priority under Ten-Year Network Development Plan amendments. Watch floating wind permitting timeline compression as the signal indicating whether Pomeranian substation congestion resolves or persists as capital absorption risk.| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | Baltic Sea auction awards under National Centre for Emissions Management frameworks anchor multi-billion-zloty capital deployment. |
| Corporate Power Purchase Agreement Expansion | Direct contracting between Silesian steelmakers and renewable developers bypasses incumbent retail supplier channels. |
| Prosumer Storage Technology Licensing | Net-billing refinements enable battery pairing that shifts evening peak load profiles for Polish distribution operators. |
| Backward Integration into Electrolyzer Manufacturing | Green hydrogen offtake amendments prioritize grid connections for curtailed renewable generation in West Pomerania. |
| Floating Wind Certification Program | Semi-submersible platform standards unlock deep-water Baltic acreage beyond 25-kilometer coastal zones. |
Study Parameters
Desk research of EU Green Deal implementation documents, Polish Energy Regulatory Office auction schedules, and REPowerEU methane standard amendments preceded structured interviews with offshore wind project developers, photovoltaic EPC contractors, utility planning officers, and industrial procurement leads at Upper Silesia steel facilities. Secondary validation drew from transmission system operator build-out disclosures, National Centre for Emissions Management auction result databases, and port authority logistics records from Gdańsk and Szczecin. Bottom-up project pipeline aggregation triangulated against top-down capacity target assessments from Polish ministry planning documents.
Variance decomposition across technology segments, application scales, and voivodeship-level grid constraints shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompass fuel source differentiation between solar, offshore wind, biomass and hydro; generation capacity tier from residential prosumer to utility-scale; and regulatory framework exposure across auction-backed, corporate PPA, and net-billing remuneration structures. CAGRs derived from installed capacity build-out trajectories, equipment cost curves, and offtake contract pricing trends. Industry-specific forecast inputs incorporated Baltic Sea water depth measurements for floating wind technical potential and Silesian degraded land availability for solar deployment acceleration.
Forecasts assume regulatory continuity in EU Green Deal alignment and Polish offshore wind auction mechanisms; material policy shifts such as REPowerEU methane standard enforcement escalation or Ten-Year Network Development Plan grid investment delays would require re-modeling. Specific risk factors encompass substation congestion resolution timelines in Pomerania, European nacelle manufacturing capacity expansion rates, and jack-up vessel crew training program throughput. Revision becomes warranted when floating wind environmental impact assessment procedural overlap exceeds concurrent review capacity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
East Asia Renewable Energy Market