
 Philippines Power Generation EPC Market | 2026-2036
Philippines Power Generation EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Power Generation EPC Market Analytics
Steel-reinforced concrete foundations for turbine pedestals is shifting toward higher-grade composite anchoring systems that reduce civil works duration and seismic retrofit costs. Aboitiz Power Corporation leverages its captive construction arm to compress project timelines across Mindanao. San Miguel Global Power anchors its bidding strategy through backward integration into LNG terminal development. First Gen Corporation specializes in geothermal EPC execution where subsurface drilling expertise creates technical barriers to rival entry.
Philippines Power Generation EPC encompasses the engineering, procurement, and construction of electricity generation facilities, requiring turbine alignment tolerances within 0.05 millimeters per meter and concrete curing protocols that withstand tropical cyclone loading. The primary purpose is delivering turnkey power assets that interconnect with the National Grid Corporation of the Philippines transmission system under performance-guaranteed contracts. Solar and wind technology segments attract the majority of new capacity awards as feed-in-tariff eligibility windows close. Above 100 MW power capacity projects dominate capital deployment though distributed below-10 MW installations grow fastest in off-grid island configurations. Government client type procurements through the Department of Energy's competitive selection process concentrate margin pools in pre-development and permitting phases.
The Department of Energy enforces the Renewable Energy Law of 2008 through mandated renewable portfolio standards that reshape utility procurement calendars. The Energy Regulatory Commission governs cost recovery mechanisms under performance-based ratemaking that influences EPC contractor risk allocation in build-own-operate structures. BIS-equivalent Philippine construction standards and local content requirements under the Build-Operate-Transfer Law constrain foreign contractor market access. Stakeholders must monitor interconnection queue congestion at NGCP substations and calibrate development timelines against transmission upgrade schedules.
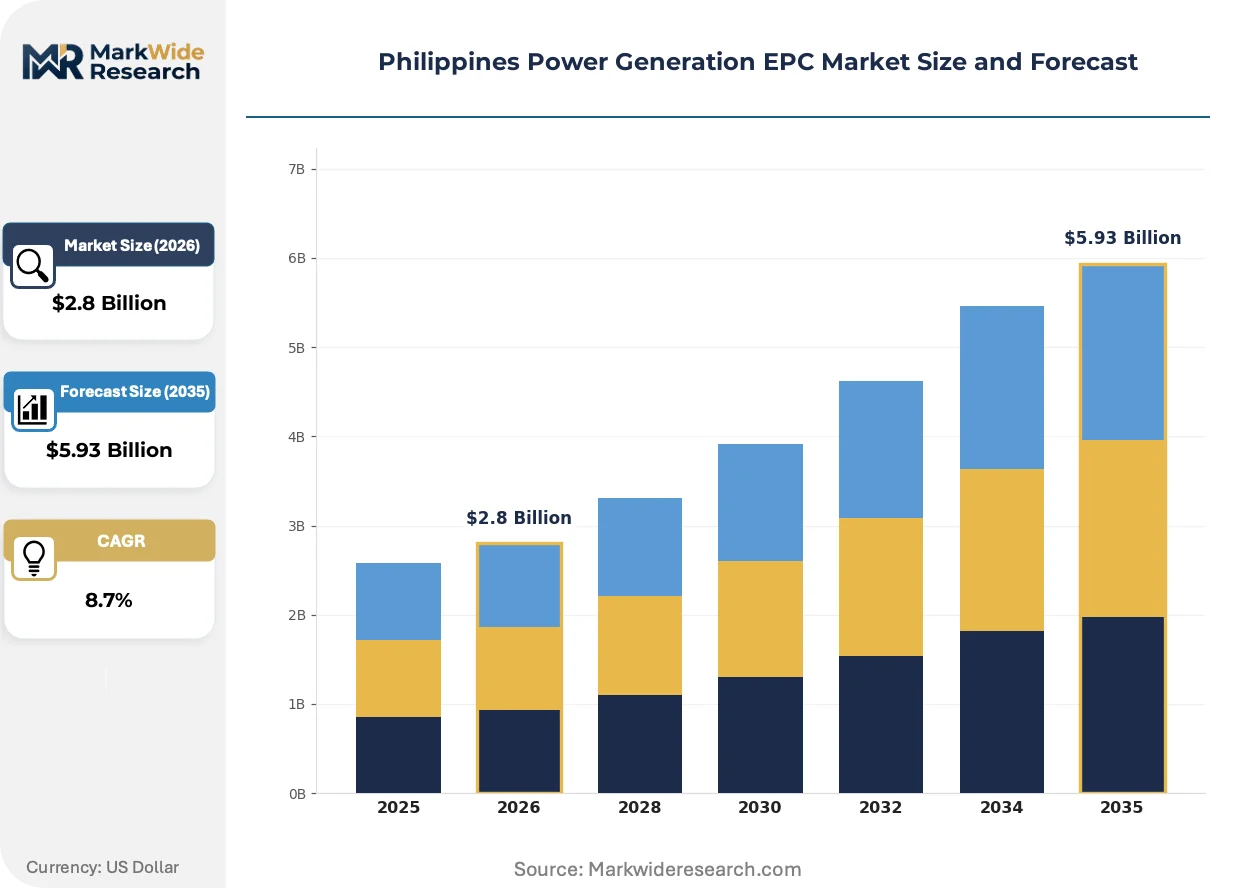
Market Dynamics
The Renewable Energy Law of 2008 mandates minimum renewable portfolio standards that force utilities to accelerate procurement of clean capacity, compressing traditional fossil-fuel project timelines while LNG terminal development in Batangas province anchors combined-cycle gas turbine demand.
Growth Catalysts
- Feed-in-Tariff Windows:Closing eligibility deadlines for solar and wind projects are pulling forward utility procurement calendars and concentrating EPC awards in renewable technology segments.
- Batangas LNG Hub:Multiple liquefied natural gas terminal projects in this province are anchoring new power park development and driving combined-cycle gas turbine installation demand.
- Performance-Based Ratemaking:The Energy Regulatory Commission's cost recovery mechanisms under this framework are reshaping contractor risk allocation in build-own-operate structures.
Market Restraints
- Interconnection Queue Congestion:NGCP substation capacity constraints are forcing developers to calibrate timelines against transmission upgrade schedules, delaying project energization.
- Local Content Requirements:Build-Operate-Transfer Law mandates constrain foreign contractor market access and limit technology transfer flexibility in specialized equipment procurement.
- Seismic Retrofit Costs:Tropical cyclone loading requirements for concrete curing protocols are elevating foundation engineering costs above regional benchmarks.
Strategic Opportunities
- Off-Grid Island Configurations:Distributed below-10 MW installations in archipelago locations represent the fastest-growing deployment segment outside Luzon-Visayas grid connectivity.
- Composite Anchoring Systems:Higher-grade materials for turbine pedestals are reducing civil works duration and creating differentiation for specialized foundation contractors.
- Geothermal Subsurface Expertise:Drilling capabilities in volcanic terrain create technical barriers that specialized EPC firms can leverage for margin protection.
Industry Challenges
- Turbine Alignment Tolerances:Precision requirements within 0.05 millimeters per meter demand specialized craft labor pools that remain shallow in the domestic market.
- Permitting Phase Concentration:Government competitive selection processes through the Department of Energy compress margin pools into pre-development activities with extended capital lockup periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Power Generation EPC Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Hydro, Biomass Installation Type: Onshore, Offshore, Distributed, Centralized Power Capacity: Up to 10 MW, 11-50 MW, 51-100 MW, Above 100 MW Client Type: Government, Private Sector, Utilities, Independent Power Producers |
| Companies Covered | ACEN Corporation, UPC Renewables, Aboitiz Power Corporation, AECOM, JGC Philippines Inc., San Miguel Global Power, Black & Veatch Corp., Fluor Corporation, First Gen Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Power Generation EPC Market Evolving Landscape
Digital twin modeling and modular construction methods are compressing project delivery schedules while regulatory pressure on carbon intensity is rewriting fuel technology preferences across the development pipeline.
Composite anchoring systems for steel-reinforced concrete foundations are rewriting civil construction economics in combined-cycle gas turbine installations. EPC contractors deploying these materials in Batangas power parks are reducing seismic retrofit contingencies by half. The technology is compressing foundation curing cycles from twenty-eight days to fourteen days in tropical humidity conditions.
The Department of Energy's enforcement of renewable portfolio standards under the 2008 law is mandating utility procurement minimums that reshape capacity award calendars. Industrial load centers in Luzon must now source specified percentages from qualifying renewable technologies or face supply license penalties. Solar and wind EPC segments are capturing disproportionate developer attention as fossil-fuel project queues face regulatory deprioritization.
Buyer concentration among integrated energy conglomerates with captive construction arms is consolidating award decisions around vertically structured procurement. Independent developers without backward integration into LNG terminal or equipment supply chains are finding bid competitiveness eroded. Mindanao-based load growth is exhibiting this pattern most acutely as Aboitiz Power Corporation leverages in-house execution capabilities to compress rival timelines.
Philippines Power Generation EPC Market Segmentation
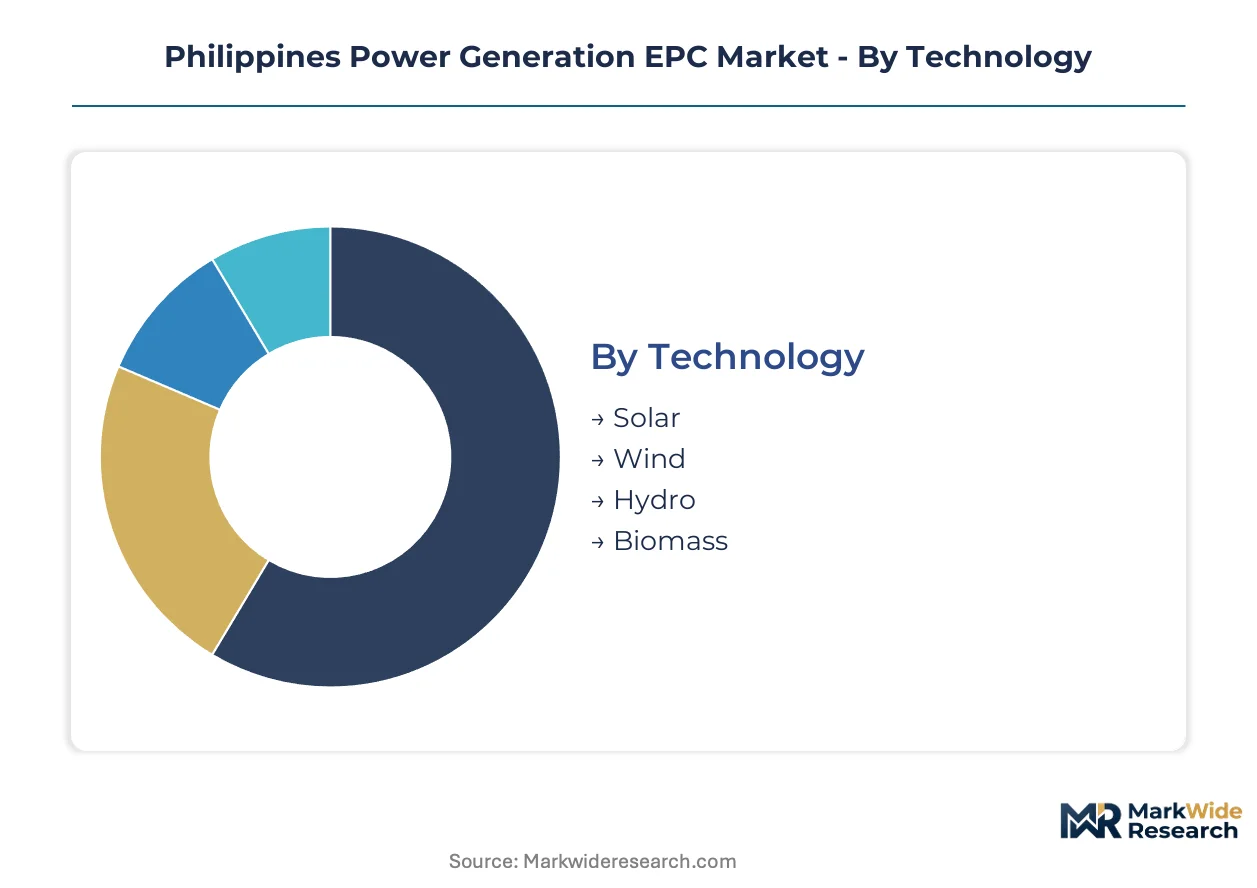
Technology choices determine foundation engineering specifications and interconnection protocols across Philippine archipelago development. Installation configuration dictates labor mobilization strategies and equipment logistics for EPC contractors. Power capacity thresholds trigger distinct regulatory pathways under Department of Energy competitive selection processes.
Technology:
Standardization dominates solar and wind with modular equipment packages, while geothermal and hydro demand bespoke subsurface engineering that fragments contractor specialization.
- Solar:Photovoltaic module mounting systems with fixed-tilt or tracking configurations dominate procurement volumes. Batangas and Luzon industrial zones concentrate utility-scale awards as feed-in-tariff windows compress development calendars.
- Wind:Horizontal-axis turbine installations require specialized marine logistics for nacelle delivery across island supply chains. Ilocos Norte and Rizal province anchor onshore development where wind resource mapping has matured.
- Hydro:Run-of-river configurations predominate given the country's mountainous terrain and distributed watersheds.
- Biomass:Agricultural residue-to-energy systems cluster around sugar milling and rice processing facilities in Negros and Mindanao.
Leading the category by volume: Solar. Expanding most quickly: Wind.
Installation Type:
Cost tier separation runs from offshore marine infrastructure at premium pricing through distributed below-10 MW systems with standardized balance-of-plant packages.
- Onshore:Ground-mounted turbine and solar array construction on terrestrial sites with established road access. Luzon load centers concentrate demand where NGCP interconnection capacity constrains queue progression.
- Offshore:Floating or fixed-bottom marine foundations requiring specialized jack-up vessels and corrosion-resistant substructures. No operational projects exist though pre-development studies target Batangas and Mindoro Strait locations.
- Distributed:Below-10 MW configurations serving isolated island grids or industrial captive demand.
- Centralized:Single-point large-scale generation with dedicated transmission substations.
Dominant by capital deployment: Onshore. Gaining share fastest: Distributed.
Power Capacity:
Application scale determines procurement channel — government competitive selection for above-100 MW assets versus bilateral contracting for sub-10 MW distributed systems.
- Above 100 MW:Utility-scale baseload and intermediate capacity requiring full environmental impact assessment and Department of Energy approval. Batangas combined-cycle gas turbine parks and Luzon solar farms concentrate EPC award values in this bracket.
- 51-100 MW:Mid-scale assets serving provincial load centers with simplified permitting under renewable energy law provisions. Mindanao electrification programs drive procurement concentration.
- 11-50 MW:Commercial and industrial direct supply configurations.
- Up to 10 MW:Mini-grid and rural electrification projects with fast-track registration.
Capturing majority capital: Above 100 MW. Climbing the fastest: Up to 10 MW.
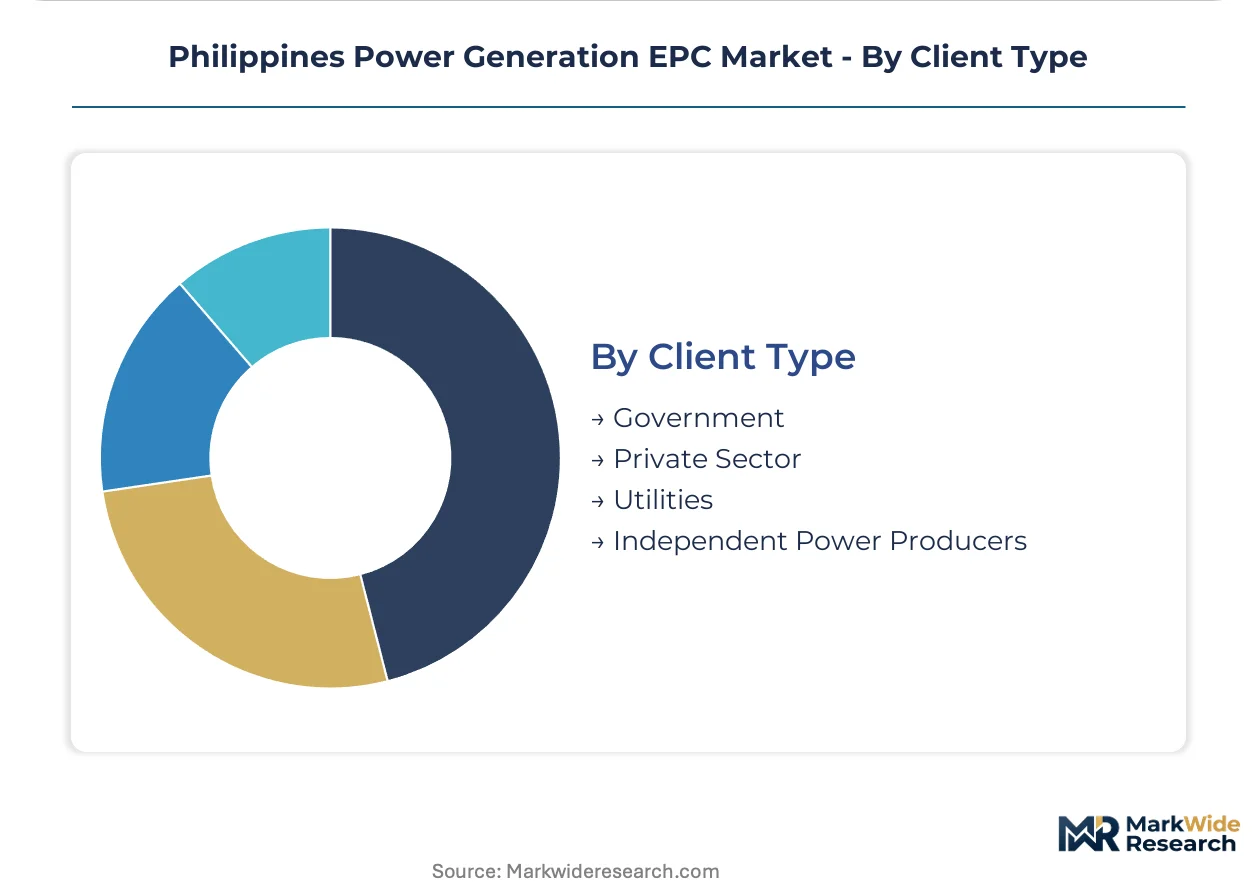
Client Type:
Customer type shapes risk allocation — government procurements concentrate margin in pre-development phases while private sector awards emphasize construction execution certainty.
- Government:Department of Energy competitive selection process mandates with performance-guaranteed contracts and local content requirements. Transmission interconnection subsidies and sovereign guarantees compress financing spreads.
- Private Sector:Industrial load centers and commercial offtakers procuring captive generation under bilateral power purchase agreements. Mining and data center operators in Cebu and Pampanga drive demand concentration.
- Utilities:Manila Electric Company and provincial cooperatives fulfilling renewable portfolio standard obligations.
- Independent Power Producers:Merchant developers bidding into wholesale electricity spot market or securing anchor offtake contracts.
Commanding award volume: Government. Steepest expansion trajectory: Private Sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Load growth concentrates in Luzon industrial zones where Batangas province anchors liquefied natural gas terminal development. The Department of Energy's renewable portfolio standards reshape procurement calendars across archipelago markets. Regional execution capabilities vary sharply between grid-connected load centers and off-grid island configurations.
Luzon
Industrial load centers in Batangas and Cavite drive combined-cycle gas turbine demand anchored by LNG terminal projects. The Department of Energy's competitive selection process concentrates government procurement in this corridor. NGCP interconnection queue congestion at substations forces developers to calibrate timelines against transmission upgrade schedules.
Visayas
Cebu and Iloilo host commercial and industrial captive generation demand from mining and data center operators. The Energy Regulatory Commission's performance-based ratemaking influences contractor risk allocation in build-own-operate structures. Negros island anchors biomass EPC activity around sugar milling facilities.
Mindanao
Aboitiz Power Corporation leverages its captive construction arm to compress project timelines across this load growth frontier. The Renewable Energy Law of 2008 mandates accelerate utility procurement of qualifying clean capacity. Davao and Cagayan de Oro concentrate mid-scale asset development under simplified permitting provisions.
Off-Grid Islands
Distributed below-10 MW installations represent the fastest-growing deployment segment outside main grid connectivity. Fast-track registration under renewable energy law provisions enables rapid project energization. Palawan and Mindoro configurations lead mini-grid and rural electrification procurement.
Philippines Power Generation EPC Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy conglomerates consolidating award decisions around vertically structured procurement. Independent developers without backward integration into LNG terminal or equipment supply chains face eroded bid competitiveness. Three archetypes dominate: captive construction arms of integrated utilities, international engineering firms with local partnerships, and specialized geothermal subsurface contractors. Competitive moves center on pre-development phase concentration and composite anchoring system differentiation for foundation engineering.
Within the integrated utility tier, Aboitiz Power Corporation and San Miguel Global Power exemplify vertical execution strategies that compress rival timelines through in-house capabilities. First Gen Corporation occupies a specialized position in geothermal EPC where subsurface drilling expertise creates technical barriers. These three Philippine-based entities anchor competitive positioning against international entrants including AECOM, JGC Philippines, Black & Veatch, and Fluor Corporation.
| Leading Market Players |
|---|
| ACEN Corporation |
| UPC Renewables |
| Aboitiz Power Corporation |
| AECOM |
| JGC Philippines Inc. |
| San Miguel Global Power |
| Black & Veatch Corp. |
| Fluor Corporation |
| First Gen Corporation |
| Others |
Value Network & Pricing Analysis
Specialized turbine alignment craft labor pools concentrated in Batangas and Cavite provinces drive labor-cost differentials that widen pricing-tier spreads between premium precision-contractors and economy-tier generalists. The Department of Energy's local content requirements under the Build-Operate-Transfer Law amplify these spreads by constraining foreign contractor market access and compressing domestic skilled labor availability.
Pricing Analysis
Volume-margins split sharply across project tiers: above-100 MW utility-scale assets command premium pricing for performance-guaranteed contracts with extended warranty terms, while below-10 MW distributed installations compete on standardized balance-of-plant packages with thin execution margins. Price differentiation hinges on precision certification tiers (turbine alignment tolerances within 0.05 millimeters per meter) and vertical integration depth into LNG terminal development. Pricing pressure stems from buyer concentration among integrated energy conglomerates with captive construction arms that internalize margin pools. Industrial load centers in Luzon exhibit highest price sensitivity due to procurement volume leverage, while off-grid island mini-grids show lowest sensitivity given limited contractor alternatives.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale combined-cycle gas turbine demand anchored by Batangas LNG terminal projects, while distributor-mediated procurement serves distributed solar and wind configurations across archipelago locations. Geographic supply concentration centers on China for photovoltaic modules and inverters, South Korea for precision turbine components, and Japan for advanced composite anchoring systems. Raw material dependencies include high-grade steel for turbine pedestals, copper for generator windings, and specialized concrete admixtures for tropical cyclone-resistant curing protocols. Supply chain risk concentrates in single-source vulnerability for precision alignment instrumentation and marine logistics capacity for nacelle delivery across island chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines Power Generation EPC Market operates as a supply-constrained environment where shallow domestic craft labor pools for precision turbine alignment prop pricing power toward contractors with verified capability certification.
For Market Incumbents: Extend foundation engineering differentiation through composite anchoring system deployment to compress civil works duration and capture seismic retrofit value pools. Deepen backward integration into LNG terminal development to mirror San Miguel Global Power's bidding strategy and defend margin position against emerging international engineering firms with local partnership structures. Prioritize pre-development phase concentration where Department of Energy competitive selection processes anchor margin pools. For New Entrants and Emerging Players: The 40-60% price-point gap between premium precision-contractors and economy-tier generalists in distributed below-10 MW configurations opens white-space targeting for modular construction specialists. Off-grid island mini-grids in Palawan and Mindoro represent the most penetrable geography given fast-track registration under renewable energy law provisions and limited incumbent presence. Pursue technology licensing partnerships with Chinese photovoltaic module suppliers to establish cost-competitive positioning without capital-intensive manufacturing footprint. For Investors and Strategic Acquirers: Re-rating potential sits with specialized geothermal subsurface contractors given First Gen Corporation's demonstrated margin protection through volcanic terrain drilling capabilities and regulatory-mandated renewable portfolio standard procurement acceleration. Long-term viability favors acquisition targets with captive construction arm integration or exclusive equipment supply relationships that compress rival bid timelines. Monitor NGCP interconnection queue clearance rates as the critical inflection signal for project energization velocity and working capital cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Anchoring System Deployment | Reduces Batangas power park foundation curing cycles from twenty-eight days to fourteen days. |
| Backward Integration into LNG Terminals | Mirrors San Miguel Global Power's vertical execution strategy for bid competitiveness. |
| Geothermal Subsurface Capability Buildout | Creates technical barriers in volcanic terrain where First Gen Corporation dominates. |
| Off-Grid Island Mini-Grid Expansion | Captures fastest-growing deployment segment through Palawan and Mindoro fast-track registration. |
| Renewable Portfolio Standard Compliance Positioning | Aligns with Department of Energy enforcement timelines reshaping utility procurement calendars. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators provided execution-grounded validation. Secondary sources included Department of Energy competitive selection process documentation, Energy Regulatory Commission ratemaking filings, NGCP interconnection queue databases, and project development tracking systems. Bottom-up project pipeline aggregation and top-down macroeconomic demand modeling were triangulated to constrain forecast variance.
Granularity-level modeling distinguished fuel source, generation capacity tier, and regional grid type across the projection horizon. Technology segments were modeled at equipment-package level with distinct foundation engineering specifications and interconnection protocols. CAGRs were derived from project award velocity analysis and capital deployment tracking throughout the forecast period. Key inputs included feed-in-tariff eligibility window closure schedules, Batangas LNG terminal commissioning timelines, and NGCP transmission upgrade sequencing.
Inputs from Department of Energy filings and NGCP interconnection databases were available through the study window; gaps in real-time project cost disclosure and contractor margin reporting introduce uncertainty bands around price-tier estimates. Forecasts reflect base-case assumptions regarding regulatory enforcement continuity and labor mobility constraints. Periodic stress-testing of base assumptions is recommended given vulnerability to renewable portfolio standard policy adjustments and seismic code revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Peaking Power Plant Market
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
Oman Power Market
Power Generation
Captive Power Plant Market
Power Generation
India Gensets Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Mobile Power Plant Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Global Power to Gas Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Third Generation Energy Sources Market