
 Rooftop Solar EPC Market | 2026-2036
Rooftop Solar EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Rooftop Solar EPC Market Insights
The shift from single-source to multi-source module procurement is decoupling project risk from individual supplier performance in rooftop solar EPC. Tata Power Solar leverages backward integration into cell manufacturing to control cost volatility across its project pipeline. Jakson Group anchors its competitiveness through specialized engineering capabilities in commercial and industrial rooftop segments. ReNew competes on utility-scale execution discipline that it extends into large rooftop installations for corporate offtakers.
Rooftop solar EPC encompasses the end-to-end delivery of grid-connected photovoltaic systems mounted on building structures, typically involving structural load assessment, DC-AC electrical design, and net-metering integration to offset on-site consumption. The primary commercial purpose is to convert unused roof area into dispatchable, behind-the-meter generation assets with 25-year performance warranties. Installation services command the largest share of project value chains due to labor intensity and racking customization requirements, while bifacial technology segments are expanding fastest as module efficiency thresholds rise above 21% in commercial applications. Maintenance contracts represent emerging margin pools as asset owners prioritize performance ratio guarantees over upfront capital minimization.
India's Ministry of New and Renewable Energy coordinates rooftop subsidy disbursement through state nodal agencies, while BIS certification mandates module quality standards that filter import eligibility. The EU Green Deal and F-Gas Regulation shape equipment specifications across European rooftop deployments by restricting fluorinated gas use in inverters and switchgear. Stakeholders must monitor how distributed generation tariff reforms in key states alter the economics of net metering versus gross metering structures.
Market Dynamics
Module efficiency thresholds above 21% are compressing project economics and forcing EPC contractors to requalify supplier bases around bifacial and TOPCon cell architectures.
Growth Catalysts
- India's PLI scheme:Domestic cell manufacturing incentives reduce import dependency for EPC contractors sourcing modules for commercial rooftops. State nodal agencies accelerate subsidy disbursement timelines.
- Net-metering reforms:Distributed generation tariff structures in key Indian states improve payback periods for behind-the-meter assets. Commercial offtakers respond with accelerated procurement cycles.
- Bifacial technology maturation:Dual-sided module architectures capture albedo reflection from commercial roofing surfaces. Engineering margins expand through reduced watt-per-square-foot requirements.
Market Restraints
- Polysilicon supply concentration:Upstream ingot and wafer production clusters in specific geographies expose EPC contractors to input cost volatility. Project bidding windows compress margin certainty.
- BIS certification timelines:India's quality standards body mandates module testing protocols that extend procurement lead times. Import eligibility filters constrain supplier optionality.
- Grid integration capacity:Distribution network reinforcement lags behind rooftop connection requests in dense urban load centers. Utility interconnection queues delay commercial project commissioning.
Strategic Opportunities
- Industrial microgrids:Manufacturing facilities with 24/7 load profiles seek island-capable rooftop systems. EPC contractors bundle storage and smart inverter architectures.
- EU F-Gas Regulation:Fluorinated gas restrictions on inverters and switchgear create specification upgrade cycles. European commercial retrofit demand accelerates for compliant equipment.
- Performance guarantee monetization:Asset owners prioritize 25-year output warranties over upfront capital minimization. EPC contractors capture recurring revenue through O&M contract structures.
Industry Challenges
- Structural engineering specialization:Load assessment for aging commercial rooftops requires scarce civil engineering talent. EPC contractors compete for qualified assessors across project pipelines.
- Racking customization complexity:Non-standard roof geometries demand bespoke mounting system design. Fabrication lead times extend project schedules and working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rooftop Solar EPC Market |
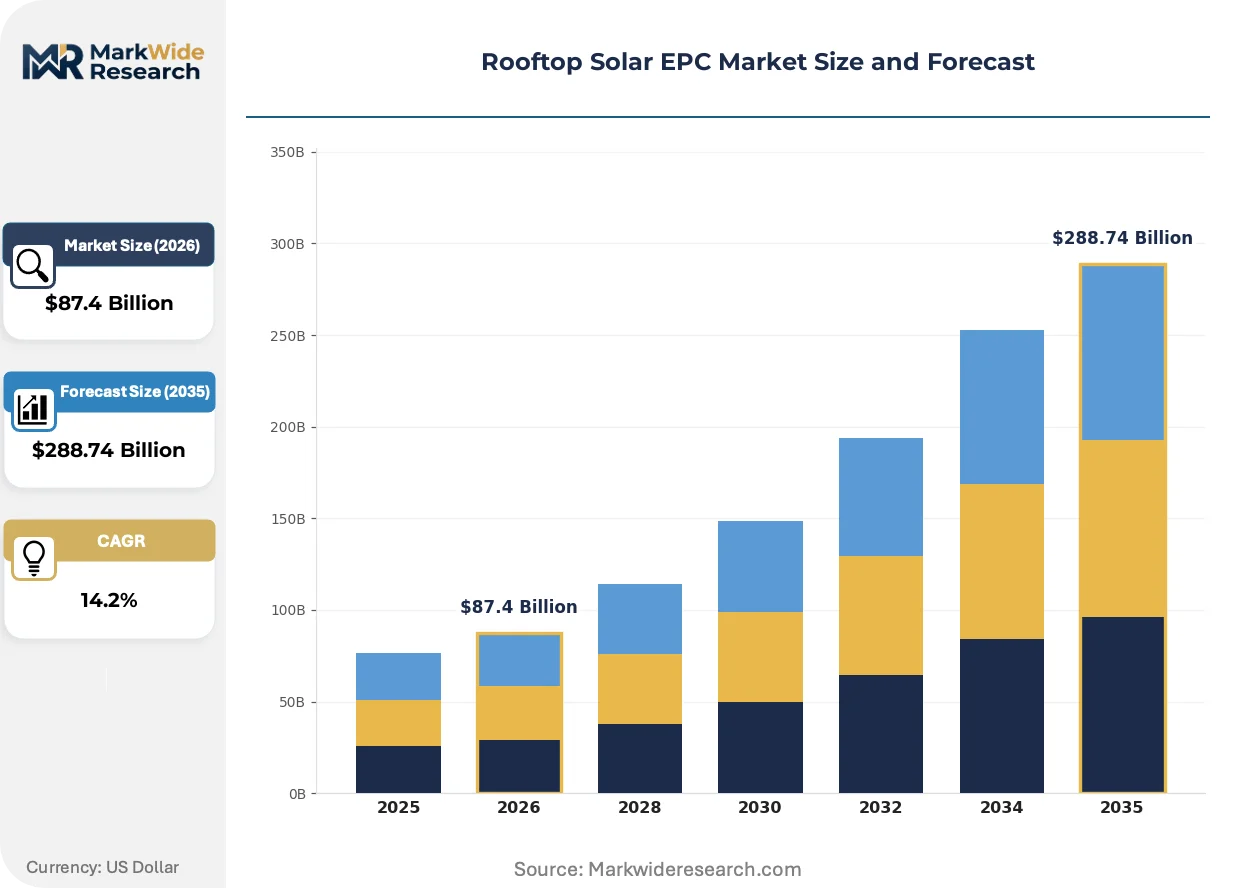
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $288.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design & Engineering, Procurement, Installation, Testing & Commissioning, Maintenance Customer Type: Residential Homeowners, Commercial Enterprises, Educational Institutions, Government Facilities Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial, Concentrated Photovoltaic Project Size: Small Scale, Medium Scale, Large Scale, Utility Scale |
| Companies Covered | Tata Power Solar, Jakson Group, Sunsure Energy, Amplus Solar, Roofsol Energy, Havells India, Vikram Solar, ReNew, Adani Green Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rooftop Solar EPC Market Trends and Innovations
Digital twin modeling and drone-based site surveys are compressing pre-construction timelines while improving accuracy in structural load predictions for complex commercial rooftops.
Bifacial photovoltaic modules are converging with tracking-enabled racking systems originally developed for ground-mount utility projects. Large commercial and industrial offtakers in India and China pilot these hybrid configurations on flat factory roofs. The technology pairing is enabling higher capacity factors per square meter and compressing levelized cost thresholds previously associated only with utility-scale deployments.
The EU F-Gas Regulation restricts fluorinated greenhouse gases in electrical switchgear and inverters deployed across European rooftop installations. Equipment manufacturers reformulate insulation and cooling systems to maintain thermal performance under tighter environmental standards. Commercial EPC contractors in Germany and the Netherlands face accelerated specification upgrade cycles as 2027 phase-down deadlines approach.
Corporate buyers are consolidating vendor relationships around EPC contractors offering integrated financing and long-term performance guarantees. Single-source accountability replaces fragmented procurement across separate module, inverter, and installation contracts. This concentration is most visible in India's commercial sector, where multinational manufacturing tenants demand turnkey solutions with standardized reporting for Scope 2 emissions reduction verification.
Rooftop Solar EPC Market Segmentation
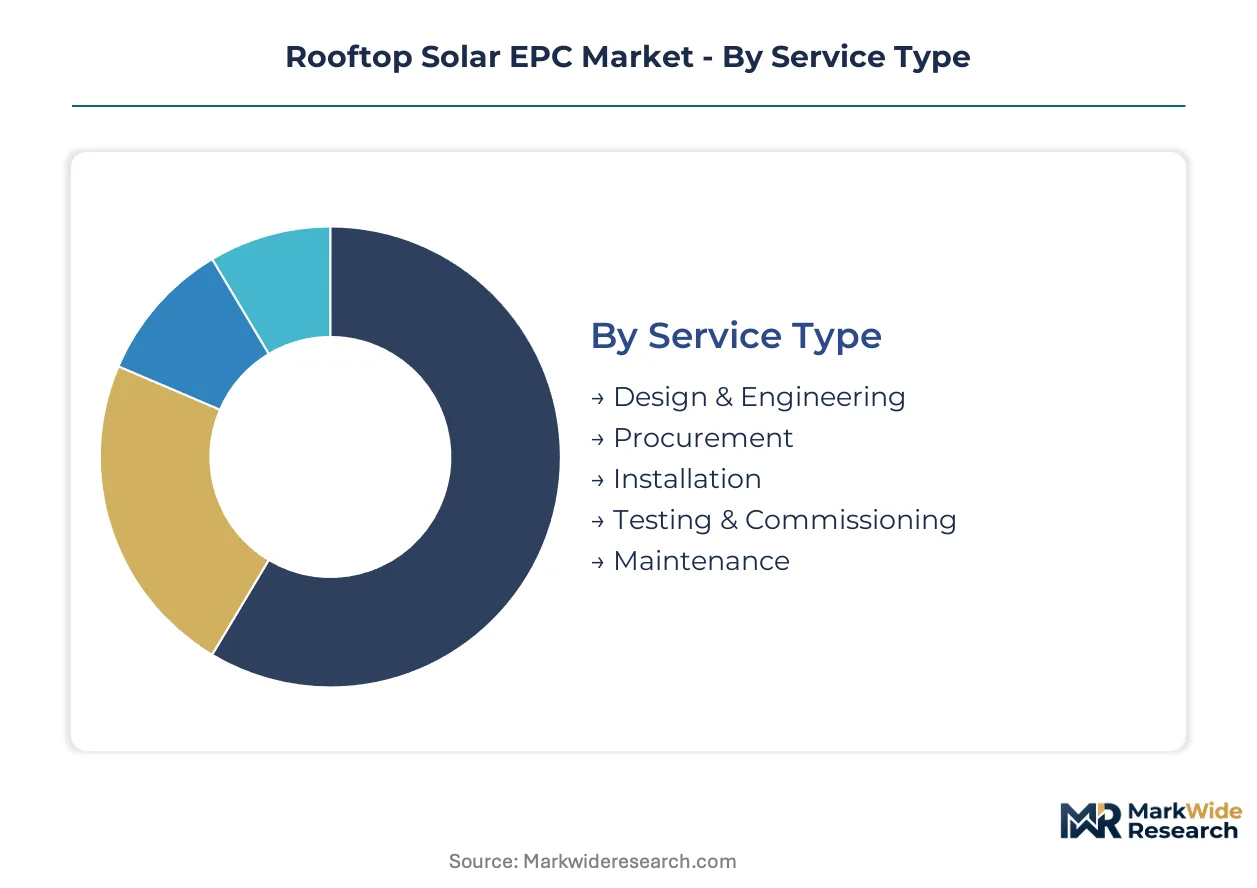
Rooftop solar EPC contractors configure service portfolios around distinct customer risk profiles and technical complexity thresholds. Segmentation reveals where margin pools concentrate versus where volume commoditizes.
Service Type:
Standardized execution dominates procurement and installation, while engineering and maintenance retain customization premiums.
- Design & Engineering:Structural load assessment and electrical system modeling require licensed civil and electrical engineering credentials. Demand clusters with commercial enterprises in India seeking BIS-compliant documentation for subsidy eligibility. Scarcity of qualified assessors extends project timelines.
- Procurement:Module and inverter sourcing has shifted from single-source to multi-source strategies as EPC contractors hedge polysilicon volatility. Commercial offtakers in China and Germany drive consolidated vendor relationships with integrated financing requirements.
- Installation:Labor-intensive racking mounting and DC-AC interconnection command the largest value share. Residential homeowners in India prioritize speed over customization, compressing margins.
- Testing & Commissioning:Grid synchronization and net-metering activation require utility coordination. Distribution network reinforcement lags delay commercial project handoffs in dense urban clusters.
- Maintenance:Performance ratio guarantees and 25-year output warranties create recurring revenue streams. Asset owners prioritize O&M contracts over upfront capital minimization.
Leading the category by volume: Installation. Growing fastest: Maintenance.
Customer Type:
Volume concentrates in commercial segments, while project complexity escalates with facility age and load profile specialization.
- Commercial Enterprises:Manufacturing facilities with 24/7 load profiles seek island-capable microgrid configurations. India's PLI scheme accelerates procurement cycles for corporate offtakers verifying Scope 2 reductions.
- Residential Homeowners:Individual rooftop systems under net-metering frameworks prioritize payback period over performance guarantees. Subsidy disbursement through state nodal agencies shapes demand geography.
- Educational Institutions:Campus-scale deployments combine multiple building rooftops with centralized monitoring. Flat roof geometries simplify racking design.
- Government Facilities:Public procurement mandates domestic content requirements and extended warranty terms. BIS certification filters constrain supplier pools.
Commercial enterprises generate dominant revenue share. Educational institutions expand most quickly as EPC contractors bundle smart monitoring.
Technology:
Cell architecture choices determine project economics as efficiency thresholds reshape supplier qualification.
- Monocrystalline:Single-crystal silicon wafers deliver highest conversion efficiency in standard test conditions. Residential and commercial segments in Germany specify premium modules for space-constrained rooftops.
- Bifacial:Dual-sided architectures capture albedo reflection from commercial roofing surfaces. Factory roof pilots in India and China pair bifacial modules with tracking-enabled racking for utility-scale capacity factors.
- Polycrystalline:Multi-crystal silicon offers cost advantages where roof area abundance offsets lower efficiency. Price-sensitive residential markets retain demand.
- Thin-Film:Cadmium telluride and CIGS technologies perform in low-light and high-temperature conditions. Specialized commercial applications with irregular roof geometries.
- Concentrated Photovoltaic:Lens-based sunlight concentration targets utility-scale ground installations. Rooftop deployment remains experimental due to tracking complexity.
Monocrystalline holds volume leadership. Bifacial technology climbs the fastest as module efficiency thresholds exceed 21%.
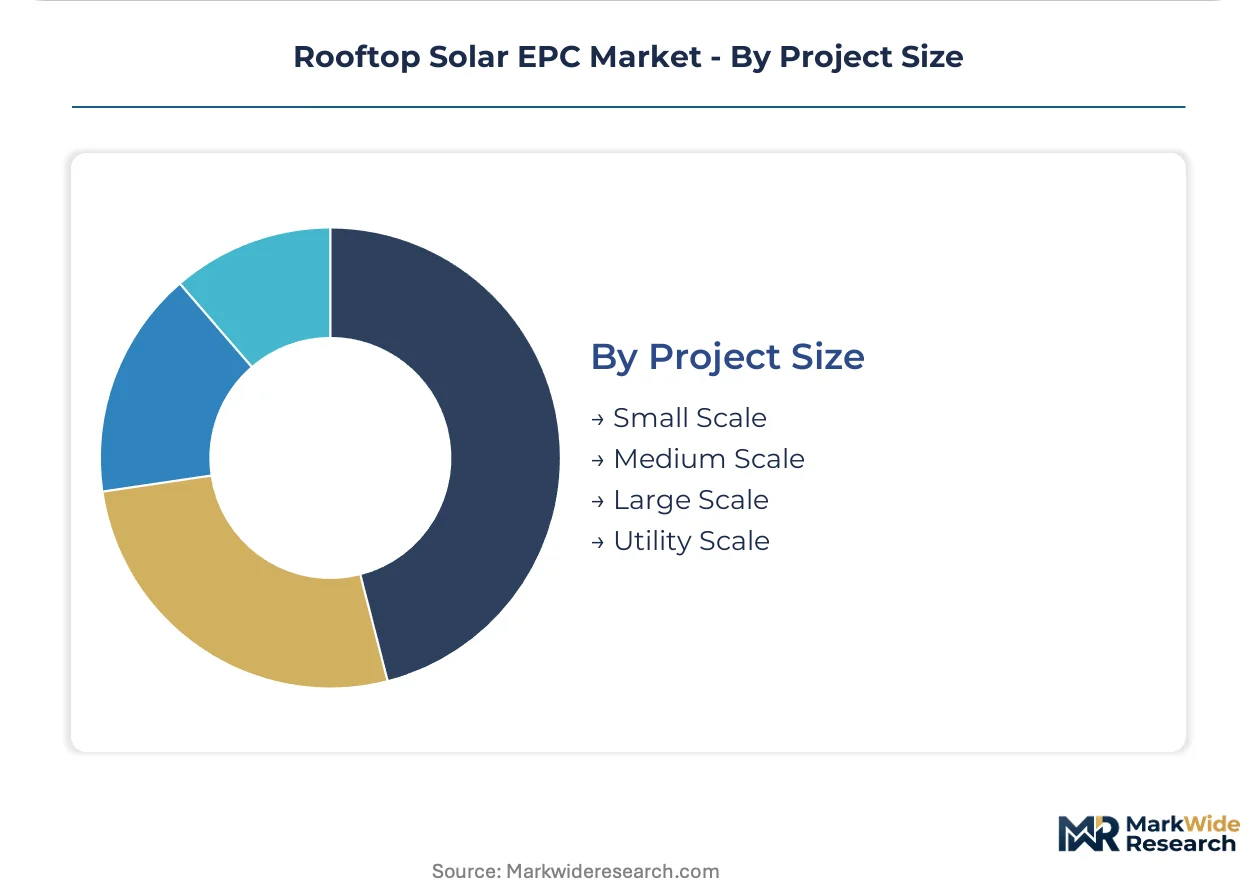
Project Size:
Economies of scale in procurement and installation labor create distinct competitive dynamics across size tiers.
- Large Scale:Multi-megawatt commercial and industrial rooftops replicate utility-scale execution discipline. Corporate offtakers demand single-source accountability with standardized emissions reporting.
- Medium Scale:Small commercial and institutional projects balance customization with repeatability. Educational institutions and government facilities cluster here.
- Small Scale:Residential systems under net-metering frameworks compete on installed cost per watt. State-level subsidy variations fragment demand geography.
- Utility Scale:Ground-mounted installations exceed typical rooftop definitions but inform technology transfer. Tracking and bifacial innovations migrate to flat commercial roofs.
Medium scale projects dominate active pipeline volume. Large scale deployments gain share fastest as corporate procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polysilicon refining clusters in Xinjiang and Inner Mongolia anchor Asia-Pacific module supply chains. German engineering standards and India's subsidy disbursement mechanisms create distinct procurement environments. Distribution network reinforcement lags constrain interconnection capacity in dense urban load centers across multiple jurisdictions.
India
Commercial manufacturing facilities with 24/7 load profiles drive procurement acceleration. The Ministry of New and Renewable Energy coordinates subsidy disbursement through state nodal agencies with BIS certification mandates filtering import eligibility. Gujarat and Maharashtra industrial corridors concentrate EPC contractor activity around port-adjacent module logistics.
China
Dual carbon goals compress deployment timelines for commercial and industrial rooftops. MIIT production standards and GB certification protocols shape equipment specifications for domestic installations. Yangtze River Delta factory zones pilot bifacial-tracking hybrid configurations on flat industrial roofs.
Germany
Corporate offtakers demand standardized emissions reporting for Scope 2 verification. The EU F-Gas Regulation restricts fluorinated gases in inverters and switchgear with 2027 phase-down deadlines accelerating specification upgrades. North Rhine-Westphalia and Bavaria industrial zones concentrate retrofit demand for compliant equipment.
United States
Investment Tax Credit extensions improve project economics for commercial behind-the-meter assets. FERC interconnection standards and state-level net-metering frameworks fragment regulatory complexity. California and Texas distribution utilities face interconnection queue bottlenecks delaying commercial project commissioning.
Japan
Feed-in-tariff transitions push commercial offtakers toward self-consumption models. METI renewable energy targets and JIS module standards shape procurement specifications. Kanto and Kansai manufacturing belts concentrate EPC activity around automotive and electronics sector demand.
Rooftop Solar EPC Market Competitive Landscape
Backward integration into cell manufacturing dominates the current landscape as contractors hedge polysilicon volatility. The vendor base stratifies across utility-scale execution specialists, commercial rooftop engineering boutiques, and integrated power conglomerates. Three archetypes prevail: captive module producers controlling upstream cost exposure, engineering-heavy firms specializing in complex structural assessments, and renewable IPPs extending utility discipline into corporate offtaker relationships. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure BIS-compliant supply channels and distribution utility relationships.
Among India-based integrated power groups, Tata Power Solar and Adani Green Energy exemplify backward integration archetypes with captive cell production capabilities. Jakson Group occupies a position within the engineering-specialist tier, while ReNew represents utility-scale execution discipline extended into large commercial rooftop installations. These three anchors illustrate how procurement risk decoupling and structural engineering scarcity reshape competitive positioning across the project pipeline.
| Leading Market Players |
|---|
| Tata Power Solar |
| Jakson Group |
| Sunsure Energy |
| Amplus Solar |
| Roofsol Energy |
| Havells India |
| Vikram Solar |
| ReNew |
| Adani Green Energy |
| Others |
Pricing and Supply Chain Analysis
Scarce structural engineering talent concentrated in Gujarat and Maharashtra commands premium labor rates that widen pricing spreads between standardized residential installations and complex commercial microgrids. These labor-cost differentials separate economy-tier residential bids from premium commercial offerings that bundle 25-year performance guarantees with island-capable storage architectures.
Pricing Analysis
Warranty bundling separates premium EPC offerings from unbundled economy bids where asset owners self-source O&M. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service inclusion. Cost compression in the residential tier intensifies because state nodal agencies compress subsidy disbursement timelines. Residential homeowners exhibit highest price sensitivity, while corporate offtakers with 24/7 load profiles prioritize performance guarantees over upfront capital minimization.
Supply Chain Analysis
Dual-sourcing mandates from commercial offtakers require EPC contractors to qualify multiple module suppliers beyond single-source dependencies. Polysilicon refining clusters in China, wafer slicing operations in Vietnam, and cell manufacturing expansion in India anchor upstream supply. Module and inverter procurement draws from concentrated ingot production, aluminum racking extrusions, and fluorinated gas-dependent switchgear. Single-source vulnerability in polysilicon exposes contractors to input cost volatility. Distribution runs through port-adjacent logistics hubs serving state nodal agency subsidy corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive cell production controls cost volatility across project pipelines. Backward integration into module manufacturing represents the decisive upstream lever separating integrated power groups from installation-dependent competitors.
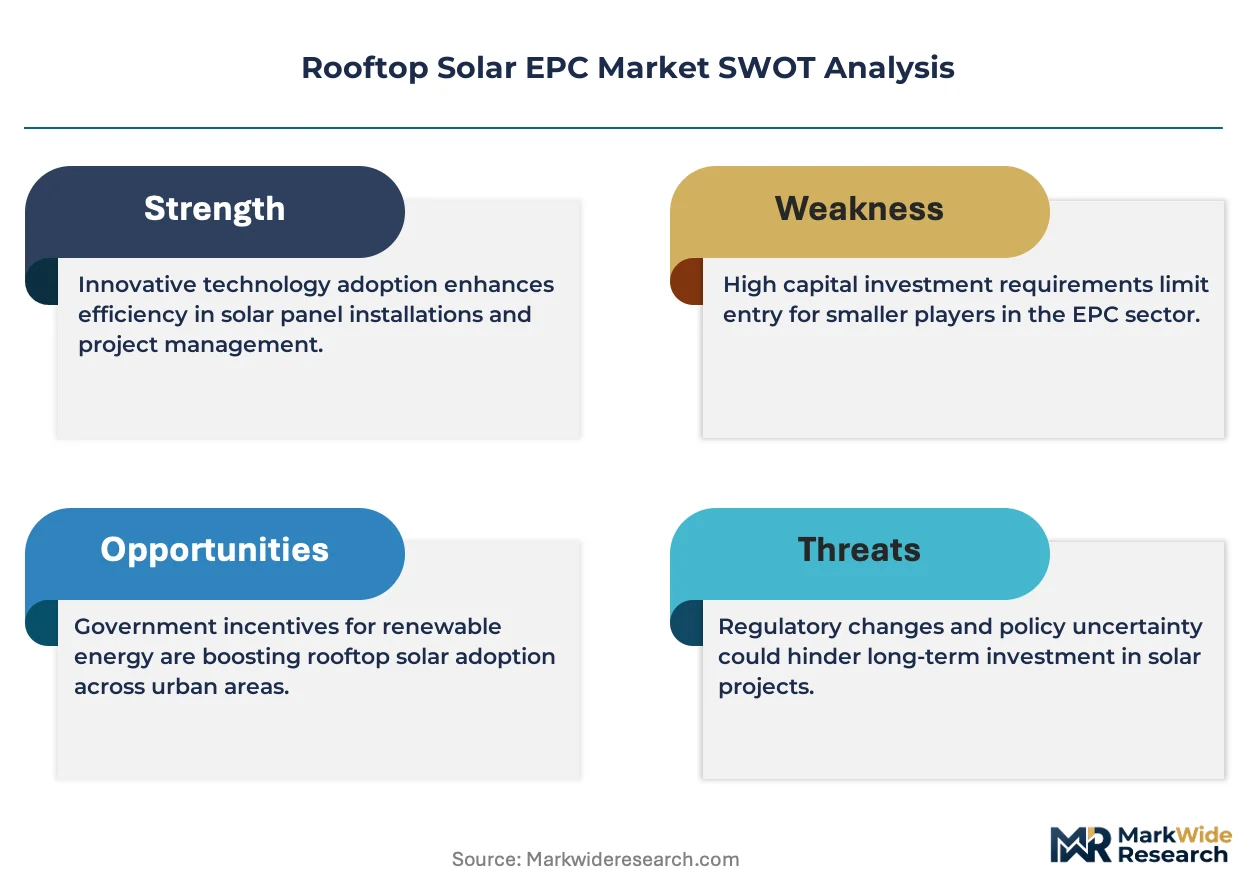
For Market Incumbents: Deploy captive module production to hedge polysilicon price swings that compress bidding margins. Incumbents must secure BIS-compliant supply channels ahead of certification timeline extensions while acquiring scarce structural engineering talent pools in industrial corridor states. Emerging engineering-specialist boutiques threaten premium commercial segments with faster load assessment turnaround. For New Entrants and Emerging Players: Capture maintenance contract white space as asset owners shift priority from upfront capital minimization toward 25-year performance guarantees. Educational institutions with flat roof geometries and bundled smart monitoring requirements offer the most penetrable segment. A direct O&M-first go-to-market angle bypasses crowded installation procurement. For Investors and Strategic Acquirers: Re-rating potential sits with engineering-heavy boutiques given structural scarcity of qualified civil assessors for aging commercial rooftops. Long-term viability favors contractors with demonstrated utility-scale execution discipline that extends into corporate offtaker relationships. Watch distributed generation tariff reforms in key Indian states as the inflection signal for net-metering versus gross-metering economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Manufacturing | Captive production hedges polysilicon volatility under India's PLI scheme incentives. |
| Multi-Source Supplier Qualification | Dual-sourcing mandates from commercial offtakers decouple project risk from individual supplier performance. |
| Performance Guarantee Monetization | 25-year output warranties create recurring O&M revenue streams displacing upfront-only competition. |
| Structural Engineering Talent Acquisition | Scarce civil assessors for aging commercial rooftops extend project timelines and working capital cycles. |
| EU F-Gas Compliance Equipment Upgrade | Fluorinated gas restrictions accelerate specification refresh cycles for inverter and switchgear procurement. |
Research Methodology
Independent corroboration across EPC project developers, distribution utility interconnection officers, and state nodal agency subsidy administrators underwrites the qualitative findings. Primary interviews with commercial manufacturing facility energy managers, rooftop structural assessors, and module procurement leads combined with secondary validation from MNRE disbursement records, BIS certification databases, and EU F-Gas Regulation compliance filings. Bottom-up project pipeline aggregation and top-down policy impact assessment triangulate market sizing.
Comparable-period anchoring to historical deployment trajectories across the projection horizon enables trend extrapolation with technology transition adjustments. Segmentation dimensions modeled include service type, customer risk profile, cell architecture efficiency tier, and project scale category. CAGRs derive from installed capacity build rates cross-referenced with module cost curve trajectories and subsidy disbursement velocity. Bifacial technology maturation and net-metering tariff reform timelines constitute industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polysilicon supply concentration and distribution network reinforcement lag. Forecasts reflect documented assumptions regarding PLI scheme continuation and BIS certification protocol stability. Deviation in India's distributed generation tariff structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Solar Panel Cleaning System Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
France Distributed Solar Power Generation Market