
 South East Asia Power Market | 2026-2036
South East Asia Power Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia Power Market Outlook
Ultra-supercritical steam parameters is rotating investment priorities across the South East Asia Power Market as developers chase efficiency gains above 45 percent. Tenaga Nasional Berhad leverages its integrated generation-transmission footprint to anchor project pipelines in Peninsular Malaysia. PT Perusahaan Listrik Negara sustains dominance across Java-Bali through captive coal supplies and grid control. Gulf Energy Development Public Company Limited differentiates via gas-fired combined-cycle expansions tied to Thailand's LNG import infrastructure.
The South East Asia Power Market encompasses electricity generation, transmission, and distribution infrastructure spanning fuel sources from coal and natural gas to solar, wind, and hydropower, with installed capacity typically measured in megawatts and dispatch characterized by capacity factors, heat rates, and grid stability parameters. Its primary purpose is delivering reliable electrons to industrial loads, commercial centers, and residential clusters across archipelagic terrain where geography fragments grid topology. Renewable Energy capacity additions now outpace Fossil Fuels in annual greenfield announcements, though coal retirements lag policy timelines. The Industrial application segment commands the deepest margin pools as offtake agreements stretch ten to twenty-five years, while Residential electrification in frontier provinces still relies on distributed mini-grids rather than central station extension.
Indonesia's MEMR enforces local content requirements for power equipment, while Thailand's ERC licenses independent power producers under enhanced competitive bidding rules, and Vietnam's MOIT directs state-owned EVN to prioritize renewable purchase obligations under revised PDP8. These frameworks reshape developer capital allocation, equipment sourcing, and offtake negotiation leverage across the region. Stakeholders must track which regulatory body relaxes or tightens foreign ownership ceilings first, as that jurisdiction will absorb disproportionate private capital flows.
Market Dynamics
Ultra-supercritical coal technology and floating solar photovoltaic deployment on hydropower reservoirs are restructuring capital allocation across South East Asia's generation stack, as developers chase efficiency gains above 45 percent while navigating tightening ASEAN grid interconnection standards.
Growth Catalysts
- ASEAN Grid Code Harmonization:Interconnection standards tightening across member states enable cross-border electricity trading and unlock economies of scale for large-scale renewable projects spanning multiple jurisdictions.
- Industrial Manufacturing Expansion:Facilities in Indonesia and Vietnam are extending offtake agreements to twenty-five years, creating bankable revenue streams that attract project finance for new capacity additions.
- Floating Solar Technology Maturation:Installations on Thailand's hydropower reservoirs concentrate developer attention by eliminating land acquisition constraints and reducing evaporative water loss at existing dams.
Market Restraints
- Local Content Requirements:Indonesia's MEMR mandates domestic equipment sourcing that extends procurement timelines and limits supplier pool flexibility for international developers.
- LNG Import Infrastructure Concentration:Thailand's dependence on limited terminal capacity creates fuel supply vulnerability for gas-fired combined-cycle expansions during peak demand periods.
- Coal Retirement Lag:Policy timelines for fossil fuel phase-out exceed actual decommissioning rates, locking in stranded asset risk and complicating grid balancing with variable renewable penetration.
Strategic Opportunities
- Frontier Province Electrification:Residential clusters in Indonesia's eastern islands remain underserved by central station extension, creating distributed mini-grid deployment opportunities for private capital.
- Renewable Purchase Obligations:Vietnam's MOIT directs EVN to prioritize clean energy procurement under revised PDP8, establishing mandated offtake channels for independent power producers.
- Battery Storage Convergence:Pairing lithium-ion systems with solar and wind assets addresses grid stability parameters and opens ancillary service revenue streams in frequency regulation markets.
Industry Challenges
- Grid Code Certification Complexity:Equipment manufacturers face extended testing protocols to demonstrate fault ride-through capability and reactive power support under evolving ASEAN technical standards.
- Interconnection Queue Management:Transmission system operators struggle to process connection requests from distributed generators, creating project delays that erode developer returns during construction financing periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia Power Market |
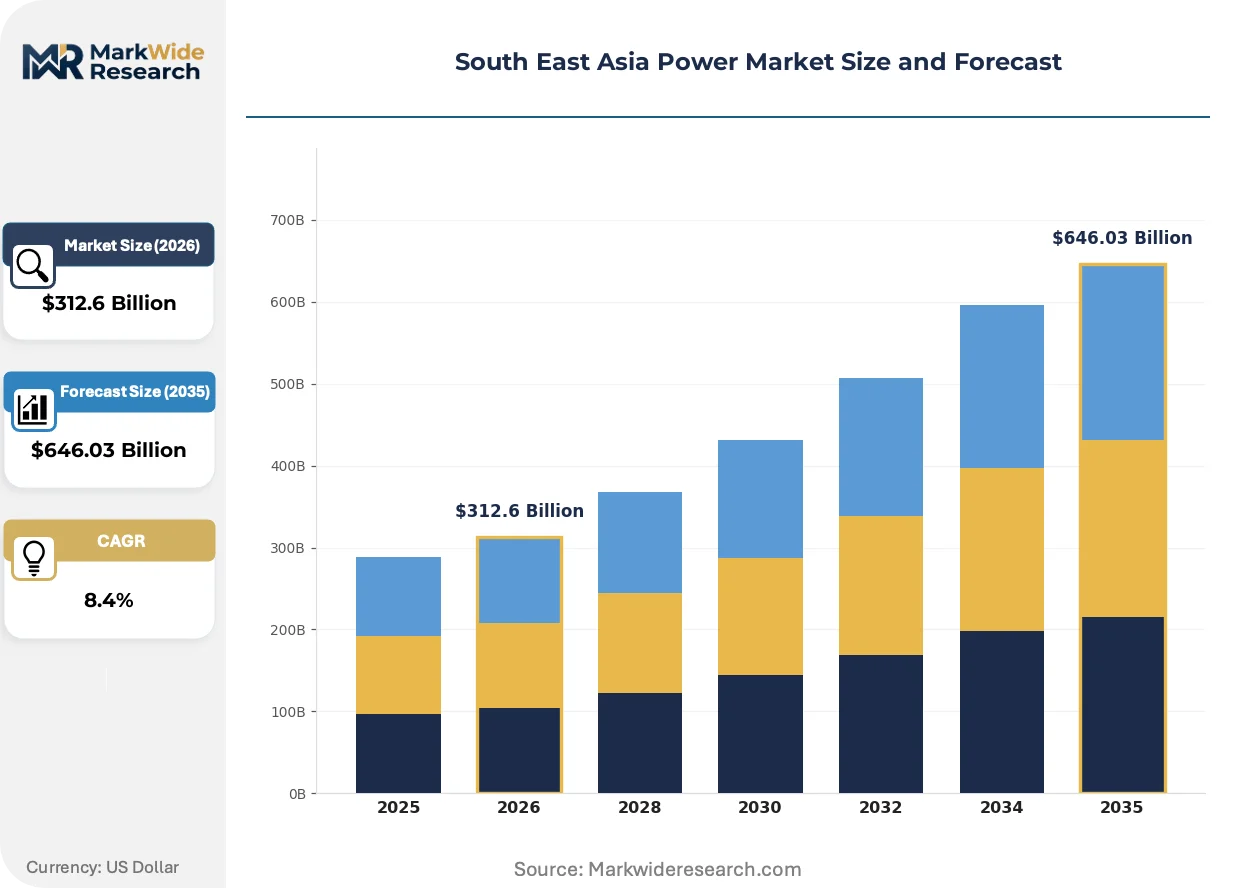
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $646.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable Energy, Fossil Fuels, Nuclear Energy, Hydropower Application: Industrial, Commercial, Residential, Transportation Technology: Solar, Wind, Gas Turbines, Biomass End User: Utilities, Manufacturers, Households, Government |
| Companies Covered | Tenaga Nasional Berhad, PT Perusahaan Listrik Negara, Electricity Generating Authority of Thailand, SP Group, Vietnam Electricity Construction JSC, Sarawak Energy, Gulf Energy Development Public Company Limited, B.Grimm Power, Ratch Group, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia Power Market Strategic Shifts
Technology trajectories across South East Asia's power sector center on efficiency maximization and grid flexibility, with capital rotating toward solutions that reconcile baseload reliability with renewable intermittency management.
Bifacial solar modules with tracking systems is displacing fixed-tilt monofacial installations in utility-scale projects across Thailand and Vietnam. Independent power producers deploying these arrays capture elevated capacity factors from reflected irradiance on reservoir surfaces and agricultural land. This technology is displacing conventional engineering-procurement-construction contracting models that optimized for lowest upfront capital rather than levelized cost of electricity.
Thailand's ERC licensing framework for competitive bidding is compressing developer margins while accelerating project timelines. The enhanced auction rules require bidders to submit grid impact studies and community benefit plans alongside price offers. Gas-fired independent power producers with existing LNG offtake contracts are restructuring bid strategies to emphasize dispatch flexibility rather than baseload availability.
Corporate renewable energy procurement through direct power purchase agreements is fragmenting traditional utility-centric distribution channels. Manufacturing facilities in Peninsular Malaysia and Vietnam's industrial zones are negotiating sleeved contracts that bypass state-owned offtakers. This pattern is most visible in Vietnam's northern provinces where foreign-invested electronics assemblers seek price certainty and green credentials independent of EVN's retail tariff structure.
South East Asia Power Market Segmentation
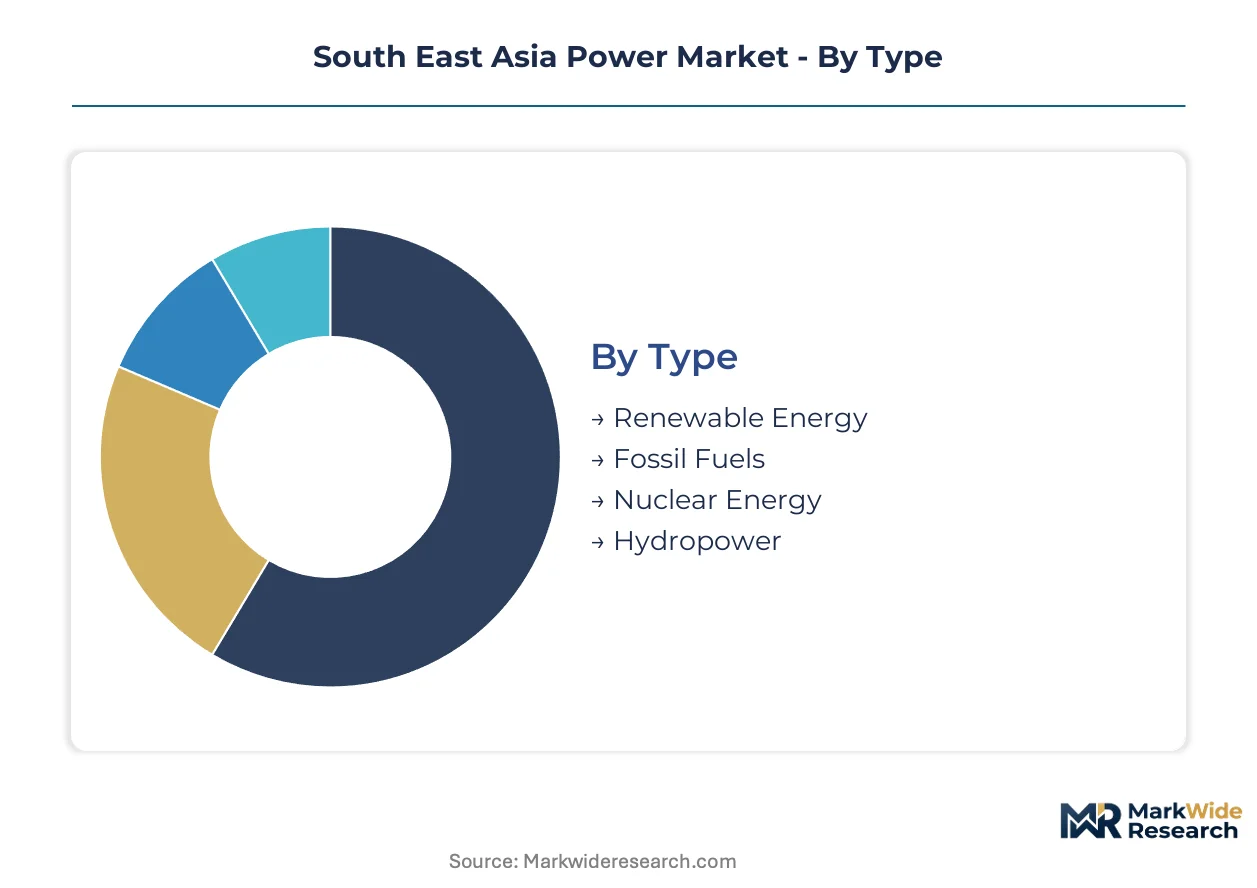
Generation technology mix and offtake contract structures fragment capital deployment across South East Asia's archipelagic grid topology. Regulatory frameworks in Indonesia, Thailand, and Vietnam assign distinct compliance burdens to each segment, reshaping developer prioritization and equipment sourcing decisions.
Type:
Indonesia's MEMR enforces divergent local content thresholds across generation sources, while Vietnam's PDP8 mandates differential renewable purchase obligations that restructure revenue visibility by fuel category.
- Fossil Fuels:Ultra-supercritical coal and combined-cycle natural gas plants anchor baseload dispatch across Java-Bali and Peninsular Malaysia. Industrial manufacturing clusters in Vietnam's northern provinces extend twenty-five-year offtake agreements to gas-fired developers, locking in bankable revenue streams despite LNG import infrastructure constraints.
- Renewable Energy:Floating solar photovoltaic arrays on Thailand's hydropower reservoirs and bifacial tracking installations across agricultural land eliminate land acquisition bottlenecks. Corporate power purchase agreements from foreign-invested electronics assemblers concentrate demand in Vietnam's industrial zones, bypassing state-owned utility retail tariffs.
- Hydropower:Existing dam infrastructure in Laos and Myanmar feeds cross-border trading arrangements under tightening ASEAN grid codes.
- Nuclear Energy:No operational capacity exists; Vietnam suspended reactor construction plans following Fukushima, leaving regulatory frameworks undeveloped.
Fossil Fuels handles the majority of throughput; Renewable Energy is the fastest mover on share.
Application:
Margin pools vary sharply by contract duration and counterparty credit quality, with industrial offtakers commanding preferential dispatch and tariff terms unavailable to residential clusters.
- Industrial:Manufacturing facilities across Indonesia and Vietnam negotiate sleeved direct power purchase agreements that circumvent state-owned offtakers. Tenaga Nasional Berhad and Gulf Energy Development structure capacity charges around production volume guarantees from electronics and automotive assemblers.
- Residential:Frontier provinces in Indonesia's eastern islands rely on distributed mini-grids rather than central station extension, creating capital deployment opportunities for private developers outside PT Perusahaan Listrik Negara's franchise areas. Thailand's ERC licensing framework prioritizes universal service obligations in competitive bidding rounds.
- Commercial:Shopping centers and office towers in Bangkok and Kuala Lumpur adopt rooftop solar plus battery configurations to manage retail tariff exposure.
- Transportation:Electric vehicle charging infrastructure concentrates in Singapore and metropolitan Bangkok, drawing on grid stability investments rather than dedicated generation assets.
Industrial captures the deepest margin pools; Residential exhibits the steepest expansion trajectory as electrification rates climb in frontier provinces.
Technology:
Equipment certification complexity under evolving ASEAN grid codes fragments supplier qualification, extending procurement timelines for technologies requiring fault ride-through demonstration.
- Solar:Bifacial modules with tracking systems displace fixed-tilt monofacial installations in utility-scale projects across Thailand and Vietnam. Reflected irradiance from reservoir surfaces and agricultural land elevates capacity factors, restructuring engineering-procurement-construction contracting toward levelized cost optimization rather than upfront capital minimization.
- Gas Turbines:Combined-cycle configurations dominate Thailand's LNG-linked expansions, with Gulf Energy Development leveraging existing terminal offtake contracts to emphasize dispatch flexibility in ERC competitive bidding.
- Wind:Onshore projects concentrate in Vietnam's central highlands, where MOIT-directed renewable purchase obligations establish mandated offtake channels.
- Biomass:Agricultural residue-fired plants cluster in Thailand's sugarcane belt, capturing feedstock proximity advantages.
Gas Turbines carries the heaviest installed base; Solar is gaining share fastest as floating photovoltaic technology matures.
End User:
Counterparty risk profiles and contract enforceability diverge sharply across state-owned utilities, private manufacturers, and household clusters, reshaping project finance availability and tenor.
- Utilities:PT Perusahaan Listrik Negara and Electricity of Vietnam anchor procurement through integrated generation-transmission footprints. State-owned offtakers control interconnection queue management, creating project delays that erode developer returns during construction financing periods.
- Manufacturers:Foreign-invested electronics assemblers in Peninsular Malaysia and Vietnam's industrial zones negotiate sleeved corporate renewable energy procurement. Direct power purchase agreements fragment traditional utility-centric distribution channels as manufacturing facilities seek price certainty independent of retail tariff structures.
- Government:Military and public infrastructure loads in Thailand and Indonesia receive priority dispatch allocation under national security frameworks.
- Households:Residential electrification in Indonesia's eastern provinces depends on distributed mini-grid deployment by private capital, bypassing central station extension economics.
Utilities dominate offtake volume; Manufacturers are expanding most quickly as corporate procurement bypasses state-owned intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laos exports hydropower across its borders to Thailand and Vietnam through cross-border trading arrangements that tighten ASEAN grid interconnection standards. Electricity flows from Mekong dam infrastructure into Thai distribution networks and Vietnamese industrial zones. These trade corridors reshape capital allocation across mainland Southeast Asia.
Indonesia
Industrial manufacturing clusters in Java-Bali extend electricity offtake agreements as captive coal supplies anchor baseload dispatch. MEMR enforces local content requirements for power equipment that extend procurement timelines. Private developers deploy distributed mini-grids across eastern islands including Papua and Maluku where PT Perusahaan Listrik Negara's central station extension proves uneconomical.
Thailand
Floating solar photovoltaic arrays on hydropower reservoirs eliminate land acquisition constraints while reducing evaporative water loss. ERC licenses independent power producers under enhanced competitive bidding rules that compress developer margins. Gulf Energy Development leverages existing LNG terminal offtake contracts to emphasize dispatch flexibility in auctions around Bangkok and the Eastern Economic Corridor.
Vietnam
Foreign-invested electronics assemblers in northern provinces including Bac Ninh and Hai Phong negotiate sleeved corporate power purchase agreements. MOIT directs Electricity of Vietnam to prioritize renewable purchase obligations under revised PDP8. Wind projects concentrate in the central highlands where MOIT-directed mandates establish bankable offtake channels.
Malaysia
Tenaga Nasional Berhad anchors project pipelines in Peninsular Malaysia through its integrated generation-transmission footprint. Industrial loads in Selangor and Johor negotiate capacity charges tied to production volume guarantees. Sarawak Energy feeds hydropower exports into the Borneo grid while domestic manufacturing expansion drives electricity demand in Kuching industrial zones.
Singapore
SP Group manages island-wide distribution infrastructure where land scarcity precludes utility-scale renewable deployment. The city-state imports natural gas through limited terminal capacity while exploring regional power import agreements under ASEAN grid code harmonization. Commercial and industrial clusters in Jurong and Tuas adopt rooftop solar plus battery configurations to manage retail tariff exposure.
South East Asia Power Market Competitive Environment
Listed leaders compete with private specialists across generation technology portfolios, with state-owned utilities controlling transmission interconnection queues while independent power producers capture margin pools through long-term offtake agreements. Market concentration varies by jurisdiction: PT Perusahaan Listrik Negara sustains integrated dominance across Java-Bali, while Thailand's ERC framework fragments procurement among multiple licensed developers. Three archetypes define competitive positioning: state-backed integrated utilities with captive fuel access, gas-fired independent power producers with LNG infrastructure ties, and renewable specialists exploiting corporate procurement channels. Dominant competitive moves include portfolio diversification across fuel sources and strategic partnerships to secure interconnection queue priority.
Within the state-backed utility tier, Tenaga Nasional Berhad and PT Perusahaan Listrik Negara occupy positions defined by integrated generation-transmission footprints and captive fuel supply arrangements. Gulf Energy Development Public Company Limited exemplifies the gas-fired independent power producer archetype, with its corporate structure tied to Thailand's LNG import terminal access. Among renewable-focused developers, B.Grimm Power and Ratch Group represent specialists competing for corporate power purchase agreement volumes across Thailand and Vietnam.
| Leading Market Players |
|---|
| Tenaga Nasional Berhad |
| PT Perusahaan Listrik Negara |
| Electricity Generating Authority of Thailand |
| SP Group |
| Vietnam Electricity Construction JSC |
| Sarawak Energy |
| Gulf Energy Development Public Company Limited |
| B.Grimm Power |
| Ratch Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-day equipment procurement cycles for ultra-supercritical turbine components concentrate supplier leverage among Japanese and German OEMs, amplifying pricing power for integrated utilities with captive fuel arrangements while squeezing independent power producers reliant on spot LNG markets. This lead-time structure rewards developers with backward integration into equipment sourcing or long-term offtake contracts that absorb cost volatility.
Pricing Analysis
Industrial manufacturing buyers anchor contract-based long-term offtake pricing across Java-Bali and Vietnam's northern provinces. Price differentiation hinges on capacity factor guarantees and local content certification tiers under Indonesia's MEMR rules. Cost compression in gas-fired capacity is intensifying because LNG terminal congestion limits fuel supply flexibility during peak demand periods. State-owned utilities exhibit lowest price sensitivity due to integrated generation-transmission footprints, while distributed mini-grid developers in frontier provinces face acute margin pressure from diesel fuel exposure.
Supply Chain Analysis
Extended interconnection queue timelines stretching eighteen to twenty-four months tether project completion schedules to transmission system operator processing capacity. Equipment manufacturing concentrates in Japan, Germany, and South Korea for gas turbines and ultra-supercritical boilers. Polysilicon and lithium-ion cells for solar-plus-storage projects draw from Chinese and South Korean suppliers. Single-source vulnerability pervades specialized grid code certification testing, where only two ASEAN-accredited laboratories validate fault ride-through capability. Distribution runs through state-owned utility procurement channels in Indonesia and Vietnam, while Thailand's ERC competitive bidding fragments offtaker concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate renewable energy procurement is fragmenting traditional utility-centric distribution channels, creating specialized service niches for developers capable of structuring sleeved power purchase agreements outside state-owned retail tariff frameworks.
For Market Incumbents: Shield integrated generation-transmission positions by accelerating floating solar deployment on existing hydropower reservoirs, eliminating land acquisition bottlenecks that constrain competitor expansion. Prioritize interconnection queue management investments to preserve priority access for captive project pipelines, as transmission system operator processing delays erode developer returns during construction financing periods. Cement LNG terminal offtake contracts to lock in dispatch flexibility premiums under Thailand's ERC competitive bidding rules. For New Entrants and Emerging Players: Corporate power purchase agreement structuring gaps in Vietnam's industrial zones offer white-space entry where foreign-invested electronics assemblers seek price certainty independent of EVN's retail tariffs. Frontier province mini-grid deployment across Indonesia's eastern islands presents the most penetrable geography, bypassing PT Perusahaan Listrik Negara's central station extension economics. Lead with distributed solar-plus-battery configurations that address grid stability parameters while capturing ancillary service revenue streams. For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned utility renewable development arms seeking private capital participation to meet renewable purchase obligations under Vietnam's revised PDP8. Long-term viability hinges on regulatory continuity across ASEAN grid code harmonization and local content requirement enforcement. Watch for interconnection standard tightening as the inflection signal that reallocates capital toward cross-border trading infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Solar Capacity Buildout | Thailand's hydropower reservoirs eliminate land constraints while reducing evaporative losses at existing dams. |
| Corporate Power Purchase Agreement | Vietnam's electronics assemblers bypass EVN retail tariffs through sleeved direct contracts with independent producers. |
| Ultra-Supercritical Technology Licensing | Efficiency gains above forty-five percent attract capital toward coal fleet modernization despite retirement timelines. |
| Backward Integration into LNG Terminals | Gulf Energy Development leverages captive terminal access to emphasize dispatch flexibility in ERC auctions. |
| Green Certification Program | Renewable purchase obligations under PDP8 establish mandated offtake channels for clean energy project finance. |
Study Parameters
Desk research of IEA power market databases, ASEAN energy regulator filings, and project development tracking platforms preceded structured interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators. Secondary validation drew from EIA international energy statistics, national power development plan documents, and interconnection queue management records. Bottom-up capacity addition modeling triangulated against top-down macroeconomic demand projections.
Variance decomposition across fuel source, generation capacity tier, and regulatory framework segments shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market value expansion. Forecast inputs incorporated ASEAN grid code harmonization timelines, local content requirement enforcement patterns, and LNG import infrastructure capacity constraints.
Forecasts assume regulatory continuity in Indonesia's MEMR local content regimes, Thailand's ERC competitive bidding frameworks, and Vietnam's PDP8 renewable obligations; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
South America Thermal Power Market
Power Generation
Global Gensets Market
Power Generation
Coal Fired Power Generation Market
Power Generation
Peaking Power Plant Market
Power Generation
India Gas Generator Market
Power Generation
Aeroderivative Gas Turbine Market
Power Generation
Power Plant EPC Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
Marine Power Plant Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Algeria Power Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Oilfield Power Generation Market
Power Generation
Asia-Pacific Thermal Power Plant Market