
 Mosaic Tiles Market | 2026-2036
Mosaic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Mosaic Tiles Market Insights
Commercial property developers is collapsing as the dominant buyer archetype, while interior designers and hospitality procurement teams gain share in specification authority. Kajaria Ceramics leverages its Gujarat manufacturing base to dominate domestic volume. Mohawk Industries sustains North American distribution density through captive retail channels. Porcelanosa Grupo differentiates via vertically controlled design-to-retail operations across Iberia and the Americas.
Mosaic tiles are small-format surfacing elements, typically measuring under 100 mm per side, assembled from glass, ceramic, stone, or porcelain and bonded to mesh or paper sheets for field installation. Their primary commercial purpose spans decorative wall cladding, wet-area flooring, and artistic architectural interventions where color gradation and tactile variation matter. Ceramic and porcelain segments anchor volume due to durability and water absorption below 0.5 percent, while glass mosaics command margin pools in premium hospitality and art installation channels. Mesh-mounted installation leads commercial efficiency, though peel-and-stick formats are gaining traction in residential renovation where labor scarcity drives demand for simplified application.
EPA regulations govern VOC emissions from adhesive systems used in direct-mount and peel-and-stick installations, while REACH restricts hazardous substance content in imported glass and ceramic glazes entering European markets. BIS certification requirements in India enforce dimensional tolerance and lead-content limits for domestic mosaic tile production. Stakeholders must monitor adhesive chemistry compliance across multiple jurisdictions as specification standards diverge between residential and commercial end-use codes.
Market Dynamics
Hotel renovation cycles are compressing specification timelines, forcing procurement teams to pre-approve mosaic tile palettes before ground breaks on hospitality projects. REACH compliance deadlines in Europe and EPA VOC thresholds in the United States are simultaneously tightening adhesive chemistry requirements, bifurcating supply chains between compliant and legacy product lines.
Growth Catalysts
- Hospitality Interiors:Hotel renovation cycles are accelerating procurement volumes as asset managers refresh properties ahead of brand standard updates. Wet-area applications in spa and pool environments favor ceramic mosaic durability.
- REACH Compliance:European hazardous substance restrictions are filtering out low-grade imports, creating shelf space for certified producers who invested in lead-free glaze formulations ahead of enforcement windows.
- Peel-and-Stick Formats:Labor scarcity in residential renovation channels is pulling simplified mesh-mounted systems into DIY segments previously served by professional tile setters.
Market Restraints
- Silica Sand Volatility:Glass mosaic production depends on high-purity silica sand concentrated in limited coastal deposits, exposing margin structures to freight cost swings and extraction permitting delays.
- Gujarat-Rajasthan Concentration:Indian ceramic mosaic output clusters in two adjacent states, creating geographic risk exposure to monsoon logistics disruptions and state-level electricity tariff fluctuations.
- Porcelain Substitution:Large-format porcelain panels are capturing wall cladding share in commercial lobbies and elevator cores, compressing mosaic specification to accent strips and art installations.
Strategic Opportunities
- Wellness Infrastructure:Thermal spa and hammam construction in Saudi Arabia and the UAE is creating demand for heat-resistant glass mosaic systems with specialized epoxy setting materials.
- BIS Certification Tailwind:India's mandatory dimensional tolerance and lead-content standards are accelerating formalization of domestic supply, rewarding organized producers with public project eligibility.
- Digital-Physical Convergence:Architects are specifying parametrically designed mosaic gradients that require CNC waterjet cutting of stone tesserae, opening premium fabrication services adjacent to commodity tile sales.
Industry Challenges
- Skilled Setter Scarcity:Mesh-mounted mosaic installation demands precise lippage control and grout color matching that apprentice programs are failing to replenish at replacement rates.
- Multi-Jurisdiction Adhesive Certification:Specifiers now require VOC documentation spanning EPA Method 24, French VOC A+ labeling, and German AgBB protocols, extending product qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mosaic Tiles Market |
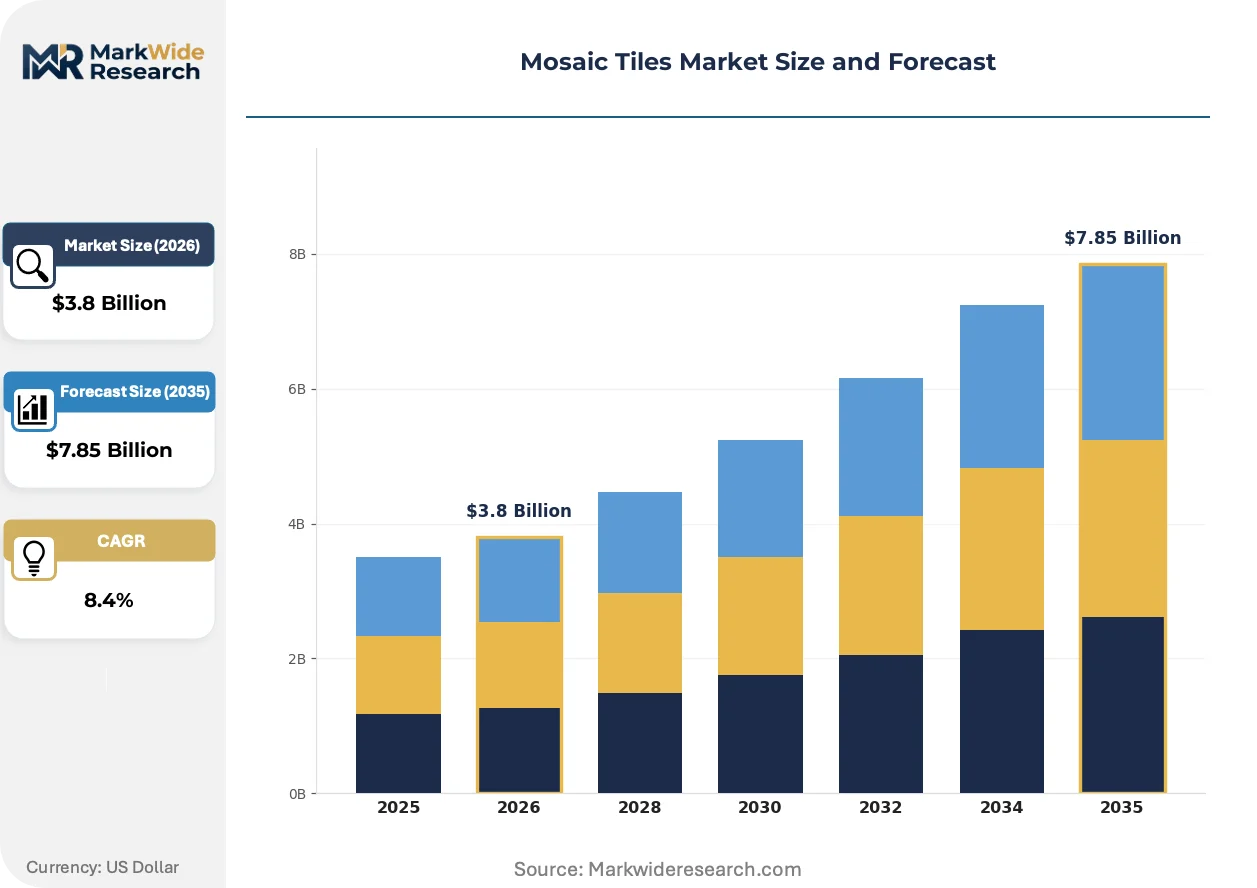
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Ceramic, Stone, Metal, Porcelain, Shell Application: Residential Flooring, Commercial Wall Cladding, Landscape Decoration, Art Installations, Swimming Pool Decoration, Hospitality Interiors Installation Type: Direct Adhesive, Mesh-Mounted, Peel and Stick, Float Mounting End User: Interior Designers, Contractors, Property Developers, Artisans |
| Companies Covered | Kajaria Ceramics, Florim Ceramiche, Mohawk Industries, Emser Tile, Crossville, Grupo Lamosa, Porcelanosa Grupo, Roca Group, RAK Ceramics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mosaic Tiles Market Trends and Innovations
Digital specification tools are compressing the path from architect concept to purchase order, while material science advances enable thinner, lighter mosaic systems that reduce structural load and shipping cube.
Recycled glass smalti is displacing virgin silica feedstock in premium hospitality applications. Boutique hotel chains in California and New York are specifying 100% post-consumer content for LEED v4.1 interior credits. This material shift is compressing traditional glass mosaic margin structures while opening volume pathways through municipal recycling contracts.
EPA Method 24 VOC testing protocols are tightening enforcement on adhesive manufacturers serving the North American market. Industrial consequence includes reformulation of solvent-based epoxy systems toward zero-VOC acrylic alternatives. Commercial peel-and-stick segments are absorbing the compliance cost fastest, while traditional thin-set applications lag in certification completion.
Architects are unbundling material specification from installation contracting, creating direct procurement relationships with mosaic producers that bypass traditional distributor markup layers. Boutique hospitality projects in Miami and Los Angeles are piloting this model, with design-build firms absorbing inventory risk in exchange for palette exclusivity on signature properties.
Mosaic Tiles Market Segmentation
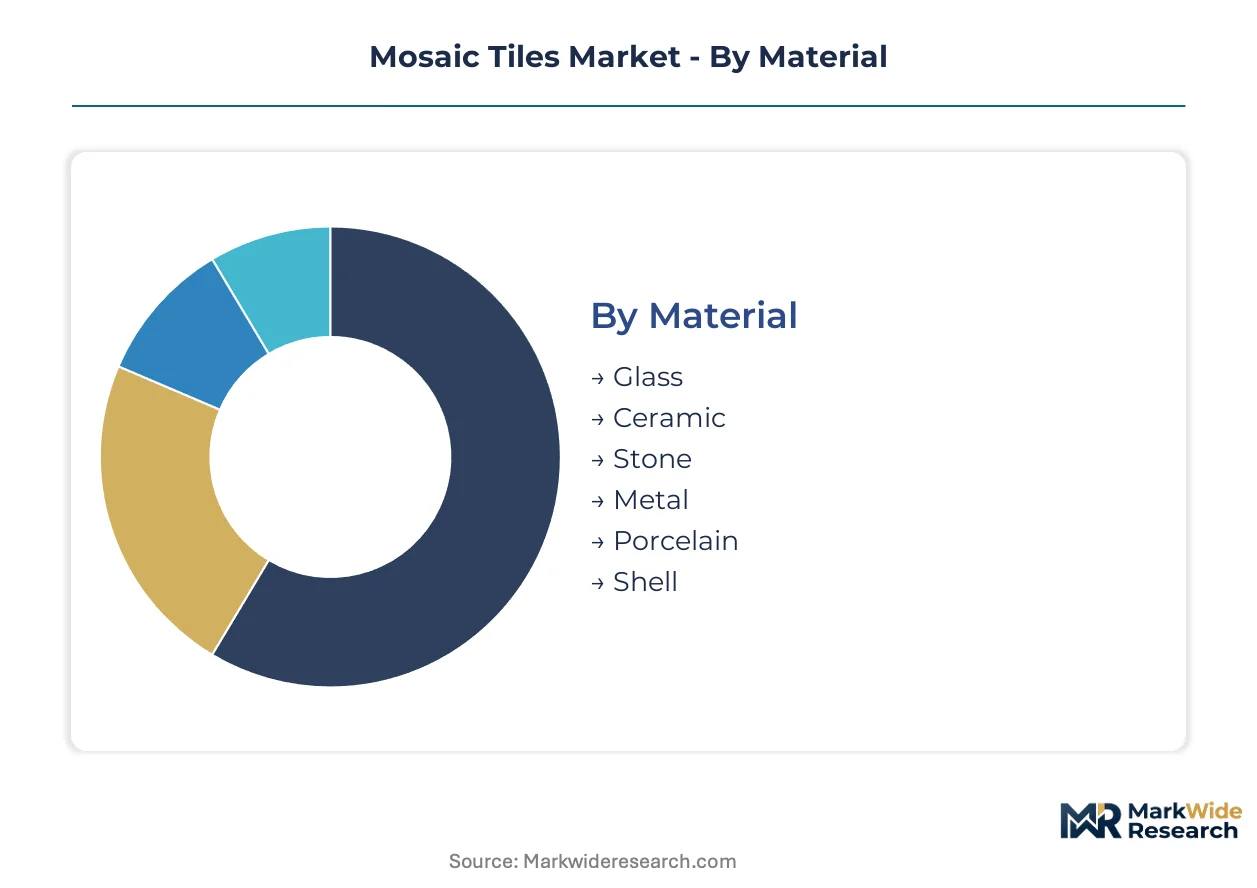
Mosaic tile procurement channels fragment sharply by material chemistry and installation complexity. Specification authority has shifted from general contractors toward specialized designers and hospitality procurement teams, rewiring traditional distribution hierarchies.
Material:
Channel mix varies dramatically by material density and fragility. Glass and ceramic flow through distributor networks to contractor channels, while stone and metal concentrate in direct architect-producer relationships for premium projects.
- Ceramic:Fired clay bodies with water absorption below 0.5 percent anchor volume in wet-area commercial specifications. Hospitality renovation cycles in India and the UAE concentrate procurement through Gujarat production clusters facing BIS certification mandates.
- Glass:Smalti and fused silica compositions command margin pools in art installation and thermal spa applications. California and New York boutique hotel chains specify 100% post-consumer recycled content for LEED v4.1 compliance, compressing traditional margin structures.
- Stone:Marble, travertine, and granite tesserae serve luxury residential and monumental architecture through direct quarry-to-project channels.
- Metal:Stainless steel and copper mosaics target elevator cores and feature walls in commercial lobbies, bypassing mesh-mounted systems for precision-cut direct adhesion.
- Porcelain:Vitreous ceramic bodies with extreme density compete against large-format panels in high-traffic flooring specifications.
- Shell:Mother-of-pearl and abalone surfaces occupy niche artisan markets for bespoke residential bathrooms and yacht interiors.
Ceramic dominates installed base. Glass is where expansion concentrates.
Application:
Cost tier stratification separates commodity flooring from premium architectural interventions. Residential applications absorb price-sensitive mesh-mounted systems while commercial wall cladding tolerates complex labor for visual impact.
- Hospitality Interiors:Hotel spa, pool, and guest bathroom specifications demand slip-resistant ceramic and heat-resistant glass systems. Saudi Arabia and UAE thermal hammam construction is pulling specialized epoxy setting materials through direct procurement channels.
- Commercial Wall Cladding:Lobby and elevator core applications face substitution pressure from large-format porcelain panels, compressing mosaic specification to accent strips and art interventions.
- Residential Flooring:Kitchen and bathroom renovations favor mesh-mounted ceramic for cost efficiency, though peel-and-stick formats are gaining traction where labor scarcity bites hardest.
- Swimming Pool Decoration:Frost-resistant glass and porcelain systems with specialized grout chemistry serve commercial aquatics through certified installer networks.
- Art Installations:Parametrically designed gradients requiring CNC waterjet cutting of stone tesserae open premium fabrication services adjacent to commodity sales.
- Landscape Decoration:Exterior paving and water feature applications specify freeze-thaw resistant porcelain and stone through landscape architect channels.
Commercial wall cladding holds the deepest specification heritage. Hospitality interiors are climbing the fastest.
Installation Type:
Volume concentration favors mesh-mounted efficiency in commercial projects, while residential renovation channels pull simplified formats where apprentice pipelines fail to replenish skilled setter ranks.
- Mesh-Mounted:Paper or fiberglass sheet backing enables rapid field installation with precise lippage control. Commercial hospitality projects specify this format exclusively, though skilled setter scarcity extends project timelines.
- Peel and Stick:Pressure-sensitive adhesive backing eliminates thin-set curing time, capturing residential DIY segments and renovation contractor channels facing labor shortages.
- Direct Adhesive:Traditional thin-set application persists in exterior and wet-area specifications requiring maximum bond strength and freeze-thaw resistance.
- Float Mounting:Mechanical anchoring systems for exterior facade applications allow thermal expansion in curtain wall assemblies, specified by facade engineers on high-rise commercial towers.
Mesh-mounted systems command current volume leadership. Peel-and-stick formats show the steepest expansion trajectory.
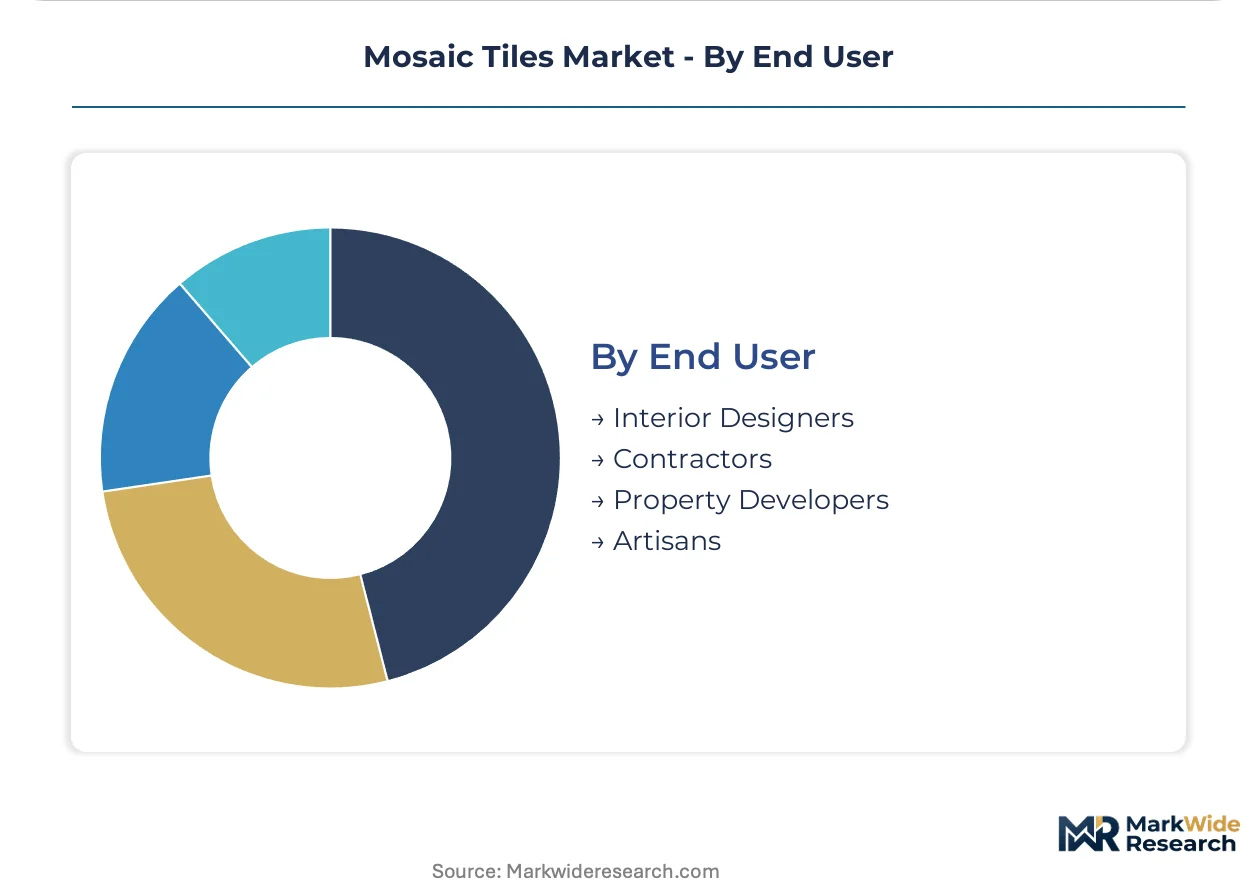
End User:
Customer type determines margin capture and channel control. Interior designers and hospitality procurement teams are unbundling specification from installation contracting, collapsing traditional distributor markup layers.
- Interior Designers:Specification authority concentrates in boutique hospitality and luxury residential channels. Miami and Los Angeles design-build firms pilot direct producer relationships, absorbing inventory risk for palette exclusivity.
- Contractors:General construction and renovation contractors dominate residential flooring volume through distributor relationships, though margin compression limits brand loyalty.
- Property Developers:Commercial multifamily and hospitality asset managers pre-approve mosaic palettes ahead of ground-breaking, compressing specification timelines and favoring certified producers with multi-jurisdiction adhesive documentation.
- Artisans:Studio fabricators and mosaic artists commission custom stone and glass tesserae through direct quarry and smalti producer relationships, bypassing standard distribution entirely.
Contractors retain volume dominance. Interior designers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports ceramic mosaic tiles to the United Arab Emirates and Saudi Arabia, serving thermal spa and hospitality construction corridors. European buyers source glass smalti through Italian and Spanish producer networks. North American distributors pull mesh-mounted systems from Mexican assembly plants serving renovation contractor channels.
India
Hospitality renovation cycles and public infrastructure projects drive ceramic mosaic procurement through Gujarat and Rajasthan production clusters. BIS certification mandates enforce dimensional tolerance and lead-content limits on domestic manufacturers. Morbi in Gujarat anchors the country's largest ceramic tile production belt, where organized producers are gaining public project eligibility through compliance investments.
United States
Hotel asset managers and residential renovation contractors absorb peel-and-stick formats amid skilled setter scarcity. EPA Method 24 VOC testing protocols compel adhesive reformulation toward zero-VOC acrylic systems. Distribution concentrates in the Southeast and Southwest, where captive retail channels serve contractor networks with certified product documentation.
United Arab Emirates
Thermal hammam and luxury hospitality construction pull heat-resistant glass mosaic systems with specialized epoxy setting materials. MOHAP and municipal building codes enforce surface material safety standards for wet-area applications. Dubai's design district hosts specification studios where architects direct procurement from Indian and Italian producer networks.
Germany
Commercial facade and wellness infrastructure projects specify freeze-thaw resistant porcelain and stone tesserae. REACH restrictions filter hazardous substance content in imported glazes, favoring certified European producers. The Rhine-Ruhr industrial corridor distributes mesh-mounted systems through specialized tile merchant networks serving renovation markets.
Italy
Art installation and boutique hospitality channels sustain demand for CNC waterjet-cut stone mosaics and recycled glass smalti. ECHA enforcement windows on lead-free glaze formulations protect domestic producer margins. The Emilia-Romagna ceramic district maintains direct architect relationships for parametrically designed gradient specifications.
Mosaic Tiles Market Competitive Landscape
Player mix skews toward integrated ceramic producers with captive raw material sourcing and distributor-owned retail networks. The competitive structure fragments across three tiers: multinational surface material conglomerates with cross-category portfolios, regional ceramic specialists with state-level production clustering, and artisan-scale studios serving bespoke architectural commissions. Dominant competitive moves include backward integration into frit and glaze chemistry, plus direct specification relationships with hospitality procurement teams that bypass traditional distribution markup layers.
Among India-based ceramic producers, Kajaria Ceramics and RAK Ceramics exemplify the scale-driven archetype with Gujarat manufacturing concentration and BIS certification compliance. Porcelanosa Grupo represents the vertically controlled design-to-retail model across Iberia and the Americas. Mohawk Industries anchors North American distribution density through captive retail channel ownership. These three entities illustrate divergent strategic paths: production cluster dominance, integrated retail control, and distribution network capture.
| Leading Market Players |
|---|
| Kajaria Ceramics |
| Florim Ceramiche |
| Mohawk Industries |
| Emser Tile |
| Crossville |
| Grupo Lamosa |
| Porcelanosa Grupo |
| Roca Group |
| RAK Ceramics |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Gujarat ceramic producers and UAE hospitality developers lock in silica sand supply access while anchoring price visibility across volatile monsoon shipping windows. These arrangements concentrate procurement power with organized manufacturers holding BIS certification, compressing spot-market liquidity for smaller Rajasthan competitors facing electricity tariff fluctuations.
Pricing Analysis
Current-generation mesh-mounted ceramic systems trade at substantial premiums over prior-generation direct-adhesive formats, while next-generation peel-and-stick variants command mid-tier positioning despite simplified labor requirements. Three-tier pricing structure across premium glass smalti, standard ceramic mesh-mounted, and economy unmounted tesserae segments reflects certification grade and volume scale differentiation. Pricing pressure stems from large-format porcelain panel substitution in commercial wall cladding, eroding mosaic specification to accent applications. Residential renovation contractors exhibit highest price sensitivity, while hospitality procurement teams absorb premium positioning for brand-standard compliance.
Supply Chain Analysis
Strategic stockpile preferences dominate among Indian ceramic producers buffering against monsoon logistics disruptions, while European glass smalti specialists maintain lean just-in-time inventories given Italian producer proximity. Manufacturing gravity centers on India, Italy, and Spain, with raw material dependencies spanning Rajasthan silica sand, Murano smalti craftsmanship, and Castellón glaze frits. Single-source vulnerability concentrates in high-purity coastal silica deposits for glass mosaic production. Distribution runs through captive retail networks in North America, specialized tile merchants in Germany, and direct architect relationships in Italian art installation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority unbundling from general contractors to interior designers and hospitality procurement teams constitutes a platform-economics inflection, with digital specification tools collapsing traditional distributor markup layers and enabling direct producer-buyer interoperability.
For Market Incumbents: Fortify backward integration into frit and glaze chemistry to defend margin position against REACH compliance cost absorption. Prioritize captive supply of lead-free formulations ahead of ECHA enforcement windows. Expand mesh-mounted capacity in Gujarat production clusters to capture BIS certification tailwinds in Indian public infrastructure procurement. For New Entrants and Emerging Players: Lead with peel-and-stick format innovation targeting North American residential renovation channels where skilled setter scarcity creates white-space opportunity. Pursue wellness infrastructure specification in Saudi Arabia and UAE thermal hammam construction through heat-resistant glass mosaic specialization. Establish direct relationships with Miami and Los Angeles design-build firms piloting inventory-risk absorption models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically controlled design-to-retail operations with captive architect specification relationships across Iberia and the Americas. Long-term viability favors producers with demonstrated multi-jurisdiction adhesive certification spanning EPA Method 24, French VOC A+ labeling, and German AgBB protocols. Target acquisition archetypes include organized Indian ceramic producers with BIS compliance and public project eligibility. Monitor skilled setter apprenticeship program replenishment rates as inflection indicator for labor-scarcity format adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glaze Chemistry | Captures REACH compliance margin protection through in-house lead-free formulation control. |
| Direct Architect Relationship Development | Bypasses distributor markup layers in Miami and Los Angeles boutique hospitality specification channels. |
| Peel-and-Stick Format Expansion | Addresses North American skilled setter scarcity through simplified residential renovation application. |
| Wellness Infrastructure Specialization | Secures UAE and Saudi thermal hammam demand through heat-resistant glass mosaic systems. |
| BIS Certification Investment | Unlocks Indian public project eligibility as dimensional tolerance mandates accelerate formalization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with ceramic plant managers, hospitality procurement directors, tile merchant network heads, and adhesive formulation chemists; and secondary validation through BIS certification databases, EPA Method 24 filing records, ECHA REACH substance restriction updates, and customs trade flows for silica sand and frit imports. Bottom-up triangulation across Gujarat and Rajasthan production cluster outputs converged with top-down hospitality construction spend estimates.
Across the projection horizon, the analytical framework modeled volume and value trajectories by material chemistry, installation complexity tier, end-user archetype, and regional regulatory cluster. CAGRs derived from segment-level growth rate synthesis applied to base-year sizing. Forecast inputs incorporated hotel renovation cycle velocity, adhesive reformulation compliance timelines, and large-format porcelain substitution elasticity in commercial wall cladding specifications.
The analysis sits within stated boundaries; outcomes outside sustained hospitality capital expenditure levels or accelerated REACH enforcement windows would require recalibration. Forecasts reflect documented assumptions regarding skilled setter pipeline replenishment and silica sand extraction permitting continuity. Revision becomes warranted when large-format porcelain panel substitution rates in elevator core applications cross thresholds that compress mosaic specification below accent-strip viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Exterior Wall System Market