
 Europe Construction Repair and Rehabilitation Chemicals Market | 2026-2036
Europe Construction Repair and Rehabilitation Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Construction Repair and Rehabilitation Chemicals Market Insights
Project finance for public infrastructure rehabilitation is fragmenting the competitive landscape, allowing mid-scale specialists to bid alongside integrated multinationals. Sika AG leverages its polymer technology leadership to anchor premium positions in bridge deck waterproofing across Alpine corridors. MBCC Group sustains manufacturing scale advantages in cementitious repair mortars through its dense Central European plant network. RPM International Inc. competes via brand strength in protective coatings for industrial facility refurbishment.
Construction repair and rehabilitation chemicals encompass polymer-modified cementitious systems, epoxy resins, polyurethane sealants, and acrylic coatings formulated to restore structural integrity, prevent moisture ingress, and extend service life of deteriorated concrete, masonry, and steel substrates. These materials typically achieve compressive strengths exceeding 30 MPa and bond strengths above 1.5 MPa to deteriorated substrates, enabling engineers to specify targeted intervention rather than full replacement. Grouts and injection systems dominate volume in infrastructure tunnel rehabilitation where void-filling and crack-sealing requirements are most acute. Polymer-based technologies command margin premiums in commercial facade restoration projects demanding aesthetic compatibility and rapid return-to-service. Cement-based formulations retain cost leadership in residential basement waterproofing where budget sensitivity shapes contractor selection.
REACH compliance and the EU Green Deal's carbon disclosure mandates are elevating formulation transparency requirements across the supply chain, with ECHA substance restrictions directly limiting certain epoxy hardener chemistries in member state markets. CE marking under the Construction Products Regulation remains mandatory for structural bonding and anchoring applications, creating documentation barriers for non-European suppliers. The EU F-Gas Regulation indirectly shapes demand by accelerating building envelope tightness standards that increase moisture-driven deterioration risks. Stakeholders must monitor evolving embodied carbon thresholds in public procurement frameworks, as these will progressively favor repair-over-replace strategies and chemically intensive intervention methods.
Market Dynamics
Bridge and tunnel maintenance programs across Germany, France, and Italy are fragmenting procurement authority toward regional infrastructure agencies. These agencies now specify low-cement polymer systems under embodied carbon benchmarks, reshaping supplier qualification requirements and technical documentation burdens.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Public procurement frameworks in member states progressively favor repair-over-replace strategies, expanding addressable market for structural intervention chemicals.
- Coastal concrete deterioration:Mediterranean member states including Spain, Greece, and Portugal accelerate rehabilitation cycles due to chloride-induced corrosion, concentrating demand for injection grouts and cathodic protection systems.
- Polymer-modified cementitious systems:These materials achieve compressive strengths exceeding 30 MPa while reducing cement content, aligning with decarbonization mandates in Alpine corridor infrastructure.
Market Restraints
- Epoxy resin feedstock volatility:Bisphenol-A and amine hardener prices fluctuate with crude oil derivatives, compressing margin stability for formulators of structural adhesives.
- ECHA substance restrictions:REACH Annex XVII limitations on certain aromatic amine hardeners directly constrain formulation options for tunnel waterproofing applications.
- Cement-based formulation cost leadership:Budget-sensitive residential waterproofing segments resist premium polymer technologies, capping price realization in high-volume basement repair markets.
Strategic Opportunities
- CE marking documentation services:Non-European suppliers face mandatory Construction Products Regulation compliance barriers, creating white space for EU-based technical consultancies and authorized representatives.
- Facade restoration aesthetics:Commercial building owners in Paris, Milan, and Vienna demand color-matched acrylic coatings with rapid return-to-service, commanding margin premiums over infrastructure-grade materials.
- EU F-Gas Regulation building envelope standards:Tightness requirements increase moisture-driven deterioration risks, expanding preventive maintenance chemical demand in Nordic and Central European markets.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise in polyurethane and epoxy systems concentrates among aging technical workforces in Germany and Switzerland, constraining R&D throughput for mid-scale specialists.
- CE marking certification timelines:Structural bonding and anchoring applications require extensive testing under European Technical Assessment procedures, delaying product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Construction Repair and Rehabilitation Chemicals Market |
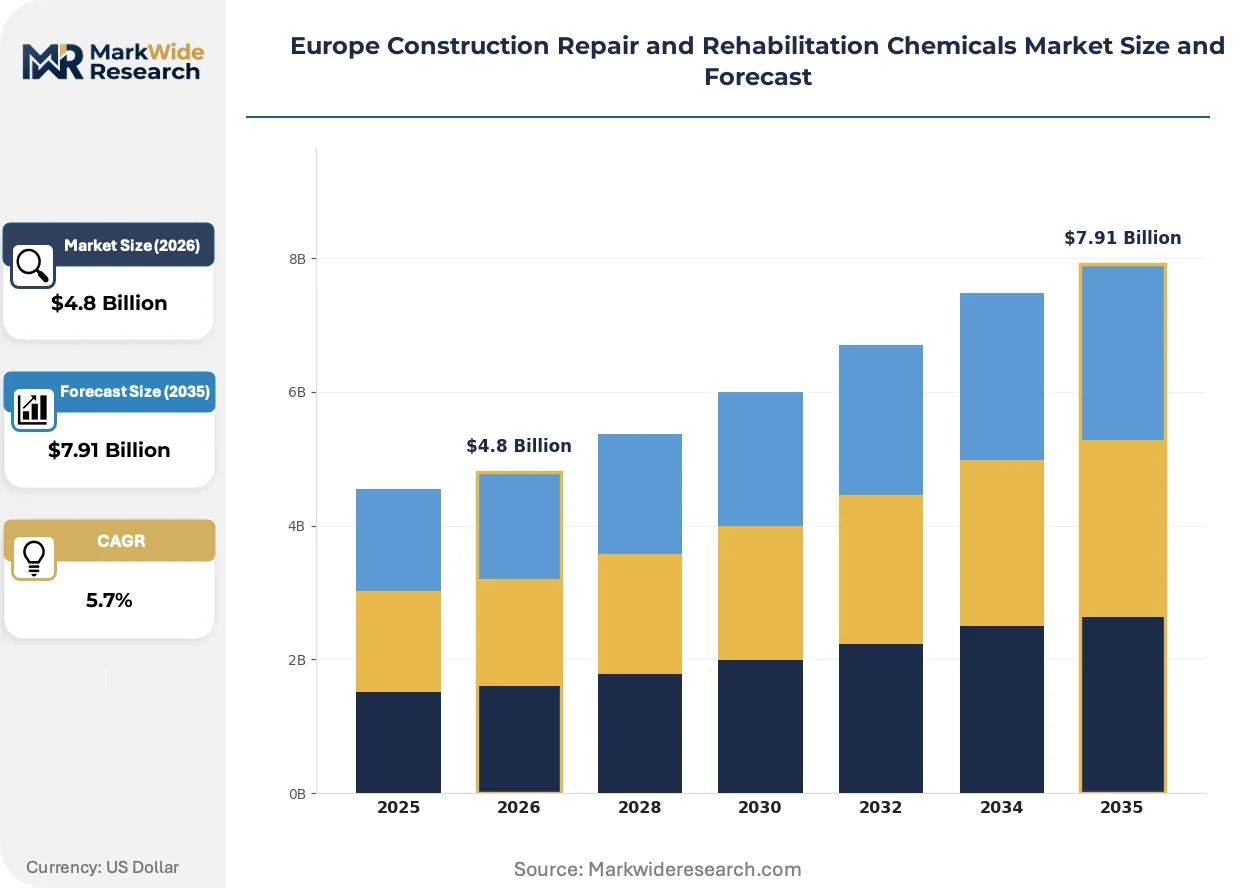
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Sealants, Grouts, Coatings Application: Infrastructure, Residential, Commercial, Industrial End User: Contractors, Architects, Government, Engineers Technology: Polymer-based, Cement-based, Epoxy, Others |
| Companies Covered | RPM International Inc., MBCC Group, Sika AG, Ardex Group, Fosroc Inc., MAPEI S.p.A., Remmers Gruppe AG, MC-Bauchemie, Saint-Gobain, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Construction Repair and Rehabilitation Chemicals Market Trends and Innovations
Formulation chemistry is pivoting toward bio-based and recycled-content raw materials as ECHA disclosure mandates deepen supply chain transparency. This shift is compressing traditional petrochemical feedstock dependence while opening technical differentiation avenues for early movers.
Low-cement ultra-high-performance concrete repair mortars are migrating from niche bridge deck applications toward standard tunnel rehabilitation specifications. German and Austrian infrastructure agencies now specify these systems for Alpine corridor maintenance, compressing procurement cycles from multi-year framework agreements to single-project tenders. The technology is enabling thinner application profiles that reduce material volumes and site congestion.
REACH compliance and the EU Green Deal's carbon disclosure mandates are elevating formulation transparency requirements across the supply chain. ECHA substance restrictions directly limit certain epoxy hardener chemistries, forcing reformulation investments among structural adhesive suppliers. Mediterranean member states with accelerated coastal deterioration cycles face the tightest compliance timelines due to higher chemical throughput.
Regional infrastructure agencies are consolidating procurement authority while fragmenting technical specifications. French departmental councils and Italian regional governments now issue separate tenders for injection grouts versus surface coatings, displacing bundled product supply contracts. This pattern is most visible in Rhône-Alpes and Lombardy, where maintenance budgets have devolved from national ministries.
Europe Construction Repair and Rehabilitation Chemicals Market Segmentation
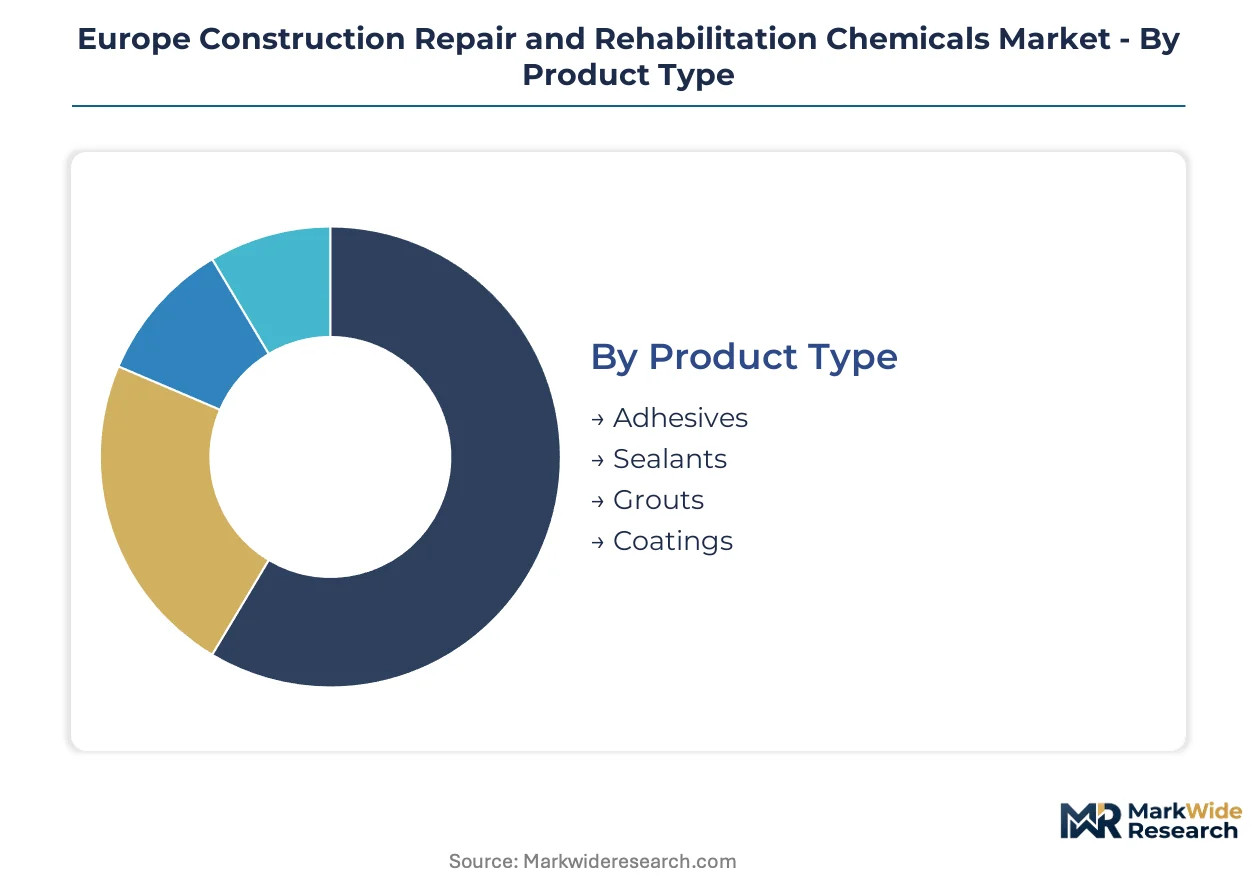
Segmentation reveals how procurement authority fragments across Europe's construction repair chemicals market. Specification power varies sharply by end-user type, while technology choices increasingly track embodied carbon compliance rather than pure performance metrics.
Product Type:
Cost tier differentiation separates premium polymer systems from commodity cementitious formulations across European procurement frameworks.
- Adhesives:Epoxy and polyurethane structural bonding systems achieve tensile strengths above 15 MPa for concrete-to-concrete and steel-to-concrete connections. German bridge deck specifications under DIN standards drive demand for thixotropic formulations that resist sag on vertical surfaces.
- Sealants:Polysulfide and silicone formulations accommodate joint movement up to 25% while resisting chloride ingress in Mediterranean coastal structures. Italian and Spanish infrastructure agencies specify these for tunnel expansion joints where thermal cycling stresses concentrate.
- Grouts:Cementitious and epoxy injection systems fill voids and stabilize rock anchors in Alpine tunnel rehabilitation.
- Coatings:Acrylic and polyurethane protective layers extend concrete service life in Nordic freeze-thaw environments.
Grouts hold installed capacity. Sealants are rotating up the share rankings.
Application:
Application scope determines regulatory exposure and procurement cycle length across member state markets.
- Infrastructure:Bridge, tunnel, and highway rehabilitation commands the most stringent CE marking requirements under the Construction Products Regulation. French departmental councils and Italian regional governments now unbundle injection grout tenders from surface coating contracts, fragmenting supplier relationships.
- Residential:Basement waterproofing and facade repair operate on compressed timelines with budget-constrained contractors. Cement-based crystalline waterproofing dominates this tier due to cost sensitivity among Central European renovation specialists.
- Commercial:Office and retail facade restoration in Paris, Milan, and Vienna demands color-matched acrylic coatings with rapid return-to-service.
- Industrial:Manufacturing facility floors and containment areas require chemical-resistant epoxy systems.
Infrastructure anchors specification authority. Commercial is gaining share fastest.
End User:
Customer type shapes technical documentation burdens and price realization potential.
- Contractors:Direct procurement concentrates in mid-scale waterproofing specialists across Germany and Austria. These firms prioritize pumpability and open-time consistency over laboratory-certified performance data.
- Architects:Specification influence peaks in commercial facade and heritage restoration projects. French architects under HQE certification frameworks increasingly mandate Environmental Product Declarations for repair mortars.
- Government:Regional infrastructure agencies in Rhône-Alpes and Lombardy now issue separate technical specifications for structural versus non-structural applications.
- Engineers:Structural design consultants drive epoxy adhesive selection for post-installed anchoring in seismic retrofit projects.
Contractors control volume throughput. Architects are climbing the influence rankings.
Technology:
Technology maturity determines compliance trajectory under REACH and EU Green Deal mandates.
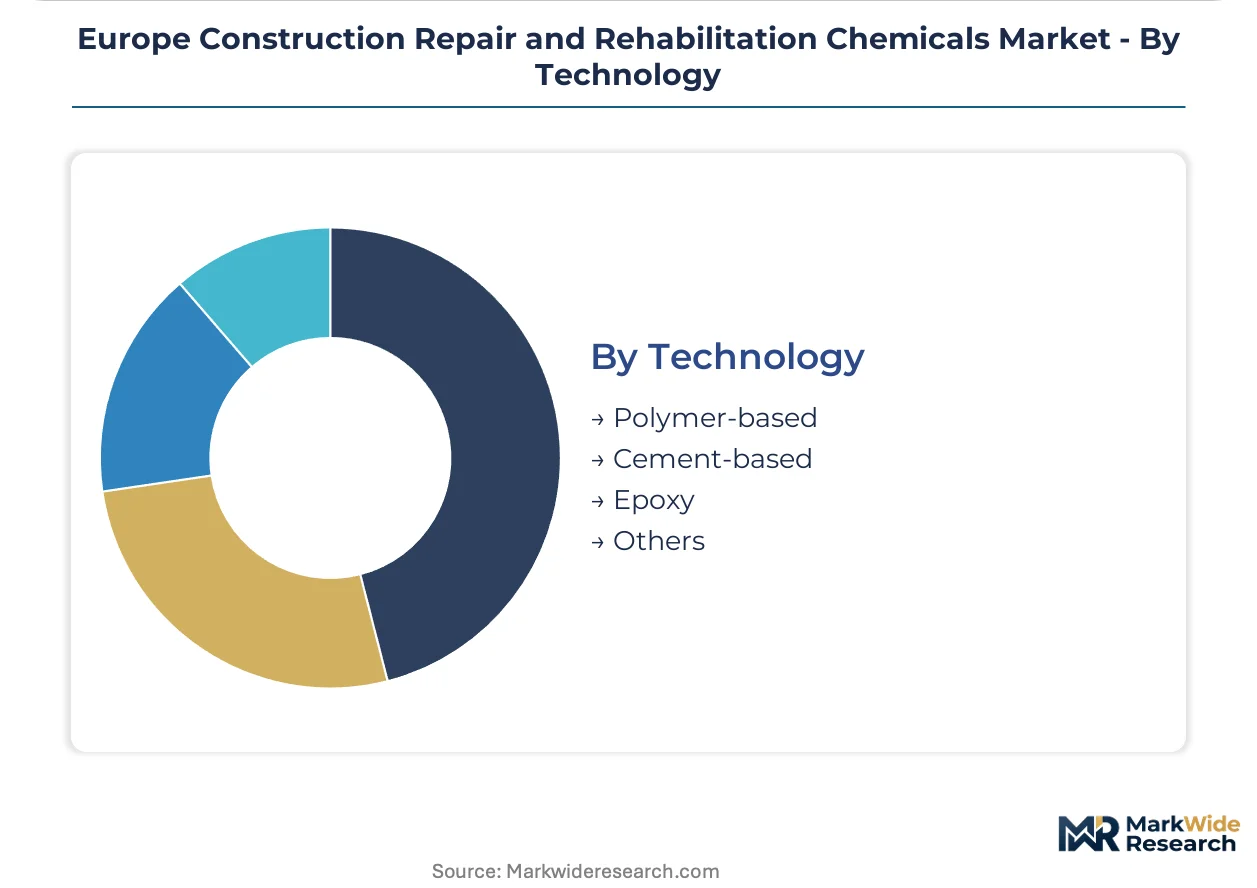
- Polymer-based:Acrylic, polyurethane, and hybrid systems achieve rapid cure and aesthetic compatibility. These formulations command margin premiums in Alpine corridor bridge waterproofing where Sika AG anchors premium positioning.
- Cement-based:Ordinary Portland cement and blended systems retain cost leadership in residential waterproofing. MBCC Group sustains manufacturing scale advantages through its dense Central European plant network.
- Epoxy:Two-component structural adhesives face ECHA restrictions on aromatic amine hardeners.
- Others:Bio-based and recycled-content raw materials emerge as technical differentiation avenues.
Cement-based holds installed capacity. Polymer-based is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German infrastructure agencies command premium pricing for low-cement polymer systems, while Mediterranean contractors face compressed margins on cementitious formulations. This asymmetry reflects divergent regulatory enforcement timelines and embodied carbon procurement mandates across member states.
Germany
Alpine corridor bridge maintenance and tunnel rehabilitation drive demand for thixotropic epoxy adhesives and injection grouts. DIN standards and the Federal Ministry for Digital and Transport's embodied carbon benchmarks favor polymer-modified cementitious systems with reduced clinker content. Bavaria and Baden-Württemberg concentrate specification authority where regional infrastructure agencies unbundle coating and grout tenders.
France
Departmental councils in Rhône-Alpes and Île-de-France accelerate facade restoration and heritage structure rehabilitation. HQE certification frameworks mandate Environmental Product Declarations for repair mortars, elevating documentation burdens on suppliers. Paris-based architects specify color-matched acrylic coatings for commercial building envelopes, commanding rapid return-to-service premiums.
Italy
Regional governments in Lombardy and Veneto issue separate technical specifications for structural versus non-structural applications. Coastal chloride-induced corrosion in Campania and Sicily concentrates demand for cathodic protection systems and polysulfide sealants. CE marking enforcement under the Construction Products Regulation delays product launches for tunnel waterproofing suppliers.
Spain
Mediterranean coastal deterioration in Catalonia and Andalusia shortens rehabilitation cycles for concrete infrastructure. ECHA substance restrictions on aromatic amine hardeners constrain formulation options for structural adhesive suppliers serving Barcelona and Valencia metro projects. Public procurement frameworks progressively embed repair-over-replace criteria under EU Green Deal transposition.
Netherlands
Randstad urban consolidation drives basement waterproofing and foundation repair demand among renovation specialists. Delta Programme climate adaptation funding elevates specifications for moisture-resistant coatings in below-grade applications. Eindhoven-based contractors prioritize pumpability and open-time consistency in cementitious crystalline waterproofing selection.
Europe Construction Repair and Rehabilitation Chemicals Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation technology. The vendor base separates into consolidated multinationals with dense manufacturing footprints and mid-scale specialists competing on technical documentation agility. Three archetypes dominate: polymer technology leaders anchoring premium bridge and tunnel positions, cementitious scale players optimizing Central European logistics, and coating brand houses leveraging specifier relationships in commercial restoration. Competitive moves concentrate on CE marking certification services for non-European entrants and backward integration into bio-based raw material sourcing.
Among Swiss and German platform integrators, Sika AG and MBCC Group exemplify divergent scale-positioning strategies. Sika AG anchors premium polymer system supply across Alpine infrastructure corridors. MBCC Group sustains manufacturing density advantages through distributed Central European plant networks. RPM International Inc. represents the brand-driven archetype in protective coatings for industrial facility refurbishment. These three occupy positions that illustrate how technology depth, geographic manufacturing scale, and specifier channel control segment competitive terrain.
| Leading Market Players |
|---|
| RPM International Inc. |
| MBCC Group |
| Sika AG |
| Ardex Group |
| Fosroc Inc. |
| MAPEI S.p.A. |
| Remmers Gruppe AG |
| MC-Bauchemie |
| Saint-Gobain |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in German cementitious repair mortar production is compressing supplier margins while forcing polymer system specialists to anchor premium positioning through technical differentiation. This utilization asymmetry between commodity and specialty tiers shapes procurement behavior across regional infrastructure agencies and contractor networks.
Pricing Analysis
The customization-premium spread separates configured-to-order polymer systems from standard cementitious formulations by 40-60 percent at the project level. Three-tier pricing structure across premium, standard, and economy levels tracks CE marking certification grade and volume scale, with bridge deck waterproofing commanding the widest spreads. Cost compression in residential basement waterproofing is intensifying because cement-based crystalline systems retain contractor preference on bid sheets. Government infrastructure agencies show least price sensitivity, while renovation specialists in the Netherlands and Austria exhibit acute budget responsiveness.
Supply Chain Analysis
Contract manufacturing concentration sits with MBCC Group's distributed Central European plant network and Sika AG's captive polymer synthesis facilities in Germany and Switzerland. Raw material dependencies draw from petrochemical feedstocks in the Netherlands and Belgium, Portland cement clinker from Poland and Turkey, and specialty amine hardeners from Swiss chemical producers. Single-source vulnerability in aromatic amine supply chains constrains epoxy adhesive formulators under ECHA Annex XVII restrictions. Distribution runs through authorized applicator networks and technical distributor channels serving regional infrastructure agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's embodied carbon thresholds are accelerating specification turnover faster than formulation cycles can adapt, compressing competitive advantage windows for suppliers unable to document Environmental Product Declarations.
For Market Incumbents: Build regulatory documentation moats by securing CE marking under European Technical Assessment procedures for structural bonding applications before ECHA restrictions tighten further. Anchor backward integration into bio-based raw material sourcing to deflect margin pressure from petrochemical volatility. Deepen technical service capabilities for regional infrastructure agencies unbundling coating and grout tenders in Rhône-Alpes and Lombardy. For New Entrants and Emerging Players: Mid-market commercial facade restoration in Paris, Milan, and Vienna represents the most penetrable entry point, as color-matched acrylic coatings with rapid return-to-service command margin premiums with lower certification barriers than infrastructure-grade systems. CE marking documentation services for non-European suppliers offer immediate revenue without manufacturing capital. Target technical consultancy partnerships with French architects under HQE certification frameworks to bypass direct competition with established applicator networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across polymer-modified cementitious system production as ECHA compliance and carbon disclosure mandates elevate R&D and testing expenditures. Acquisition candidates should demonstrate existing European Technical Assessment coverage and established relationships with Alpine corridor infrastructure agencies. Quarterly review of public procurement framework revisions in Germany, France, and Italy is advised to detect inflection toward repair-over-replace criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Raw Materials | Reduces petrochemical exposure while meeting EU Green Deal carbon disclosure mandates for public tenders. |
| CE Marking Documentation Services | Captures white space from non-European suppliers facing Construction Products Regulation compliance barriers. |
| Regional Infrastructure Agency Partnerships | Secures position as unbundled tenders fragment procurement authority in Bavaria and Lombardy. |
| Environmental Product Declaration Investment | Enables specification capture under French HQE and evolving Alpine corridor embodied carbon benchmarks. |
| Technical Service Capability Expansion | Differentiates polymer system supply where DIN standards and project complexity elevate support requirements. |
Research Methodology
Initial hypotheses were tested against primary input from technical R&D directors at polymer formulators, procurement leads at regional infrastructure agencies, distribution channel partners serving Alpine corridor contractors, and plant managers at cementitious mortar facilities and refined through secondary validation. Primary fieldwork drew from customs and trade data, Cefic sector reports, SEC 10-K filings of listed chemical companies, and European Technical Assessment documentation. Bottom-up project pipeline analysis across bridge and tunnel rehabilitation programs was triangulated with top-down market sizing from formulation chemistry trade flows.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including technology tier, application type, end-user category, and regional regulatory cluster. CAGRs were derived from installed base deterioration curves and rehabilitation cycle compression in Mediterranean member states. Industry-specific forecast inputs incorporated chloride-induced corrosion rates in coastal concrete and EU F-Gas Regulation transposition timelines affecting building envelope standards.
Practitioners should monitor ECHA substance restriction proposals and EU Green Deal procurement framework revisions for early signals of specification disruption. Forecasts reflect assumptions regarding embodied carbon threshold enforcement timelines and polymer chemist workforce availability. Quarterly review of public tender unbundling patterns and REACH Annex XVII amendment schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
US Steel Merchant and Rebar Market