
 Roofing Underlay Market | 2026-2036
Roofing Underlay Market Size, Share, and Industry Trends Forecast 2026-2036
Roofing Underlay Market Analysis
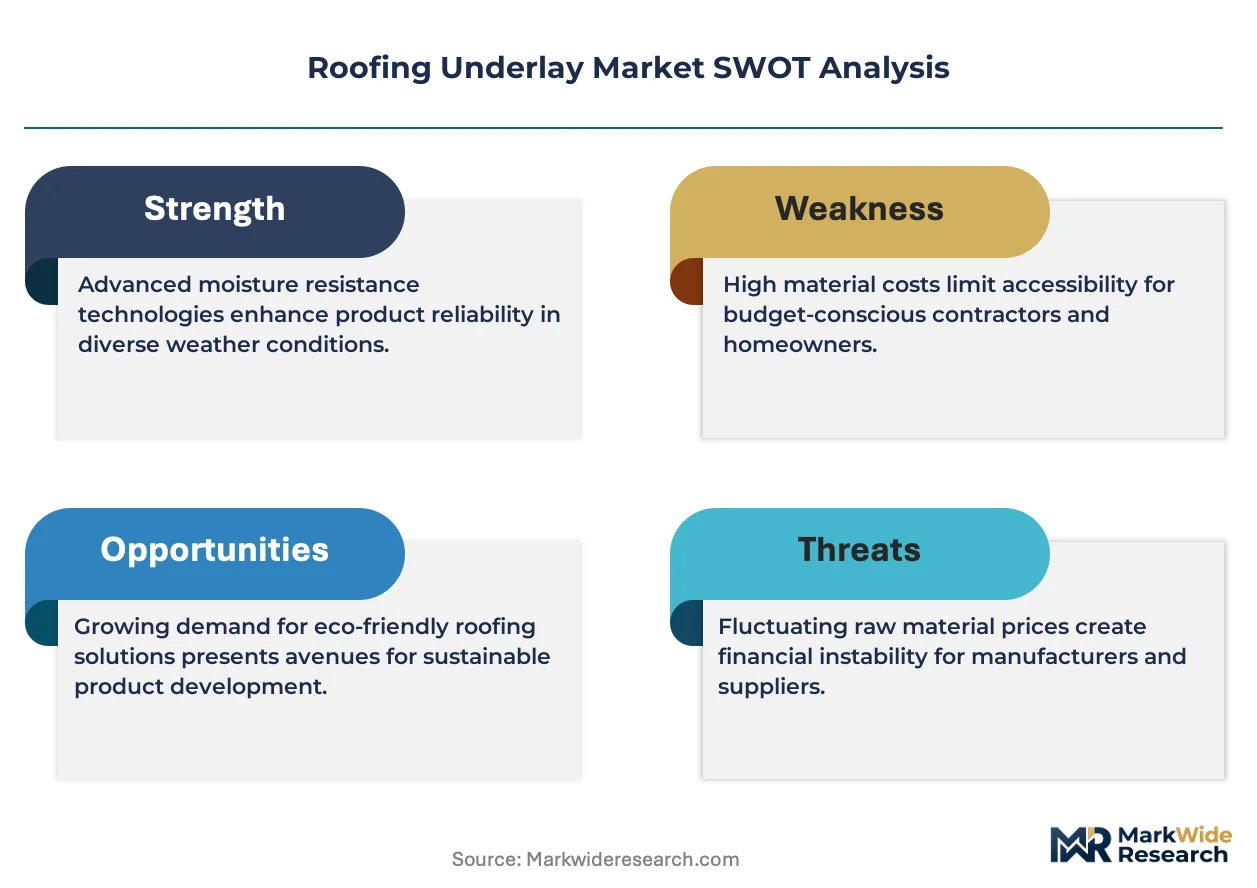
The gap between premium synthetic underlay and commodity felt is expanding in material performance, warranty terms, and contractor channel positioning. Owens Corning leverages its shingle-integrated ecosystem to bundle synthetic underlay with asphalt roofing systems. GAF Materials anchors the North American contractor supply chain through its national distribution network. DuPont de Nemours, Inc. differentiates via Tyvek-branded breathable membrane technology that extends into steep-slope residential applications.
Roofing underlay constitutes a secondary water-shedding barrier installed between the roof deck and primary weatherproofing layer, typically specified at 15 to 30 perms permeance and tested to ASTM D226 or ASTM D6757 standards. Its primary purpose is to protect the structure from wind-driven rain and ice dam infiltration during primary covering failure or installation intervals. Synthetic underlay leads product type growth due to lighter roll weights and longer UV exposure tolerance during construction delays. Mechanically attached installation dominates volume across steep-slope residential jobs, while self-adhering membranes command premium positioning in low-slope commercial and ice-dam-sensitive geographies. Polypropylene captures material share from asphalt-saturated felt on cost stability and recycled content credentials.
The US International Building Code and Florida HVHZ amendments shape product certification requirements, mandating ASTM D1970 self-adhering membranes in designated wind zones. ECHA REACH restrictions on bitumen emissions and EU Construction Products Regulation CE marking govern European material composition and labeling. ASTM, ISO 9001, and ICC-ES evaluation reports collectively determine market access for new membrane entrants across North American jurisdictions. Stakeholders must monitor evolving state-level wildfire ignition resistance standards and polymer feedstock volatility as dual determinants of product mix and margin stability.
Market Dynamics
The roofing underlay sector is bifurcating around material performance tiers as synthetic membranes displace asphalt-saturated felt in wind-uplift zones. Code amendments in hurricane-prone states now mandate enhanced secondary barriers, compressing contractor specification flexibility and accelerating product substitution cycles.
Growth Catalysts
- Florida HVHZ amendments:The state's High Velocity Hurricane Zone code revisions now require ASTM D1970 self-adhering membranes in designated wind corridors. This mandates product upgrade cycles across residential re-roofing.
- Synthetic polypropylene technology:Lighter roll weights and extended UV tolerance reduce jobsite labor costs and weather-delay risk. Coastal contractors increasingly specify these materials for multi-phase projects.
- Sun Belt housing stock aging:Concentrated demand for roof replacement across Texas, Arizona, and Florida converges with stricter wind uplift testing requirements. This geography now drives North American volume.
Market Restraints
- Polymer feedstock volatility:Propylene monomer price swings compress synthetic underlay margin stability. Manufacturers face margin compression when resin costs spike without corresponding pricing power.
- Chinese membrane oversupply:Low-cost Asian imports pressure domestic pricing in commodity segments. US distributors struggle to maintain premium positioning against undifferentiated imports.
- ASTM D226 felt substitution floor:Asphalt-saturated organic felt retains code acceptance in low-wind zones. This technical limitation caps synthetic penetration in rural and inland markets.
Strategic Opportunities
- Self-adhering membrane expansion:Ice-dam-sensitive geographies in Minnesota and Wisconsin represent underpenetrated demand for peel-and-stick installation. These cold-climate applications command premium positioning.
- Wildfire ignition resistance standards:California's evolving Chapter 7A requirements create regulatory tailwind for mineral-surfaced underlay. Product development toward Class A assembly ratings opens new specification channels.
- E-commerce contractor supply:Direct-to-crew digital platforms bypass traditional distribution markup. This channel innovation captures younger contractor demographics in suburban growth corridors.
Industry Challenges
- ICC-ES evaluation report timelines:New membrane entrants face 12-18 month certification delays for code compliance. This timeline friction advantages incumbent suppliers with established evaluation reports.
- Multi-layer system integration:Synthetic underlay must perform within shingle-manufacturer warranty requirements. Compatibility testing with primary roofing systems demands technical coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roofing Underlay Market |
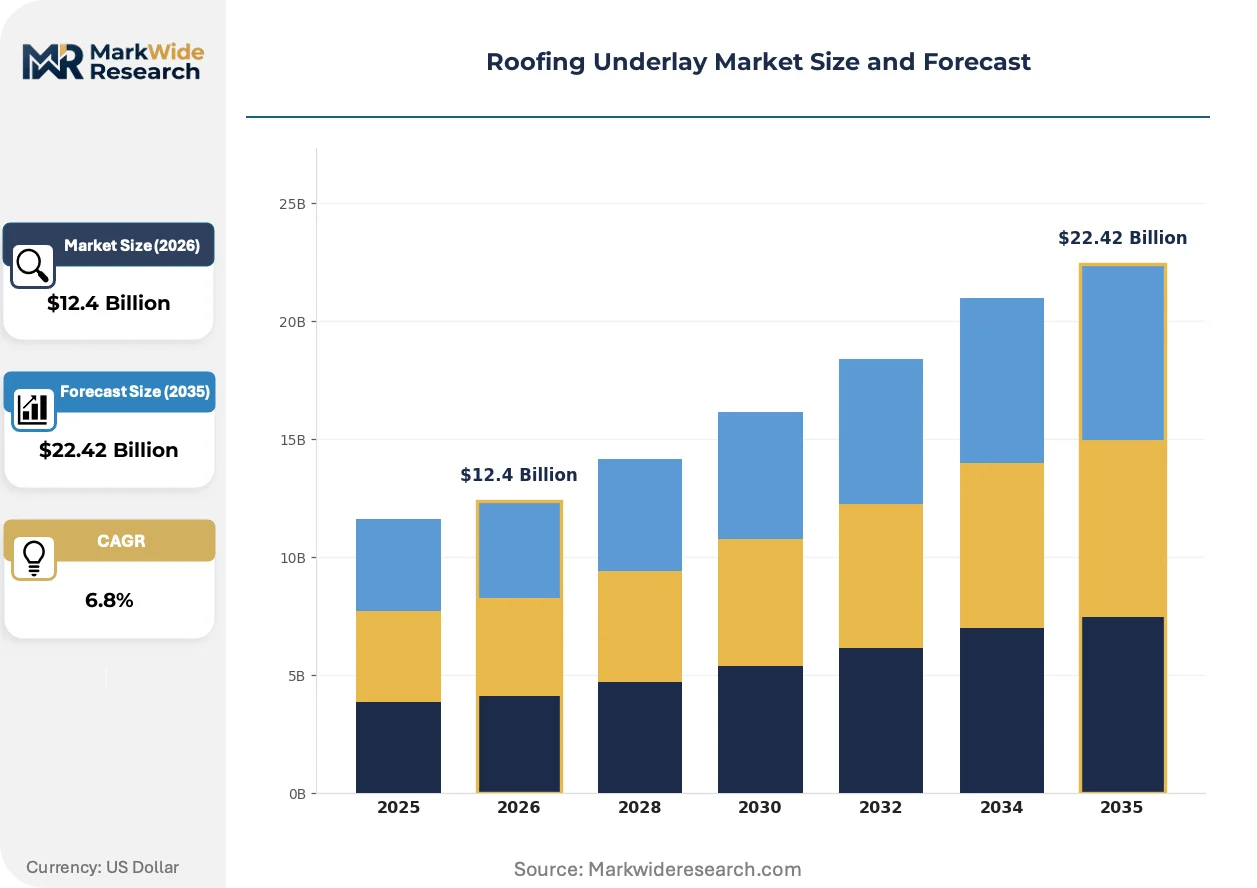
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Felt, Synthetic, Peel and Stick, Metal Material: Polypropylene, Polyester, Asphalt, Fiberglass Application: Commercial Roofing, Residential Roofing, Industrial Roofing, Agricultural Roofing Installation Type: Self-Adhering, Mechanically Attached, Loose Lay, Torch-On |
| Companies Covered | GAF Materials, Owens Corning, Atlas Roofing Corporation, DuPont de Nemours, Inc., Carlisle Companies Inc., CertainTeed Corporation, Johns Manville, IKO Industries, Inc., BMI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roofing Underlay Market Emerging Trajectories
Material science advances and code harmonization efforts are compressing product lifecycles while expanding performance thresholds. The sector is witnessing convergence between residential steep-slope and commercial low-slope membrane technologies.
Multilayer synthetic laminates is consolidating market structure around integrated breathable membranes. These constructions combine spunbond polypropylene with microporous films to achieve 15-30 perms permeance. High-end residential contractors in coastal Florida specify these systems for their UV exposure tolerance during extended construction delays. The technology is consolidating specification power among membrane specialists capable of in-house lamination.
ASTM D1970 harmonization across state amendments is tightening self-adhering membrane requirements. The standard's adoption into Florida HVHZ and Texas windborne debris regions mandates SBS-modified bitumen or butyl adhesive systems. Low-slope commercial roofing in the US Southeast faces the most acute compliance pressure, with contractors stockpiling certified inventory ahead of inspection backlogs.
Certification-driven specification is altering contractor procurement behavior. ICC-ES evaluation reports and manufacturer NOA approvals now filter distributor stocking decisions. Large roofing contractors in the US Sun Belt consolidate purchases through single-source agreements that bundle underlay with primary roofing systems, compressing independent membrane distributor margins.
Roofing Underlay Market Segmentation
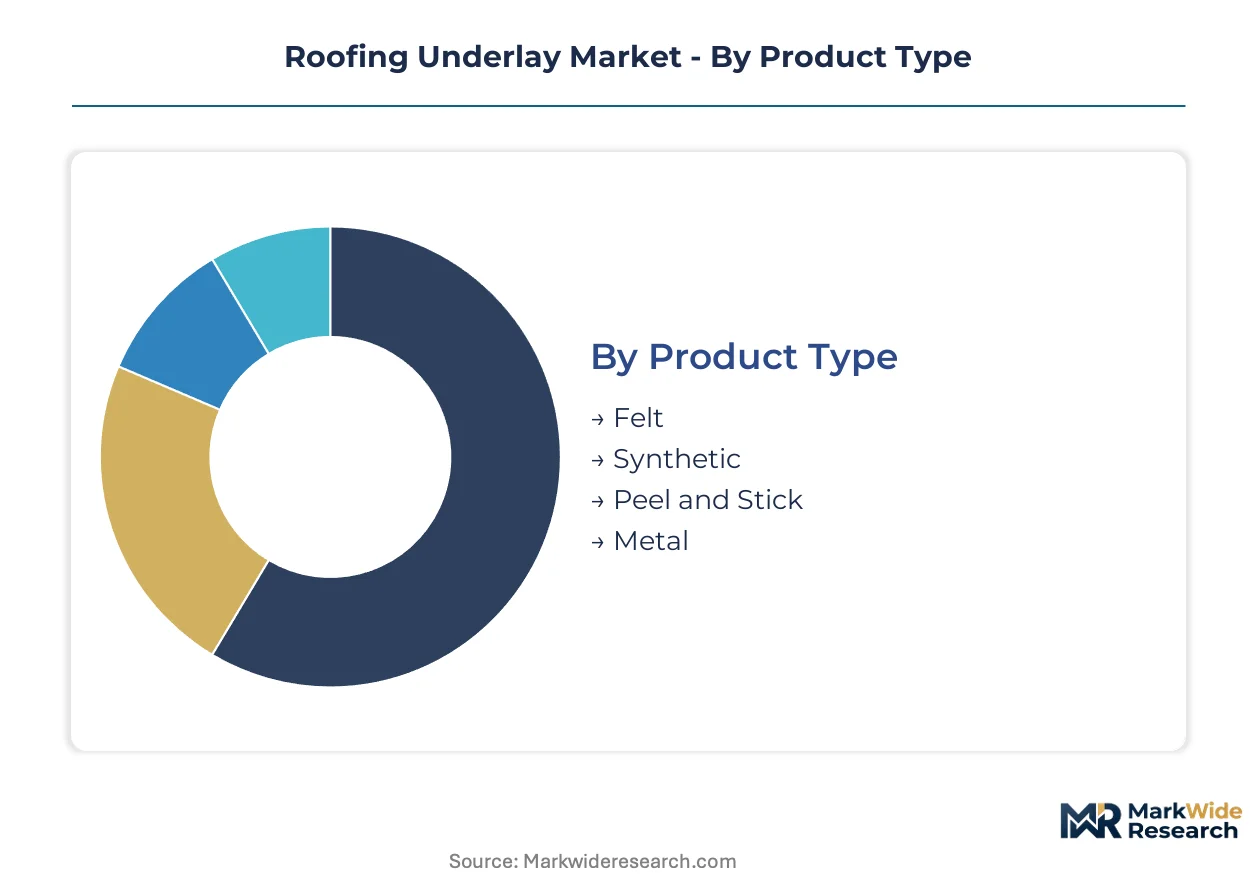
Roofing underlay segmentation reveals how material performance tiers align with code mandates and contractor procurement patterns. Specification decisions increasingly flow through building code compliance filters rather than pure cost optimization.
Product Type:
Volume concentrates in commodity felt, while premium positioning accrues to synthetic and self-adhering membranes with extended warranties and code certifications.
- Synthetic:Spunbond polypropylene or multilayer laminates deliver 30-180 day UV exposure tolerance and lighter roll weights for steep-slope residential jobs. Demand clusters in Florida HVHZ corridors and Texas coastal counties where ASTM D6757 compliance is mandatory for wind uplift resistance.
- Peel and Stick:SBS-modified bitumen or butyl adhesive systems provide self-sealing around fasteners and ice dam protection. Minnesota and Wisconsin residential re-roofing drives adoption where cold-climate water infiltration risks command premium specification.
- Felt:Asphalt-saturated organic or fiberglass mat retains code acceptance in low-wind inland zones. ASTM D226 Type I and II grades dominate rural re-roofing where cost sensitivity overrides performance premiums.
- Metal:Aluminum or copper underlayment provides fire resistance and extreme temperature durability. California wildland-urban interface zones specify these for Class A roof assembly ratings under evolving Chapter 7A amendments.
Mature deployment sits with Felt. Newer deployment is concentrated in Synthetic.
Material:
Feedstock cost stability and recycled content credentials now shape material selection as much as performance specifications.
- Polypropylene:Dominates synthetic underlay production through spunbond-meltblown-spunbond (SMS) constructions. The material's price stability versus asphalt bitumen and compatibility with recycled feedstocks drives specification in Sun Belt residential markets.
- Asphalt:Saturated organic and fiberglass felts rely on refinery byproduct bitumen supply. ECHA REACH emissions restrictions and volatile crude-linked pricing compress margin predictability for European and North American manufacturers.
- Polyester:Higher tensile strength and dimensional stability suit low-slope commercial membranes. Mechanically attached systems in warehouse and retail roofing specify these for puncture resistance during installation traffic.
- Fiberglass:Reinforced scrim or mat provides dimensional stability to asphalt-saturated composites. The material bridges felt and synthetic performance tiers at mid-market price positioning.
Feedstock volatility most affects Asphalt. Supply security most benefits Polypropylene.
Application:
End-use segmentation tracks construction cycle timing, with residential re-roofing leading volume and commercial new construction commanding project scale.
- Residential Roofing:Steep-slope asphalt shingle systems drive underlay consumption across re-roofing and new construction. Aging housing stock in Florida, Texas, and Arizona concentrates demand where 20-30 year roof replacement cycles converge with stricter wind uplift codes.
- Commercial Roofing:Low-slope membrane and metal roof systems require specialized underlay for thermal cycling and foot traffic. Distribution centers and retail construction in the US Southeast specify self-adhering or torch-on systems for building envelope continuity.
- Industrial Roofing:Manufacturing and logistics facilities prioritize chemical resistance and durability. Mechanically attached synthetic membranes dominate where process equipment emissions or heavy maintenance access demands robust secondary barriers.
- Agricultural Roofing:Barns, silos, and processing facilities balance cost constraints with moisture protection. Loose-lay or mechanically attached felt retains share where seasonal construction windows limit synthetic premium justification.
Replacement cycles dominate Residential Roofing. New construction scale concentrates in Commercial Roofing.
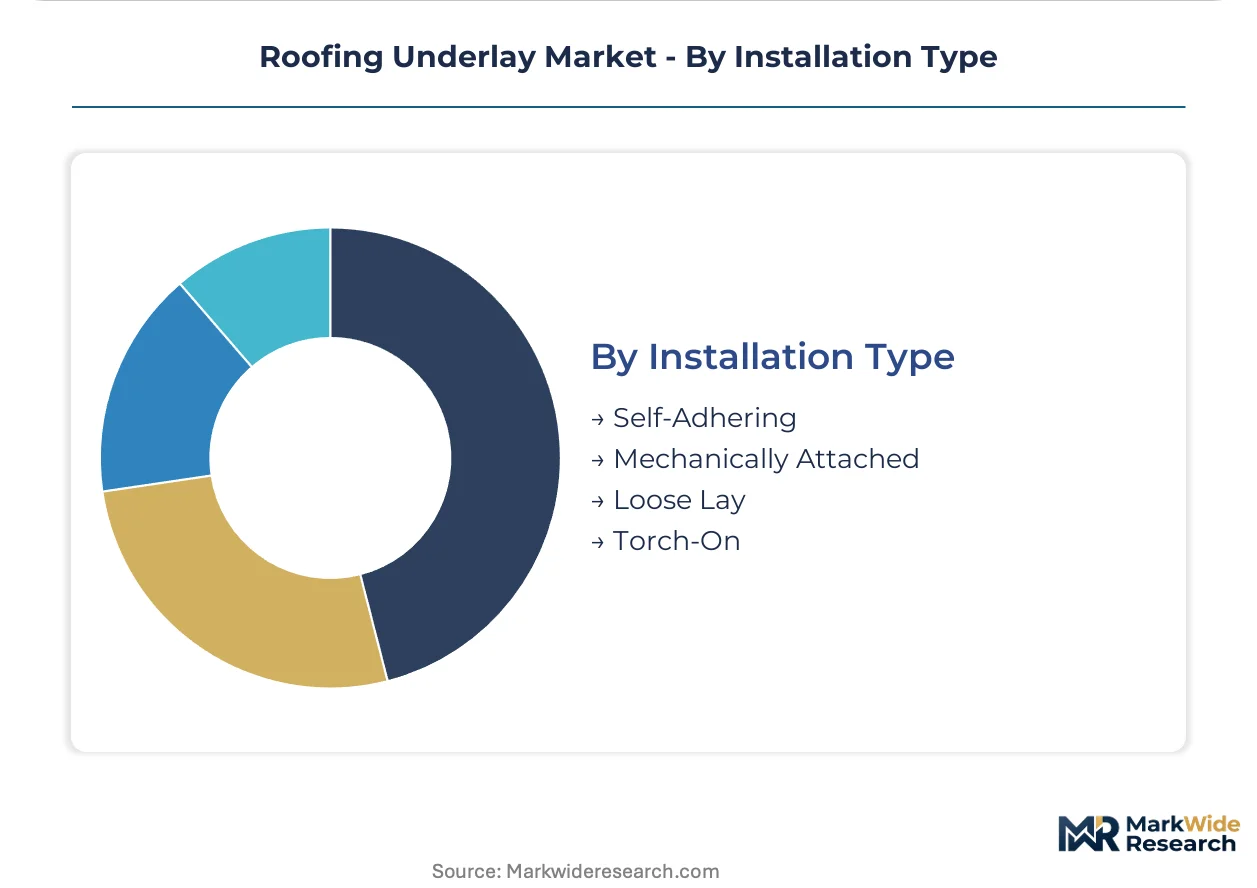
Installation Type:
Labor cost structures and climate risk profiles determine attachment method specification across contractor segments.
- Mechanically Attached:Cap staples or roofing nails secure underlay to deck in steep-slope residential applications. The method dominates volume due to speed and minimal surface preparation requirements.
- Self-Adhering:Peel-and-stick adhesive eliminates fasteners and provides self-sealing penetration protection. Ice-dam-sensitive geographies and HVHZ wind corridors mandate this for enhanced water barrier performance.
- Loose Lay:Unattached underlay relies on primary roofing system weight for retention. Agricultural and temporary protection applications use this for rapid deployment and material recovery.
- Torch-On:Heat-activated bitumen bonding suits low-slope commercial membranes requiring seam integrity. Specialized contractor certification and fire safety protocols limit adoption to trained crews.
Speed and labor efficiency favor Mechanically Attached. Code mandates and climate resilience drive Self-Adhering expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's Miami-Dade and Broward counties anchor North American roofing underlay consumption as hurricane-resistant building codes drive specification upgrades across residential re-roofing.
United States
Sun Belt housing stock aging and stricter wind uplift requirements concentrate demand in Texas, Arizona, and Florida. The International Building Code and Florida HVHZ amendments mandate ASTM D1970 self-adhering membranes in designated wind corridors. Houston and Dallas-Fort Worth metro areas experience accelerated synthetic underlay substitution as contractors stockpile certified inventory ahead of inspection backlogs.
Germany
Energy-efficient building renovation programs and steep-slope residential re-roofing sustain underlay demand across Bavaria and North Rhine-Westphalia. ECHA REACH restrictions on bitumen emissions and EU Construction Products Regulation CE marking govern material composition and labeling. Stuttgart's industrial corridor hosts membrane specialists developing multilayer breathable laminates for passive house construction standards.
China
Rapid urbanization and commercial construction expansion in the Yangtze River Delta and Pearl River Delta drive membrane consumption for low-slope roofing systems. GB standards and MIIT regulations establish product quality benchmarks for construction materials. Shanghai's Pudong district concentrates distribution infrastructure serving high-rise residential and logistics facility development.
Australia
Bushfire-prone construction zones and cyclone-resistant building codes elevate demand for fire-rated and high-wind-performance underlay across Queensland and New South Wales. The National Construction Code mandates specific secondary barrier performance in designated flame zones and wind regions. Sydney's western suburbs and Brisbane's growth corridors experience concentrated re-roofing activity as 1990s housing stock reaches replacement cycles.
Canada
Ice dam protection requirements and extreme cold-climate performance specifications drive self-adhering membrane adoption in Ontario and Quebec. National Building Code of Canada provisions and provincial amendments establish minimum underlay standards for residential steep-slope applications. Toronto's Greater Golden Horseshoe and Montreal's metropolitan area concentrate contractor networks and distribution infrastructure serving aging suburban housing stock.
Roofing Underlay Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and warranty positioning in the roofing underlay sector. The market structure consolidates around building materials conglomerates with integrated shingle-underlay systems and specialized membrane manufacturers with ICC-ES evaluation report portfolios. Three archetypes dominate: vertically integrated roofing system suppliers, standalone membrane specialists with lamination capabilities, and regional distributors with private-label sourcing relationships. Competitive moves center on backward integration into polymer feedstock and strategic partnerships with national contractor networks.
Within the integrated materials tier, GAF Materials and Owens Corning exemplify conglomerate positioning that bundles underlay with primary roofing systems. DuPont de Nemours, Inc. anchors the specialty membrane segment through Tyvek-branded breathable technology extending into steep-slope residential applications. These three companies represent distinct competitive vectors: national distribution scale, shingle-ecosystem integration, and technical differentiation through material science.
| Leading Market Players |
|---|
| GAF Materials |
| Owens Corning |
| Atlas Roofing Corporation |
| DuPont de Nemours, Inc. |
| Carlisle Companies Inc. |
| CertainTeed Corporation |
| Johns Manville |
| IKO Industries, Inc. |
| BMI Group |
| Others |
Supply Flow & Price Mechanics
Certified roofing contractor density in Florida's Miami-Dade corridor compresses labor-cost differentials into pricing-tier spreads between ASTM D1970-compliant self-adhering membranes and commodity felt alternatives. Coastal contractors command premium installation rates that amplify material-grade price gaps across the Sun Belt re-roofing market.
Pricing Analysis
Code compliance duration anchors value-based pricing for roofing underlay, with ASTM D1970 certification and ICC-ES evaluation reports commanding 40-60% premiums over uncertified alternatives. Price differentiation separates Florida HVHZ-mandated self-adhering membranes from inland mechanically attached synthetics and rural felt applications. Cost compression in commodity felt intensifies because Chinese membrane oversupply pressures distributor margins. Residential re-roofing contractors in inland Texas and Arizona exhibit highest price sensitivity, while commercial developers in hurricane corridors demonstrate lowest sensitivity due to insurance and warranty requirements.
Supply Chain Analysis
ICC-ES evaluation report requirements gate supply chain access for new membrane entrants, creating 12-18 month qualification timelines that favor incumbent suppliers with established certification portfolios. Manufacturing concentrates in the United States, China, and Germany, with polypropylene resin supply drawing from Gulf Coast petrochemical complexes and Asian polymer producers. Raw material dependencies center on propylene monomer, asphalt bitumen, and spunbond nonwoven fabrics. Single-source vulnerability sits with specialty SBS-modified bitumen formulations for self-adhering membranes. Distribution runs through national building materials distributors, regional roofing supply houses, and emerging direct-to-crew digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The roofing underlay sector is consolidating around certification-capable suppliers as Florida HVHZ amendments and polymer feedstock volatility force commodity felt producers toward exit or acquisition. Code-driven specification tightening compresses margin room for undifferentiated competitors.
For Market Incumbents: Hedge against polypropylene price volatility through captive resin agreements or backward integration into polymer feedstock. Secure ICC-ES evaluation report portfolios across multiple state jurisdictions to defend distributor shelf space against emerging membrane specialists. Channel control through national contractor network partnerships provides pricing power insulation from low-cost Asian imports.
For New Entrants and Emerging Players: Breathable multilayer laminate technology offers specification entry against established spunbond producers. Target Minnesota and Wisconsin ice-dam protection segments where peel-and-stick penetration remains below coastal hurricane zones. Pursue e-commerce contractor supply partnerships to bypass traditional distributor markups and capture younger crew demographics in suburban growth corridors.
For Investors and Strategic Acquirers: Re-rating potential sits with standalone membrane specialists holding ICC-ES evaluation report portfolios given California wildfire ignition resistance standard evolution. Five-to-ten-year viability favors acquisition targets with in-house lamination capabilities and established Florida NOA approvals. Monitor state-level wildfire code adoption timelines as inflection indicator for mineral-surfaced underlay demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive propylene supply insulates margin stability against resin price volatility spikes. |
| ICC-ES Evaluation Report Expansion | Multi-state certification portfolios unlock distributor stocking decisions across Sun Belt jurisdictions. |
| Direct-to-Crew Digital Platform Launch | Bypasses traditional distribution markup and captures younger contractor demographics in growth corridors. |
| California Chapter 7A Product Development | Class A assembly ratings open wildland-urban interface specification channels ahead of code enforcement. |
| National Contractor Network Partnership | Single-source bundling agreements compress independent membrane distributor margins and lock in volume. |
Methodological Framework
Trade association publications, building code amendment filings, and customs import records formed the secondary backbone for this analysis. Primary interviews with roofing contractor operations managers, building materials distributor procurement directors, membrane manufacturer technical sales leads, and state code enforcement officials validated demand patterns and specification trends. Bottom-up and top-down triangulation reconciled regional re-roofing activity data with product-level shipment reports.
Bottom-up volume modeling aggregated contractor crew capacity, permit issuance patterns, and material substitution rates across wind zone designations. Top-down validation cross-checked against polymer resin consumption disclosures and distributor inventory turnover benchmarks. Segmentation dimensions included product type, material composition, installation method, application sector, and regional code jurisdiction. CAGRs derived from regression analysis of replacement cycle timing, housing stock age distributions, and regulatory amendment implementation schedules.
Several conditions sit outside the modeled scope, including extreme weather event frequency beyond historical patterns, polymer feedstock supply disruptions from geopolitical conflict, and accelerated synthetic underlay degradation from unforeseen UV exposure conditions. Forecasts reflect assumptions about code amendment adoption timelines and contractor certification compliance rates. Stakeholders should weight assumptions against their own operating context and regional enforcement variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Basalt Fiber Reinforced Polymer BFRP Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Railing Market