
 Self-Healing Construction Materials Market | 2026-2036
Self-Healing Construction Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Healing Construction Materials Market Insights
Multi-source procurement of crystalline and capsule-based admixtures is realigning how contractors secure supply across project portfolios. BASF SE leverages its polymer research infrastructure to sustain technology leadership in microencapsulated healing agents. Wacker Chemie AG anchors European silicone binder supply for self-healing coating formulations. Autonomic Materials, Inc. specializes in corrosion-resistant microcapsule systems for infrastructure exposure conditions.
Self-healing construction materials encompass engineered compounds that autonomously repair microcracks through embedded vascular networks, mineral-precipitating bacteria, or polymerizable capsules activated by mechanical damage or environmental moisture, typically restoring 80-100% of original flexural strength within 28 days. Their primary purpose extends structural service life while reducing lifecycle maintenance expenditure in high-durability applications. Concrete products dominate current volume owing to established specification pathways in transportation infrastructure, while bio-based methods represent the fastest-expanding technology segment as environmental agencies tighten embodied carbon thresholds. Microcapsule systems command premium positioning due to compatibility with conventional batching equipment and predictable activation kinetics.
EPA stormwater infrastructure guidelines and EU Green Deal embodied carbon benchmarks are reshaping material qualification protocols for public works procurement. REACH chemical registration requirements constrain capsule shell chemistry options available to European formulators. ASTM standard development for autonomic healing performance testing is progressing through committee ballot stages in the United States. Stakeholders must monitor evolving certification timelines to align R&D pipelines with enforceable performance thresholds.
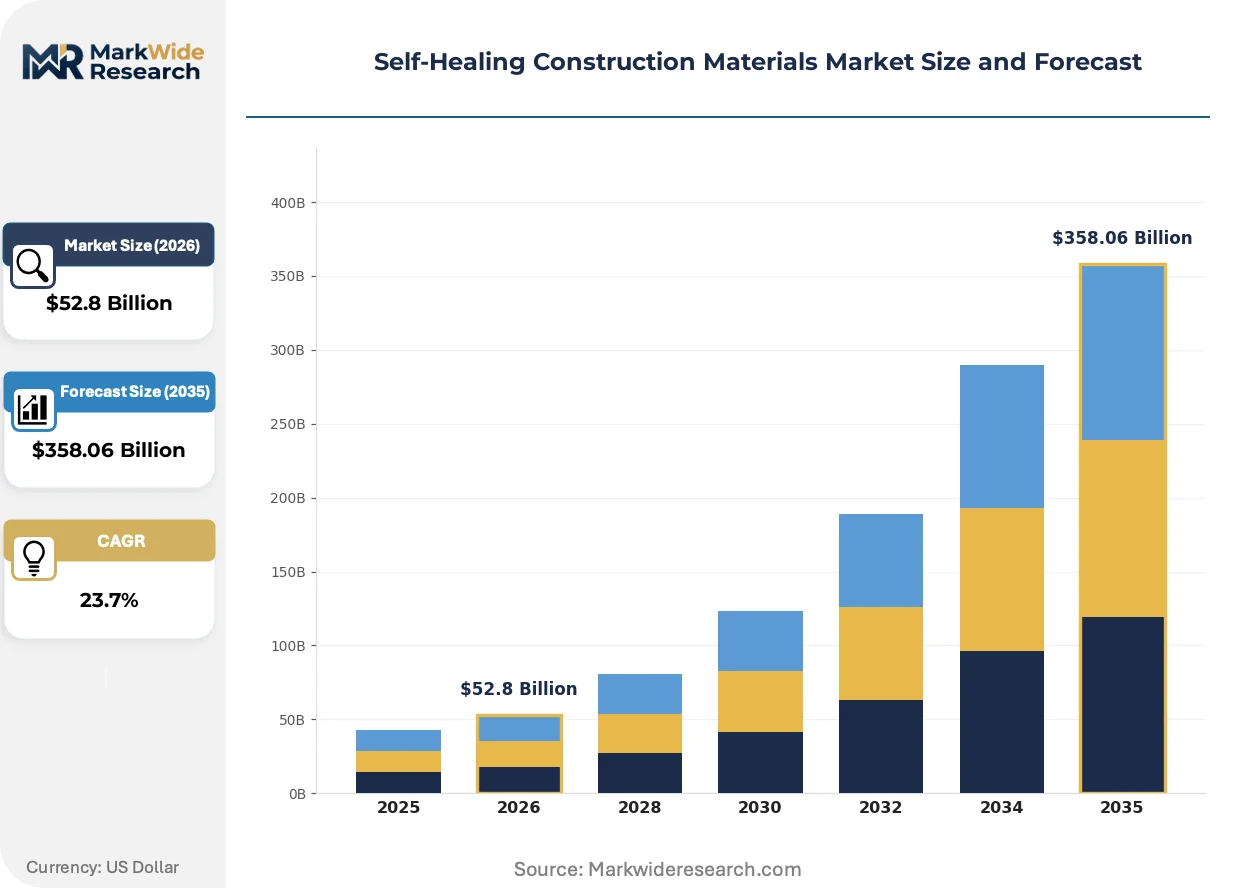
Market Dynamics
Bridge and tunnel operators in North America are scaling procurement of vascular concrete systems as lifecycle cost accounting replaces upfront bid pricing in public infrastructure awards.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Germany's Rhineland industrial corridor is accelerating material substitution timelines as contractors face enforceable carbon thresholds on public works.
- EPA stormwater infrastructure guidelines:US municipalities are qualifying self-healing concrete for detention vault and culvert rehabilitation projects requiring 50-year service life guarantees.
- Microcapsule activation kinetics:Predictable healing response windows are enabling specification in high-durability transportation applications where maintenance access is restricted.
Market Restraints
- REACH chemical registration constraints:European formulators face restricted capsule shell chemistry options as ECHA evaluates novel polymer systems for environmental persistence.
- Silicone binder supply concentration:Wacker Chemie AG's European production footprint creates geographic vulnerability for coating formulators dependent on specialty silicone intermediates.
- Bio-based bacterial spore viability:Mineral-precipitating bacteria formulations exhibit temperature-sensitive shelf stability limiting hot-climate deployment.
Strategic Opportunities
- India's PLI scheme for construction chemicals:Domestic manufacturing incentives are opening import-substitution pathways for crystalline admixture production serving South Asian infrastructure buildout.
- ASTM autonomic healing performance standards:Pending committee ballot completion in the United States will unlock federal procurement qualification for vascular network concrete systems.
- Offshore wind foundation specifications:Splash-zone exposure conditions in North Sea installations are creating demand for corrosion-resistant microcapsule coatings with 25-year maintenance intervals.
Industry Challenges
- Multidisciplinary formulation expertise scarcity:Material science, structural engineering, and microbiology skill convergence is required for bio-based system development, constraining R&D team assembly.
- Batching equipment integration complexity:Microcapsule shear sensitivity demands modified mixing protocols incompatible with legacy ready-mix plant configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Healing Construction Materials Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $358.06 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Concrete, Asphalt, Coatings Technology: Microcapsules, Vascular Systems, Bio-based Methods, Self-Repairing Polymers Application: Infrastructure, Residential, Commercial, Roadways End User: Contractors, Builders, Engineers, Environmental Agencies |
| Companies Covered | Xypex Chemical Corporation, Wacker Chemie AG, Green-Basilisk BV, Giatec Scientific Inc., Fescon Oy, Autonomic Materials, Inc., BASF SE, Acciona S.A., NEI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Healing Construction Materials Market Trends and Innovations
Vascular network concrete systems are rewriting procurement specifications across high-durability infrastructure as predictive maintenance models replace calendar-based intervention schedules.
Bacterial mineral precipitation technology is rewriting performance benchmarks for crack sealing in marine exposure conditions. Port authorities in the Netherlands and Denmark are piloting Bacillus-based systems for quay wall rehabilitation where tidal wet-dry cycling accelerates conventional concrete degradation. This biological approach is rewriting lifecycle cost calculations by eliminating epoxy injection labor from maintenance budgets.
REACH chemical registration requirements are tightening formulation disclosure obligations for capsule shell polymers sold into European public works. ECHA's expanded dossier demands are extending new product introduction timelines by 18-24 months for non-European suppliers. German admixture producers are responding by consolidating regulatory affairs functions and pre-subscribing novel chemistries ahead of commercial launch.
Performance-based contractor procurement is displacing unit-price bidding for transportation infrastructure maintenance contracts. State DOTs in the United States are bundling material supply with 20-year performance guarantees, transferring durability risk from public agencies to material suppliers and applicators. This contracting evolution is most advanced in California and Washington where climate exposure severity justifies premium material pricing.
Self-Healing Construction Materials Market Segmentation
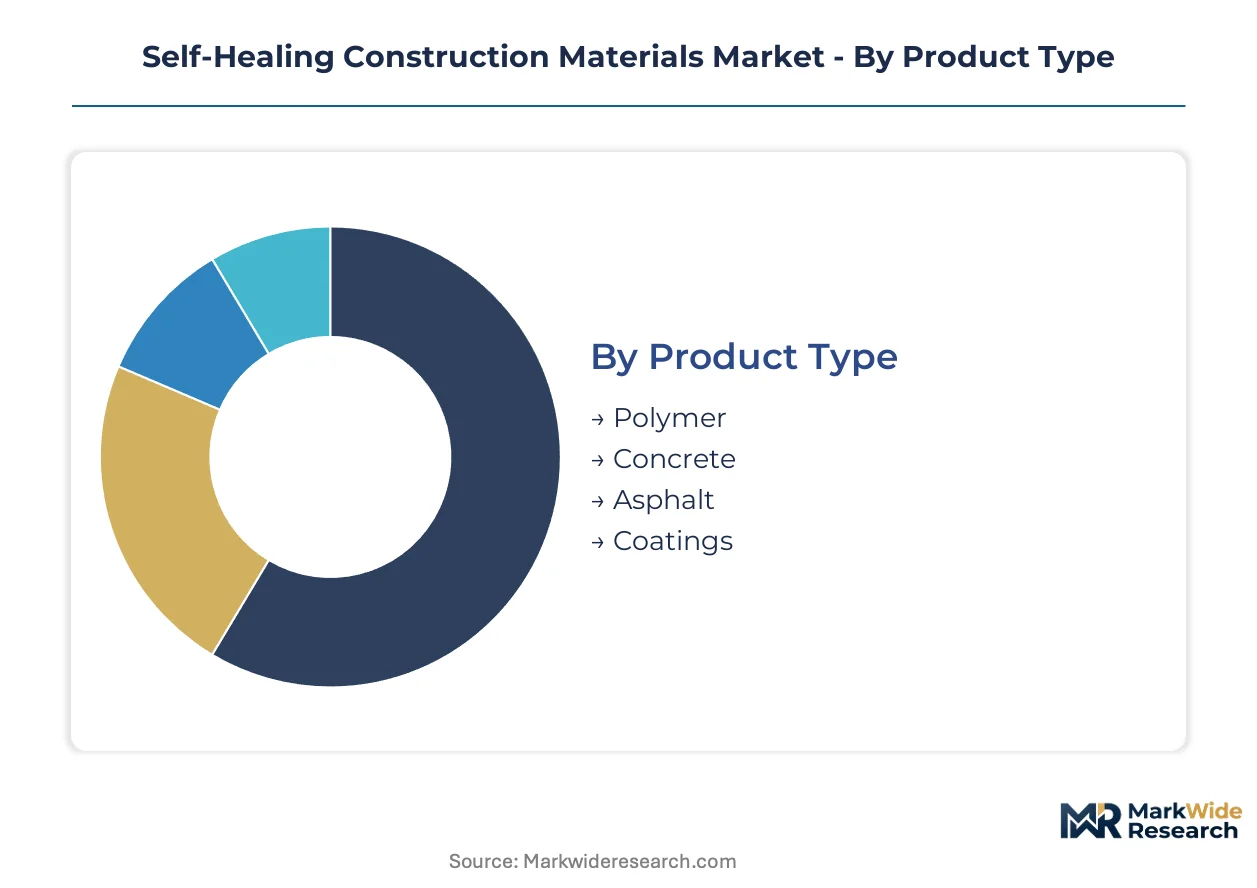
Segmentation in self-healing construction materials reflects divergent technical maturity and specification pathways across product categories. Contractors navigate procurement decisions where established concrete admixtures coexist with experimental bio-based systems requiring modified batching protocols.
Product Type:
Standardization dominates polymer and asphalt formulations while concrete and coating products demand project-specific customization.
- Polymer:Thermoplastic and thermoset matrices embed microcapsule healing agents compatible with injection molding and extrusion processes. German automotive suppliers are qualifying self-healing polymer seals for tunnel waterproofing membranes where mechanical puncture resistance is critical.
- Concrete:Cementitious matrices incorporate crystalline admixtures, vascular networks, or bacterial spores that precipitate calcium carbonate in crack voids. Bridge operators in the United States specify vascular concrete for deck overlays where 50-year service life guarantees override first-cost premiums.
- Asphalt:Bituminous binders integrate rejuvenating capsules that release healing oils under thermal cycling stress.
- Coatings:Elastomeric films with embedded microvascular channels or capsule-based corrosion inhibitors protect steel substrates in marine splash zones.
Most installed capacity flows through Concrete. Expansion is steepest in Coatings.
Technology:
Volume concentration favors microcapsule systems while capital intensity clusters around vascular network infrastructure.
- Microcapsules:Shell-core architectures rupture upon crack propagation to release polymerizable healing agents or mineral precursors. Compatibility with conventional ready-mix batching equipment drives specification in North American transportation infrastructure where plant retrofit costs are prohibitive.
- Vascular Systems:Hollow fiber networks or 3D-printed channels deliver healing reactants to damage sites through capillary action. Netherlands port authorities are piloting vascular concrete for quay walls where tidal wet-dry cycling demands predictable repair kinetics.
- Bio-based Methods:Dormant bacterial spores germinate in crack moisture to metabolize mineral precipitates.
- Self-Repairing Polymers:Intrinsic reversible bonding enables multiple healing cycles without external agent replenishment.
Microcapsules capture the dominant revenue share. Vascular Systems are climbing the fastest as lifecycle cost accounting displaces upfront bidding.
Application:
Public procurement volume concentrates in infrastructure while private development favors residential and commercial specifications.
- Infrastructure:Transportation, water management, and energy assets demand 50-100 year durability with minimal maintenance access. EPA stormwater guidelines are qualifying self-healing concrete for US municipal detention vaults requiring extended service intervals.
- Residential:Single-family and multi-family construction specify self-healing coatings for foundation waterproofing and basement crack prevention. German Passivhaus projects are integrating bacterial concrete for thermal envelope continuity where air sealing failures compromise energy performance.
- Commercial:High-rise and institutional buildings prioritize aesthetic durability in exposed concrete surfaces.
- Roadways:Pavement overlays and bridge decks subject to freeze-thaw degradation benefit from autonomic crack sealing.
Infrastructure commands the largest project pipeline. Residential is gaining share fastest as green building certifications tighten embodied carbon thresholds.
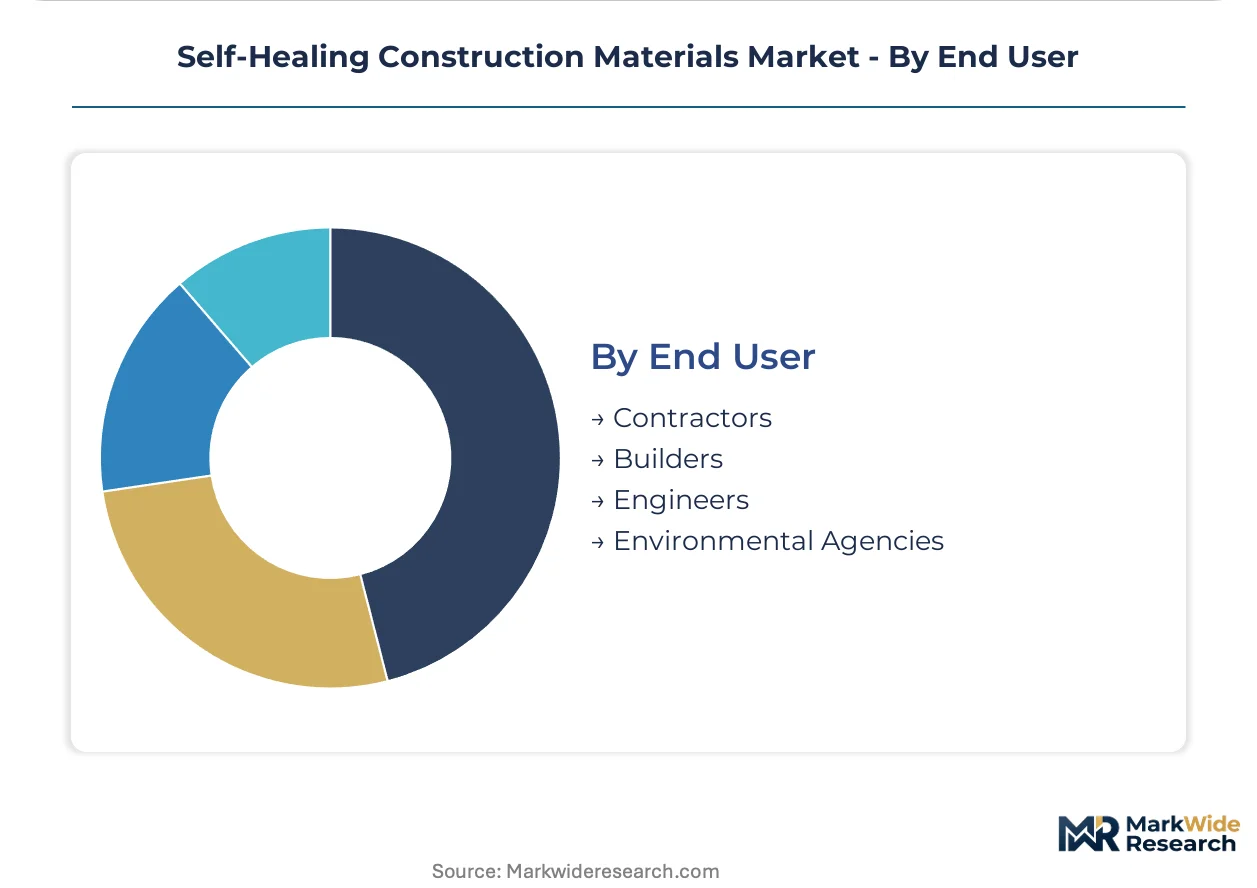
End User:
Risk tolerance varies sharply between speculative builders and public agency engineers with statutory liability exposure.
- Contractors:Construction firms executing design-build and performance-based contracts assume material durability risk. California DOT bundled procurements transfer 20-year maintenance liability to contractors specifying self-healing systems.
- Builders:Residential and commercial developers prioritize first-cost containment unless certification premiums justify material upgrades. Washington State energy code amendments are mandating extended building envelope warranties that favor self-healing coating specifications.
- Engineers:Structural and materials engineers specify performance thresholds and approve equivalency substitutions.
- Environmental Agencies:Regulators establish embodied carbon benchmarks and chemical registration requirements constraining formulation options.
Contractors absorb the largest procurement volume. Environmental Agencies are expanding their influence fastest through enforceable carbon thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland industrial corridor anchors procurement concentration for vascular concrete systems as EU embodied carbon mandates reshape material substitution timelines across European infrastructure markets.
United States
Bridge and tunnel operators in California and Washington are scaling vascular concrete procurement as lifecycle cost accounting displaces upfront bid pricing in state DOT awards. EPA stormwater infrastructure guidelines are qualifying self-healing systems for municipal detention vaults requiring 50-year service guarantees. The Pacific Northwest corridor concentrates pilot deployments where freeze-thaw exposure severity justifies premium material specifications.
Germany
Contractors in the Rhineland industrial corridor face enforceable carbon thresholds under EU Green Deal mandates that are compressing material substitution timelines for public works. ECHA's REACH chemical registration requirements are constraining capsule shell chemistry options available to domestic formulators. BASF SE's polymer research infrastructure in Ludwigshafen sustains technology leadership in microencapsulated healing agent development.
Netherlands
Port authorities in Rotterdam are piloting bacterial mineral precipitation systems for quay wall rehabilitation where tidal wet-dry cycling accelerates conventional concrete degradation. EU Green Deal embodied carbon benchmarks are tightening qualification protocols for marine infrastructure procurement. Dutch engineering consultancies are bundling 20-year performance guarantees with material supply contracts.
India
Domestic infrastructure buildout is creating import-substitution pathways for crystalline admixture production under the PLI scheme for construction chemicals. The country's national construction regulator is evaluating extended warranty frameworks for transportation infrastructure. Maharashtra and Gujarat industrial corridors are attracting capacity investments serving South Asian cement demand.
United Kingdom
Offshore wind foundation specifications in the North Sea are generating demand for corrosion-resistant microcapsule coatings with 25-year maintenance intervals. The Environment Agency is aligning stormwater asset standards with extended service life requirements. Scottish port authorities are testing vascular network concrete for splash-zone exposure conditions.
Self-Healing Construction Materials Market Competitive Landscape
Global majors compete with regional champions across technology licensing and specification influence, producing a tiered structure where polymer science conglomerates anchor premium positioning while specialized admixture formulators capture project-specific niches. Three archetypes dominate: diversified chemical conglomerates with polymer research infrastructure, dedicated construction chemical specialists with batching equipment integration expertise, and bio-technology ventures commercializing bacterial mineral precipitation systems. Competitive moves concentrate on backward integration into capsule shell polymer production and strategic partnerships with ready-mix plant operators to secure specification lock-in.
Among diversified chemical conglomerates, BASF SE and Wacker Chemie AG occupy positions that exemplify scale-driven technology leadership, with the former anchoring microencapsulated healing agent development and the latter controlling European silicone binder supply for coating formulations. Autonomic Materials, Inc. sits within the specialized corrosion-protection tier, representing the microcapsule systems archetype focused on infrastructure exposure conditions. These three companies illustrate how competitive positioning fragments across technology vectors rather than consolidating around geographic or scale advantages alone.
| Leading Market Players |
|---|
| Xypex Chemical Corporation |
| Wacker Chemie AG |
| Green-Basilisk BV |
| Giatec Scientific Inc. |
| Fescon Oy |
| Autonomic Materials, Inc. |
| BASF SE |
| Acciona S.A. |
| NEI Corporation |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up construction chemical specialists have consolidated regional admixture formulators across Germany and the Netherlands, concentrating procurement leverage over capsule shell polymer suppliers while enforcing price discipline through long-term offtake commitments tied to EU Green Deal compliance milestones.
Pricing Analysis
Input-cost pass-through from silicone intermediates and specialty polymer shells dominates pricing dynamics for coating formulators. Three-tier pricing structure across performance-guaranteed, specification-grade, and commodity admixture levels separates contractors bundling 20-year warranties from project-based procurement. Cost compression in standard crystalline admixtures is intensifying as Indian PLI-supported domestic capacity enters South Asian markets. Public infrastructure contractors exhibit lowest price sensitivity due to lifecycle cost accounting mandates, while speculative residential developers resist premiums without green certification requirements.
Supply Chain Analysis
Single-source vulnerability sits with Wacker Chemie AG's European silicone binder production, which feeds coating formulators dependent on specialty intermediates for marine splash-zone applications. Manufacturing concentrates in Germany, India, and the United States, drawing from epoxy resin precursors, bacterial spore cultures, and hollow fiber vascular networks. Tariff exposure on Chinese-sourced microcapsule shell polymers threatens margin stability for North American admixture blenders. Distribution runs through ready-mix plant technical partnerships rather than merchant chemical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory ratchet effects, with EU Green Deal embodied carbon mandates creating irreversible demand thresholds that lock in material substitution across public infrastructure procurement cycles.
For Market Incumbents: Deepen backward integration into capsule shell polymer production to offset REACH registration cost inflation and secure formulation autonomy against ECHA disclosure expansion. Anchor capacity expansion in India's Maharashtra industrial corridor to capture PLI scheme benefits and serve cement demand growth. Lock in specification influence through exclusive batching equipment integration partnerships with ready-mix plant operators.
For New Entrants and Emerging Players: Digital specification platforms bypassing incumbent distributor relationships offer direct access to contractor procurement teams evaluating performance-based material guarantees. Target residential Passivhaus segments in Germany where air sealing failures drive bacterial concrete adoption faster than infrastructure replacement cycles. Lead with bio-based bacterial mineral precipitation systems to differentiate from established microcapsule suppliers.
For Investors and Strategic Acquirers: Diversified chemical conglomerates with polymer research infrastructure are the most active acquirers in this space, seeking construction chemical adjacencies to leverage existing R&D scale. Five-to-ten year viability hinges on ASTM standard completion unlocking federal procurement qualification in the United States. Watch ASTM committee ballot progression as the decisive inflection signal for vascular network concrete market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Capsule Shell Polymers | BASF SE's polymer research infrastructure in Ludwigshafen demonstrates how captive supply secures formulation flexibility under REACH constraints. |
| Performance-Based Contractor Procurement | California DOT bundled contracts transfer 20-year maintenance liability, creating specification lock-in for qualifying material suppliers. |
| Bio-Based Bacterial System Commercialization | Green-Basilisk BV's quay wall pilots in Rotterdam establish marine exposure credibility that microcapsule systems cannot match. |
| ASTM Standard Pre-Subscription | Early regulatory affairs investment compresses new product introduction timelines for vascular network concrete systems. |
| PLI Scheme Capacity Localization | Domestic crystalline admixture production in Maharashtra and Gujarat captures import-substitution margins serving South Asian infrastructure buildout. |
Research Methodology
Multiple input streams — primary interviews with admixture formulators, ready-mix plant operators, and state DOT specification engineers; secondary validation through ECHA registration databases, ASTM committee documentation, and EU Green Deal implementation guidance; plus customs trade data on construction chemical imports — were reconciled through bottom-up project pipeline assessment and top-down market sizing triangulation.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology pathway, application sector, and end-user risk tolerance, with CAGRs derived from elasticity-adjusted substitution curves tracking embodied carbon threshold enforcement. Forecast inputs incorporated contractor bundling contract penetration rates and bacterial spore formulation shelf stability improvements.
The model assumes a particular technology adoption path; alternative pathways for vascular network concrete standardization would alter the outlook if ASTM ballot completion accelerates or stalls. Forecasts reflect assumptions about regulatory enforcement consistency and raw material cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Cladding Market
Building Materials
Indonesia Architectural Coatings Market
Building Materials
Timber Frames Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
West Africa Cement Market
Building Materials
Qatar Cement Market
Building Materials
Plaster Accelerator Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
Construction Stone Market
Building Materials
Global Metal Cladding Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Global Facade Market