
 Global Convertible Roof System Market | 2026-2036
Global Convertible Roof System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Convertible Roof System Market Intelligence
The IATF 16949 quality management standard for automotive suppliers is redrawing the competitive landscape for convertible roof system manufacturers. Webasto Group leverages its deep expertise in both soft and hardtop systems to serve a wide range of OEM clients. Magna International Inc. competes through its extensive manufacturing footprint and integrated mechatronic capabilities. The Haartz Corporation specializes in advanced textile and fabric solutions, primarily for the soft top segment.
A convertible roof system is an integrated mechatronic assembly designed to retract and store a vehicle's roof, transforming it from a closed to an open-air configuration. These systems often incorporate hydraulic actuators or electric motors capable of completing a full open/close cycle in under 20 seconds. Hardtop systems, particularly retractable hardtops, command higher price points and are prevalent in the luxury segment. Electric motor-driven mechanisms are displacing older hydraulic systems due to their lighter weight and improved reliability.
Vehicle safety standards, such as the Federal Motor Vehicle Safety Standards (FMVSS) in the United States, mandate specific rollover protection and structural integrity tests. In Europe, compliance with CE marking and directives on electromagnetic compatibility is essential for the electronic components within these systems. Supplier selection will increasingly hinge on the ability to integrate advanced sensors for autonomous operation and weather detection.
Market Dynamics
The central dynamic shaping the market is the technical tension between lightweighting imperatives for vehicle efficiency and stringent safety standards for structural integrity. This forces a trade-off between complex, lightweight materials and the cost and engineering required for rollover protection.
Growth Catalysts
- Luxury Segment Concentration:Demand from premium vehicle OEMs, particularly in automotive manufacturing hubs like Germany, provides a consistent revenue stream and a testbed for advanced features before they cascade to mass-market models.
- Lightweight Composites:The development of materials like carbon fiber enables more intricate and efficient retractable roof designs without imposing significant weight penalties, improving vehicle performance and fuel economy.
- Mechatronic Advancement:Continuous improvements in the reliability and speed of electric motors and actuators make modern convertible systems more appealing to consumers compared to older, slower hydraulic mechanisms.
Market Restraints
- High System Cost:The integration of motors, sensors, and complex kinematic linkages makes convertible roof systems an expensive feature, largely confining their application to higher-priced luxury and sports vehicle segments.
- Structural Reinforcement Penalty:Removing a fixed roof necessitates significant chassis reinforcement to maintain torsional rigidity and crash safety, adding weight and cost that can negate some benefits of lightweight roof materials.
- Rollover Safety Mandates:Vehicle safety standards, such as the FMVSS in the United States, impose strict rollover protection requirements that demand additional engineering, testing, and often pop-up protection systems for open-top cars.
Strategic Opportunities
- Smart Roof Systems:Integrating roof mechanisms with weather sensors for automatic closure or with vehicle autonomous driving systems presents a significant opportunity for value-added differentiation and enhanced user convenience.
- Advanced Soft Top Fabrics:The development of multi-layer textile composites with enhanced acoustic insulation, thermal properties, and weather resistance can position soft tops as a lighter, more versatile alternative to retractable hardtops.
- Electric Vehicle Platforms:Designing compact and energy-efficient roof systems specifically for EV architectures, which have unique packaging and power constraints, opens a new and expanding vehicle segment for suppliers.
Industry Challenges
- Mechatronic Integration Complexity:Ensuring seamless communication between the roof control unit, electric motors, and the vehicle's central CAN bus network requires specialized software and systems integration expertise, which can be a bottleneck.
- Supply Chain for Composites:The sourcing of high-quality, automotive-grade carbon fiber composites is dependent on a limited number of specialized suppliers, creating potential risks of price volatility and supply disruptions.
- Electromagnetic Compatibility Compliance:Meeting stringent EMC directives, such as CE marking requirements in Europe, for the dense electronic components within a roof module is a time-consuming and costly validation challenge for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Convertible Roof System Market |
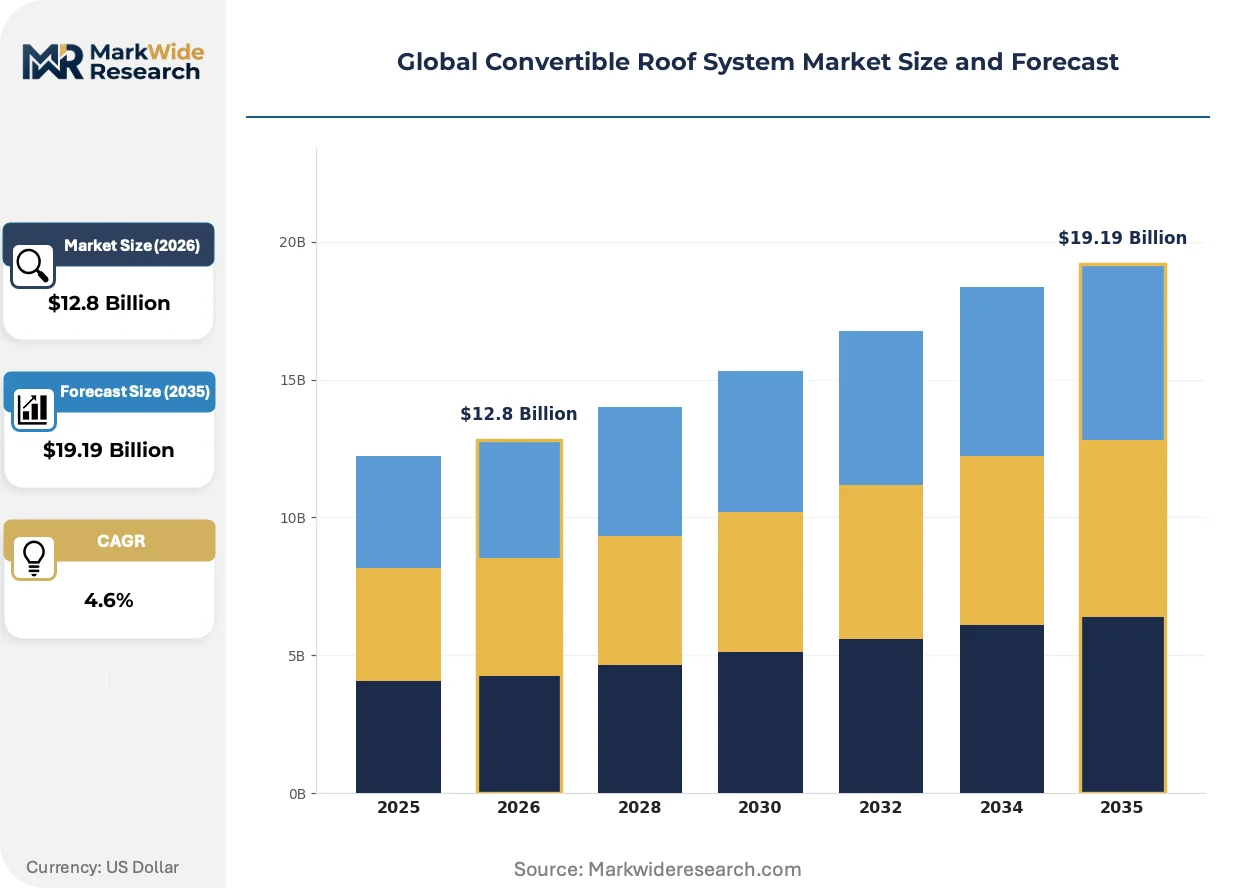
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Top, Hardtop, Retractable Hardtop, Folding Steel Roof, Canvas Roof Technology: Manual Operation, Hydraulic System, Electric Motor, Pneumatic System, Hybrid Mechanism Application: Passenger Vehicles, Sports Cars, Luxury Models, Commercial Vans, Special Purpose Vehicles End User: OEMs, Vehicle Retrofitting, Auto Dealerships, Specialty Body Manufacturers, Aftermarket Providers |
| Companies Covered | The Haartz Corporation, Aisin Seiki Co., Ltd., Webasto Group, CIE Automotive, Inalfa Roof Systems Group B.V., Magna International Inc., Continental AG, BOS Group, Valmet Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Convertible Roof System Market Strategic Shifts & Innovations
The evolution of convertible roof systems is defined by a push for greater intelligence and material efficiency. This moves the technology beyond simple open-and-close functionality toward fully integrated, smart vehicle components that enhance safety, convenience, and performance.
Integrated mechatronic modules combine actuators, sensors, and control logic into a single, pre-validated assembly. The luxury and sports car segments are adopting these modules to reduce vehicle complexity and shorten assembly line times. This consolidation is decomposing the traditional supply chain, where individual components were sourced separately, into a model favoring complete subsystem procurement.
European Union regulations governing electromagnetic compatibility (EMC) are becoming increasingly stringent for all in-vehicle electronic systems. This compels roof system manufacturers to invest in advanced shielding and rigorous testing to prevent interference with critical ADAS and infotainment functions. The retractable hardtop segment, with its high density of motors and sensors, is most affected and often requires design modifications to secure CE marking.
OEM purchasing patterns are shifting away from specifying individual components toward sourcing a complete, performance-guaranteed roof system from a single-source supplier. This change benefits larger suppliers with deep system integration capabilities at the expense of smaller, specialized component makers. This trend is most visible in Germany, where premium automakers use this strategy to de-risk development and accelerate their time to market.
Global Convertible Roof System Market Segmentation
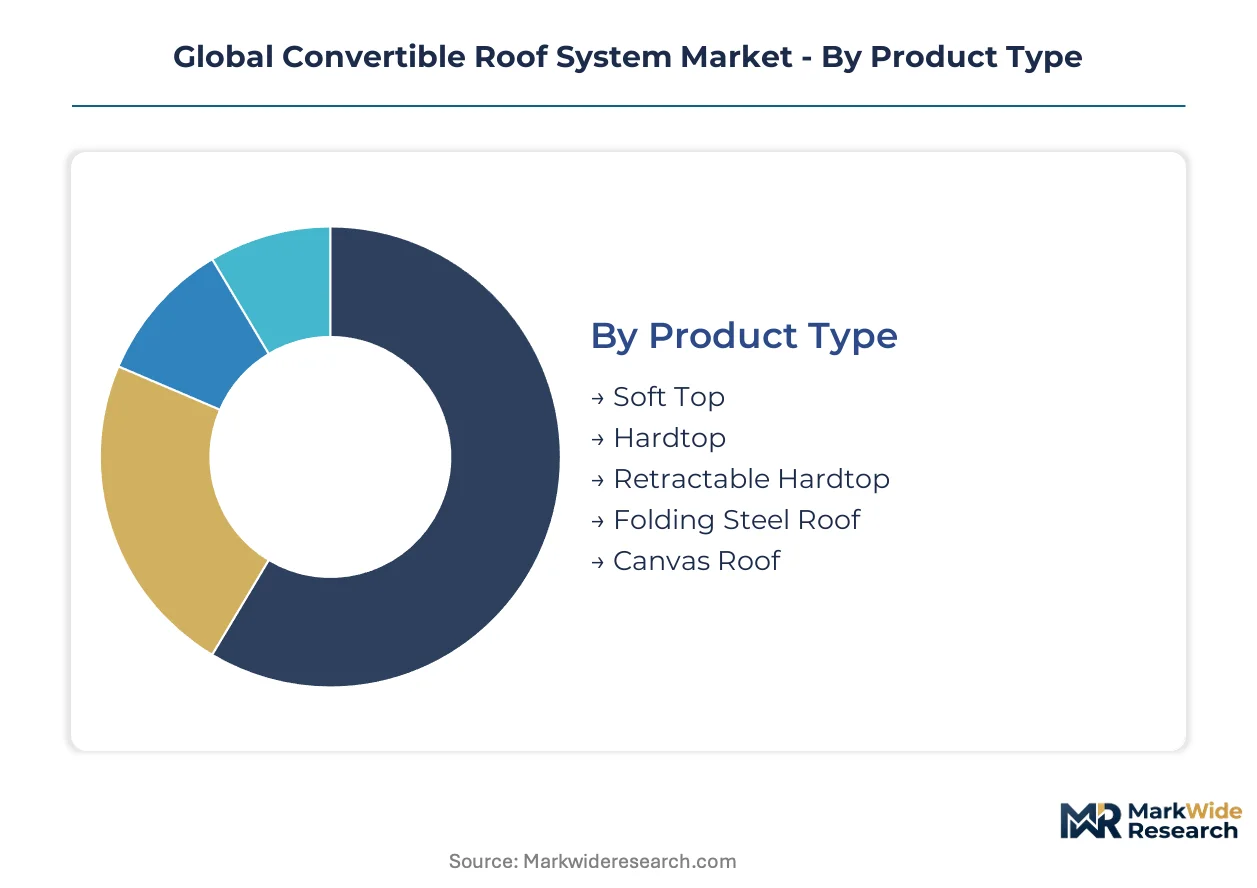
The segmentation analysis provides a granular view of the Global Convertible Roof System Market, dissecting it into distinct categories based on product type, technology, application, and end user. This detailed breakdown helps identify specific demand drivers, technological preferences, and strategic opportunities across various market dimensions, guiding targeted development and market penetration efforts.
Product Type:
The product type segmentation highlights the ongoing substitution pressure from advanced retractable designs on traditional soft-top configurations.
- Retractable Hardtop:These systems feature multiple rigid panels that fold and stack mechanically, offering enhanced security, thermal insulation, and aesthetic appeal when closed. Demand concentrates within the luxury vehicle segment, driven by consumer preference for coupe-like rigidity combined with open-air flexibility.
- Soft Top:Comprising multi-layered textile composites, soft tops provide a lightweight and compact solution for convertible vehicles, often utilizing advanced fabrics for acoustic and thermal performance. The segment maintains relevance in sports cars and niche luxury models, benefiting from lower weight and simpler mechanical integration compared to hardtops.
- Hardtop:Fixed, removable hardtops offer seasonal protection and improved security, commonly found as an accessory for roadsters.
- Folding Steel Roof:These roofs consist of articulated steel panels that retract into the vehicle trunk, providing a robust and secure enclosure.
- Canvas Roof:A simpler, often manual variant of the soft top, canvas roofs prioritize lightweight design and classic aesthetic appeal for entry-level convertibles.
Soft Top anchors the volume base while Retractable Hardtop gains share at the steepest rate.
Technology:
Technology segmentation reveals a progressive shift away from older, less efficient mechanisms towards sophisticated, integrated solutions.
- Electric Motor:These systems utilize electric actuators and geared mechanisms for roof articulation, offering improved reliability, lighter weight, and precise control compared to hydraulic alternatives. The luxury and sports car segments favor electric motor-driven systems due to their faster operation and reduced maintenance requirements.
- Hydraulic System:Relying on fluid pressure to actuate cylinders, hydraulic systems have historically powered many convertible roofs, providing robust force for heavier hardtop components. While still present in some legacy designs, these systems face displacement by electric motor solutions due to their complexity and potential for leaks.
- Manual Operation:These basic systems require direct human intervention to open or close the roof, typically found in entry-level or vintage convertible models.
- Pneumatic System:Utilizing compressed air for actuation, pneumatic systems offer an alternative to hydraulics but are less common in modern automotive roof applications due to complexity.
- Hybrid Mechanism:Combining elements of electric motors and hydraulic power, hybrid systems aim to optimize performance, speed, and packaging for specific roof designs.
The market favors solutions that prioritize efficiency and integration, with Electric Motor technology leading this evolution.
Application:
Application segmentation highlights where demand for convertible roof systems concentrates, influencing design priorities and feature sets.
- Luxury Models:This application segment represents a primary demand driver for advanced convertible roof systems, incorporating complex mechatronics and premium materials. OEMs in Germany, for example, frequently integrate these systems to differentiate high-end vehicles, offering advanced features like automatic weather detection.
- Passenger Vehicles:Encompassing a broader range of mainstream cars, this segment includes convertibles designed for everyday use, balancing cost, functionality, and aesthetic appeal. While less feature-rich than luxury counterparts, these vehicles aim for reliable and user-friendly roof operation, often adopting proven technologies.
- Sports Cars:These vehicles prioritize lightweight designs and rapid roof operation, often integrating carbon fiber composites to enhance performance characteristics.
- Commercial Vans:Convertible roof systems are highly uncommon in commercial vans, which prioritize cargo capacity and utility over open-air driving.
- Special Purpose Vehicles:Niche applications may include custom vehicles or specialized recreational vehicles where a convertible roof provides unique functional benefits.
Demand concentration within Luxury Models drives innovation, while Passenger Vehicles represent the broadest consumer base.
End User:
End user segmentation delineates the primary channels through which convertible roof systems reach the final vehicle, reflecting diverse supply chain dynamics.
- OEMs:Original Equipment Manufacturers represent the largest end-user segment, integrating complete convertible roof systems directly into their vehicle production lines. Supplier selection here is heavily influenced by IATF 16949 compliance and the ability to deliver complex, pre-validated mechatronic modules at scale.
- Specialty Body Manufacturers:These firms specialize in custom vehicle conversions or low-volume, high-performance models, requiring bespoke roof system solutions. They often collaborate closely with suppliers for unique design integration and specialized engineering support, particularly for complex hardtop systems.
- Vehicle Retrofitting:This niche segment involves modifying existing vehicles to incorporate convertible roof systems, often for custom projects or classic car restorations.
- Auto Dealerships:While dealerships sell vehicles with integrated roof systems, they are not direct end-users for system procurement, acting as a sales channel.
- Aftermarket Providers:These entities supply replacement parts or accessories for existing convertible roof systems, supporting maintenance and repair needs.
The market structure prioritizes direct supply to OEMs for volume production, with Specialty Body Manufacturers catering to bespoke requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stringent vehicle safety standards, like the Federal Motor Vehicle Safety Standards (FMVSS) in the United States, influence convertible roof system design globally. Compliance with CE marking directives in Europe also pushes for advanced electronic integration. These regulatory pressures, alongside consumer preferences, define market growth trajectories in major automotive hubs.
Germany
Demand for advanced convertible roof systems concentrates in Germany, driven by luxury vehicle OEMs and a strong engineering tradition. European CE marking requirements for electronic components ensure high standards for system integration and electromagnetic compatibility. Automotive manufacturing clusters in Stuttgart and Munich remain central to the development and adoption of sophisticated retractable hardtops.
United States
The United States market sees consistent demand from the luxury and sports car segments, valuing both performance and open-air driving experiences. Federal Motor Vehicle Safety Standards (FMVSS) mandate rigorous rollover protection, shaping structural reinforcement strategies for convertible designs. Detroit's automotive hub, alongside innovation centers in California, drives adoption of electric motor-driven roof systems.
Japan
Japan exhibits demand for compact sports cars and niche luxury convertibles, emphasizing precision engineering and reliability. Compliance with Japanese Industrial Standards (JIS) ensures quality and performance across all automotive components, including roof systems. Major automotive manufacturing regions like Toyota City and Yokohama are key for integrating advanced mechatronic roof modules.
China
China's emerging luxury vehicle market and rapid adoption of electric vehicles create new demand vectors for convertible roof systems. National GB standards guide material selection and manufacturing processes for automotive components, including roof structures. Manufacturing centers in Shanghai and Guangzhou are increasingly integrating sophisticated roof solutions into domestic premium brands.
Italy
Italy's market for convertible roof systems is anchored by high-performance sports cars and design-focused luxury models. European CE marking directives are critical for the electronic and structural integrity of these complex systems. Automotive design and production hubs in Turin and Modena continue to innovate with lightweight materials and advanced kinematics for premium convertibles.
Global Convertible Roof System Market Key Industry Players
Player mix skews toward large, integrated automotive suppliers with extensive mechatronic capabilities. The market exhibits a tiered structure, with a few dominant players alongside specialized component manufacturers. Strategic archetypes include full-system integrators, textile specialists, and niche engineering firms. Dominant competitive moves involve strategic partnerships for advanced technology and continuous investment in R&D for lightweight materials.
Within the integrated mechatronics segment, Webasto Group and Magna International Inc. exemplify global reach, offering comprehensive roof system solutions to OEMs. The Haartz Corporation, a specialist in advanced textile and fabric solutions, occupies a position as a key supplier for soft top components. These companies reflect the market's reliance on both large-scale, diversified suppliers and focused niche providers for specialized materials.
| Leading Market Players |
|---|
| The Haartz Corporation |
| Aisin Seiki Co., Ltd. |
| Webasto Group |
| CIE Automotive |
| Inalfa Roof Systems Group B.V. |
| Magna International Inc. |
| Continental AG |
| BOS Group |
| Valmet Automotive |
| Others |
Cost & Logistics Intelligence
IATF 16949 compliance gates supplier qualification and influences pricing power for complex mechatronic modules. This standard ensures quality but also drives differentiation, impacting cost structures across the value chain.
Pricing Analysis
Cost-plus contracts, often indexed to material and labor costs, govern long-term supply agreements for convertible roof systems. Pricing stratifies across premium, standard, and economy tiers, driven by certification level (IATF 16949) and customization level for OEM-specific designs. Pricing pressure stems from OEM demands for lightweighting and advanced features without proportional cost increases. Luxury models are least price-sensitive, while passenger vehicles are highly cost-conscious.
Supply Chain Analysis
Inventory management and lead-time optimization remain critical challenges for convertible roof system suppliers due to complex assemblies. Geographic supply concentrates in Germany, Japan, and China, reflecting major automotive manufacturing hubs. The supply chain draws from carbon fiber composites, advanced textiles, electric motors, and hydraulic components. Single-source vulnerability for specialized composites represents a structural risk. Distribution runs through direct supply to OEMs for volume production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The convertible roof system market is at a platform-economics inflection point, driven by the increasing interoperability with vehicle autonomous driving systems. This integration creates new value propositions and redefines system boundaries.
For Market Incumbents: Consolidate core competencies in mechatronic integration and advanced materials to counter emerging software-defined vehicle architectures. Invest in modular system designs for EV platforms and acquire specialized sensor integration expertise. The shift towards integrated smart vehicle components poses a threat to traditional hardware-centric suppliers. Deepen R&D into electromagnetic compatibility compliance to maintain competitive advantage.
For New Entrants and Emerging Players: Differentiate on rapid prototyping and AI-driven design optimization for next-generation smart roof systems. Target the electric vehicle platform segment and advanced soft top fabric solutions. The niche market for specialized body manufacturers offers entry points. Focus on value-added features like predictive maintenance and automatic weather detection.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive conglomerates seeking to divest non-core mechatronics divisions. The market offers long-term viability over the next decade, fueled by luxury segment concentration and EV adoption. Target mid-sized specialists in sensor integration or lightweight composite manufacturing. OEM announcements regarding fully autonomous convertible models will indicate market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization for EVs | Reduces development costs and accelerates time-to-market for convertible roof systems on electric vehicle architectures. |
| Advanced Sensor Integration | Enables smart roof functionalities like automatic closure and enhances safety features for autonomous driving systems. |
| Lightweight Carbon Fiber R&D | Improves vehicle performance and fuel efficiency by reducing the structural weight of retractable hardtop systems. |
| Strategic Partnership with Software Firms | Develops sophisticated control logic and HMI for seamless integration into modern vehicle infotainment systems. |
| Geographic Manufacturing Footprint Expansion in Asia | Captures demand from China's emerging luxury vehicle market and strengthens regional supply chain resilience. |
Research Approach
Initial hypotheses were tested against primary input from OEM procurement managers, Tier 1 suppliers, and specialty body manufacturers, then refined through iterative processes. Vehicle production databases, IHS Markit registration data, company financial filings, and automotive industry reports provided robust secondary validation. This approach ensured a comprehensive view, triangulating insights from both bottom-up market intelligence and top-down industry analysis.
Variance decomposition was applied to isolate the impact of distinct market drivers and constraints across the analysis window. The analysis modeled market dimensions including product type, technology, application, end-user, and regional OEM demand. Compound annual growth rates were derived from historical data and projected future trends, considering evolving material costs and regulatory shifts as key inputs.
Decision-makers should treat outputs as directional under current macroeconomic and technological assumptions; material deviation would warrant model refresh. Geopolitical disruptions or shifts in vehicle safety standards could alter market trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Cultured Marble Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market