
 GCC Prefabricated Housing Market | 2026-2036
GCC Prefabricated Housing Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Prefabricated Housing Market Foresight
Saudi Vision 2030 sustainability mandates is expanding procurement criteria for state-backed housing developments. Albaddad International leverages its manufacturing scale across Riyadh and Jeddah to anchor government contracts. Speed House Group of Companies differentiates through turnkey installation capabilities serving remote industrial camps. SAPCO sustains its position via vertical integration from steel fabrication to on-site assembly.
Prefabricated housing denotes dwelling units manufactured in factory-controlled conditions and transported for final assembly, typically employing steel frames, insulated panels, or precast concrete modules engineered to withstand regional seismic and thermal loads. The primary purpose centers on compressing construction schedules while maintaining structural compliance for residential, commercial, and worker accommodation applications. Modular homes dominate value generation due to customization flexibility for giga-project workforces, while panelized systems compete on speed for repetitive government housing estates. Steel material demand outpaces wood alternatives as fire-resistance ratings tighten across Gulf building codes.
Gulf Standardization Organization (GSO) building codes, Saudi Building Code (SBC), and UAE Fire and Life Safety Code collectively mandate seismic performance, thermal insulation, and fire-rated assemblies that factory-built units must certify before site delivery. These frameworks effectively filter out informal builders and reward manufacturers with in-house testing laboratories. Stakeholders must monitor evolving green building mandates from Saudi Standards, Metrology and Quality Organization (SASO) and Emirates Green Building Council as energy-efficiency thresholds tighten procurement specifications.
Market Dynamics
Saudi Arabia's giga-project pipeline is compressing traditional construction timelines, forcing developers toward factory-built solutions that align with Vision 2030 localization targets. Steel-frame modular systems now dominate procurement for workforce housing in NEOM and Red Sea Project corridors.
Growth Catalysts
- Saudi Building Code (SBC) seismic mandates:Factory certification requirements for structural performance are filtering informal builders and rewarding manufacturers with in-house testing laboratories.
- Kuwait's Public Authority for Housing Welfare:State-backed affordable housing estates are specifying panelized systems for repetitive residential blocks, accelerating standardization.
- Steel-frame fabrication:Fire-resistance ratings under UAE Fire and Life Safety Code are displacing wood alternatives in high-density worker accommodation applications.
Market Restraints
- Hot-rolled steel price volatility:GCC steel import dependence exposes manufacturers to freight and raw material cost swings that compress bid margins.
- Transportation infrastructure gaps:Limited heavy-haul corridors between Jeddah Industrial City and remote giga-project sites inflate module delivery costs.
- Skilled welding labor scarcity:Certified steel fabricators concentrate in Riyadh and Dammam, constraining expansion into secondary Emirates markets.
Strategic Opportunities
- Oman's underpenetrated affordable housing segment:Ministry of Housing and Urban Planning tenders for low-income units lack established prefabricated suppliers.
- Bahrain's financial district commercial pods:Modular office units for fintech clusters represent untested application expansion beyond residential.
- SASO energy-efficiency mandates:Thermal performance certification requirements for factory-built units are creating first-mover advantage for insulated panel specialists.
Industry Challenges
- GSO conformity assessment timelines:Factory audits and type-approval processes for cross-border GCC sales extend project mobilization by eight to fourteen weeks.
- Legacy site infrastructure incompatibility:Crane capacity and foundation specifications at existing government housing developments often mismatch modular unit weights and connection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Prefabricated Housing Market |
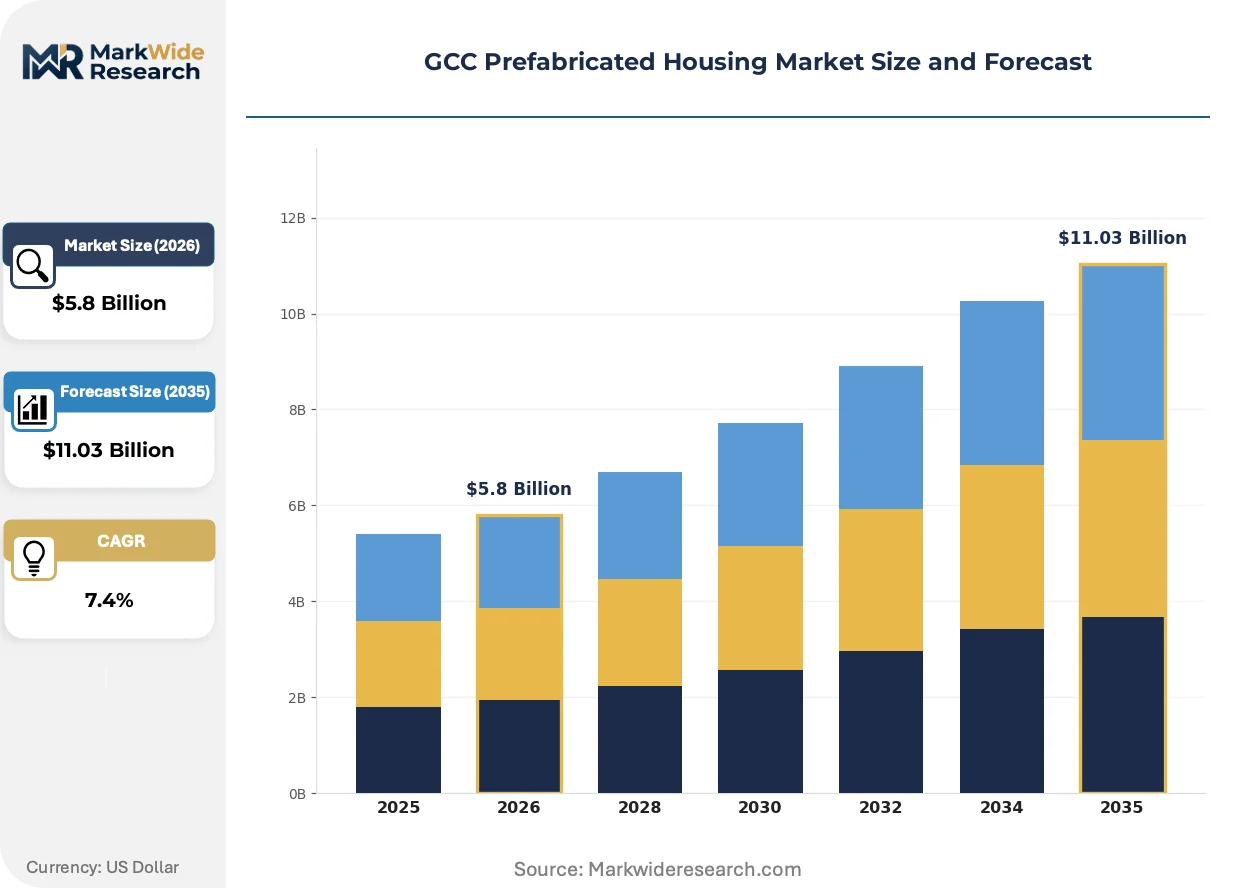
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.03 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Manufactured Homes, Shipping Container Homes Material: Wood, Steel, Concrete, Plastic End User: Residential Developers, Government Projects, Commercial Use, Disaster Relief Installation: On-Site Assembly, Off-Site Construction, Pre-Cut Delivery, Turnkey Solution |
| Companies Covered | Saudi Arabian Prefabricated Buildings Co. (SAPCO), Extra Co Group of Companies, Albaddad International, Speed House Group of Companies, Exeed Precast, Algeco, Red Sea Housing Services, Strabag Dubai LLC, Modular Construction Company (MCC), Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Prefabricated Housing Market Shifts & Advancements
Digital fabrication and connected building systems are reshaping how Gulf developers specify factory-built housing. Procurement criteria now emphasize lifecycle data transparency alongside speed-to-occupancy metrics.
Building information modeling (BIM) integration with CNC steel cutting is expanding into quality assurance protocols for seismic-resistant frame assemblies. Saudi Aramco and ADNOC camp developers now mandate digital twins for module traceability. This convergence is compressing defect liability periods and shifting warranty risk toward manufacturers.
SASO's updated insulation performance standards for residential buildings are tightening thermal envelope requirements for factory-built units. Manufacturers must recalibrate panel lamination processes to maintain R-value certifications under accelerated aging tests. Kuwaiti and Qatari housing authorities are adopting these thresholds for upcoming affordable housing tenders.
Developer procurement teams now bundle module supply with ten-year maintenance contracts, displacing traditional design-bid-build separation. Saudi Real Estate Development Fund borrowers increasingly specify single-source accountability for envelope performance. This consolidation is most visible in Riyadh's Diriyah Gate and Jeddah Economic City workforce housing packages.
GCC Prefabricated Housing Market Segmentation
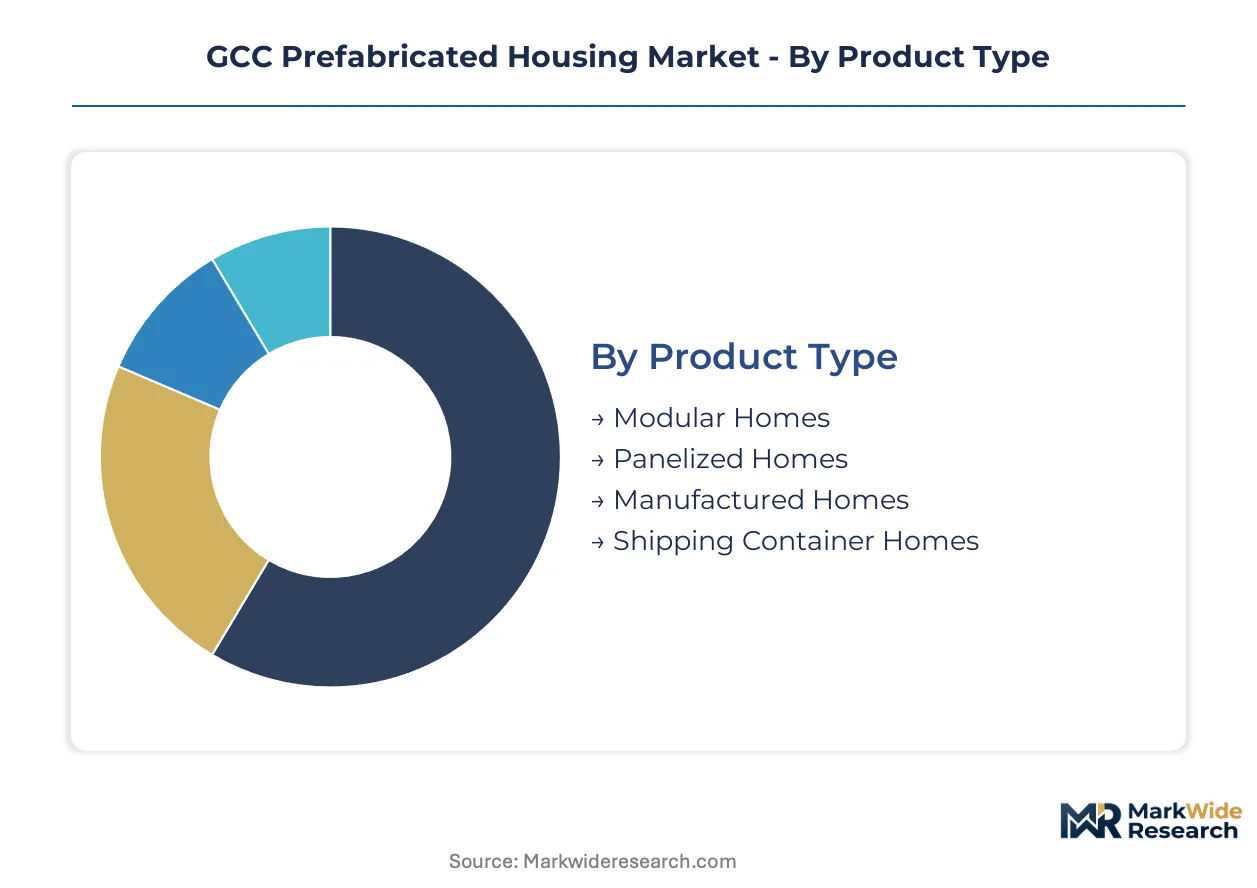
GCC procurement specifications fragment across construction methodology, structural material, and delivery responsibility. Understanding segment boundaries clarifies where manufacturers compete on speed versus customization versus total installed cost.
Product Type:
Structural configuration determines factory-to-site workflow complexity and finish quality latitude.
- Modular Homes:Three-dimensional volumetric units arrive with MEP rough-ins and interior finishes intact. Demand concentrates in Saudi giga-project workforce corridors where NEOM and Red Sea Project developers specify 500+ unit blocks for rapid site mobilization.
- Panelized Homes:Flat-packed wall and roof assemblies enable higher transport density for repetitive government housing estates. Kuwait's Public Authority for Housing Welfare specifies these for standardized low-income residential blocks across Jahra and Ahmadi governorates.
- Manufactured Homes:Transportable single-unit dwellings built on steel chassis meet UAE mobile residence codes for temporary worker accommodation in Dubai South logistics zones.
- Shipping Container Homes:Repurposed ISO container structures serve remote industrial camp applications in Oman's Duqm Special Economic Zone where conventional material logistics prove prohibitive.
Mature deployment sits with Modular Homes. Newer deployment is concentrated in Shipping Container Homes.
Material:
Fire-resistance ratings and seismic performance requirements are filtering material selection across Gulf building codes.
- Steel:Hot-rolled and cold-formed structural sections dominate high-density worker accommodation in the UAE and Saudi Arabia. Emirates Fire and Life Safety Code mandates two-hour fire ratings that steel-frame assemblies with intumescent coatings satisfy more reliably than combustible alternatives.
- Concrete:Precast wall panels and hollow-core slabs serve permanent residential applications in Qatar's Lusail City and Bahrain's Diyar Al Muharraq where thermal mass and acoustic separation carry premium specification weight.
- Wood:Engineered timber and cross-laminated lumber retain niche presence in low-rise villa segments of Dubai Hills and Riyadh's Diplomatic Quarter where aesthetic finish and carbon accounting influence developer selection.
- Plastic:Fiber-reinforced polymer composites address corrosive coastal environments in Kuwait's Failaka Island restoration and Saudi Red Sea coastal tourism nodes.
Steel commands the dominant specification share. Plastic is gaining traction fastest in coastal corrosion applications.
End User:
Procurement authority and payment security differentiate customer segments for manufacturer credit risk assessment.
- Government Projects:Saudi Real Estate Development Fund and Kuwait Public Authority for Housing Welfare tenders specify factory-built units for affordable housing estates with sovereign-backed payment terms and multi-year maintenance bundling.
- Residential Developers:Private developers in Dubai's Mohammed Bin Rashid City and Riyadh's King Abdullah Financial District specify modular units for workforce housing adjacent to commercial construction sites.
- Commercial Use:Modular office pods and retail kiosks serve Bahrain's fintech harbor and Qatar's Msheireb Downtown Doha mixed-use districts.
- Disaster Relief:Rapid-deployment units address emergency housing requirements following flash flooding in Oman's Al Sharqiyah and Jazan regions.
Government Projects anchor volume commitment. Residential Developers are expanding most quickly as private capital flows into Saudi giga-project adjacencies.
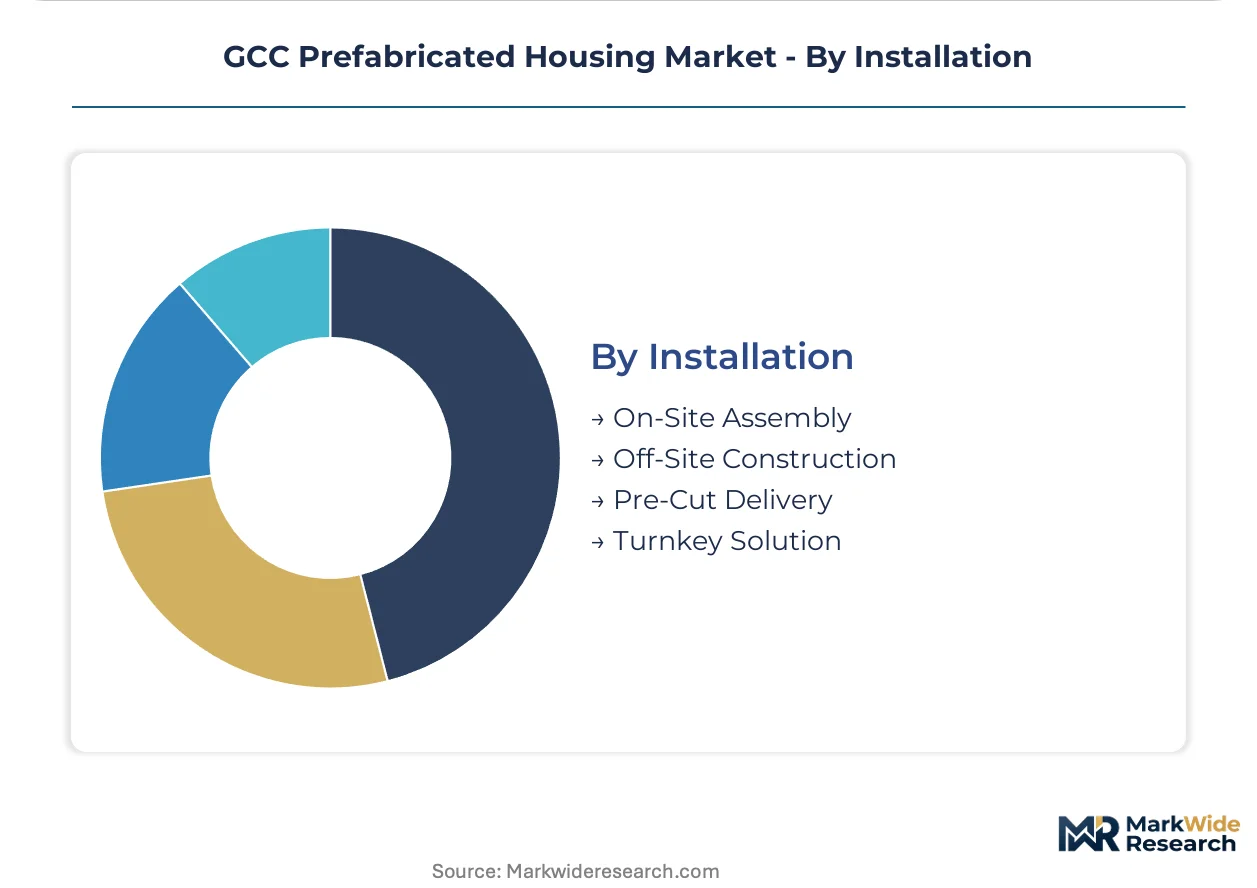
Installation:
Responsibility demarcation for foundation, transport, and final connection determines manufacturer margin structure and liability exposure.
- Turnkey Solution:Single-source contracts covering design, fabrication, transport, and commissioning command premium pricing in remote Saudi giga-project sites where developer staff scarcity necessitates complete vendor accountability.
- On-Site Assembly:Manufacturer crews execute module connection and MEP integration at destination. This model dominates UAE high-rise modular applications where crane coordination and vertical logistics require specialized expertise.
- Off-Site Construction:Factory-complete volumetric units minimize site labor for Kuwaiti and Qatari projects facing skilled worker quota constraints.
- Pre-Cut Delivery:Kit-of-parts shipments with installation manuals serve Omani and Bahraini markets where local contractor networks prefer controlling field labor.
Turnkey Solution carries the highest contract values. Pre-Cut Delivery is penetrating secondary markets where local construction capacity exceeds factory logistics reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory capacity clusters in Saudi Arabia's industrial cities while consumption spreads across all six GCC states. Riyadh and Dammam host the densest steel fabrication infrastructure. Cross-border logistics constraints fragment supply chain efficiency between production and end-use sites.
Saudi Arabia
NEOM and Red Sea Project corridors drive volumetric modular demand for 500-unit workforce blocks. Saudi Building Code seismic certification requirements filter out informal builders and reward manufacturers with in-house testing laboratories. Jeddah Industrial City anchors steel-frame production serving western giga-project sites.
United Arab Emirates
Dubai's affordable housing zones and Mohammed Bin Rashid City workforce accommodations sustain panelized system procurement. Emirates Fire and Life Safety Code mandates two-hour fire ratings that steel-frame assemblies satisfy more reliably than wood alternatives. Jebel Ali industrial corridor concentrates fabrication capacity serving northern emirates distribution.
Kuwait
Public Authority for Housing Welfare tenders specify flat-packed panelized systems for standardized low-income estates across Jahra and Ahmadi governorates. Ministry of Public Works building codes align with Gulf Standardization Organization thermal performance thresholds. Al Ahmadi industrial zone hosts prefabrication facilities serving southern governorate housing clusters.
Qatar
Lusail City permanent residential applications favor precast concrete wall panels and hollow-core slabs for thermal mass and acoustic separation. Qatar General Organization for Standardization building regulations mandate seismic performance certification for factory-built units. Doha Industrial Area fabrication plants supply modular units for Msheireb Downtown mixed-use districts.
Oman
Duqm Special Economic Zone and remote industrial camps drive repurposed ISO container demand where conventional material logistics prove prohibitive. Ministry of Housing and Urban Planning low-income tenders lack established prefabricated suppliers, creating entry openings. Sohar Port freezone positioning offers import duty advantages for steel module landing.
GCC Prefabricated Housing Market Competitive Landscape
The competitive structure tilts toward vertically integrated national champions with captive steel fabrication and in-house testing laboratories. Mid-scale regional specialists compete on turnkey installation speed for remote site deployments. Two dominant strategic archetypes emerge: sovereign-contract aggregators bundling multi-year maintenance obligations, and project-specific fabricators optimizing for rapid mobilization. Capacity expansion and strategic partnerships with giga-project developers constitute the primary competitive moves.
Within the integrated-manufacturing tier, Saudi Arabian Prefabricated Buildings Co. (SAPCO) and Albaddad International represent archetypes of steel-to-assembly vertical control. Speed House Group of Companies occupies a position emphasizing turnkey remote-site capabilities. These three anchors demonstrate how geographic production positioning and service bundling differentiate procurement outcomes for state-backed housing developments.
| Leading Market Players |
|---|
| Saudi Arabian Prefabricated Buildings Co. (SAPCO) |
| Extra Co Group of Companies |
| Albaddad International |
| Speed House Group of Companies |
| Exeed Precast |
| Algeco |
| Red Sea Housing Services |
| Strabag Dubai LLC |
| Modular Construction Company (MCC) |
| Others |
Supply & Pricing Matrix
Certified welding labor concentration in Riyadh and Dammam establishes labor-cost differentials that widen pricing-tier spreads between premium turnkey contracts and economy pre-cut deliveries. Steel-frame fabricators with captive in-house certification command bid premiums of 15-25 percent over regional competitors lacking testing laboratory accreditation.
Pricing Analysis
Margin tightening in economy-tier panelized systems reflects hot-rolled steel import dependence and freight cost volatility compressing manufacturer bids. Project-based contract pricing dominates procurement for Saudi giga-project workforce blocks, with differentiation driven by SASO seismic certification grade and bundled ten-year maintenance obligations. Price erosion runs through standard-tier manufactured homes as Kuwaiti housing authorities consolidate tender volumes and squeeze unit economics. Government project buyers exhibit lowest price sensitivity given sovereign-backed payment terms, while Omani low-income housing tenders attract aggressive cost competition from unqualified informal builders.
Supply Chain Analysis
Saudi Vision 2030 localization mandates are reshaping sourcing patterns toward domestic steel fabrication and in-country panel lamination capacity. Supply concentration centers on Saudi Arabia, the UAE, and Kuwait, with hot-rolled structural steel, intumescent fire coatings, and mineral wool insulation drawing from regional petrochemical feedstocks and Asian specialty chemical imports. Single-source vulnerability sits with certified seismic testing laboratory capacity, where GSO conformity assessment bottlenecks extend mobilization timelines. Distribution runs through Jeddah Industrial City and Dammam fabrication clusters serving cross-border GCC project sites via heavy-haul corridor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained certified fabrication capacity props pricing power for manufacturers with in-house testing infrastructure, as GSO audit backlogs create eight-to-fourteen-week mobilization delays that filter price-sensitive competitors.
For Market Incumbents: Acquire captive steel rolling mill capacity in Saudi Arabia's Eastern Province to secure hot-rolled structural section supply against import price volatility. Backward integration into mineral wool insulation production addresses SASO thermal performance threshold tightening. Defend market position by expanding in-house seismic testing laboratory accreditation to capture Red Sea Project corridor contracts filtering informal competitors lacking SBC certification.
For New Entrants and Emerging Players: BIM-integrated digital fabrication capabilities offer technology-first positioning against legacy manufacturers reliant on manual quality assurance. Target Oman's underpenetrated affordable housing segment where Ministry of Housing and Urban Planning tenders lack established prefabricated suppliers. Penetrate via turnkey remote-site installation partnerships with Duqm Special Economic Zone developers facing conventional material logistics prohibitions.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated national champions given SASO energy-efficiency mandate acceleration and multi-year maintenance contract bundling trends. Acquisition focus should target steel-to-assembly manufacturers with GSO cross-border certification and established relationships with Saudi Real Estate Development Fund borrowers. Watch for inflection signals in Kuwait Public Authority for Housing Welfare tender specifications adopting Saudi thermal performance thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Jeddah Industrial City steel fabrication scale-up secures NEOM corridor workforce housing procurement. |
| Backward Integration | In-house mineral wool insulation production addresses SASO R-value certification tightening for panelized systems. |
| Long-term Supply Agreement | Multi-year maintenance bundling with Saudi Real Estate Development Fund borrowers displaces traditional design-bid-build separation. |
| Joint Venture | Technology licensing partnerships with European BIM-integrated CNC cutting specialists accelerate digital fabrication adoption. |
| Green Certification Program | Emirates Green Building Council thermal envelope accreditation opens Dubai affordable housing zone procurement. |
Research Methodology
Multi-period observation of steel-frame fabrication capacity utilization, GSO conformity assessment queue lengths, and giga-project workforce housing mobilization timelines anchored the trend analysis, supplemented by interviews with Saudi Real Estate Development Fund procurement officers, Kuwait Public Authority for Housing Welfare tender administrators, UAE-based EPC contractor project directors, and steel-frame manufacturer plant managers. Secondary validation drew from Saudi Building Code technical committee disclosures, SASO energy-efficiency standard drafts, Gulf Standardization Organization factory audit protocols, and Emirates Green Building Council certification databases. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic construction spend forecasts.
Segment-weighting across construction methodology, structural material, and installation responsibility dimensions shaped the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical factory output against announced giga-project housing unit commitments, with cross-validation against steel import volume trajectories and skilled welding labor supply elasticity estimates. Industry-specific forecast inputs included NEOM and Red Sea Project workforce population projections and Kuwaiti affordable housing estate tender calendars.
Several conditions sit outside the modeled scope, including unannounced giga-project scope revisions, abrupt GCC customs union tariff reconfigurations, and sovereign liquidity constraints affecting Saudi Real Estate Development Fund disbursement timing. Forecasts reflect documented assumptions regarding steel price stabilization and GSO audit capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Turkey Construction Market
Building Construction
China Modular Construction Market
Building Construction
Europe Modular Construction Market
Building Construction
India Prefabricated Buildings Market
Building Construction
Honduras Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Singapore Data Center Construction Market
Building Construction
Prefabricated Construction Market
Building Construction
Japan Construction Market
Building Construction
Modular and Portable Building Market
Building Construction
Sweden New Construction Market
Building Construction
US Prefabricated Buildings Market
Building Construction
Energy-Efficient Building Market
Building Construction
Italy Construction Market
Building Construction
Spain Prefab Wood Buildings Market