
 Asia-Pacific Ceramic Sanitary Ware Market | 2026-2036
Asia-Pacific Ceramic Sanitary Ware Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ceramic Sanitary Ware Market Outlook
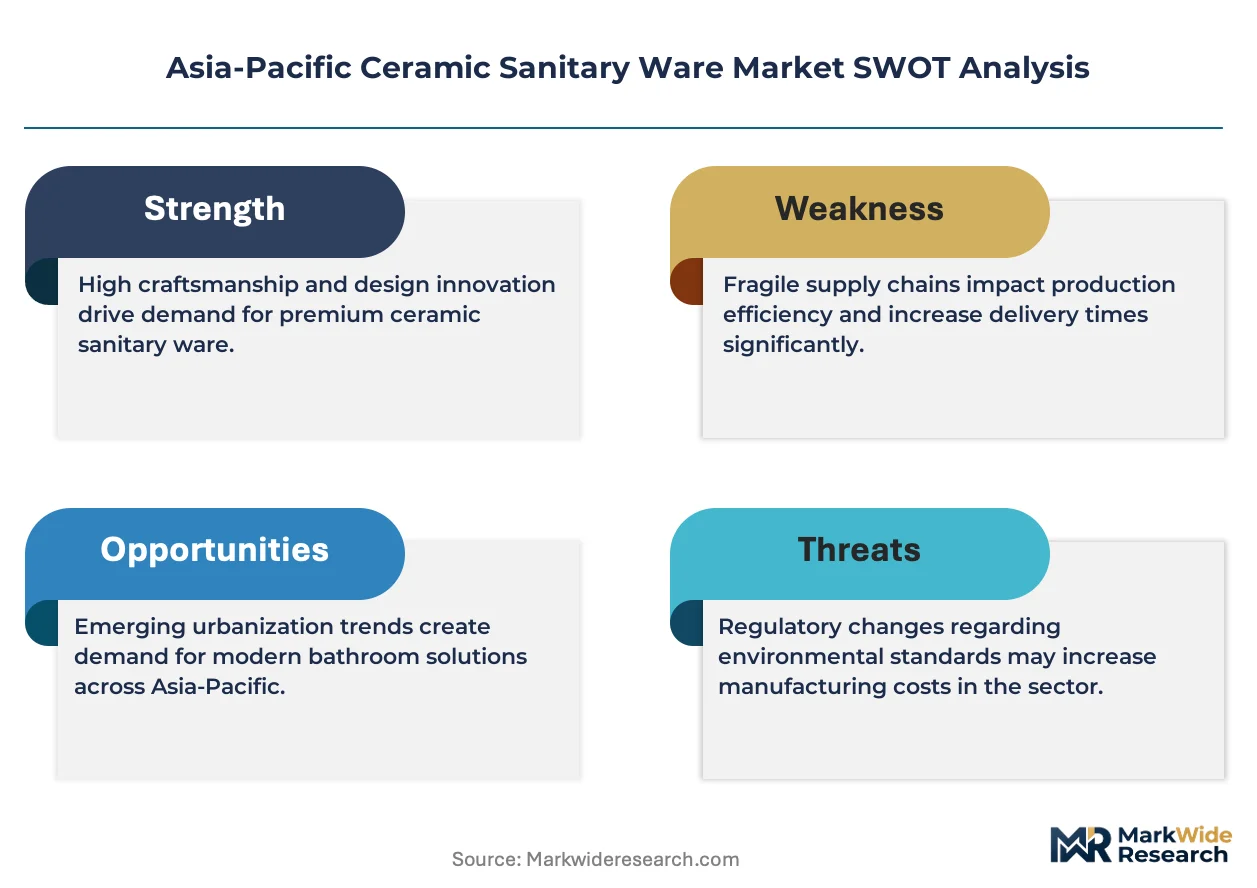
India's BIS certification revision for ceramic plumbing fixtures is consolidating the cost-of-entry calculus across the Asia-Pacific Ceramic Sanitary Ware landscape. Toto Inc. leverages its integrated kiln technology leadership to sustain premium positioning in Japan and Australia. RAK Ceramics anchors its competitive stance through captive raw-material sourcing across the UAE-India corridor. Lixil Group Corporation competes by controlling distribution depth in Southeast Asian home improvement channels.
Asia-Pacific ceramic sanitary ware encompasses vitreous china and fine fireclay fixtures formed through slip casting or pressure casting, fired above 1200 degrees Celsius to achieve non-porous, hygienic surfaces designed for water closets, lavatories, and institutional plumbing systems. Toilets dominate volume throughput across residential and commercial pipelines, while bidets are gaining structural momentum in South Korea and Japan amid hygiene-upgrade cycles. The offline channel still occupies the majority of transaction value in India and Indonesia, though specialty stores are differentiating through design consultation and installation bundling.
India's BIS, China's SAMR, and Australia's WaterMark scheme collectively shape product standards, testing protocols, and cross-border market access across the region. India's PLI scheme for ceramics is redirecting capital toward automated glazing lines and energy-efficient tunnel kilns. Stakeholders must monitor how China's evolving GB standards for water consumption per flush interact with Australia's WaterMark certification reciprocity talks, as divergence here would fragment supply chain planning for pan-Asia manufacturers.
Market Dynamics
India's BIS certification tightening is compressing the supplier base across Asia-Pacific ceramic sanitary ware, forcing smaller fabricators toward either consolidation or exit while automated kiln operators capture displaced volume.
Growth Catalysts
- Water-efficiency mandates:Australia's WaterMark scheme and China's GB standards for flush-volume limits are accelerating fixture replacement cycles in commercial and residential buildings. Specifiers now prioritize dual-flush and rimless designs to preempt compliance deadlines.
- Industrial corridor clustering:Vietnam's Binh Duong province is absorbing capital inflows for export-oriented kiln complexes that serve both domestic Southeast Asian demand and overseas buyers. Proximity to Ho Chi Minh City's port infrastructure reduces logistics friction for containerized sanitary ware.
- PLI scheme redirection:India's production-linked incentive scheme for ceramics is channeling investment toward automated glazing lines and energy-efficient tunnel kilns. Domestic manufacturers are retrofitting legacy plants to capture subsidy-linked output thresholds.
Market Restraints
- Feldspar and kaolin price volatility:Raw material input costs for ceramic body formulation fluctuate with energy-intensive mining operations in India and China. Smaller fabricators lack long-term offtake agreements to hedge against spot-market spikes.
- Kiln technology supplier concentration:Advanced roller-hearth and tunnel kiln systems are concentrated among a limited set of German and Italian equipment providers. Asian manufacturers face extended lead times and currency exposure when importing firing infrastructure.
- Compliance cost asymmetry:India's revised BIS certification for ceramic plumbing fixtures imposes testing and documentation burdens that favor capital-rich producers. Mid-tier fabricators in Morbi and Thangadh report margin compression from repeated sample submission cycles.
Strategic Opportunities
- Underpenetrated rural India:Sanitary ware penetration in India's tier-3 towns and villages remains below urban benchmarks. Government sanitation programs and microfinance availability are unlocking first-time fixture purchases outside metro corridors.
- Smart fixture convergence:Integration of sensor-activated flush mechanisms with ceramic substrates is creating premium product categories. Japanese and South Korean building automation standards are driving specification of touchless water closets in healthcare and hospitality.
- Direct-to-contractor platforms:Digital procurement channels are disintermediating traditional distributor networks for project-scale orders. Construction consortia in Indonesia and the Philippines are piloting aggregated purchasing to compress procurement cycles.
Industry Challenges
- Glaze chemist scarcity:Formulation expertise for vitreous china surface engineering is concentrated among aging specialists in Japan and Italy. Southeast Asian manufacturers struggle to recruit talent capable of optimizing thermal expansion coefficients for local raw material blends.
- Certification timeline compression:Australia's WaterMark and India's BIS operate on non-harmonized testing protocols. Pan-Asia manufacturers face duplicated sample preparation and laboratory scheduling when targeting multiple national markets simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ceramic Sanitary Ware Market |
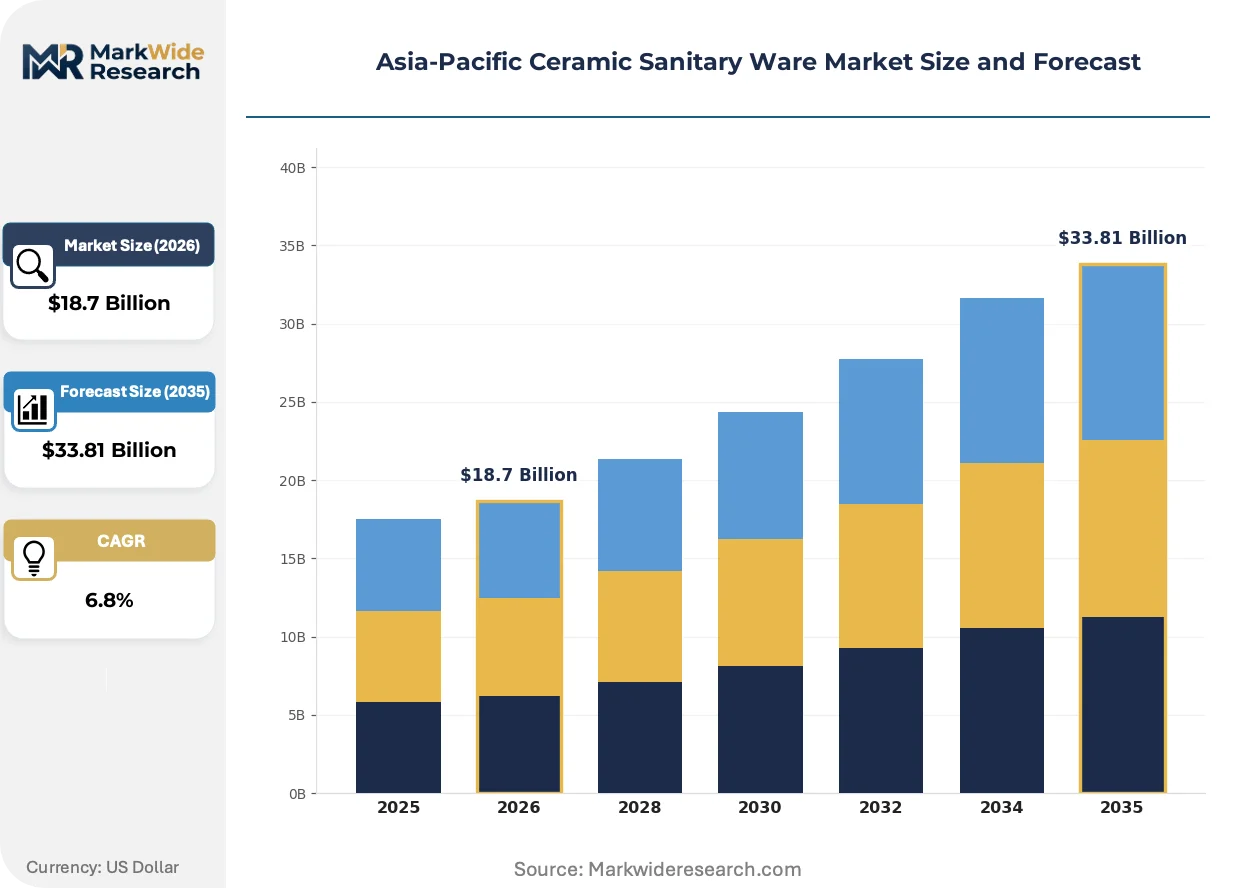
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilets, Basins, Bidets, Urinals Distribution Channel: Online, Offline, Specialty Stores, Home Improvement Retailers End User: Residential, Commercial, Institutional, Hospitality Design Type: Modern, Traditional, Minimalistic, Utility |
| Companies Covered | Kohler Co., Toto Inc., Roca Sanitario, RAK Ceramics, Lixil Group Corporation, Kerovit, Geberit AG, Villeroy & Boch AG, Somany Ceramics Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ceramic Sanitary Ware Market Strategic Shifts
Digital firing control systems and water-consumption benchmarking are compressing the performance gap between premium and mid-tier ceramic sanitary ware across Asia-Pacific specification channels.
Pressure-casting automation is decentralizing production scale requirements across the Asia-Pacific ceramic sanitary ware landscape. Mid-cap manufacturers in Vietnam and Indonesia are adopting robotic slip-casting cells previously accessible only to integrated multinationals. This technology diffusion is enabling regional fabricators to match dimensional tolerances of imported premium fixtures without captive raw-material sourcing.
India's BIS revision for ceramic plumbing fixtures is mandating stricter water absorption and load-bearing thresholds effective across domestic and export-bound production. The regulation is forcing Morbi-cluster manufacturers to upgrade from traditional biscuit firing to single-fire vitrification processes. Export-oriented fabricators are prioritizing BIS certification as a competitive signal in Middle Eastern and African markets where Indian-origin ware dominates volume.
Specialty retail channels are bundling design consultation with installation coordination to differentiate against price-driven e-commerce platforms. Home improvement chains in South Korea and urban China are deploying in-house specification teams for bathroom renovation projects. This service-layer addition is capturing margin that commodity distributors cannot replicate through transactional sales alone.
Asia-Pacific Ceramic Sanitary Ware Market Segmentation
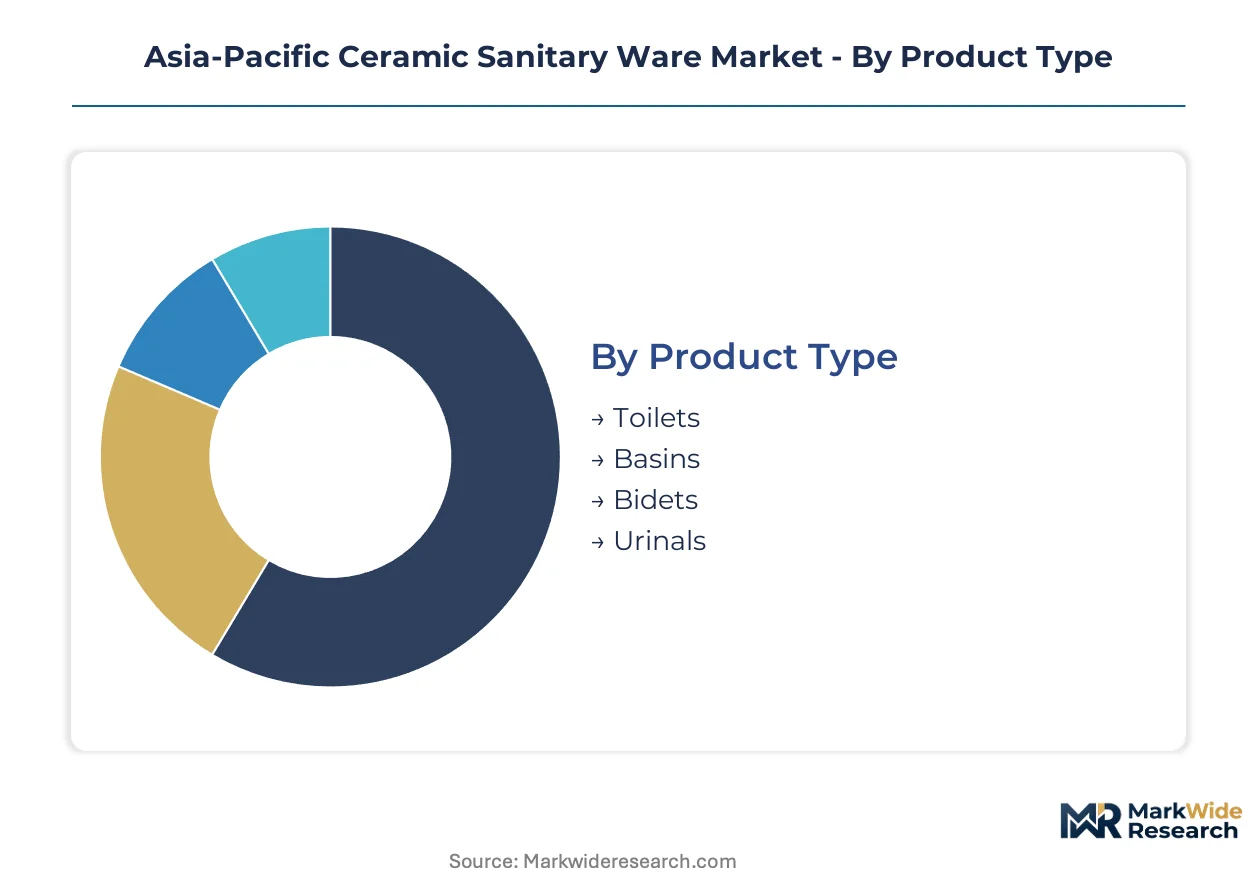
Ceramic sanitary ware procurement in Asia-Pacific stratifies sharply across project scale, specification intensity, and channel access. Product portfolios must align with divergent building codes from Australia's WaterMark to India's BIS while serving everything from mass housing to luxury hospitality fit-outs.
Product Type:
Standardization dominates high-volume categories while premium tiers demand custom glaze formulations and dimensional precision.
- Toilets:Water closets absorb the majority of kiln throughput across residential and commercial pipelines. India's BIS water-absorption thresholds and Australia's flush-volume mandates are compressing supply toward single-fire vitrification processes in Morbi and Thangadh clusters.
- Basins:Countertop and undermount varieties exhibit the widest specification variance across hospitality and high-end residential projects. Vietnam's Binh Duong corridor is capturing export orders for rimless designs meeting Japanese JIS dimensional tolerances.
- Bidets:Sensor-integrated variants are gaining specification momentum in South Korea and Japan amid healthcare hygiene upgrades.
- Urinals:Waterless and ultra-low-flush models serve commercial restroom retrofits targeting China's GB water-consumption benchmarks.
Most installed capacity flows through Toilets. Expansion is steepest in Bidets.
Distribution Channel:
Channel selection determines margin capture and specification control, with project scale dictating route-to-market efficiency.
- Online:Digital platforms are disintermediating traditional distributors for standardized SKUs in India's tier-2 cities. Construction consortia in Indonesia and the Philippines are piloting aggregated procurement through B2B marketplaces.
- Offline:General trade distributors retain dominance in India's tier-3 towns and Indonesia's outer islands where credit relationships and installation bundling sustain loyalty.
- Specialty Stores:Design consultation and project coordination services differentiate these channels in South Korea and urban China.
- Home Improvement Retailers:Chains in Australia and Japan leverage specification teams for bathroom renovation bundling.
Offline channels still process the majority of transaction value. Digital penetration is climbing fastest in Online.
End User:
User category shapes everything from certification documentation depth to payment cycle duration.
- Residential:Mass housing projects in Vietnam and Indonesia drive volume absorption of standardized water-efficient fixtures. India's Swachh Bharat sanitation programs are unlocking first-time purchases in rural districts.
- Commercial:Office and retail fit-outs in Australia's major metros prioritize WaterMark-certified dual-flush systems to preempt compliance deadlines.
- Institutional:Healthcare and education facilities in Japan specify touchless ceramic fixtures meeting METI building automation standards.
- Hospitality:Luxury hotel developments across Southeast Asia demand custom glaze finishes and dimensional precision from captive kiln operators.
Residential construction channels the greatest unit volume. Hospitality commands the steepest margin expansion.
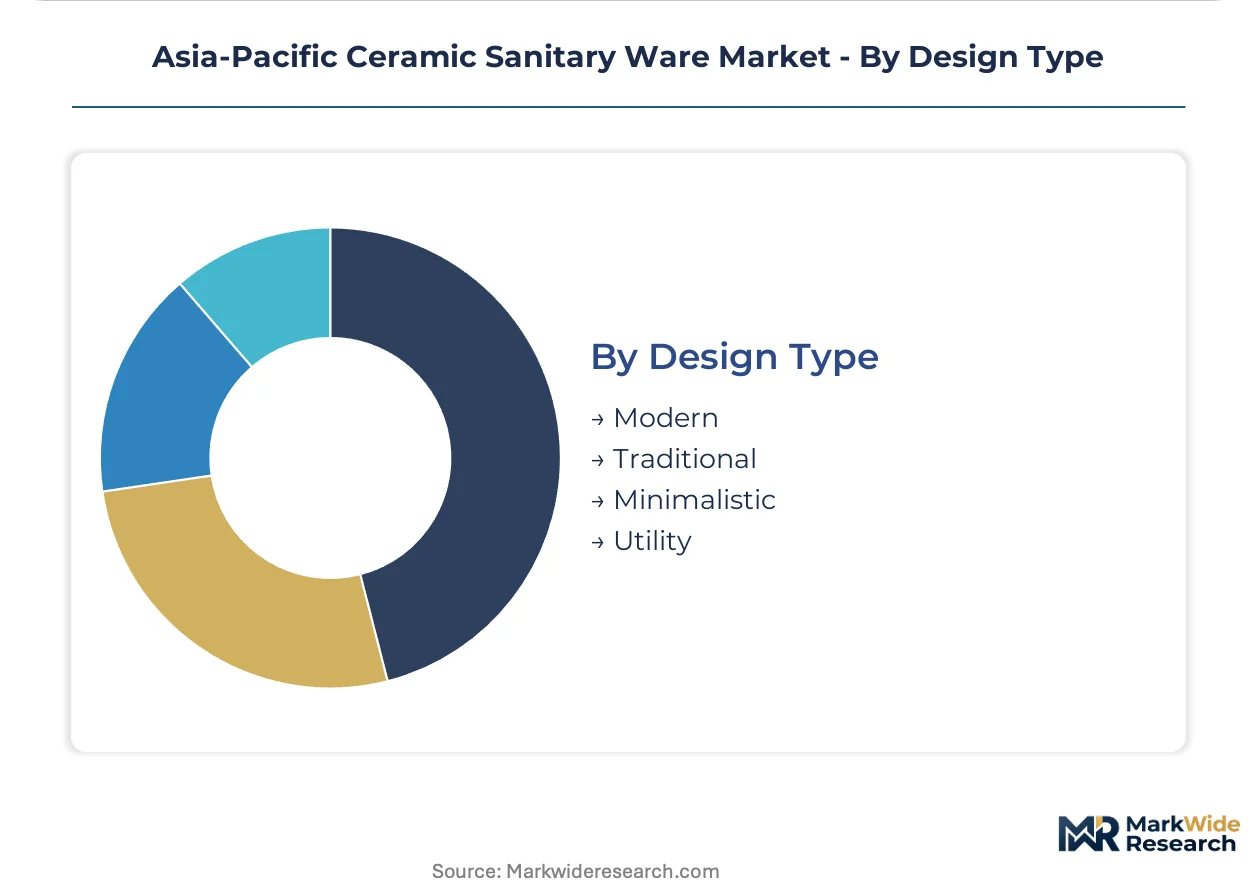
Design Type:
Aesthetic positioning correlates with raw material grade and firing protocol sophistication.
- Modern:Rimless geometries and concealed trapways dominate premium residential and hospitality specifications across South Korea and urban China.
- Traditional:Pedestal basins and close-coupled toilets retain share in India's heritage hospitality projects and conservative residential segments.
- Minimalistic:Wall-hung fixtures with slim cisterns are gaining traction in Japan's compact urban dwellings.
- Utility:Basic vitreous china without decorative glazing serves price-sensitive mass housing in Indonesia and Philippines.
Modern designs command the largest specification share. Minimalistic is gaining share fastest in space-constrained metros.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's post-war reconstruction era established the region's first large-scale vitreous china manufacturing base, with integrated kiln complexes in Seto and Tokoname prefectures setting technical benchmarks that persist across Asia-Pacific specification channels today.
China
Guangdong and Fujian provinces host the densest concentration of automated pressure-casting capacity serving both domestic property development and export markets. SAMR's evolving GB standards for per-flush water consumption are forcing kiln operators to retool glazing lines ahead of compliance deadlines. Foshan's Chancheng district anchors a vertically integrated supply chain spanning raw material refinement to containerized export logistics.
India
Gujarat's Morbi and Thangadh clusters process the majority of domestic sanitary ware volume amid Swachh Bharat rural sanitation program absorption. BIS certification tightening for ceramic plumbing fixtures is compressing the supplier base toward automated single-fire vitrification adopters. The state's PLI scheme for ceramics is redirecting capital toward energy-efficient tunnel kilns in the Rajkot-Surendranagar corridor.
Vietnam
Binh Duong province's industrial corridor is absorbing export-oriented kiln investment serving Southeast Asian and overseas buyers simultaneously. Proximity to Ho Chi Minh City's port infrastructure reduces container logistics friction for ceramic fixture shipments. Domestic residential construction across Hanoi and Da Nang metros is absorbing larger volumes of water-efficient toilet and basin configurations.
Japan
Healthcare and hospitality specification channels drive sensor-integrated bidet and touchless fixture demand under METI building automation standards. Toto Inc.'s integrated kiln technology leadership sustains premium positioning in domestic and Australian export markets. Aging glaze chemist expertise concentrated in Seto and Tokoname prefectures constrains rapid capacity scaling for next-generation vitreous china formulations.
Australia
WaterMark certification mandates accelerate commercial and residential fixture replacement cycles toward dual-flush and rimless designs. Home improvement retail chains leverage in-house specification teams for bathroom renovation project bundling in Sydney and Melbourne metros. Certification reciprocity negotiations with China's GB standards regime remain unresolved, fragmenting supply chain planning for pan-Asia manufacturers targeting both markets.
Asia-Pacific Ceramic Sanitary Ware Market Competitive Environment
The competitive structure tilts toward integrated multinationals with captive kiln technology and raw-material sourcing. Tiered positioning separates automated single-fire vitrification operators from legacy biscuit-firing fabricators facing margin compression. Three archetypes dominate: technology-integrated Japanese specialists, UAE-India corridor raw-material controllers, and Southeast Asian export-platform operators. Capacity expansion and certification pre-positioning constitute the dominant competitive moves as BIS and WaterMark timelines compress.
Among technology-integrated specialists, Toto Inc. exemplifies kiln automation leadership anchored in Japanese domestic production. RAK Ceramics occupies a position representing UAE-India corridor raw-material control across captive sourcing networks. Lixil Group Corporation sits within the distribution-depth archetype, with channel positioning in Southeast Asian home improvement retail. These three company profiles illustrate how competitive positioning stratifies across technology control, upstream integration, and route-to-market density rather than scale alone.
| Leading Market Players |
|---|
| Kohler Co. |
| Toto Inc. |
| Roca Sanitario |
| RAK Ceramics |
| Lixil Group Corporation |
| Kerovit |
| Geberit AG |
| Villeroy & Boch AG |
| Somany Ceramics Limited |
| Others |
Value Chain & Pricing Dynamics
Feldspar and kaolin price indices cascading from energy-intensive mining operations in India and China compress margin structures across premium, standard, and economy fixture tiers. This raw-material cost transmission forces automated kiln operators toward volume-scale absorption while legacy biscuit-firing fabricators in Morbi face exit pressures from unsustainable pricing floors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates WaterMark-certified single-fire vitrification from BIS-compliant biscuit-fired output from unbranded commodity ware. Price differentiation hinges on certification grade and captive raw-material sourcing. Cost compression in the economy tier intensifies as India's PLI scheme redirects subsidy capture toward automated operators. Mass housing developers in Vietnam and Indonesia exhibit highest price sensitivity, while Australian hospitality specifiers absorb premium markups for rimless geometries.
Supply Chain Analysis
Single-source vulnerability sits with German and Italian kiln technology providers supplying roller-hearth and tunnel firing systems to Asian fabricators. Manufacturing gravity centers on China, India, and Vietnam, with ceramic body formulation drawing from feldspar deposits in Rajasthan, kaolin belts in Guangdong, and ball clay reserves in Binh Duong. Extended equipment lead times and euro-denominated procurement expose operators to currency volatility. Distribution runs through project-scale contractor networks in Indonesia and Philippines, with specialty retail chains capturing margin through design consultation bundling in South Korea and urban China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's BIS certification tightening and Australia's WaterMark reciprocity negotiations are accelerating fixture replacement cycles and supplier consolidation simultaneously.
For Market Incumbents: To counter margin compression from automated kiln technology diffusion, prioritize backward integration into captive feldspar and kaolin sourcing across the UAE-India corridor while pre-positioning BIS and WaterMark certification ahead of compliance deadlines. Channel control through specialty retail specification teams in Southeast Asian home improvement chains sustains pricing power against digital disintermediation. For New Entrants and Emerging Players: India's PLI scheme for ceramics opens a window for automated single-fire vitrification investment in the Rajkot-Surendranagar corridor, targeting subsidy-linked output thresholds. Underpenetrated rural India and tier-3 towns present white-space absorption for standardized water-efficient fixtures under Swachh Bharat program procurement. Direct-to-contractor digital platforms in Indonesia and Philippines offer disintermediated route-to-market efficiency against legacy distributor networks. For Investors and Strategic Acquirers: Asymmetric upside sits with automated kiln operators possessing BIS pre-certification and captive raw-material sourcing. Long-term viability favors fabricators with energy-efficient tunnel kiln retrofit completion and export-oriented positioning toward Middle Eastern and African markets where Indian-origin ware dominates volume. Monitor WaterMark-GB standards reciprocity negotiation outcomes as inflection signal for pan-Asia supply chain planning fragmentation or harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Glazing Line Retrofit | Captures India's PLI scheme subsidies while meeting BIS water-absorption thresholds. |
| Captive Raw-Material Sourcing | Secures feldspar offtake agreements insulating against Rajasthan mining cost volatility. |
| Certification Pre-Positioning | Enables simultaneous Australia WaterMark and India BIS market access without duplicated testing. |
| Specialty Retail Channel Expansion | Deploys in-house specification teams capturing renovation project margin in South Korea. |
| Direct-to-Contractor Platform Launch | Disintermediates traditional distributors for aggregated procurement in Indonesian construction consortia. |
Study Parameters
Multiple input streams — kiln technology supplier interviews, ceramic body procurement manager surveys, and regulatory filing analysis — were reconciled against trade flow databases and energy consumption disclosures from Indian and Chinese ceramics clusters. Primary conversations with plant engineers in Morbi and Thangadh, distribution channel partners in Ho Chi Minh City, and specification teams at Australian home improvement retailers were validated against secondary sources including BIS certification registries, SAMR GB standards documentation, and Vietnam industrial zone investment reports. Bottom-up capacity assessments across Binh Duong kiln complexes were triangulated with top-down market sizing from construction pipeline data.
Historical shipment patterns from Indian customs records and Australian import statistics were cross-referenced against expert panel inputs from glaze chemists in Seto and Tokoname prefectures. The analytical framework modeled volume trajectories across product type, distribution channel, end-user category, and design aesthetic segments throughout the forecast period. CAGRs were derived from regression analysis of kiln capacity expansion timelines against residential and commercial construction absorption rates in Hanoi, Da Nang, and Southeast Asian metros. Water-efficiency mandate implementation schedules and PLI scheme disbursement trajectories served as industry-specific demand drivers.
Revisions become necessary when BIS-WaterMark reciprocity negotiations collapse, feldspar export restrictions emerge from Rajasthan, or Vietnamese industrial corridor power infrastructure fails to match kiln complex expansion. Forecasts reflect assumptions regarding subsidy continuity, raw-material price band stability, and certification timeline adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Glazed Tiles Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
European Cross-Laminated Timber Market