
 Roofing Liners Market | 2026-2036
Roofing Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Roofing Liners Market Intelligence
Performance-grade membrane specifications is unwinding legacy commodity dynamics across the roofing liners industry. Owens Corning leverages its fiberglass-reinforced product portfolio to command premium positioning in commercial specifications. Carlisle Companies anchors its competitive stance through backward integration into polymer compounding, securing raw material consistency. Sika AG differentiates via global formulation expertise applied to regional climate conditions.
Roofing liners are synthetic or bituminous sheet membranes engineered to 30–60 mil thickness, manufactured through calendering or extrusion processes, and installed as the primary weatherproofing barrier on low-slope building envelopes. EPDM and TPO formulations currently dominate volume flows, with TPO capturing accelerated specification growth due to heat-weldable seams and reflective surface properties; the 40–50 mil thickness band concentrates margin pools as commercial warranties extend toward 20-year terms. Mechanically attached and fully adhered installation methods split the commercial segment, with self-adhered systems penetrating residential retrofits where labor availability constrains hot-work permitting.
Federal EPA Energy Star roofing criteria and state-adopted versions of ASHRAE 90.1 shape product development cycles by mandating minimum solar reflectance and thermal emittance values. OSHA fall-protection standards and FM Global wind-uplift classifications further filter market access, privileging manufacturers with certified assembly testing. Stakeholders must track evolving polymer feedstock volatility and building code harmonization between municipal jurisdictions to anticipate specification shifts.
Market Dynamics
Membrane specification upgrades are compressing commodity-grade margins while concentrating volume among performance-certified manufacturers. Commercial warranty extensions toward 20-year terms are forcing raw material transparency and assembly testing investments across the supply base.
Growth Catalysts
- ASHRAE 90.1 adoption:State energy codes in California, Texas, and Florida mandate minimum solar reflectance values, accelerating TPO specification for low-slope commercial envelopes.
- Heat-weldable seam technology:TPO formulations with automated welding compatibility reduce labor hours and inspection failure rates in large-format installations.
- Retrofit density in Sun Belt metros:Aging single-ply stock in Phoenix, Las Vegas, and Miami drives replacement cycles with reflective membrane upgrades.
Market Restraints
- Polypropylene feedstock volatility:TPO resin costs fluctuate with propylene monomer availability, compressing margin predictability for non-integrated compounders.
- EPDM demand concentration:Black membrane preference persists in northern industrial applications, limiting reflective product penetration in cold-climate warehouse segments.
- FM Global wind-uplift certification:Assembly testing requirements filter market access, privileging manufacturers with captive laboratory capacity.
Strategic Opportunities
- Self-adhered system penetration:Residential retrofit channels in labor-constrained municipalities favor peel-and-stick membranes over hot-work permitting requirements.
- Cool roof incentive stacking:Utility rebate programs in Arizona and Colorado layer atop federal Energy Star criteria, improving project economics for reflective specifications.
- Building-integrated photovoltaics convergence:Membrane manufacturers partnering with solar module suppliers capture racking-integrated waterproofing specifications.
Industry Challenges
- Certified welder availability:Automated seaming equipment requires operator training that outpaces vocational pipeline output in secondary construction markets.
- Assembly testing backlog:FM Global and UL certification queues extend lead times for new product introductions, delaying specification capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roofing Liners Market |
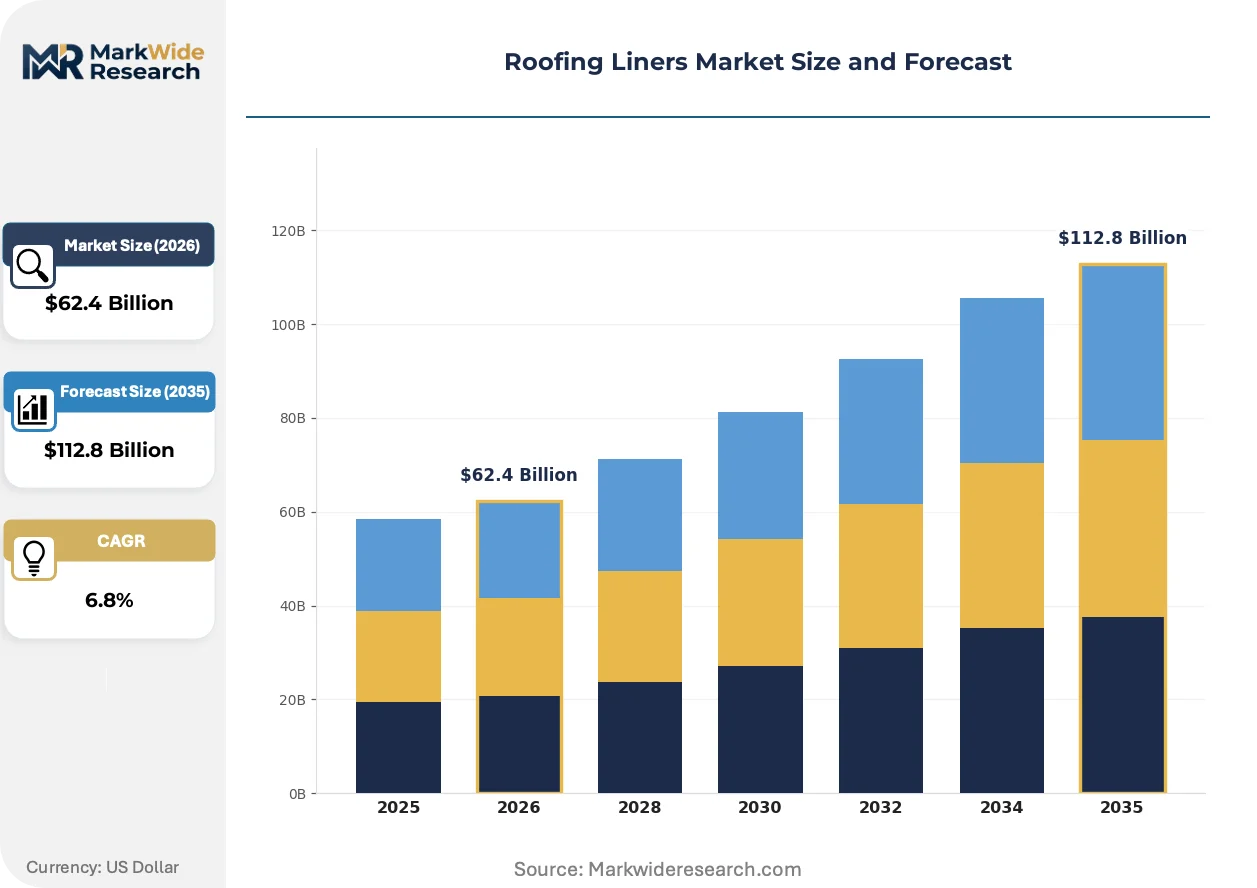
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, TPO, PVC, Bitumen Installation Method: Mechanically Attached, Fully Adhered, Ballasted, Self-Adhered End User: Residential, Commercial, Industrial, Educational Thickness: 20 Mil, 30 Mil, 40 Mil, 50 Mil |
| Companies Covered | GAF Materials Corporation, Owens Corning, CertainTeed Corporation, Carlisle Companies, Firestone Building Products, Sika AG, IKO Industries, Atlas Roofing Corporation, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roofing Liners Market Strategic Shifts & Innovations
Product development cycles are compressing as code harmonization across municipal jurisdictions forces simultaneous compliance with multiple performance standards. Manufacturers are reconfiguring R&D allocation toward climate-zone-specific formulation.
Thick-mil reinforced TPO is fragmenting specification tiers as 60-mil and 80-mil products capture premium commercial warranties previously reserved for multi-ply systems. Institutional buyers in healthcare and education verticals specify these grades for lifecycle cost certainty. The technology is fragmenting procurement patterns, with owners separating membrane supply from installation contracts to enforce material traceability.
EPA Energy Star roofing criteria revisions are tightening solar reflectance minimums for steep-slope applications previously exempt from cool-roof mandates. Manufacturers with in-house reflectance testing capacity accelerate reformulation cycles. The commercial re-roofing segment in southern states faces accelerated product obsolescence as existing inventories fail pending standard updates.
Specification authority is migrating from general contractors to owner's representatives and third-party commissioning agents. These intermediaries demand substrate-condition documentation and installation-quality verification that traditional distribution channels struggle to provide. The shift is most pronounced in municipal and federal project verticals where prevailing-wage compliance adds documentation burden.
Roofing Liners Market Segmentation
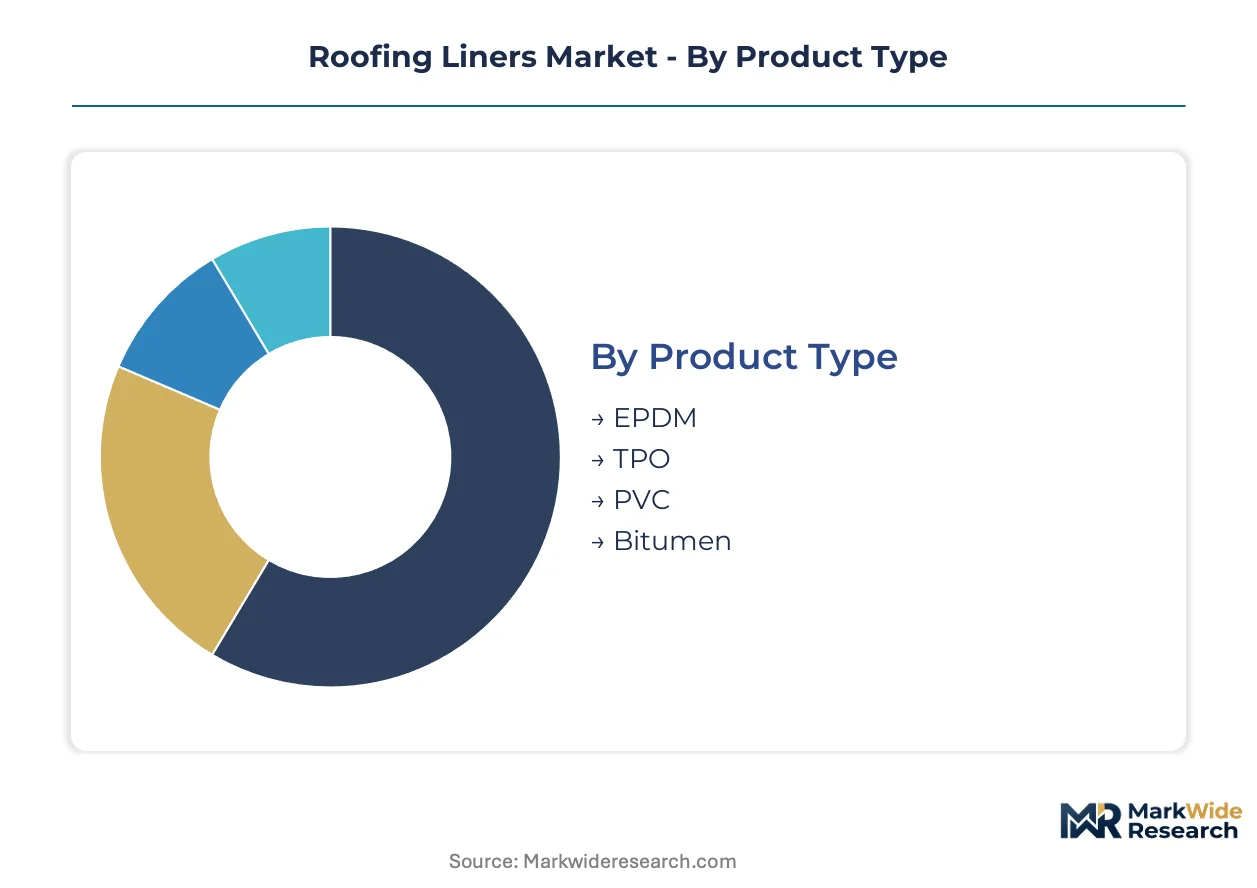
Membrane specification tiers in roofing liners concentrate margin pools unevenly across product categories. Regulatory differentiation in solar reflectance and wind-uplift certification filters which segments capture commercial warranty extensions.
Product Type:
EPA Energy Star criteria and ASHRAE 90.1 state adoptions create divergent compliance pathways for each polymer chemistry.
- TPO:Thermoplastic polyolefin formulations deliver heat-weldable seams and reflective white surfaces that satisfy California Title 24 cool-roof mandates. Demand concentrates in Texas and Florida commercial re-roofing where solar reflectance thresholds are tightening fastest.
- EPDM:Ethylene propylene diene monomer remains the standard for black membrane durability in northern industrial applications. Ohio and Michigan warehouse owners specify this chemistry for UV resistance in snow-load climates where reflectance offers minimal thermal benefit.
- PVC:Polyvinyl chloride membranes provide chemical resistance for food processing and pharmaceutical facilities requiring fume-tolerant roofing.
- Bitumen:Modified asphalt systems persist in multi-ply specifications for institutional clients demanding 30-year lifecycle certainty.
TPO handles the majority of throughput; PVC is climbing the fastest on share as chemical-resistant specifications proliferate.
Installation Method:
Labor availability and hot-work permitting constraints reshape method selection across metropolitan building departments.
- Mechanically Attached:Fastener-based systems dominate large-format commercial installations in high-wind corridors. Miami-Dade County building code amendments favor this method for hurricane-zone membrane security.
- Fully Adhered:Adhesive-applied membranes command premium specifications in healthcare and data center verticals where air-barrier continuity is critical. Phoenix and Las Vegas contractors specify this method for thermal bridging reduction in extreme heat environments.
- Ballasted:Loose-laid membranes with stone ballast serve temporary structures and budget-constrained municipal projects.
- Self-Adhered:Peel-and-stick systems penetrate residential retrofits where certified welder shortages delay hot-work permits.
Mechanically Attached captures the largest project volume; Self-Adhered shows the steepest expansion trajectory as labor constraints tighten.
End User:
Warranty term expectations and specification authority distribution vary sharply across owner categories.
- Commercial:Office and retail property owners drive 40-50 mil TPO specifications with 20-year warranty demands. Third-party commissioning agents in Atlanta and Dallas enforce substrate documentation that filters non-certified installers.
- Industrial:Manufacturing and logistics facilities prioritize EPDM for chemical resistance and puncture tolerance in roof traffic zones.
- Residential:Single-family retrofits favor self-adhered membranes in Sun Belt metros where homeowner association aesthetic rules restrict visible mechanical fasteners.
- Educational:K-12 and university procurement separates material supply from installation contracts to enforce prevailing-wage compliance and material traceability.
Commercial dominates value capture; Educational is gaining specification sophistication fastest as bond-financed projects multiply.
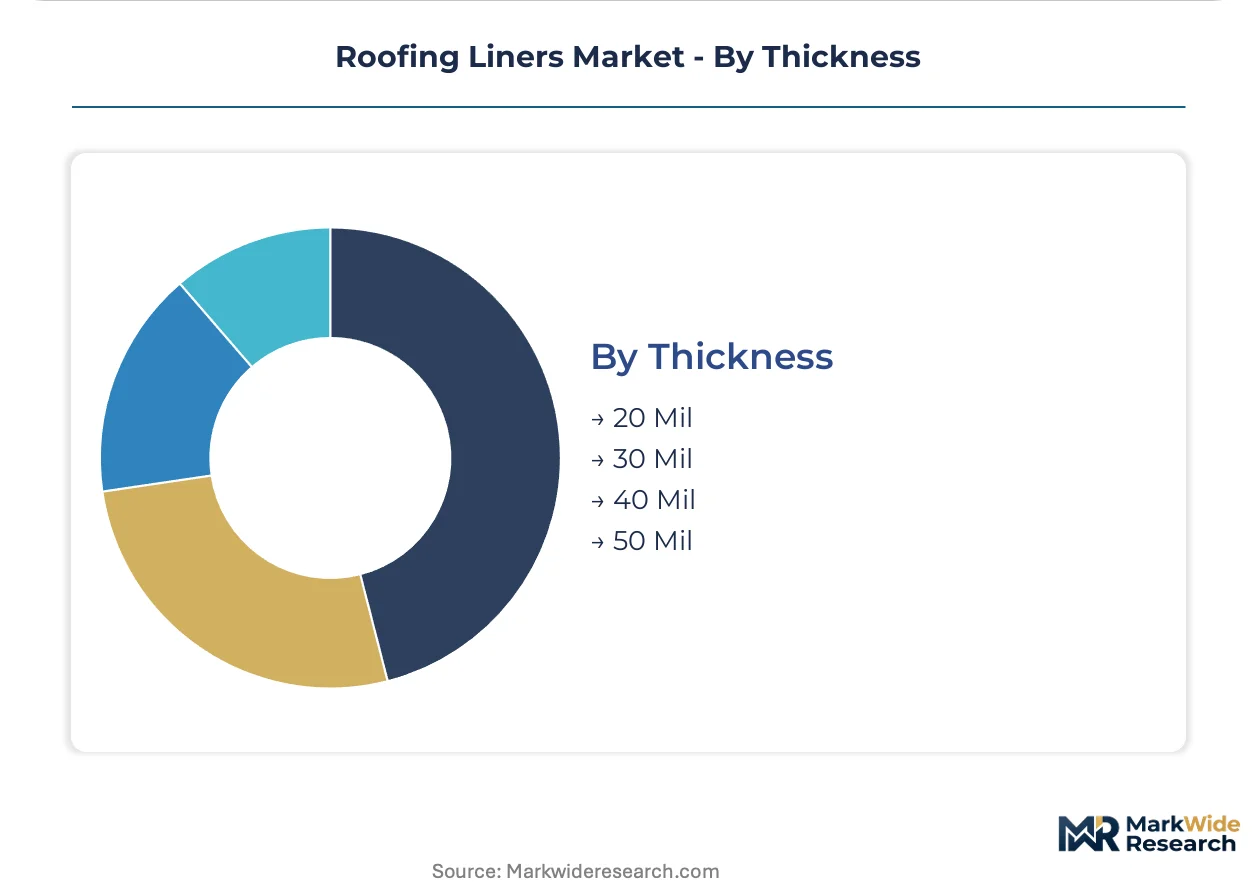
Thickness:
Mil specification directly correlates with warranty eligibility and polymer content cost exposure.
- 40 Mil:Mid-tier reinforced TPO concentrates volume in standard commercial warranties. This specification balances material cost against 15-year warranty eligibility for Class A assemblies.
- 50 Mil:Heavy-duty membranes anchor premium positioning for institutional healthcare and federal building envelopes. Chicago and Boston owners specify this grade for lifecycle cost certainty in high-traffic maintenance zones.
- 30 Mil:Economy-grade specifications serve residential and light commercial applications with shorter warranty horizons.
- 20 Mil:Thin-film products remain confined to temporary weatherproofing and underlayment functions.
40 Mil handles standard commercial throughput; 50 Mil is expanding most quickly as warranty terms extend toward 20 years.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a structural surplus in roofing liner exports to Canada and Mexico under USMCA provisions, while importing specialty polymer compounds from Germany and South Korea. Import dependence concentrates on high-performance TPO resin grades not produced domestically at commercial scale.
United States
Commercial re-roofing in Sun Belt metros drives specification intensity for reflective membranes. EPA Energy Star roofing criteria and ASHRAE 90.1 state adoptions in California, Texas, and Florida mandate minimum solar reflectance thresholds. The Phoenix-Las Vegas corridor concentrates replacement demand as aging single-ply stock reaches end-of-service.
Germany
Industrial facility modernization across the Ruhr and Bavaria sustains demand for chemical-resistant PVC systems. REACH regulation governs polymer additive formulations, forcing reformulation cycles for phthalate-free plasticizers. The Stuttgart-Munich manufacturing belt anchors specification authority for automotive and pharmaceutical plant envelopes.
China
Urban renewal programs in the Yangtze and Pearl River Delta regions accelerate membrane deployment on commercial superstructures. GB standards for building energy efficiency tighten thermal performance requirements for low-slope roofing. Shanghai and Shenzhen municipal codes now mandate cool-roof compliance for new construction above 20,000 square meters.
India
Infrastructure expansion under the Smart Cities Mission drives membrane specification for municipal and institutional buildings. Bureau of Indian Standards certification for waterproofing materials filters import access for non-domestic manufacturers. The Delhi-Mumbai Industrial Corridor concentrates project awards for warehouse and logistics facility roofing.
Japan
Seismic retrofit programs in the Kanto and Kansai regions sustain demand for lightweight membrane systems on existing commercial stock. METI energy efficiency guidelines for non-residential buildings mandate thermal envelope upgrades. The Osaka-Nagoya manufacturing belt specifies high-durability formulations for semiconductor and precision equipment facilities.
Roofing Liners Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and formulation depth. The vendor base splits between diversified building materials conglomerates and membrane-focused compounders. Three archetypes dominate: integrated polymer producers with captive resin supply, regional fabricators with installation-channel relationships, and specialty formulators serving chemical-resistant niches. Competitive moves concentrate on backward integration into polymer compounding and assembly certification investments for wind-uplift ratings.
Within the integrated-manufacturer tier, GAF Materials Corporation and Owens Corning exemplify scale-driven positioning through fiberglass-reinforced product portfolios. Carlisle Companies occupies a position among compounder-integrators with upstream control over polymer formulation. Sika AG anchors the specialty-formulator archetype with regional adaptation of global formulation expertise.
| Leading Market Players |
|---|
| GAF Materials Corporation |
| Owens Corning |
| CertainTeed Corporation |
| Carlisle Companies |
| Firestone Building Products |
| Sika AG |
| IKO Industries |
| Atlas Roofing Corporation |
| DuPont |
| Others |
Cost & Logistics Intelligence
Capacity utilization at TPO resin compounders in Texas and Louisiana sets price floors across membrane specification tiers. Scale advantages at integrated polymer producers compress margin headroom for non-captive compounders serving commercial roofing channels.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing with volume-tiered discounts for 40-mil and 50-mil membrane rolls. Pricing stratifies across premium, standard, and economy tiers based on warranty term length and FM Global wind-uplift certification grade. Cost compression in commodity-grade TPO is intensifying because polypropylene feedstock volatility squeezes non-integrated compounders. Municipal procurement officers show highest price sensitivity; healthcare facility owners with bond-financed projects demonstrate lowest sensitivity due to lifecycle-cost framing.
Supply Chain Analysis
Gulf Coast petrochemical corridor concentration underwrites North American TPO resin availability. Raw material flows draw from propylene monomer production in Texas, ethylene feedstock from Louisiana crackers, and reinforcement scrim from South Carolina fiberglass operations. Single-source vulnerability concentrates at propylene oxide suppliers serving specialty PVC plasticizer formulations. Distribution runs through manufacturer-direct specification sales for large commercial projects and regional roofing distributors for residential retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The roofing liners market sits in early-cycle recovery as commercial re-roofing backlog rebuilds across Sun Belt metros. Federal Energy Star criteria tightening and ASHRAE 90.1 state adoptions provide cyclical uplift through specification upgrade mandates.
For Market Incumbents: Fortify backward integration into polymer compounding to offset propylene feedstock volatility exposure. Deepen captive laboratory capacity for FM Global wind-uplift certification to filter competitor access in hurricane-zone specifications. Prioritize 60-mil and 80-mil TPO formulation R&D to capture institutional healthcare and education verticals extending warranties toward 20-year terms. For New Entrants and Emerging Players: Anchor in self-adhered membrane segments where certified welder shortages delay hot-work permits in labor-constrained municipalities. Target residential retrofit channels in Phoenix and Las Vegas where homeowner association aesthetic rules restrict visible mechanical fasteners. Pursue utility rebate program stacking in Arizona and Colorado to improve project economics for reflective specifications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounder-integrators with captive resin supply and long-term commercial warranty servicing relationships. Five-to-ten year viability favors manufacturers with assembly certification investments and climate-zone-specific formulation libraries. Monitor propylene monomer price spreads as inflection indicator for margin compression risk at non-integrated competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Carlisle Companies secures raw material consistency against propylene feedstock volatility. |
| Assembly Certification Investment | FM Global wind-uplift ratings filter market access in Miami-Dade hurricane zones. |
| Climate-Zone Formulation Development | Sika AG applies global expertise to regional solar reflectance mandates. |
| Self-Adhered System Expansion | Peel-and-stick membranes penetrate residential retrofits where welder shortages constrain permits. |
| Building-Integrated Photovoltaics Partnership | Membrane-solar convergence captures racking-integrated waterproofing specifications. |
Research Approach
Operator-level perspectives from commercial roofing contractors, membrane specification consultants, facility maintenance directors, and municipal procurement officers anchored the qualitative base. Primary interview findings triangulated against customs trade data, EPA Energy Star certification databases, state energy code adoption records, and SEC 10-K filings from listed building materials conglomerates. Bottom-up volume modeling across thickness tiers and installation methods reconciled with top-down market sizing from polymer feedstock consumption patterns.
Sensitivity analysis tested forecast outputs against propylene price volatility scenarios and ASHRAE 90.1 adoption timing variations across the analysis window. Segmentation dimensions modeled include polymer chemistry, mil thickness specification, installation method, end-use vertical, and regional climate zone. CAGRs derived from replacement cycle analysis of aging single-ply stock and new construction square footage projections. Industry-specific inputs incorporated commercial warranty term extension trends and certified welder pipeline constraints.
Decision-makers should treat outputs as directional under base assumptions of continued EPA Energy Star criteria tightening and stable USMCA trade provisions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as state-level energy code harmonization and polymer feedstock supply reconfiguration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Acoustic Panel Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market