
 Building Insulation Materials Market | 2026-2036
Building Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Building Insulation Materials Market Intelligence
Data center construction is rebalancing the end-user mix alongside traditional residential and commercial building demand. Owens Corning leverages its fiberglass manufacturing scale to serve hyperscale facility projects. Knauf Insulation GmbH anchors European supply through mineral wool specialization. Kingspan Group plc differentiates via high-performance foam board systems for controlled-environment builds.
Building insulation materials are engineered thermal barriers—typically fiberglass (molten glass spun into fibers bonded with phenolic resin), mineral wool (slag or rock melted and fiberized), foam board (extruded or expanded polystyrene, polyisocyanurate), or cellulose (recycled paper treated with fire retardants)—designed to reduce heat transfer across building envelopes and minimize HVAC energy loads. Foam board commands premium positioning in commercial roofs and walls where high R-value per inch drives specification, while fiberglass maintains volume leadership in residential walls due to cost efficiency and installer familiarity. Retrofitting applications are expanding fastest as building energy codes tighten, though new construction still occupies the largest value pool through integrated design-specification channels.
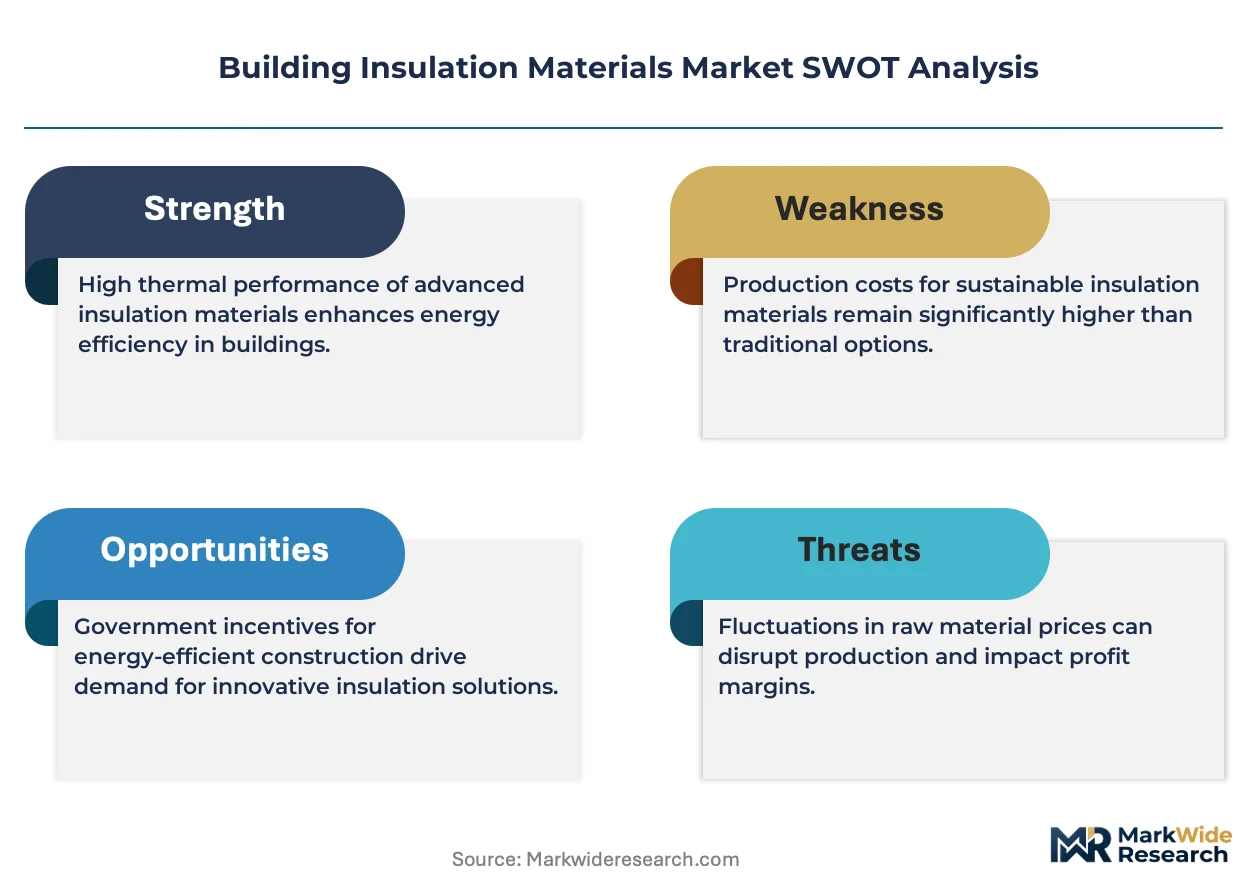
The EU Green Deal and EPBD recast mandate nearly zero-energy building standards across member states, directly lifting mineral wool and foam board specifications. EPA ENERGY STAR and ASHRAE 90.1 in the United States shape product certification thresholds and code adoption timelines. Stakeholders must monitor regulatory calibration cycles and material substitution risks from bio-based alternatives entering test markets.
Market Dynamics
Retrofit mandates across the EU Green Deal are compressing specification cycles and tilting contractor procurement toward mineral wool and high-R-value foam board systems.
Growth Catalysts
- EU Green Deal thermal mandates:Member states face binding near-zero-energy building deadlines, forcing wholesale envelope upgrades across Germany, France, and Poland's aging housing stock.
- Data center hyperscale expansion:Cloud infrastructure buildouts in Northern Virginia, Frankfurt, and Dublin are specifying rigid foam board for precision climate control.
- Cellulose fire-retardant advances:Borate-treated recycled paper insulation is penetrating residential retrofit channels as contractors seek lower-embodied-carbon alternatives.
Market Restraints
- Phenolic resin cost volatility:Fiberglass binder chemistry ties margins to benzene and formaldehyde feedstock fluctuations, squeezing mid-tier manufacturers.
- Slag supply concentration:Mineral wool production depends on steel mill byproduct availability concentrated in China's industrial northeast and the Ruhr Valley.
- Polyisocyanurate technical ceiling:Foam board faces R-value degradation in high-moisture applications, limiting specification in below-grade commercial foundations.
Strategic Opportunities
- Polish retrofit acceleration:Warsaw and Kraków face 2027 EPBD compliance cliffs for pre-1990 multifamily housing, creating concentrated demand for external thermal insulation composite systems.
- Aerogel-blanket convergence:Silica aerogel paired with fiberglass matting is opening thin-profile retrofit applications where cavity depth is constrained.
- Professional installer channel consolidation:National contractor networks in France are capturing specification authority, displacing fragmented local trades.
Industry Challenges
- Building physics modeling skills gap:Hygrothermal simulation expertise lags behind code complexity, delaying envelope design approvals.
- CE marking timeline compression:CPR harmonized standards updates are forcing retesting of legacy mineral wool formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Insulation Materials Market |
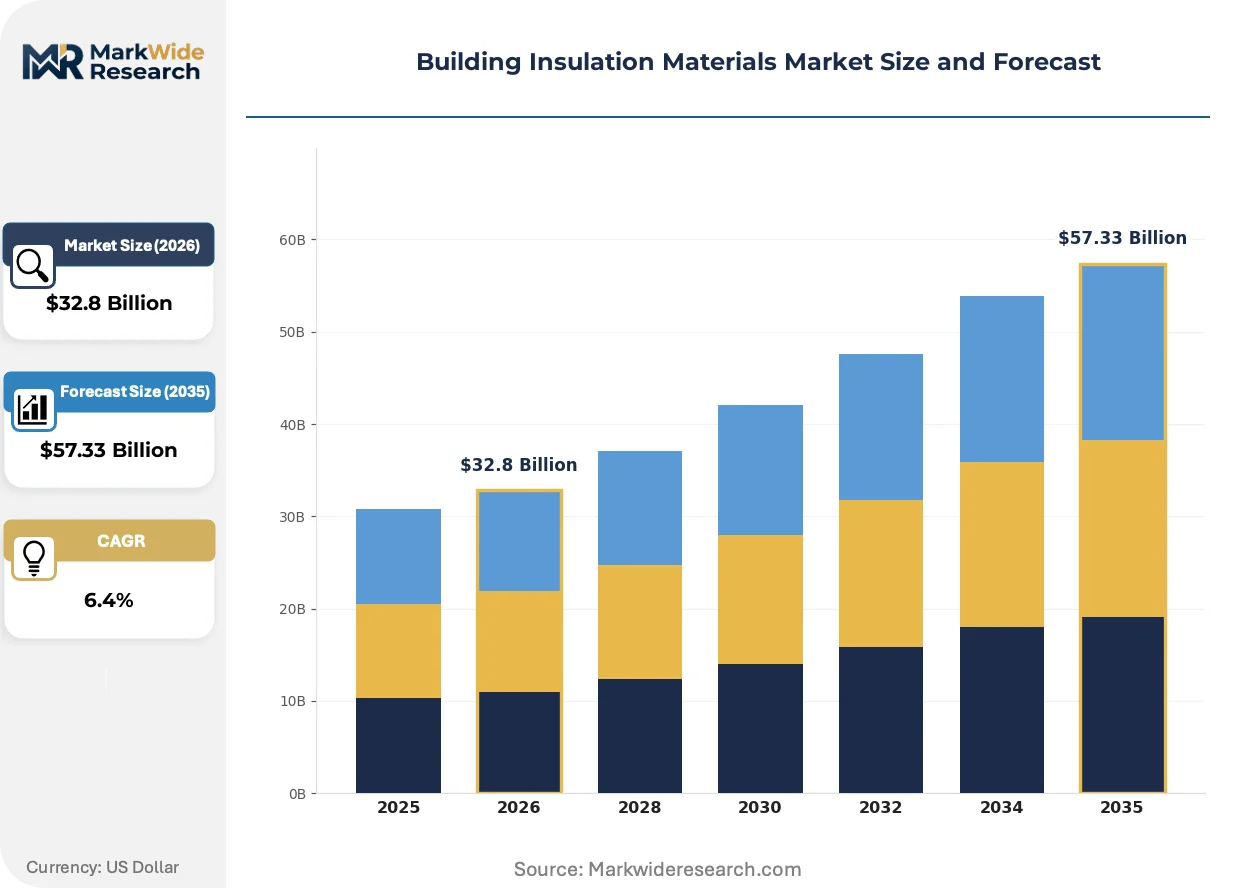
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Foam Board, Mineral Wool, Cellulose Application: Walls, Roofs, Floors, Ducts End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Institutional Projects Installation Type: New Construction, Retrofitting, DIY, Professional Installation |
| Companies Covered | ROCKWOOL International A/S, Knauf Insulation GmbH, Owens Corning, Dow Inc., BASF SE, Compagnie de Saint-Gobain S.A., Johns Manville Corporation, GAF Materials LLC, Kingspan Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Insulation Materials Market Strategic Shifts & Innovations
Bio-based binder chemistry and digital building energy modeling are converging to reshape material specification workflows across retrofit and new construction channels.
Vacuum insulation panels are unifying extreme thermal performance with millimeter-scale thickness, enabling heritage building retrofits where facade preservation rules out conventional insulation depth. Historic preservation authorities in Vienna and Amsterdam are specifying VIP systems for listed structures. The technology is unifying previously incompatible conservation and energy efficiency mandates.
REACH restriction proposals on flame retardants are forcing reformulation of expanded polystyrene chemistry ahead of 2026 sunset reviews. ECHA's regulatory trajectory is compressing R&D timelines for halogen-free alternatives. Nordic building authorities are accelerating specification of mineral wool in schools and healthcare facilities as precautionary substitution.
Energy performance contracting is bundling insulation installation with guaranteed HVAC savings, transferring technical risk from building owners to installation firms. French tertiary sector retrofits are adopting this model fastest. The shift concentrates buyer power among national facilities management groups with balance sheet capacity to underwrite long-term performance guarantees.
Building Insulation Materials Market Segmentation
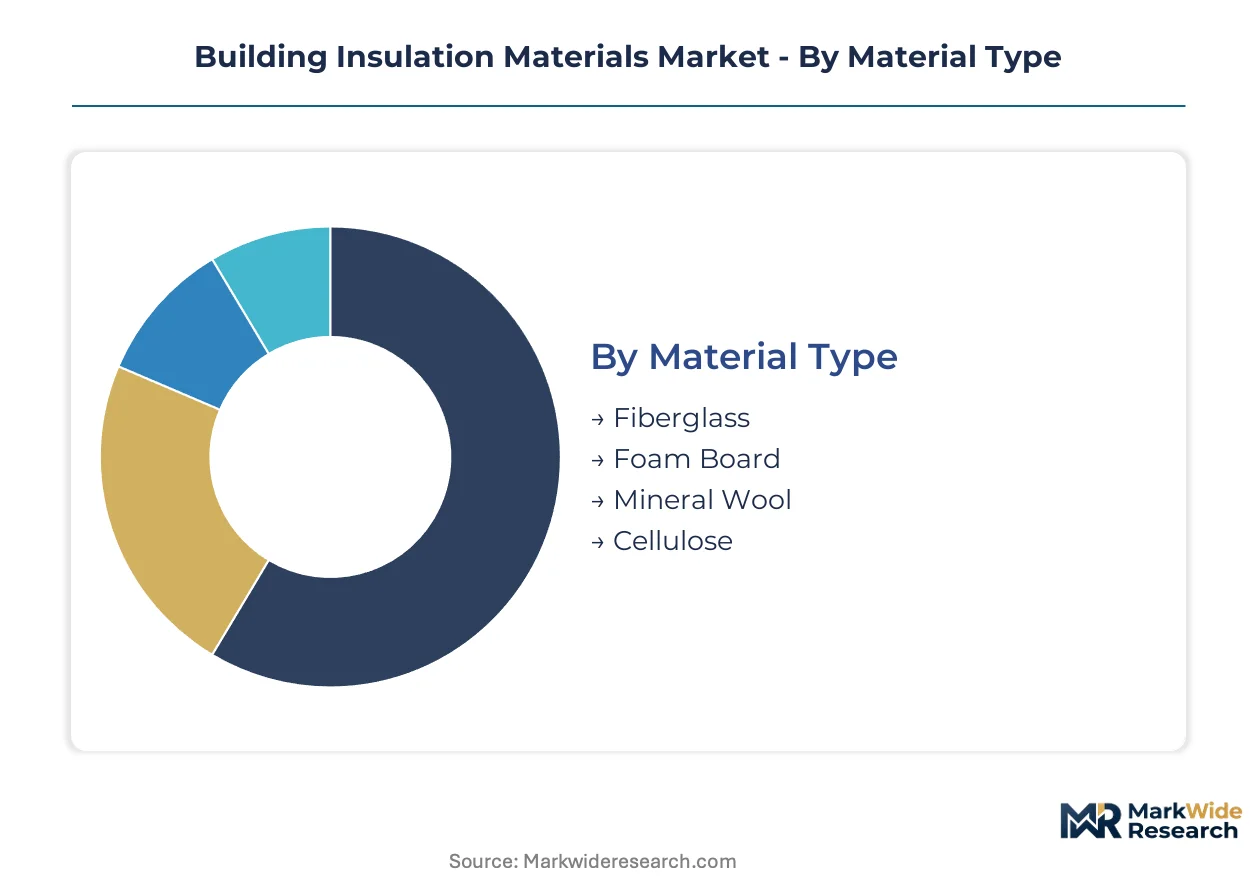
Building insulation materials fragment across four distinct category axes, each governing different procurement logics. Material type determines thermal performance specifications and regulatory compliance pathways. Application and end-user dimensions shape installation protocols and channel economics.
Material Type:
Cost tier and R-value per inch drive specification authority across commercial and residential procurement workflows.
- Fiberglass:Molten glass fibers bonded with phenolic resin deliver cost-efficient thermal resistance. Residential wall cavities in Germany and Poland absorb volume as retrofit deadlines compress contractor procurement cycles toward familiar, installer-friendly systems.
- Foam Board:Extruded polystyrene and polyisocyanurate cores achieve maximum R-value density per inch. Data center builds in Northern Virginia and Frankfurt specify rigid foam for precision climate envelopes where cavity depth constraints meet extreme thermal targets.
- Mineral Wool:Slag or rock fiberization yields fire-resistant, sound-absorbent batts favored in commercial multi-story construction across EU member states tightening EPBD compliance.
- Cellulose:Borate-treated recycled paper offers lower embodied carbon for residential retrofits in France where environmental procurement scoring influences municipal contracts.
Fiberglass leads on scale; foam board leads on momentum.
Application:
Building envelope position dictates moisture management requirements and installation labor intensity.
- Walls:Cavity-fill batts and continuous exterior insulation govern the largest material volume pool. External thermal insulation composite systems dominate Polish multifamily retrofits facing 2027 compliance cliffs.
- Roofs:High-R-value foam board commands premium positioning where thermal bridging risks concentrate heat loss. Commercial flat-roof specifications in France favor polyisocyanurate assemblies with guaranteed performance contracting.
- Floors:Rigid board and batt combinations address slab-edge and crawl-space applications with below-grade moisture challenges limiting foam board specification.
- Ducts:Faced fiberglass wrap and rigid duct board serve HVAC distribution efficiency mandates under ASHRAE 90.1 in US commercial builds.
Walls absorb the greatest volume; roofs generate the highest margin per installed square meter.
End User:
Project scale and professionalization of procurement separate institutional buyers from fragmented residential demand.
- Residential Buildings:Single-family and multifamily structures drive fiberglass and cellulose volume through contractor networks and retail channels. Polish and German housing stock retrofits concentrate demand for mineral wool external systems.
- Commercial Buildings:Office, retail, and hospitality specifications favor high-performance foam board and mineral wool assemblies with energy performance contracting guarantees. French tertiary sector adoption leads this shift.
- Industrial Facilities:Process-integrated thermal management and fire safety requirements specify mineral wool for high-temperature equipment enclosures.
- Institutional Projects:Schools and healthcare facilities across Nordic markets accelerate mineral wool substitution as REACH flame-retardant restrictions compress expanded polystyrene viability.
Residential channels move the most volume; institutional procurement is tightening specification fastest.
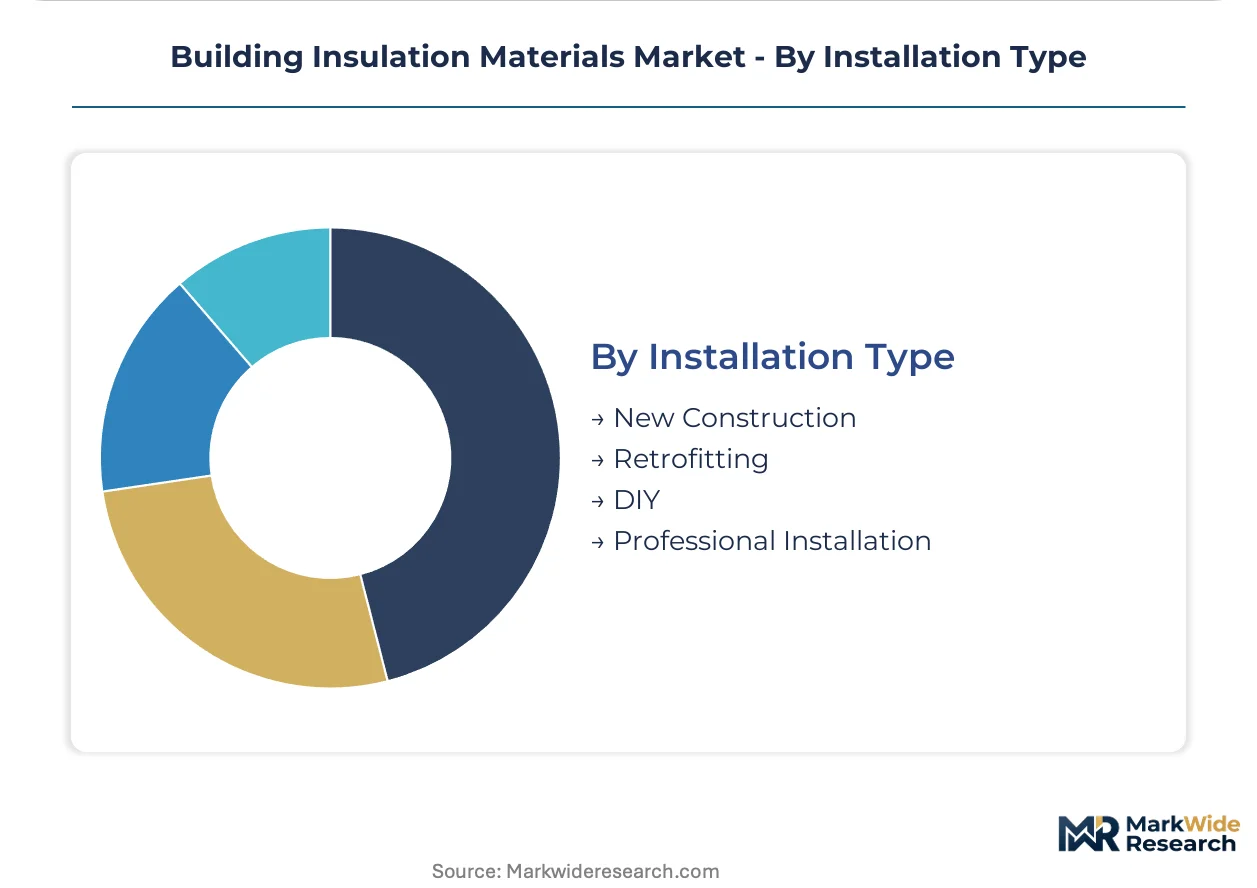
Installation Type:
Channel structure determines margin capture between manufacturers and end-users.
- New Construction:Integrated design-specification workflows embed insulation into architectural packages before ground-breaking. Volume concentrates with national contractor networks in France capturing specification authority.
- Retrofitting:Existing building envelope upgrades expand most quickly as EU Green Deal deadlines force wholesale thermal improvements. Warsaw and Kraków multifamily stock drives concentrated demand for external systems.
- DIY:Big-box retail and e-commerce channels serve homeowner self-installation with batt and roll formats, primarily fiberglass.
- Professional Installation:Certified contractor networks control commercial and institutional procurement, bundling technical risk with guaranteed HVAC savings under performance contracting models.
Professional installation captures the value premium; retrofitting channels are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr Valley industrial corridor concentrates mineral wool production capacity alongside steel mill slag supply chains. Regional retrofit mandates and data center construction are redistributing demand across national markets with varying code enforcement timelines.
Germany
Pre-1990 multifamily housing stock drives external thermal insulation composite system installations in Berlin and Hamburg. The Federal Government's Building Energy Act tightens envelope performance thresholds through 2030. Bavarian industrial zones anchor fiberglass batt manufacturing for Central European distribution.
France
Tertiary sector energy performance contracting accelerates mineral wool specification in Paris and Lyon commercial retrofits. The RE2020 environmental regulation mandates lifecycle carbon accounting for insulation materials. Auvergne-Rhône-Alpes hosts rigid foam board production serving controlled-environment builds.
Poland
Warsaw and Kraków multifamily districts face 2027 EPBD compliance cliffs for thermal envelope upgrades. National building codes align with EU Green Deal near-zero-energy standards through progressive enforcement. Silesian manufacturing corridors supply mineral wool for Baltic state export markets.
United States
Hyperscale data center construction in Northern Virginia specifies polyisocyanurate foam board for precision climate control. EPA ENERGY STAR certification thresholds shape product qualification workflows. Texas and California building codes adopt ASHRAE 90.1 amendments at varying jurisdictional speeds.
China
Steel mill slag availability in the industrial northeast feeds mineral wool production for domestic retrofit programs. Dual carbon goals accelerate envelope efficiency mandates in Beijing and Shanghai municipal jurisdictions. Yangtze River Delta fabrication clusters serve Southeast Asian export demand.
Building Insulation Materials Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers position for EU Green Deal retrofit waves and data center construction cycles. The vendor base organizes around three tiers: integrated chemical conglomerates with feedstock control, specialized insulation pure-plays with formulation expertise, and regional fabricators serving contractor networks. Two strategic archetypes have emerged: scale-driven mineral wool producers leveraging slag supply proximity, and technology-differentiated foam board specialists targeting high-R-value commercial applications. M&A activity concentrates on regional contractor network acquisition, while vertical integration into resin and binder chemistry protects margin exposure to benzene volatility.
Within the European pure-play tier, ROCKWOOL International A/S and Knauf Insulation GmbH exemplify mineral wool specialization anchored to industrial byproduct supply chains. Owens Corning occupies a position representing North American fiberglass scale leadership. Among diversified chemical conglomerates, BASF SE and Dow Inc. sit within the feedstock-integrated archetype, leveraging captive polymer production for foam board formulation control. Kingspan Group plc exemplifies the building envelope systems integrator model, bundling insulation with structural panel solutions. Saint-Gobain's position reflects multi-material portfolio breadth spanning glass, mineral wool, and gypsum-based thermal barriers.
| Leading Market Players |
|---|
| ROCKWOOL International A/S |
| Knauf Insulation GmbH |
| Owens Corning |
| Dow Inc. |
| BASF SE |
| Compagnie de Saint-Gobain S.A. |
| Johns Manville Corporation |
| GAF Materials LLC |
| Kingspan Group plc |
| Others |
Cost & Logistics Intelligence
Certified installer pools in Poland's Silesian corridor concentrate skilled labor availability, compressing wage differentials between premium contractor networks and fragmented local trades. This labor-cost compression narrows pricing-tier spreads across external thermal insulation composite systems as Warsaw retrofit deadlines intensify competition for qualified installation capacity.
Pricing Analysis
Input-cost pass-through from phenolic resin and borate fire-retardant chemistry governs fiberglass and cellulose pricing trajectories. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked mineral wool systems from uncertified regional alternatives. Pricing pressure stems from steel mill slag availability fluctuations affecting mineral wool feedstock costs. Municipal procurement officers in France exhibit highest price sensitivity due to environmental scoring mandates, while data center developers in Northern Virginia prioritize thermal performance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for construction site insulation offcuts remain underdeveloped, though French energy performance contractors are piloting material recovery programs for cellulose reprocessing. Supply concentrates in Germany, China, and the United States for fiberglass matting, slag fiberization, and foam board extrusion respectively. Raw material dependencies encompass benzene derivatives for phenolic binders, steel mill slag for mineral wool, and isocyanurate precursors for rigid foam. Single-source vulnerability in China's industrial northeast slag supply poses structural risk. Distribution runs through national contractor networks capturing specification authority in commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal retrofit mandates tightening specification standards and China's dual carbon goals accelerating domestic envelope efficiency programs at divergent compliance cost structures.
For Market Incumbents: Anchor mineral wool capacity in the Ruhr Valley to secure captive slag supply from ThyssenKrupp and ArcelorMittal operations. Defend against bio-based binder substitution by accelerating borate-treatment R&D for cellulose fire-performance parity. Channel control through acquisition of Polish ETIC system installers protects margin capture as Warsaw compliance cliffs concentrate demand. For New Entrants and Emerging Players: Regional fabricators in the Baltic states represent the most penetrable channel partner type for external thermal insulation composite system distribution. Target Kraków multifamily districts facing 2027 EPBD deadlines where incumbent coverage gaps persist. White-space exists in aerogel-blanket retrofit applications for Vienna heritage structures with cavity depth constraints. Go-to-market through French energy performance contracting networks bundles technical risk transfer with guaranteed HVAC savings. For Investors and Strategic Acquirers: Building envelope systems integrators are the most active acquirer in this space, consolidating regional contractor networks to capture specification authority. Five-to-ten year viability hinges on EU member state enforcement calibration of near-zero-energy building deadlines. Acquisition target archetype: mid-cap mineral wool fabricators with slag supply agreements in Poland or Germany. Monitor ECHA REACH restriction timelines on halogenated flame retardants as inflection indicator for expanded polystyrene substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Resin Production | Captive binder chemistry protects Owens Corning and Johns Manville margins from benzene feedstock volatility. |
| CE Marking Acceleration for Mineral Wool Formulations | CPR harmonized standards updates force retesting investments that concentrate market share among ROCKWOOL and Knauf. |
| Energy Performance Contracting Partnerships | French tertiary sector retrofits bundle insulation with guaranteed HVAC savings, transferring technical risk to installers. |
| Aerogel-Blanket Product Line Extension | Silica aerogel paired with fiberglass matting opens thin-profile heritage retrofit channels in Vienna and Amsterdam. |
| Slag Supply Agreement Renegotiation | Long-term offtake contracts with Ruhr Valley steel mills secure mineral wool feedstock for Knauf and ROCKWOOL expansion. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork encompassed plant managers at fiberglass and mineral wool manufacturing facilities, procurement leads at French tertiary sector energy service companies, technical R&D directors at foam board formulators, and certified ETIC system installers in Warsaw and Kraków. Secondary validation drew from EU EPBD implementation reports, ECHA REACH restriction proposal documentation, German Federal Government Building Energy Act regulatory filings, and SEC 10-K disclosures from listed building materials conglomerates. Bottom-up volume modeling across material type and application segments triangulated against top-down macroeconomic elasticity assumptions.
Comparable-period anchoring calibrated the projection horizon against historical retrofit installation rates through 2023 and new construction permitting velocity across Germany, France, and Poland. The analytical framework segmented by material type, application envelope position, end-user procurement archetype, and installation channel structure. CAGRs derived from elasticity-adjusted demand curves incorporating EU Green Deal compliance deadline phasing and data center hyperscale construction pipelines. Industry-specific forecast inputs encompassed slag supply availability from steel production forecasts and phenolic resin feedstock cost indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA regulatory calibration cycles and bio-based binder technology maturation. Assumptions reflect current EPBD enforcement trajectories and REACH restriction timelines. Practitioners should monitor Polish building code inspection capacity buildout and Nordic mineral wool substitution rates in schools and healthcare facilities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Roof Window Market