
 Medium Cars Market | 2026-2036
Medium Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Cars Market Intelligence
The EU Green Deal's tightening CO2 fleet targets is shifting engineering priorities across European medium car portfolios. Toyota Motor sustains hybrid leadership through its Prius and Corolla platforms, while Volkswagen anchors its ID lineup with dedicated EV architectures for the Golf-class segment. Hyundai Motor Company differentiates through competitive battery-electric offerings that undercut legacy pricing tiers.
Medium cars denote passenger vehicles with wheelbases between 2.65 and 2.80 meters, curb weights of 1,300–1,600 kilograms, and engine displacements or motor outputs calibrated for urban and interurban duty cycles, serving as the primary mobility solution for households and fleet operators balancing cost, interior volume, and maneuverability. Sedan configurations retain residual strength in corporate fleet channels where trunk segregation matters, while crossover variants capture the fastest volume trajectory as ride-height preferences reshape buyer expectations across individual and rental segments. Electric powertrains command disproportionate engineering investment despite gasoline still dominating absolute unit economics in price-sensitive markets.
The US EPA, California Air Resources Board, and EU EMA framework collectively shape powertrain compliance costs, safety certification pathways, and carbon-accounting obligations that determine which medium car variants achieve market access. China's MIIT dual carbon goals and NEV mandate add a third regulatory gravity center that OEMs must satisfy for volume eligibility. Stakeholders should monitor how divergent regional compliance calendars force platform-strategy choices between unified global architectures and market-specific derivatives.
Market Dynamics
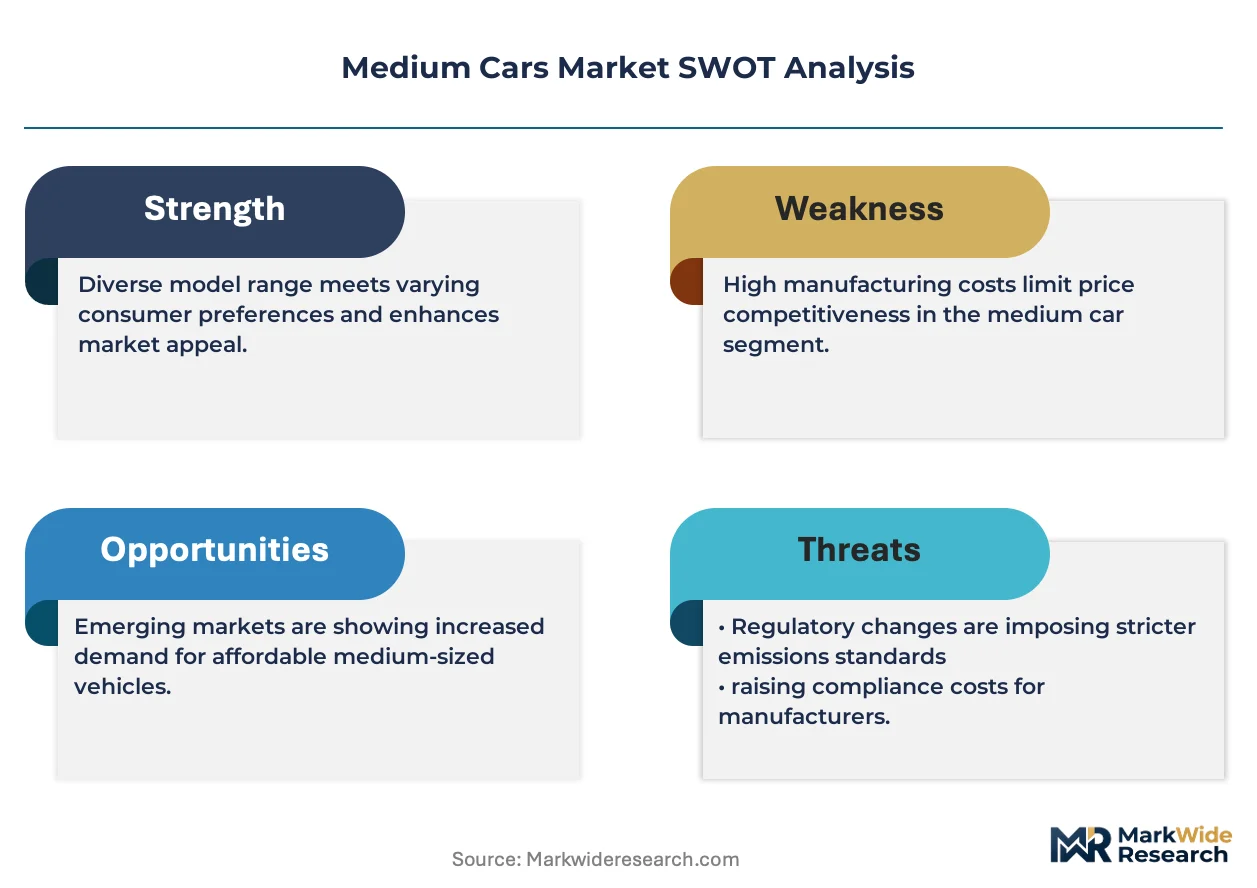
Electrification mandates across multiple jurisdictions are compressing powertrain development cycles while fleet operators accelerate procurement of medium cars for corporate mobility programs, forcing OEMs to reconcile divergent compliance calendars with unified platform economics.
Growth Catalysts
- EU Green Deal CO2 performance standards:The tightening fleet targets compel automakers to accelerate electrification across medium car lineups, expanding eligible model variants for zero-emission zones in Stuttgart, Wolfsburg, and Munich.
- Battery cost convergence:Lithium-ion pack economics are approaching parity with internal combustion powertrains at the 60-80 kWh scale, unlocking volume deployment in the Golf-class segment where total cost of ownership determines fleet procurement decisions.
- Corporate mobility programs:Enterprise fleet operators in Germany are expanding medium car procurement for employee benefit schemes, prioritizing models with certified CO2 footprints that satisfy CSRD reporting obligations.
Market Restraints
- Raw material concentration:Cathode active material supply concentrates in Chinese processing facilities, exposing European automakers to export licensing volatility and forced technology transfer requirements under MIIT industrial policy.
- Charging infrastructure asymmetry:Urban-rural deployment gaps in fast-charging corridors constrain battery-electric medium car adoption outside metropolitan clusters, preserving gasoline residual demand in interurban duty cycles.
- Residual value uncertainty:Depreciation curves for battery-electric medium cars remain unproven at scale, elevating fleet leasing costs and compressing remarketing margins for rental channel operators.
Strategic Opportunities
- Vehicle-to-grid integration:Bidirectional charging capabilities in medium car battery packs open revenue streams from grid stabilization services, with Germany's Bundesnetzagentur developing tariff frameworks for aggregated fleet participation.
- Software-defined architectures:Over-the-air update pipelines enable feature monetization post-sale, converting hardware transactions into recurring revenue from navigation, autonomy, and comfort subscriptions.
- India PLI scheme localization:Component manufacturing incentives under India's production-linked incentive framework attract cell-to-pack assembly investments, establishing export capacity for right-hand-drive medium car variants serving ASEAN markets.
Industry Challenges
- Embedded systems integration:Consolidating legacy supplier ECU architectures into centralized compute domains demands software competency scarce among incumbent tier-one electronics suppliers.
- Homologation timeline compression:Parallel certification pathways for EU type approval, US EPA emissions compliance, and China MIIT new energy vehicle qualification strain engineering bandwidth and delay market entry synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Cars Market |
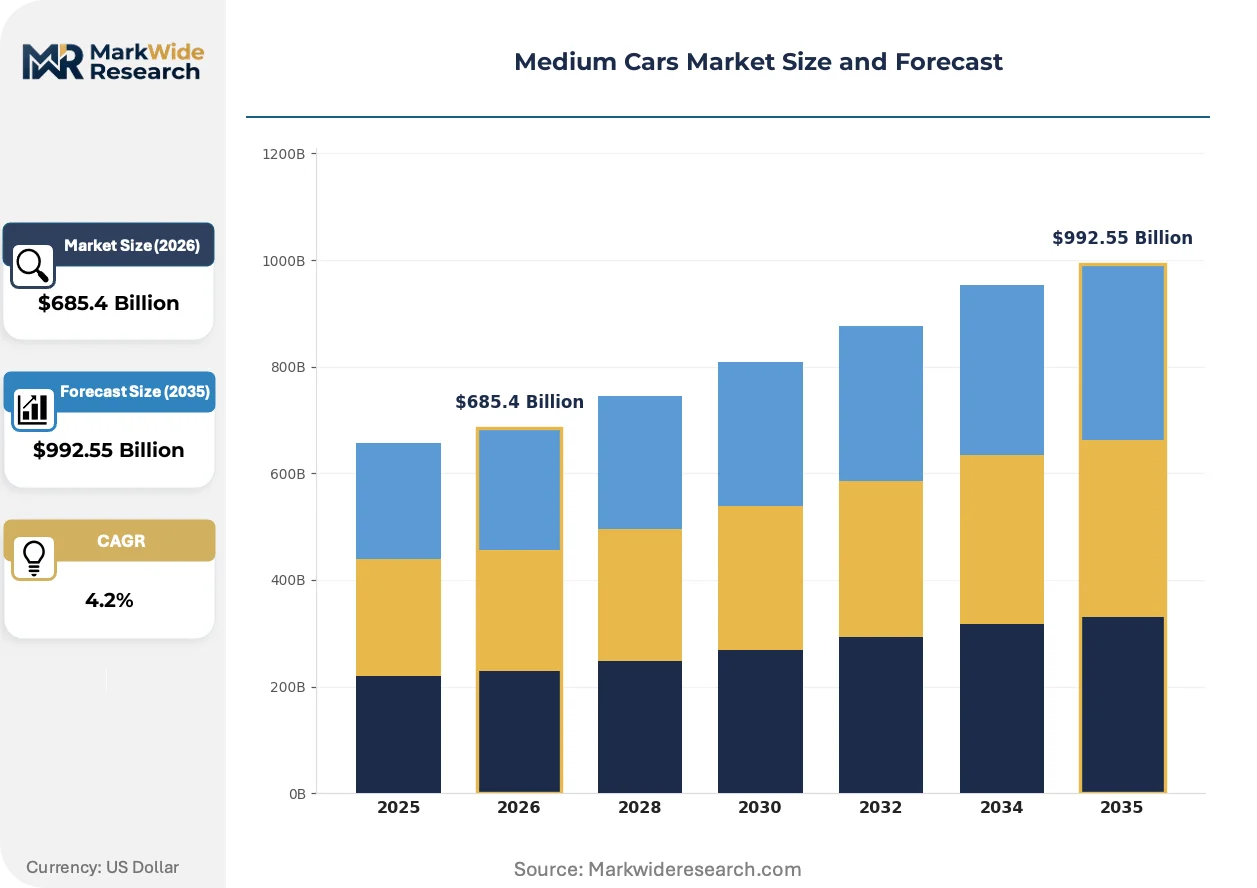
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $992.55 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, Hatchback, Coupe, Crossover Powertrain: Gasoline, Diesel, Hybrid, Electric Customer Segment: Individual Buyers, Fleet Operators, Rentals, Businesses Drive Type: Front-Wheel Drive, All-Wheel Drive, Rear-Wheel Drive, Four-Wheel Drive |
| Companies Covered | Stellantis NV, Toyota Motor, Volkswagen, Hyundai Motor Company, Kia Corporation, General Motors, Ford Motor Company, Honda Motor Company, Renault, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Cars Market Strategic Shifts & Innovations
Powertrain electrification is fragmenting platform development into modular cell-to-pack architectures that accommodate divergent regional regulations without full vehicle redesign, while software monetization and charging infrastructure integration reshape revenue models beyond unit sales.
Cell-to-pack battery engineering is modularizing thermal management and structural integration, eliminating module housings to increase energy density and reduce bill-of-materials complexity. Fleet operators and retail buyers are adopting these configurations as standard offerings in the 60-80 kWh range, compressing development timelines for derivative body styles and enabling faster regional variant deployment.
The EU Green Deal's 2035 fleet CO2 phase-out deadline is accelerating powertrain portfolio decisions, forcing Volkswagen, Toyota, and Hyundai to dedicate engineering resources to dedicated EV architectures rather than adapted combustion platforms. Germany's KBA type approval authority is processing record volumes of battery-electric medium car certifications, with Stuttgart and Wolfsburg engineering clusters prioritizing skateboard chassis designs that satisfy both EU and export market crash standards.
Subscription-based feature activation is displacing trim-level bundling in medium car distribution, with buyers purchasing base hardware and unlocking autonomy, performance, or comfort capabilities through over-the-air payments. Corporate fleet procurement teams in Germany are negotiating enterprise licenses for pooled vehicle access, replacing traditional lease structures with utilization-based contracts that internalize charging and maintenance within per-kilometer rates.
Medium Cars Market Segmentation
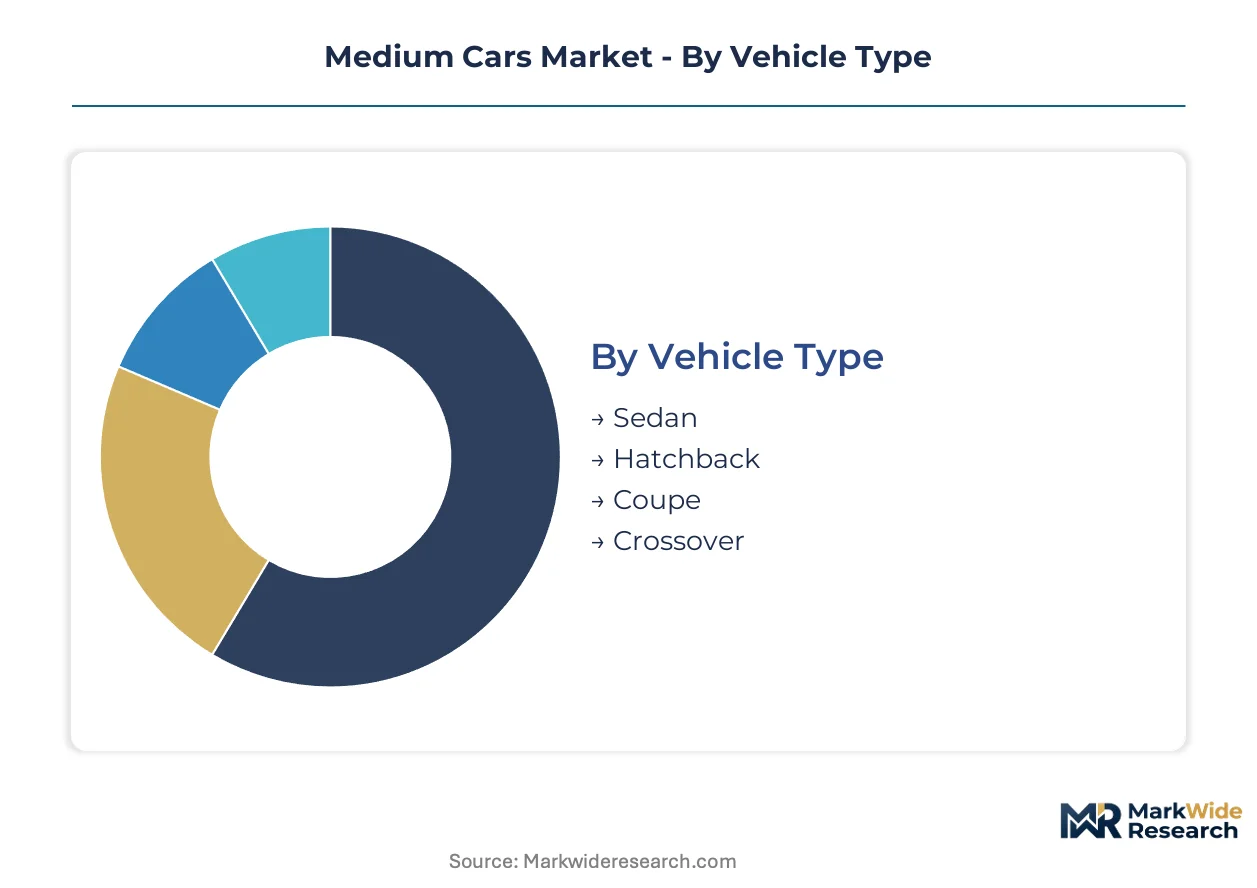
Segmentation in the medium cars market determines regulatory compliance pathways, with each vehicle type and powertrain combination facing distinct EU type approval, EPA emissions, and MIIT new energy vehicle certification requirements. Fleet procurement teams structure RFPs around these boundaries, while OEMs optimize platform economics across segments with divergent homologation timelines.
Vehicle Type:
EU type approval complexity varies sharply across body styles, with sedans requiring separate trunk integrity testing while crossovers face modified pedestrian protection standards under the EU Green Deal framework.
- Sedan:Three-box architecture with dedicated trunk compartment satisfies corporate fleet procurement requirements in Germany where cargo segregation supports CSRD reporting on employee benefit schemes. Stuttgart-based engineering clusters prioritize sedan variants for business lease channels, though volume is shifting toward crossover alternatives.
- Crossover:Elevated ride height and hatchback accessibility capture the steepest expansion trajectory among individual buyers and rental fleets. Wolfsburg engineering centers allocate disproportionate resources to crossover skateboard chassis designs that accommodate both EU and export market crash standards.
- Hatchback:Two-box utility with fold-flat seating dominates European urban markets where parking constraints favor compact footprints. KBA type approval volumes for hatchback variants remain substantial despite share erosion to crossover body styles.
- Coupe:Low-roof two-door configuration serves premium positioning within medium car dimensions, attracting buyers prioritizing styling over rear-seat utility. Homologation requirements align with sedan standards, simplifying platform derivatives for OEMs.
Leading the category by volume: Crossover. Expanding most quickly: Crossover.
Powertrain:
Cost tier stratification separates powertrains by battery scale and compliance investment, with electric variants commanding engineering premiums that fleet operators amortize through total cost of ownership calculations.
- Electric:Battery-electric architectures with 60-80 kWh cell-to-pack configurations approach upfront cost parity with combustion alternatives at scale. Germany's Bundesnetzagentur tariff frameworks enable vehicle-to-grid revenue streams that improve fleet procurement economics.
- Hybrid:Parallel and series-parallel systems bridge regulatory compliance gaps where charging infrastructure remains underdeveloped. Toyota's Prius and Corolla platforms demonstrate volume viability across EU CO2 fleet target compliance scenarios.
- Gasoline:Internal combustion engines with turbocharged downsizing retain absolute unit economics leadership in price-sensitive markets. EPA emissions certification pathways remain streamlined relative to electrified alternatives.
- Diesel:Compression-ignition powertrains face accelerating regulatory pressure under EU urban access restrictions, compressing demand to interurban fleet applications where torque requirements persist.
Highest certification burden: Electric. Steepest volume decline: Diesel.
Customer Segment:
Application-specific duty cycles determine procurement specifications, with fleet operators prioritizing certified CO2 footprints for CSRD disclosure while rental channels emphasize residual value predictability.
- Fleet Operators:Corporate mobility programs in Germany expand medium car procurement for employee benefit schemes, negotiating enterprise licenses for pooled vehicle access with utilization-based contracts.
- Individual Buyers:Household purchasers balance interior volume, maneuverability, and total cost of ownership across urban and interurban duty cycles.
- Businesses:Small and medium enterprises acquire medium cars for commercial applications requiring cargo capacity without van classification.
- Rentals:Daily and weekly rental channels prioritize crossover variants with broad customer appeal and simplified maintenance protocols.
Dominant procurement volume: Fleet Operators. Fastest contract structure evolution: Fleet Operators.
Drive Type:
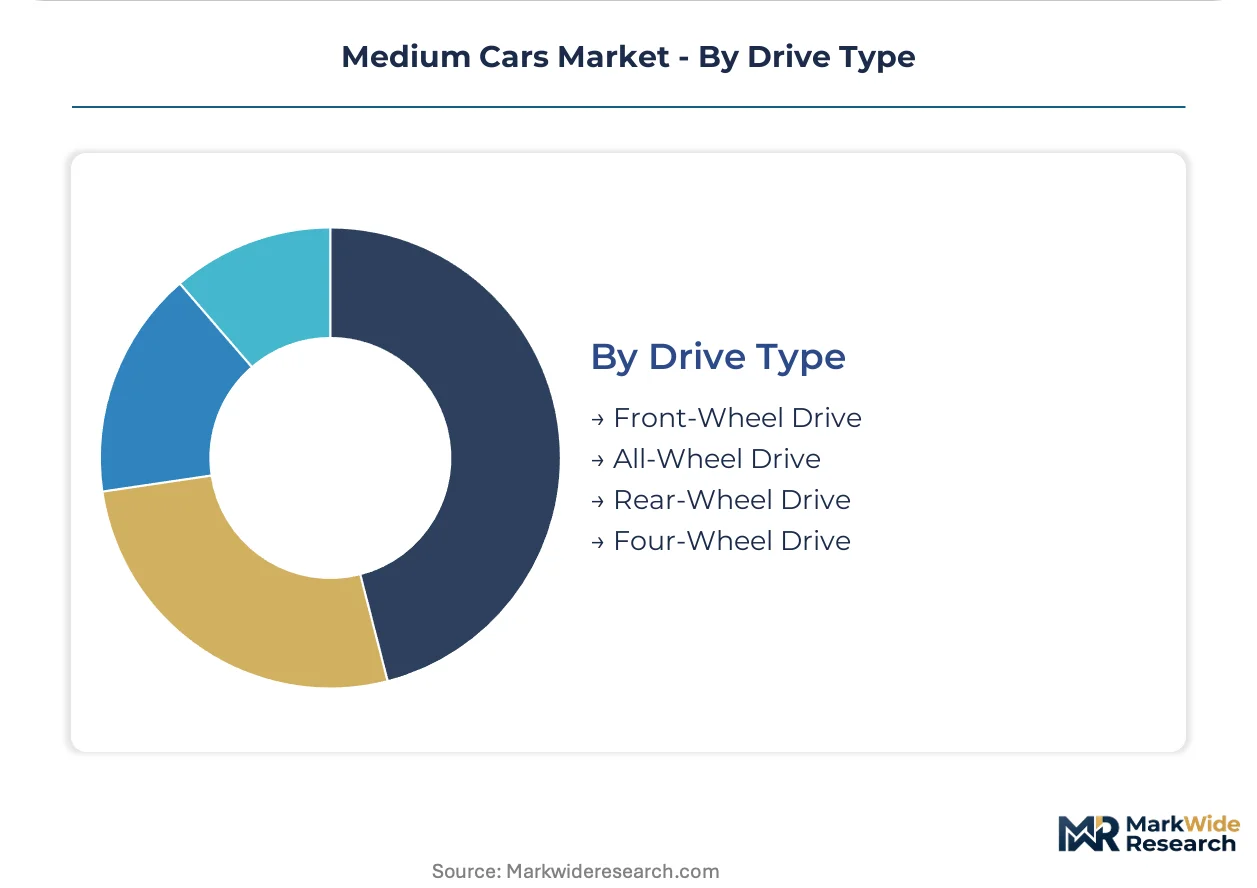
Geography-linked climate and terrain requirements segment drive type demand, with northern European markets favoring all-wheel traction while Mediterranean markets optimize for front-wheel efficiency.
- Front-Wheel Drive:Transverse engine packaging maximizes interior volume within medium car wheelbase constraints, dominating cost-optimized variants for fleet procurement.
- All-Wheel Drive:Multi-plate clutch or electric motor torque vectoring addresses traction requirements in German and Scandinavian markets with seasonal weather variability.
- Rear-Wheel Drive:Longitudinal engine placement supports performance-oriented variants with balanced weight distribution, appealing to enthusiast segments within individual buyer categories.
- Four-Wheel Drive:Part-time or full-time systems with low-range capability serve niche applications requiring off-road traction, rarely specified in standard medium car procurement.
Standard specification across volume: Front-Wheel Drive. Premium upgrade trajectory: All-Wheel Drive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors engineering and production clusters for medium cars, with Wolfsburg and Munich forming complementary development corridors that concentrate R&D investment and regulatory compliance expertise for this segment.
Germany
Corporate fleet procurement for employee benefit schemes drives volume concentration, with enterprises prioritizing certified CO2 footprints for CSRD reporting obligations. Germany's KBA type approval authority processes record volumes of battery-electric medium car certifications. Stuttgart and Wolfsburg engineering clusters prioritize skateboard chassis designs that satisfy both EU and export market crash standards.
China
Domestic NEV mandate compliance and dual carbon goals under MIIT industrial policy shape OEM platform strategies for volume eligibility. The country's MIIT framework adds regulatory gravity that automakers must satisfy for market access. Yangtze River Delta manufacturing bases concentrate cell-to-pack assembly investments serving both domestic demand and export markets.
United States
EPA emissions certification pathways and California Air Resources Board standards determine powertrain compliance costs for medium car variants seeking market access. The US EPA framework shapes safety certification pathways and carbon-accounting obligations. Detroit engineering centers balance electrification timelines against residual gasoline demand in price-sensitive interior markets.
Japan
METI industrial policy and JIS standards guide hybrid powertrain development cycles bridging regulatory compliance gaps. Toyota Motor sustains hybrid leadership through Prius and Corolla platforms calibrated for urban and interurban duty cycles. Nagoya engineering clusters concentrate series-parallel system optimization for export market certification.
India
Component manufacturing incentives under the PLI scheme attract cell-to-pack assembly investments establishing export capacity for right-hand-drive variants. India's production-linked incentive framework supports localization of battery module production. Tamil Nadu and Gujarat manufacturing corridors develop assembly capacity serving ASEAN market requirements.
Medium Cars Market Key Industry Players
Premium-margin players sit above commodity-margin players across electrification investment intensity, with dedicated EV architectures commanding engineering premiums that fleet operators amortize through total cost of ownership calculations. The vendor base organizes around three strategic archetypes: legacy OEMs with combustion heritage transitioning to skateboard platforms, hybrid specialists leveraging series-parallel expertise, and battery-electric challengers undercutting legacy pricing tiers. Dominant competitive moves include strategic partnerships for cell-to-pack supply security and portfolio diversification across crossover body styles capturing the steepest volume trajectory.
Among Japanese hybrid specialists, Toyota Motor exemplifies the bridge-technology archetype through its established Prius and Corolla platforms, while Volkswagen occupies a central position within European legacy OEMs transitioning toward dedicated EV architectures for the Golf-class segment. Hyundai Motor Company sits within the battery-electric challenger tier, differentiating through competitive offerings that compress pricing structures in fleet procurement channels.
| Leading Market Players |
|---|
| Stellantis NV |
| Toyota Motor |
| Volkswagen |
| Hyundai Motor Company |
| Kia Corporation |
| General Motors |
| Ford Motor Company |
| Honda Motor Company |
| Renault |
| Others |
Cost & Logistics Intelligence
Cell-to-pack battery engineering is compressing manufacturing costs while simultaneously concentrating cathode active material processing in Chinese facilities under MIIT industrial policy. This dual compression of cost economics and geographic supply concentration is reshaping procurement negotiations for European automakers seeking Golf-class segment competitiveness.
Pricing Analysis
Total cost of ownership calculations anchor fleet procurement decisions, with three-tier pricing structure across premium, standard, and economy levels differentiating by battery scale and software capability bundles. Price differentiation stems from certification grade under EU type approval pathways and volume scale commitments in enterprise mobility contracts. Pricing pressure stems from Hyundai Motor Company's competitive battery-electric positioning compressing legacy OEM margin structures. Fleet operators exhibit lowest price sensitivity due to amortization through utilization-based contracts, while individual retail buyers in price-sensitive markets demonstrate highest sensitivity to upfront acquisition costs.
Supply Chain Analysis
Cathode active material supply rests on Chinese processing facilities concentrated in the Yangtze River Delta, with lithium carbonate feedstock drawing from Australian and Chilean extraction operations. Raw material dependencies center on nickel-manganese-cobalt chemistries, lithium iron phosphate alternatives, and rare earth elements for electric motor assemblies. Supply chain risk manifests through export licensing volatility under MIIT forced technology transfer requirements. Distribution runs through Tier 1 supplier networks anchored in Germany and Mexico, with final assembly concentrated in Stuttgart and Wolfsburg engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's 2035 fleet CO2 phase-out deadline creates a compliance moat that elevates engineering investment thresholds for market participation, advantaging incumbents with certified type approval pathways.
For Market Incumbents: Anticipate margin compression from battery-electric challengers by accelerating skateboard chassis standardization across crossover and sedan body styles. Prioritize backward integration into cell-to-pack assembly through India's PLI scheme to secure cathode supply outside Chinese processing concentration. Defensive consolidation should target software-defined vehicle competency acquisitions addressing embedded systems integration bottlenecks. For New Entrants and Emerging Players: Vehicle-to-grid integration capabilities offer a technology-first wedge for fleet operator procurement channels where Bundesnetzagentur tariff frameworks enable new revenue stream participation. Target corporate mobility programs in Germany as the most penetrable segment given CSRD reporting obligations driving certified CO2 footprint demand. Pursue white-label platform licensing to legacy OEMs seeking rapid electrification without dedicated EV architecture development. For Investors and Strategic Acquirers: Exit pathways concentrate in battery-electric challengers with established MIIT qualification and EU type approval certifications. Long-term viability favors specialists with captive cathode supply arrangements and software monetization infrastructure. The signal to watch is KBA certification volume acceleration indicating platform readiness for fleet scale deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Skateboard chassis designs reduce homologation costs across EU and export market crash standards. |
| Battery Supply Agreement | Cell-to-pack partnerships with Yangtze River Delta manufacturers secure cathode active material access. |
| Software-Defined Vehicle Investment | Over-the-air update pipelines enable recurring revenue from navigation and autonomy subscriptions. |
| Geographic Manufacturing Footprint | India PLI scheme localization establishes right-hand-drive export capacity for ASEAN markets. |
| Charging Infrastructure Partnership | Bidirectional charging integration with Bundesnetzagentur tariffs unlocks vehicle-to-grid revenue streams. |
Research Approach
Document review covered vehicle production databases, IHS Markit registration data, SEC filings from listed automakers, and EU type approval records, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator mobility managers, and KBA certification specialists. Secondary validation drew from customs trade data, MIIT new energy vehicle qualification disclosures, and corporate sustainability reporting directive filings. Bottom-up segment modeling triangulated against top-down macroeconomic demand projections.
Historical volume trajectories cross-referenced against expert panel inputs on electrification timelines and regulatory compliance calendars. Segmentation dimensions modeled include vehicle class, propulsion architecture, OEM tier, and regional production cluster. CAGRs derived from regression analysis of technology adoption curves and fleet procurement cycle patterns. Industry-specific forecast inputs incorporated battery cost convergence trajectories and charging infrastructure deployment schedules.
Several conditions sit outside the modeled scope, including sudden raw material export restrictions, accelerated urban access ban implementations, and unanticipated breakthroughs in solid-state battery commercialization. Forecasts reflect documented assumptions on regulatory compliance calendars and technology cost curves. A small set of named triggers warrants ongoing watch: MIIT licensing volatility, Bundesnetzagentur tariff framework finalization, and KBA certification backlog duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Automotive Luxury Vehicle Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Lightweight Cars Market