
 Lightweight Cars Market | 2026-2036
Lightweight Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Lightweight Cars Market Foresight
Direct-to-consumer pre-order platforms is rewriting how low-volume lightweight manufacturers reach buyers. Gordon Murray Automotive leverages bespoke configurators to sustain ultra-premium pricing on carbon-fiber chassis orders. Caterham Cars anchors its position through kit-car channels that dominate enthusiast self-assembly segments. Polaris competes across recreational and street-legal categories with aluminum-intensive frame architectures.
Lightweight cars are passenger vehicles engineered with structural mass significantly below segment averages, typically employing aluminum monocoques, carbon-fiber reinforced polymer body panels, or magnesium powertrain castings to achieve power-to-weight ratios exceeding conventional designs. Their primary purpose is to reduce energy consumption and improve dynamic handling without sacrificing occupant safety. Aluminum dominates material segmentation due to established stamping infrastructure and recyclability, while carbon fiber captures margin pools in track-focused coupes where unit economics tolerate higher processing costs. Electric powertrains are displacing gasoline variants fastest among fleet operators prioritizing total-cost-of-ownership reductions in urban hatchback deployments.
EPA fuel-economy mandates and NHTSA crashworthiness standards jointly determine material selection thresholds for vehicles sold in the United States. EMA emissions frameworks and REACH chemical compliance shape European carbon-fiber supply chain qualification requirements. Stakeholders must monitor evolving battery-pack mass ratios, as cell chemistry improvements could alter the competitive balance between material-lightening strategies and energy-density gains.
Market Dynamics
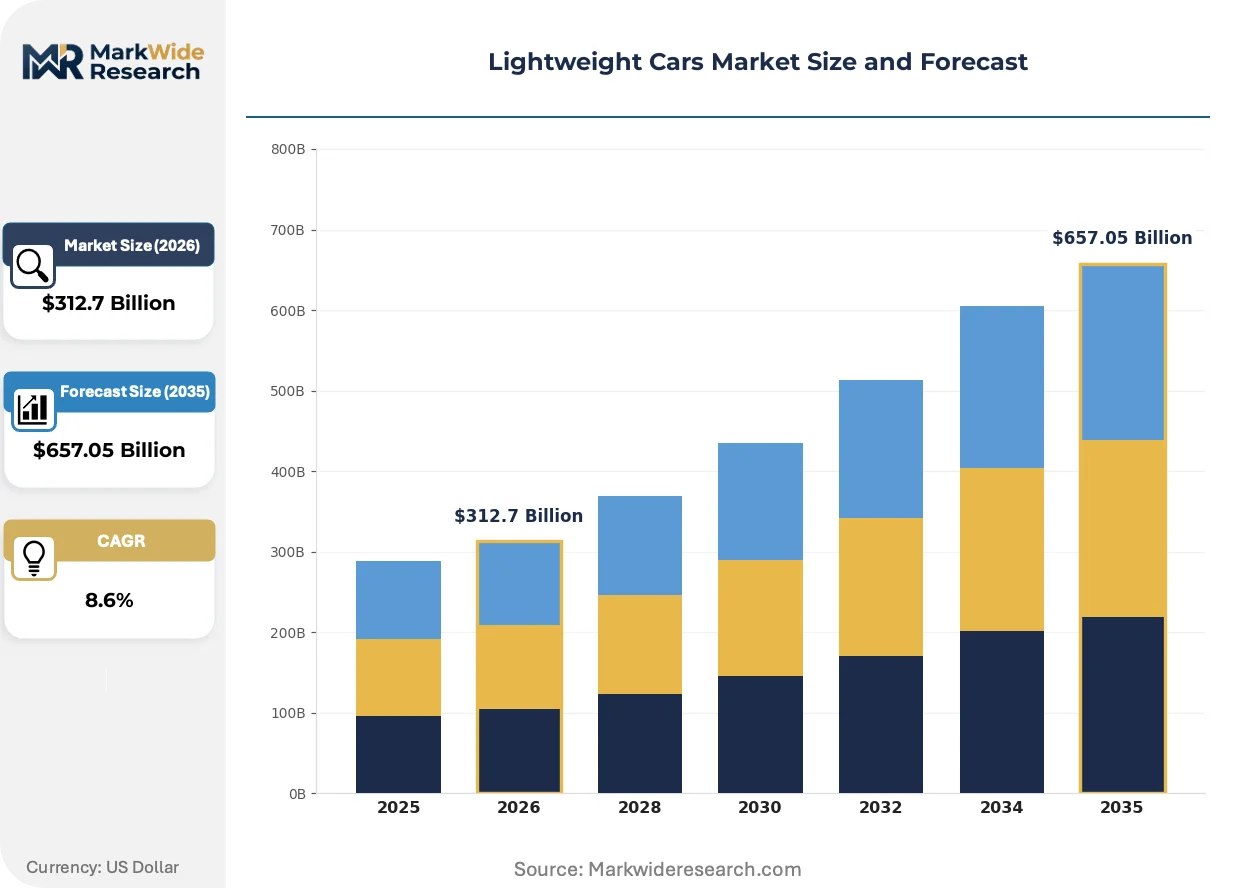
Battery-pack mass ratios are compressing the competitive window for material-lightening strategies, as cell chemistry improvements alter the calculus between chassis mass reduction and energy-density gains in electric powertrain architectures.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:NHTSA crashworthiness thresholds compel United States OEMs to pursue aluminum-intensive architectures for compliance without sacrificing occupant protection ratings.
- Fleet operator total-cost-of-ownership priorities:Urban logistics providers in Germany concentrate procurement around composite-body electric hatchbacks for last-mile delivery density.
- Carbon-fiber stamping infrastructure maturation:Automated fiber placement systems are reducing processing cost differentials against aluminum monocoques in track-focused coupe segments.
Market Restraints
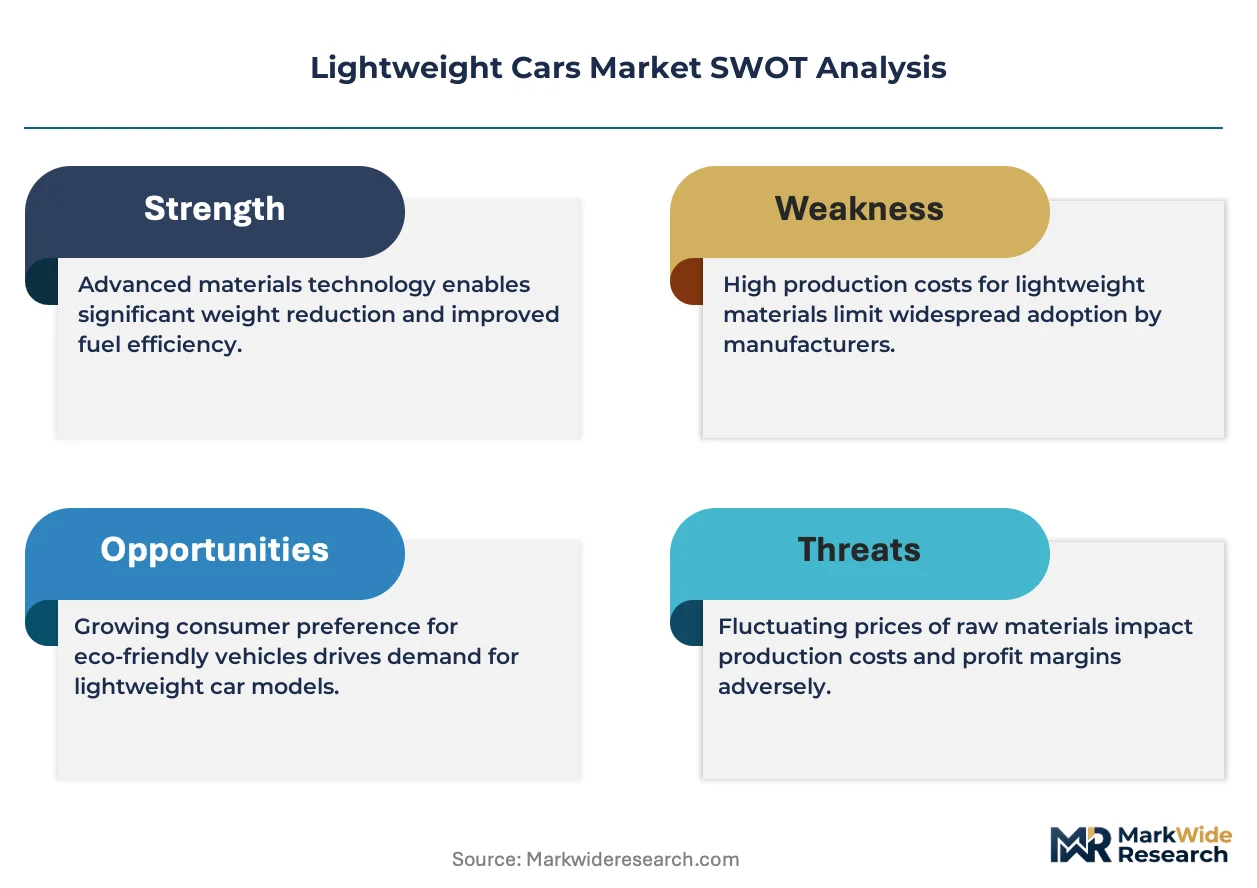
- Aluminum ingot price volatility:Primary smelter capacity concentration in specific geographies transmits commodity shocks directly to chassis stamping cost structures.
- REACH chemical compliance complexity:ECHA substance authorization requirements create qualification bottlenecks for European carbon-fiber resin supply chains.
- Magnesium corrosion limitations:Powertrain casting applications face galvanic coupling constraints that restrict component integration with aluminum subframes.
Strategic Opportunities
- Urban logistics electrification:Last-mile fleet operators in France are piloting composite-intensive delivery vehicles below 3.5 tonnes gross vehicle weight.
- Direct-to-consumer configurators:Bespoke pre-order platforms enable ultra-premium pricing capture for low-volume carbon-fiber chassis manufacturers.
- EU Green Deal manufacturing incentives:Battery-electric vehicle production subsidies in Italy are accelerating aluminum body-in-white capacity expansion.
Industry Challenges
- Multi-material joining expertise scarcity:Adhesive bonding and mechanical fastening competence gaps constrain workforce scaling for aluminum-carbon fiber hybrid architectures.
- Battery-pack structural integration certification:UN ECE R100 and FMVSS 305 testing timelines extend platform development cycles for skateboard-chassis designs.
- Recyclability standardization fragmentation:Divergent end-of-life vehicle directives across member states complicate closed-loop aluminum recovery system design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightweight Cars Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Carbon Fiber, Composite, Magnesium Vehicle Type: Hatchback, Sedan, SUV, Coupe Powertrain: Electric, Hybrid, Gasoline, Diesel Customer Type: Individual Buyers, Fleet Operators, Rental Services, Dealerships |
| Companies Covered | Automobili Mignatta, Caterham Cars, Donkervoort, Analog Automotive, Gordon Murray Automotive, Jannarelly, Bertone, Polaris, Zenos Cars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightweight Cars Market Shifts & Advancements
Digital thread integration across design-to-manufacturing workflows is compressing development cycles for multi-material vehicle architectures. Simulation-driven topology optimization now governs material placement decisions previously resolved through empirical iteration.
Generative design software is digitizing load-path optimization for aluminum-intensive chassis structures. Tier 1 stamping suppliers in Germany deploy cloud-based finite-element analysis to reduce prototype iteration counts by half. The technology is digitizing the traditional boundary between styling studios and structural engineering departments, collapsing sequential handoffs into parallel workflows.
REACH authorization requirements for epoxy resin hardeners are forcing reformulation of European carbon-fiber prepreg supply chains. ECHA substance restriction proposals targeting bisphenol derivatives are accelerating bio-based thermoset development programs. Track-focused manufacturers in the United Kingdom are qualifying Japanese-sourced cyanate ester alternatives to maintain temperature performance without SVHC classification.
Fleet procurement departments are consolidating supplier relationships around vertically integrated aluminum processors capable of closed-loop recycling. Direct long-term agreements between German logistics operators and Norwegian smelter-hydro power complexes are displacing spot-market ingot purchasing. This concentration is most visible in Scandinavia, where renewable energy certificates accompany primary metal supply contracts for carbon-footprint reporting compliance.
Lightweight Cars Market Segmentation
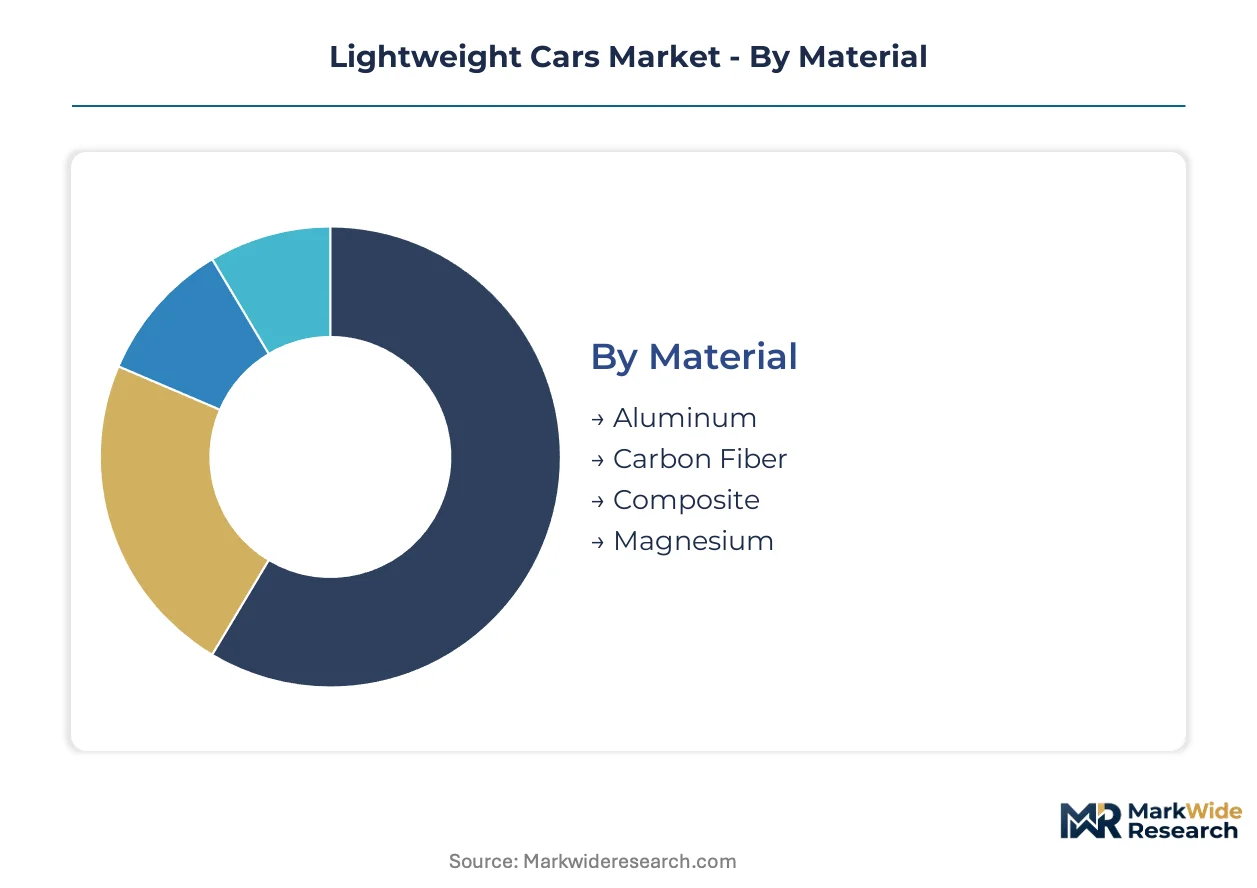
Material selection dictates manufacturing infrastructure requirements and end-market accessibility for lightweight vehicle architectures. Powertrain electrification is redrawing segment boundaries as battery mass alters the economics of chassis mass reduction. Customer procurement patterns diverge sharply between individual configuration preferences and fleet standardization mandates.
Material:
Cost tier determines processing infrastructure thresholds and end-market penetration depth across structural material categories.
- Aluminum:Monocoque stampings from 5xxx and 6xxx series alloys deliver strength-to-weight ratios sufficient for high-volume production lines. German OEMs anchor demand through body-in-white capacity expansions serving battery-electric platforms. Established recycling infrastructure and secondary smelter networks compress total material cost structures relative to alternatives.
- Carbon Fiber:Woven prepreg laminates and automated fiber placement preforms achieve specific stiffness metrics impossible with metallic alternatives. United Kingdom track-focused manufacturers sustain ultra-premium pricing through bespoke chassis configurators. REACH authorization bottlenecks for epoxy resin hardeners constrain European supply chain scaling.
- Composite:Glass-fiber reinforced polymer panels hybridized with thermoplastic matrices occupy mid-tier applications requiring corrosion resistance. French urban logistics pilots for sub-3.5-tonne delivery vehicles concentrate procurement here.
- Magnesium:Thixomolded powertrain castings and instrument panel substrates exploit density advantages for isolated components. Galvanic coupling limitations with aluminum subframes restrict structural integration scope.
Aluminum holds installed capacity. Carbon fiber is rotating up the share rankings.
Vehicle Type:
Application use case determines mass reduction priorities and material specification intensity across body styles.
- Hatchback:Compact footprints prioritize urban maneuverability and parking density over aerodynamic optimization. German fleet operators concentrate electric hatchback procurement for last-mile logistics corridors. Composite-intensive body panels displace steel in volume segments where total-cost-of-ownership dominates purchase decisions.
- SUV:Elevated ride heights and larger frontal areas compound aerodynamic drag penalties, amplifying returns from mass reduction. United States consumer preference for utility body styles drives aluminum architecture adoption among domestic OEMs pursuing EPA fuel economy compliance.
- Sedan:Three-box silhouettes retain aerodynamic efficiency advantages for highway-optimized powertrains. Declining retail share in North American markets compresses platform development investment cycles.
- Coupe:Two-door configurations tolerate higher unit costs and lower production volumes. Track-focused segments accept carbon fiber processing premiums for stiffness-to-weight optimization.
SUV volumes are expanding most quickly. Sedan share is compressing in key markets.
Powertrain:
Customer type procurement priorities diverge sharply across electrification pathways.
- Electric:Battery pack mass ratios of 25-35% of curb weight intensify chassis lightening returns. Norwegian renewable energy certificates accompany aluminum supply contracts for carbon-footprint compliance. UN ECE R100 certification timelines extend platform development cycles.
- Hybrid:Dual powertrain architectures add complexity without full battery mass penalties. Japanese OEMs optimize hybrid-specific platforms through aluminum-intensive subframes.
- Gasoline:Internal combustion powertrains retain cost advantages in price-sensitive segments. United States performance variants sustain demand for naturally aspirated engines in enthusiast niches.
- Diesel:Compression ignition efficiency advantages persist in highway-optimized commercial applications. European emissions framework stringency accelerates powertrain displacement.
Electric architectures are climbing the fastest. Diesel is losing position in fleet procurement.
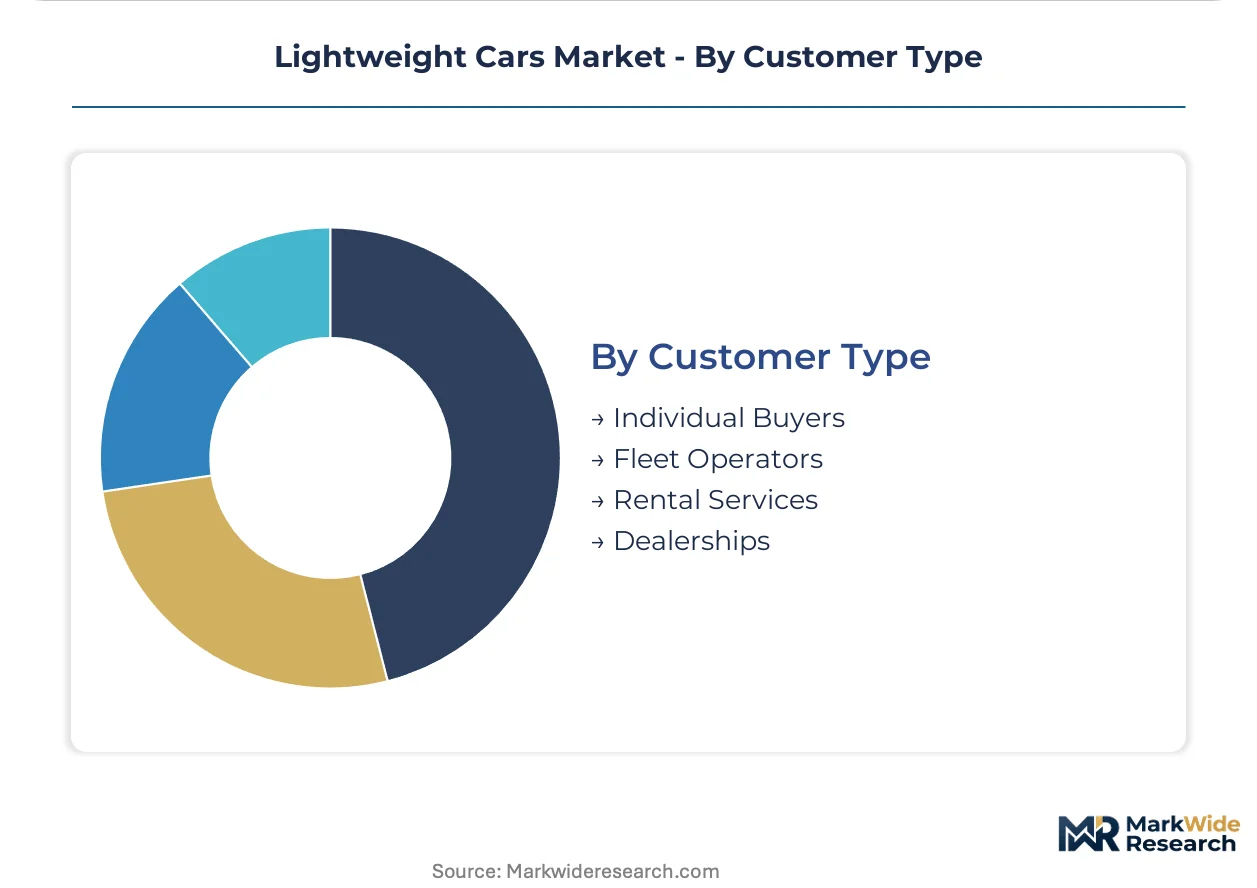
Customer Type:
Volume concentration and margin structure vary across procurement decision-maker categories.
- Fleet Operators:Total-cost-of-ownership modeling governs specification decisions with 5-7 year holding periods. German logistics providers consolidate supplier relationships around vertically integrated aluminum processors.
- Individual Buyers:Configuration flexibility and brand positioning drive willingness-to-pay premiums. Direct-to-consumer pre-order platforms enable bespoke carbon fiber chassis capture.
- Rental Services:Utilization intensity and residual value forecasting determine fleet composition. Urban car-sharing operators prioritize standardized electric hatchback deployments.
- Dealerships:Inventory financing constraints and turn velocity requirements shape stocking decisions. Franchise networks face margin compression from direct manufacturer channels.
Fleet operators concentrate procurement volume. Individual buyers sustain margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs extract premium pricing for aluminum-intensive architectures, while United States manufacturers absorb compliance cost compression under EPA mandates. This asymmetry redistributes margin capture across Atlantic supply chains.
United States
Domestic OEMs prioritize SUV body styles for aluminum architecture adoption, balancing NHTSA crashworthiness thresholds against CAFE compliance requirements. The EPA maintains stringent fleet-average mandates through 2035. Detroit-area stamping capacity serves battery-electric platform conversions for mass-market segments.
Germany
Fleet operators in urban logistics corridors concentrate procurement around composite-body electric hatchbacks with 5-7 year total-cost-of-ownership horizons. The EU Green Deal accelerates aluminum body-in-white capacity expansion through production subsidies. Baden-Württemberg hosts specialized stamping suppliers deploying cloud-based finite-element analysis for prototype compression.
United Kingdom
Track-focused manufacturers sustain ultra-premium pricing through bespoke carbon-fiber chassis configurators serving enthusiast segments. ECHA REACH authorization requirements for epoxy resin hardeners force supply chain reformulation. Motorsport Valley clusters around Oxfordshire and Northamptonshire anchor composite engineering competence.
France
Last-mile fleet operators pilot composite-intensive delivery vehicles below 3.5 tonnes gross vehicle weight for urban density optimization. ANSM chemical compliance frameworks shape resin system qualification protocols. Auvergne-Rhône-Alpes hosts thermoplastic matrix development programs for glass-fiber reinforced polymer panels.
Italy
Battery-electric vehicle production subsidies accelerate aluminum body-in-white capacity expansion serving premium export markets. EMA emissions frameworks align with national industrial policy for sustainable mobility. Emilia-Romagna maintains heritage in lightweight chassis engineering for performance-oriented marques.
Lightweight Cars Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper process expertise. Market structure concentrates around low-volume manufacturers with direct-to-consumer channels, fragmenting across kit-car, track-focused, and recreational street-legal segments. Two archetypes dominate: bespoke configurators capturing ultra-premium pricing, and vertically integrated aluminum processors serving fleet procurement consolidation. Competitive moves center on capacity expansion for carbon-fiber stamping infrastructure and strategic partnerships for closed-loop recycling systems.
Among British specialist manufacturers, Gordon Murray Automotive, Caterham Cars, and Zenos Cars exemplify contrasting channel strategies. Gordon Murray Automotive occupies the bespoke configurator archetype with ultra-premium positioning. Caterham Cars anchors the kit-car segment through enthusiast self-assembly channels. Zenos Cars represents mid-tier accessibility within composite-intensive roadster categories. These three demonstrate how geographic clustering in United Kingdom motorsport corridors supports divergent go-to-market models without direct segment overlap.
| Leading Market Players |
|---|
| Automobili Mignatta |
| Caterham Cars |
| Donkervoort |
| Analog Automotive |
| Gordon Murray Automotive |
| Jannarelly |
| Bertone |
| Polaris |
| Zenos Cars |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's specialized stamping corridors concentrate aluminum body-in-white capacity for German OEMs, translating upstream smelter proximity into downstream pricing leverage for fleet procurement consolidation. This geographic clustering compresses material cost structures while amplifying margin capture for vertically integrated processors serving long-term offtake agreements.
Pricing Analysis
The customization-premium spread separates configured-to-order carbon-fiber chassis from standard aluminum architectures by a substantial multiple. Three-tier pricing structure across premium, standard, and economy levels reflects material processing intensity, with bespoke configurators commanding ultra-premium positioning and volume hatchback segments absorbing cost compression. Pricing pressure stems from battery-pack mass ratios diminishing returns on chassis lightening investments. Fleet operators exhibit highest price sensitivity through total-cost-of-ownership modeling, while individual buyers sustain lowest sensitivity via brand positioning and configuration flexibility.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for carbon-fiber prepreg sourcing. Primary aluminum supply concentrates in Norway, Canada, and Australia, with secondary smelter networks in Germany and the United States. Raw material dependencies span aluminum ingot, epoxy resin systems, and carbon-fiber tow. Distribution runs through long-term direct agreements between fleet operators and smelter-hydro power complexes, displacing spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lightweight cars market functions as a defensive-moat story anchored in regulatory entrenchment, where EPA CAFE mandates and EMA emissions frameworks create compliance-driven demand inelasticity for approved material architectures.
For Market Incumbents: Entrench position through backward integration into closed-loop aluminum recycling systems and captive supply of carbon-fiber stamping capacity. Battery chemistry improvements threaten to displace chassis lightening returns; counter by locking fleet operators into 5-7 year total-cost-of-ownership contracts with embedded material cost predictability. For New Entrants and Emerging Players: Establish a beachhead in urban logistics electric hatchbacks for French and German last-mile fleet operators, where procurement consolidation around composite-intensive sub-3.5-tonne vehicles remains penetrable. Bypass dealership networks entirely through direct-to-consumer pre-order platforms with configurators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded carbon-fiber composite competencies outside automotive core. Long-term viability hinges on material-lightening economics persisting against energy-density gains; monitor battery-pack mass ratio inflections as the critical signal.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Capacity Expansion | Reduces carbon-fiber processing cost differentials against aluminum monocoques for track-focused manufacturers. |
| Closed-Loop Aluminum Recycling Integration | Captures margin pools from secondary smelter networks serving German OEM body-in-white expansion. |
| Direct-to-Consumer Configurator Platform | Enables bespoke pricing capture for low-volume British manufacturers in Motorsport Valley clusters. |
| Battery Supply Agreement Structuring | Secures cell chemistry roadmap visibility to calibrate chassis mass reduction investment timing. |
| REACH-Compliant Resin System Qualification | Unblocks European carbon-fiber supply chain scaling constrained by ECHA authorization bottlenecks. |
Research Methodology
The analysis maps aluminum-intensive architectures, carbon-fiber chassis systems, composite body panels, and magnesium powertrain castings, each validated through Tier 1 supplier procurement leads, OEM platform engineers, fleet operator specification managers, and aftermarket distribution heads. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, vehicle production databases, IHS Markit registration data, and customs/trade flow records. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers.
Assumption sets held battery chemistry improvement trajectories and regulatory mandate stringency paths fixed while varying aluminum ingot price volatility and carbon-fiber processing cost curves across the projection horizon. Segmentation dimensions modeled include material category, vehicle type, powertrain architecture, and customer procurement pattern. CAGRs derived from elasticity-adjusted demand curves incorporating fleet electrification timelines and individual buyer configuration preferences. Industry-specific inputs encompassed EPA CAFE compliance thresholds and EMA emissions framework phase-in schedules.
Stress conditions across aluminum commodity price bands, REACH authorization timelines, and battery energy density improvement rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory persistence and material substitution economics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Train Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Medium Cars Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
India Passenger Car Market