
 Minivans Market | 2026-2036
Minivans Market Size, Share, and Industry Trends Forecast 2026-2036
Minivans Market Intelligence
FMVSS 216a roof-crush resistance certification is rotating the competitive set toward manufacturers with structural engineering depth. Toyota Motor Corporation leverages its TNGA platform architecture to sustain high rigidity ratings across multi-row configurations. Stellantis N.V. anchors its North American position through captive supply of frame components and powertrain integration. Kia Corporation differentiates via competitive interior packaging that competes on cubic footage per dollar against larger rivals.
Minivans are purpose-built light commercial vehicles or family transport wagons featuring unibody construction, sliding side doors, and three-row seating configurations with flat-load floors; their primary purpose centers on maximizing interior volume within exterior footprint constraints for passenger comfort or cargo utility. Hybrid minivans command structural attention as electrification penetrates the segment where fuel economy regulations intensify cost pressure on pure internal combustion variants. Fleet operators represent a maturing but stable demand pool, while electric minivans occupy an emerging niche where charging infrastructure and total cost of ownership calculations determine adoption velocity.
NHTSA enforces FMVSS 208 advanced airbag and seatbelt standards that elevate passive safety system costs across all configurations, while EPA corporate average fuel economy targets push powertrain diversification into hybrid and battery-electric architectures. The California Air Resources Board operates under authority granted by the Clean Air Act waiver, applying zero-emission vehicle mandates that filter into minivan product planning cycles. Stakeholders must monitor how state-level ZEV mandates interact with federal fuel economy rules to determine powertrain portfolio allocation and factory retooling commitments.
Market Dynamics
FMVSS 216a roof-crush resistance certification is compressing engineering timelines and forcing structural redesigns across unibody platforms. Fleet operators now specify crashworthiness ratings in procurement tenders, elevating passive safety from compliance checkbox to competitive differentiator.
Growth Catalysts
- Airport shuttle electrification:Municipal transit authorities in the United States are mandating zero-emission fleet turnover by 2030, accelerating hybrid minivan orders for ground transport services.
- NHTSA side-impact thresholds:Tighter FMVSS 214 pole-impact standards are compelling manufacturers to reinforce B-pillar structures, creating upgrade demand among safety-conscious family buyers.
- Suburban family replacement cycles:Three-row seating configurations with flat-load floors are sustaining replacement demand in the United States where multi-child households prioritize interior volume per dollar.
Market Restraints
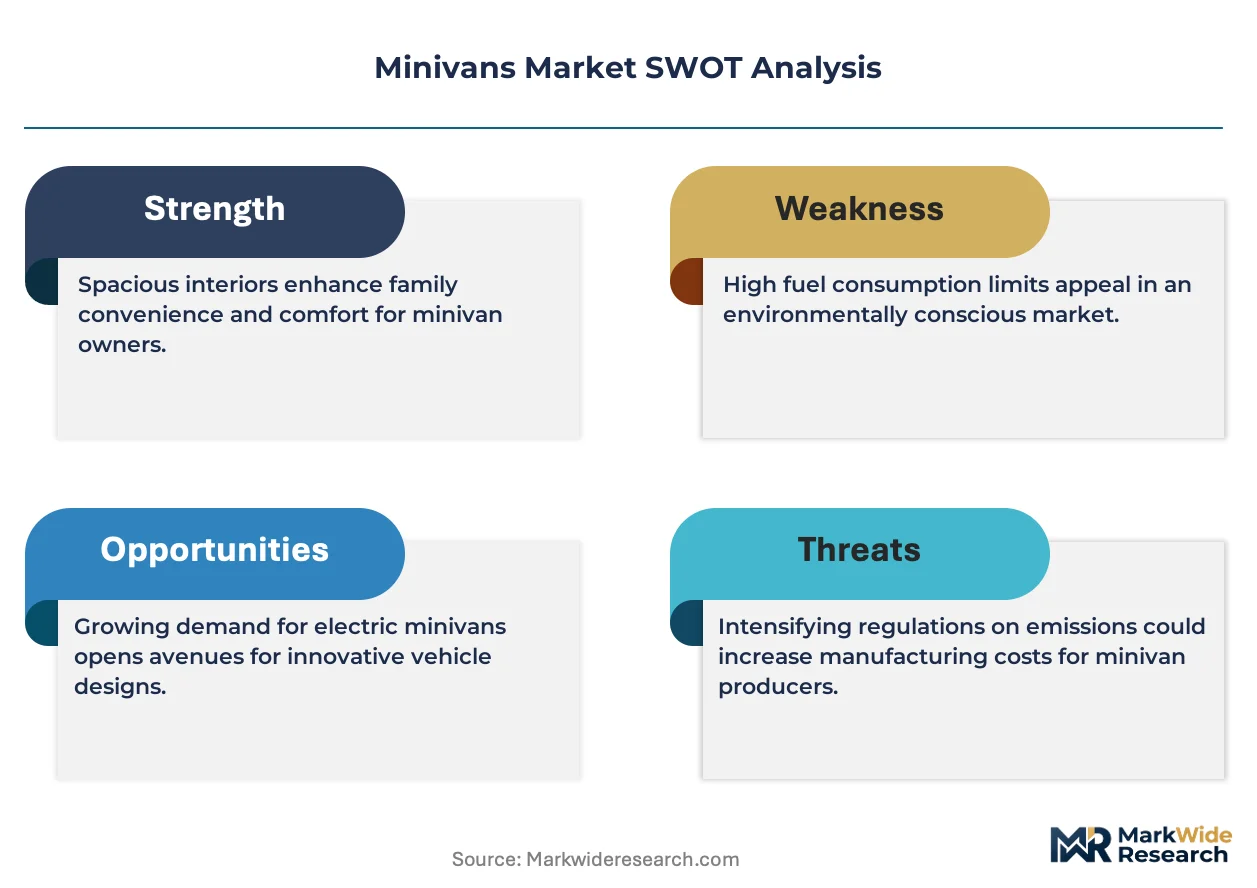
- Steel input volatility:High-strength steel prices fluctuate with energy costs, compressing margin on unibody platforms where structural rigidity cannot be compromised.
- Powertrain diversification capex:Factory retooling for hybrid and battery-electric architectures requires capital commitments that strain mid-volume manufacturers.
- SUV substitution pressure:Crossover utility vehicles with sliding door aftermarket conversions are capturing price-sensitive buyers seeking minivan utility without the segment stigma.
Strategic Opportunities
- California ZEV mandate spillover:The California Air Resources Board zero-emission vehicle requirements are filtering into minivan product planning, creating first-mover advantage for battery-electric platform launches.
- Last-mile parcel delivery:E-commerce fulfillment networks are repurposing cargo-configured minivans for urban route density where full-size vans exceed dimensional constraints.
- Vehicle-to-load bidirectional charging:Integration of V2L capability with residential solar installations is creating new value propositions for electrified minivans as home backup power sources.
Industry Challenges
- Multi-material bonding certification:Adhesive joining of aluminum closures to steel unibodies requires new weld-bond validation protocols that extend homologation timelines.
- Software-defined vehicle integration:Over-the-air update architectures for hybrid powertrain management are forcing collaboration between legacy tier-1 suppliers and silicon valley firmware developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minivans Market |
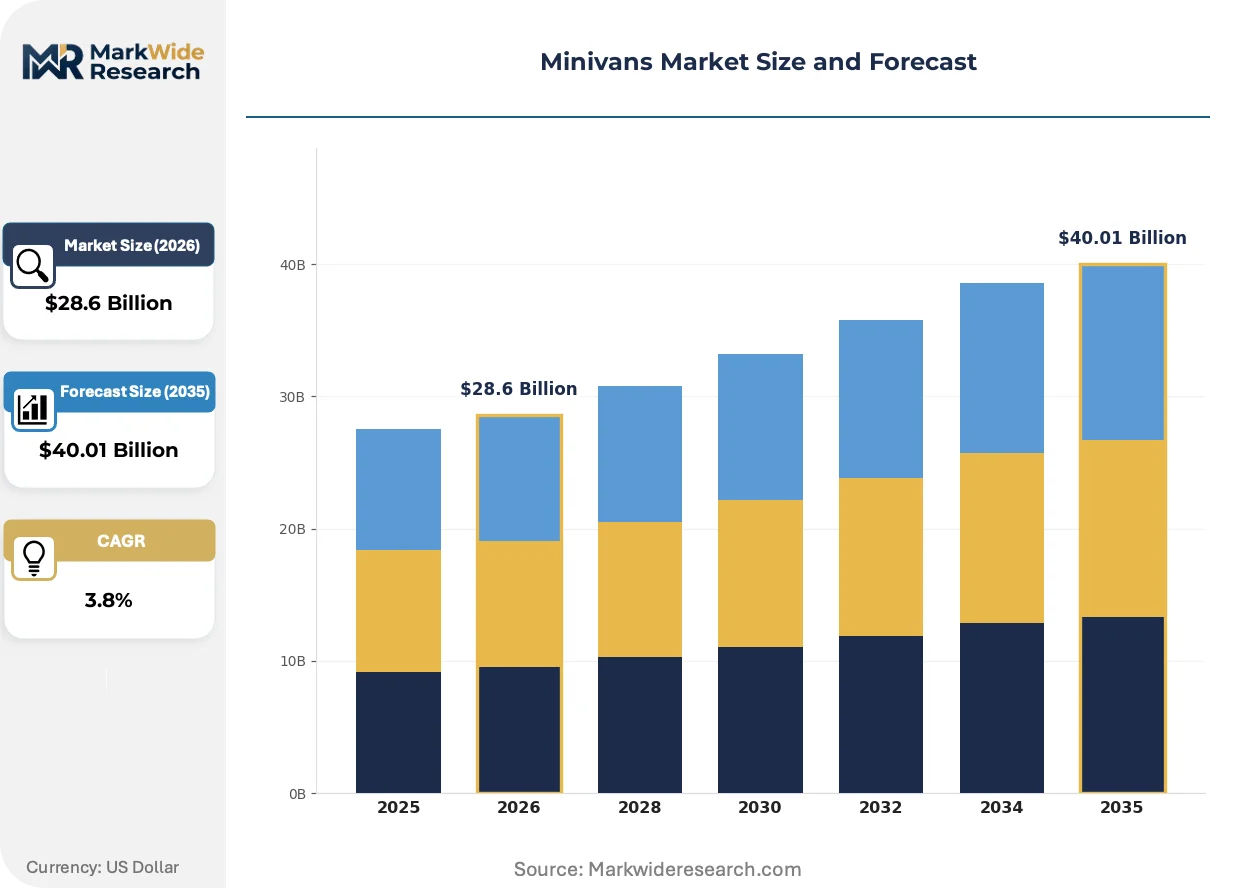
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Minivans, Cargo Minivans, Hybrid Minivans, Electric Minivans Customer Type: Families, Fleet Operators, Commercial Users, Ride-Sharing Services Feature: All-Wheel Drive, Advanced Safety Features, Entertainment Systems, Interior Space Sales Channel: Direct Sales, Online Sales, Dealerships, Auctions |
| Companies Covered | Toyota Motor Corporation, Honda Motor Company, Stellantis N.V., Nissan Motor Co. Ltd., Kia Corporation, Volkswagen, Chrysler, Hyundai Motor Company, General Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minivans Market Strategic Shifts & Innovations
Electrification is restructuring powertrain sourcing relationships while passive safety regulations compress development cycles. Platform modularity and interior reconfigurability are emerging as the primary vectors of differentiation.
High-voltage battery packaging is miniaturizing. Cell-to-pack architectures eliminate module housings, freeing underfloor space for third-row legroom. United States fleet operators are specifying these configurations for airport shuttle routes where passenger capacity per vehicle determines route economics. The technology is miniaturizing thermal management hardware, reducing packaging volume and enabling lower rooflines without sacrificing headroom.
The EPA corporate average fuel economy framework is tightening light truck fleet targets. Manufacturers must deploy hybrid powertrains across minivan nameplates to avoid penalty exposure. The United States market bears the brunt of this pressure, as suburban family transport constitutes the volume anchor for the segment.
Subscription-based vehicle access is displacing traditional ownership models. Urban households in coastal United States metropolitan areas are prioritizing flexible tenure over equity accumulation. Fleet management companies are capturing this demand through monthly minivan subscriptions that bundle maintenance, insurance, and charging infrastructure access.
Minivans Market Segmentation
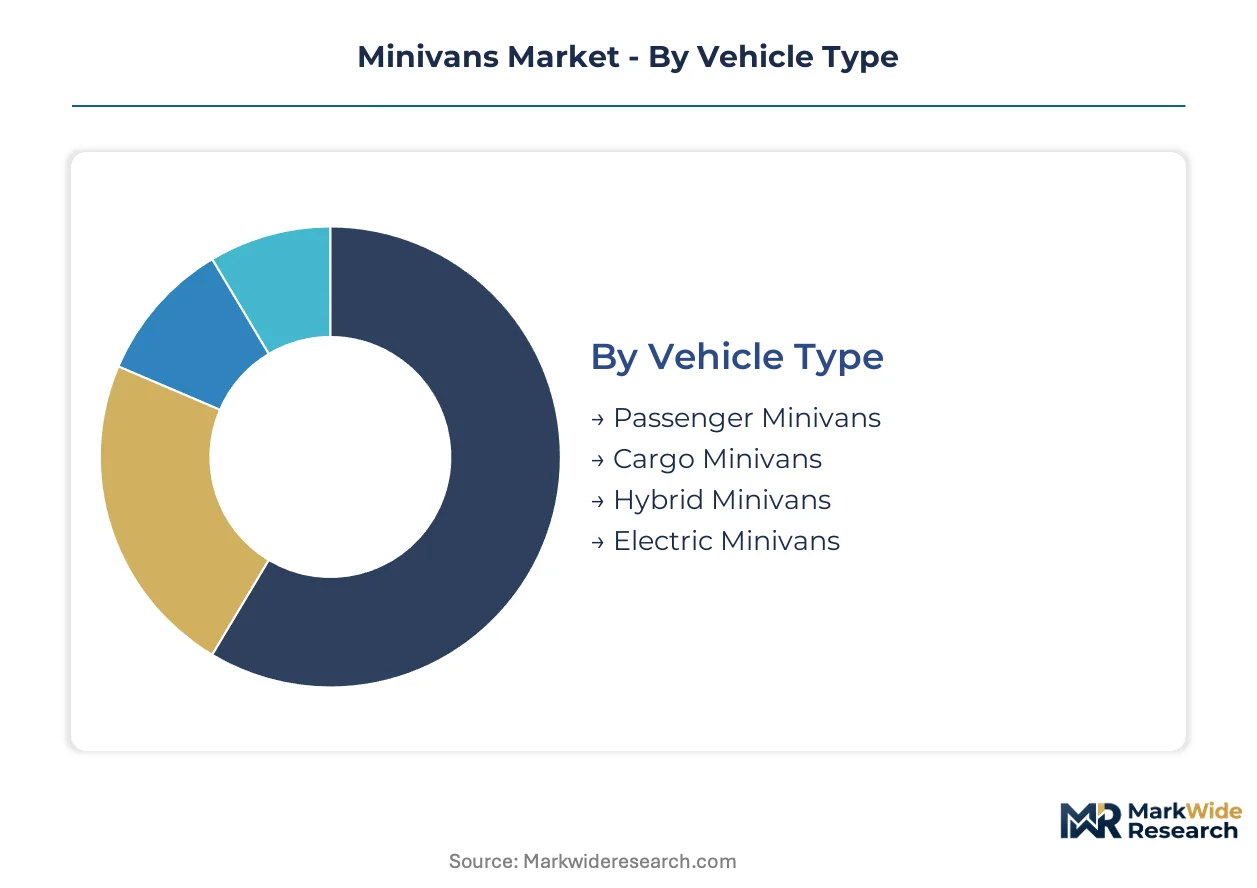
Segmentation in the minivans market reveals how powertrain diversification and fleet electrification mandates are redistributing volume across vehicle configurations. Customer procurement patterns now split sharply between family replacement cycles and commercial fleet specifications, each demanding distinct feature packaging and distribution pathways.
Vehicle Type:
Margin pools concentrate in electrified architectures where NHTSA compliance costs and battery packaging complexity create pricing power for engineering-capable manufacturers.
- Passenger Minivans:Three-row configurations with sliding side doors and flat-load floors dominate suburban United States household replacement demand. Airport shuttle operators in California and Texas specify these for passenger density on fixed routes.
- Hybrid Minivans:Cell-to-pack battery architectures underfloor free interior volume while satisfying EPA corporate average fuel economy thresholds. Fleet operators facing municipal zero-emission mandates prioritize these for transitional compliance.
- Cargo Minivans:E-commerce last-mile networks repurpose these for urban route density where full-size vans exceed dimensional constraints.
- Electric Minivans:Vehicle-to-load bidirectional charging integration targets residential solar households in coastal United States metropolitan areas.
Passenger Minivans hold installed capacity. Electric Minivans are rotating up the share rankings.
Customer Type:
Volume splits between cyclical family demand and secular fleet expansion, with procurement specifications diverging on safety certification and total cost of ownership metrics.
- Fleet Operators:Municipal transit authorities mandate FMVSS 216a roof-crush ratings and FMVSS 214 side-impact compliance in procurement tenders. California airport shuttle contracts specify hybrid powertrains for zero-emission fleet turnover deadlines.
- Families:Multi-child households in United States suburbs prioritize cubic footage per dollar and third-row legroom over powertrain sophistication.
- Commercial Users:Small business contractors value interior reconfigurability for mixed passenger-cargo duty cycles.
- Ride-Sharing Services:Subscription-based vehicle access providers bundle maintenance and charging infrastructure for urban households prioritizing flexible tenure.
Fleet Operators anchor current volume. Ride-Sharing Services are climbing the fastest as ownership models shift.
Feature:
Cost tier differentiation separates premium configurations with advanced driver assistance from economy offerings where interior packaging alone drives purchase decisions.
- Advanced Safety Features:FMVSS 208 advanced airbag architectures and automatic emergency braking satisfy family buyer risk aversion and fleet operator insurance cost reduction.
- Interior Space:Unibody platform optimization maximizes cubic footage within exterior footprint constraints for passenger comfort and cargo utility.
- All-Wheel Drive:Snow-belt United States states and mountainous regions specify this for traction confidence.
- Entertainment Systems:Rear-seat screens and streaming connectivity address family buyer priorities for occupant distraction on long-haul routes.
Interior Space commands baseline specification. Advanced Safety Features are gaining share fastest as NHTSA thresholds tighten.
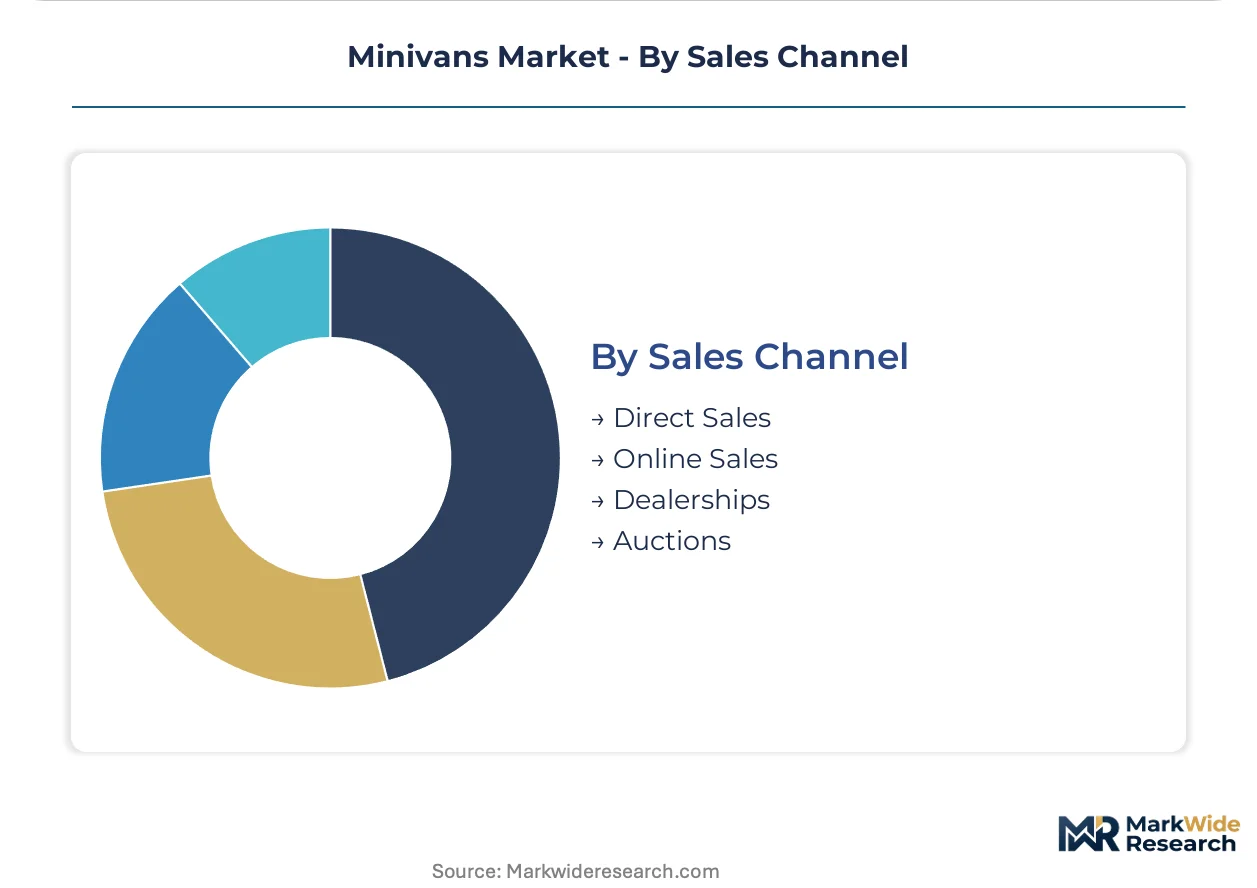
Sales Channel:
Supply concentration in dealership networks is fragmenting as direct manufacturer relationships and digital transaction platforms capture fleet and subscription volume.
- Dealerships:Franchise networks handle family buyer test drives, trade-in valuations, and financing arrangements for replacement cycle purchases.
- Direct Sales:Manufacturers bypass intermediaries for fleet contracts with standardized specifications and volume pricing.
- Online Sales:Digital configurators and home delivery attract coastal United States metropolitan households comfortable with remote transaction completion.
- Auctions:Secondary market disposal channels absorb off-lease fleet units and rental fleet rotation volume.
Dealerships retain installed capacity. Direct Sales are expanding most quickly as fleet procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal and state-level electrification mandates are redistributing minivan demand across North America, Asia-Pacific, and Europe. Fleet procurement specifications now vary sharply by jurisdiction, with zero-emission deadlines accelerating hybrid and battery-electric orders in regulatory-forward markets.
United States
Suburban family replacement cycles and airport shuttle electrification sustain volume in California, Texas, and Florida. The EPA corporate average fuel economy framework tightens light truck fleet targets, compelling hybrid powertrain deployment. Detroit-Windsor manufacturing corridors anchor unibody platform production for domestic consumption.
China
Urban last-mile delivery networks and multi-child household transport drive electrified minivan adoption in Shanghai, Guangzhou, and Shenzhen. MIIT new energy vehicle mandates accelerate battery-electric platform development. Yangtze River Delta industrial clusters concentrate cell-to-pack battery packaging for domestic OEM supply.
Japan
Kei-car regulatory thresholds and aging population mobility needs sustain compact multi-purpose vehicle demand in Tokyo, Osaka, and Nagoya. METI carbon neutrality roadmaps push hybrid powertrain refinement over full electrification. Kanto manufacturing belts integrate TNGA platform architectures for export markets.
Germany
Commercial fleet operators and large-family households generate replacement demand in Bavaria, North Rhine-Westphalia, and Baden-Württemberg. EU Green Deal vehicle emission performance standards filter into light commercial vehicle categories. Stuttgart and Wolfsburg engineering centers develop modular electric platforms for multi-row configurations.
South Korea
Domestic family transport and export-oriented manufacturing sustain production in Seoul Capital Area and Busan-Ulsan corridors. MFDS vehicle safety certification and corporate average fuel economy regulations align with EU and US thresholds. Gwangju-Honam assembly plants specialize in hybrid powertrain integration for North American export.
Minivans Market Key Industry Players
Listed leaders compete with private specialists across platform architecture and powertrain integration capabilities. The competitive set concentrates around five to seven manufacturers with structural engineering depth sufficient for FMVSS 216a certification. Three archetypes dominate: full-line OEMs with captive unibody platforms, specialist assemblers with regional distribution focus, and electrification-first entrants with battery packaging expertise. Strategic moves center on hybrid powertrain portfolio diversification and factory retooling for cell-to-pack architectures.
Among full-line OEMs with listed equity, Toyota Motor Corporation and Stellantis N.V. occupy positions defined by platform modularity and captive supply chain control. Kia Corporation exemplifies the specialist tier competing on interior packaging efficiency. These three anchors represent divergent responses to electrification pressure: one leverages hybrid system integration depth, another commands North American distribution infrastructure, and the third competes on cubic footage per dollar against larger rivals.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Honda Motor Company |
| Stellantis N.V. |
| Nissan Motor Co. Ltd. |
| Kia Corporation |
| Volkswagen |
| Chrysler |
| Hyundai Motor Company |
| General Motors |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with high-strength steel mills lock in both supply access and price visibility for unibody platform manufacturers facing FMVSS 216a roof-crush certification deadlines. These arrangements insulate Toyota Motor Corporation and Stellantis N.V. from spot market volatility while compressing margin for mid-volume competitors without equivalent procurement scale.
Pricing Analysis
Certification level creates the primary spread across minivan configurations, with FMVSS 216a-compliant architectures commanding premium positioning over non-certified fleet alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects powertrain sophistication, interior reconfigurability, and advanced driver assistance bundling. Pricing pressure stems from SUV substitution and steel input volatility, with fleet operators exhibiting highest price sensitivity due to total cost of ownership procurement criteria while family buyers prioritize cubic footage per dollar over absolute cost.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for battery cell imports from South Korea and Japan into United States assembly plants. Manufacturing gravity centers on Michigan, Ontario, and Kentucky for unibody platform stamping, with high-strength steel and lithium-ion cells as critical inputs. Single-source vulnerability concentrates in cell-to-pack thermal management hardware, while distribution runs through franchised dealership networks for family buyers and direct manufacturer relationships for fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The minivans market functions as a defensive-moat industry where regulatory entrenchment through FMVSS certification creates durable barriers against unqualified entrants. Switching costs for fleet operators amplify incumbent advantages once safety ratings and service networks achieve procurement lock-in.
For Market Incumbents: Fortify structural engineering capabilities through captive supply of frame components and powertrain integration depth. Expand hybrid production capacity in Detroit-Windsor corridors to satisfy California ZEV mandate spillover. Deepen relationships with municipal transit authorities specifying FMVSS 214 and FMVSS 216a compliance in tenders.
For New Entrants and Emerging Players: Lead with battery-electric platform specialization targeting airport shuttle electrification mandates in California and Texas. Penetrate last-mile parcel delivery segments where cargo-configured minivans face dimensional constraints against full-size vans. Deploy subscription-based vehicle access models in coastal metropolitan areas displacing traditional ownership.
For Investors and Strategic Acquirers: Capital is best deployed toward electrification-first entrants with cell-to-pack battery packaging expertise and software-defined vehicle architectures. Long-term viability hinges on factory retooling completion for hybrid and battery-electric platforms. Monitor California Air Resources Board zero-emission vehicle mandate acceleration as inflection signal for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | TNGA architecture enables FMVSS 216a certification across multi-row configurations with engineering efficiency. |
| Battery Supply Agreement | Cell-to-pack sourcing from Yangtze River Delta secures thermal management hardware for electric minivan launches. |
| Software-Defined Vehicle Investment | Over-the-air powertrain management requires collaboration between legacy tier-1 suppliers and firmware developers. |
| Geographic Manufacturing Footprint | Gwangju-Honam assembly specialization supports North American hybrid export demand with integrated powertrain capacity. |
| Charging Infrastructure Partnership | Vehicle-to-load bidirectional capability integration targets residential solar households in California metropolitan markets. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with OEM platform engineers, fleet procurement directors, municipal transit authority planners, and tier-1 supplier program managers; and secondary validation through NHTSA FMVSS filings, EPA fuel economy certification databases, vehicle production registries, and California Air Resources Board ZEV credit transaction records. Bottom-up volume triangulation across powertrain configurations reconciled with top-down market sizing derived from registration data and fleet operator procurement disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions including vehicle type, customer archetype, feature tier, and sales channel with propulsion architecture and regional regulatory cluster as industry-specific overlays. CAGRs were computed from annualized growth trajectories anchored in replacement cycle timing and electrification mandate deadlines. Forecast inputs incorporated steel price index movements and charging infrastructure deployment curves without year-specific calibration.
The analysis sits within stated boundaries; outcomes outside sustained NHTSA regulatory tightening or accelerated ZEV mandate adoption would require recalibration. Forecasts reflect documented assumptions regarding hybrid powertrain cost parity achievement and fleet operator procurement centralization trends. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Global Passenger Cars Market
Passenger Vehicles
Automotive Luxury Vehicle Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Quadricycle and Tricycle Market