
 India Passenger Car Market | 2026-2036
India Passenger Car Market Size, Share, and Industry Trends Forecast 2026-2036
India Passenger Car Market Outlook
Aftermarket service revenue is narrowing as original equipment manufacturers extend warranty periods and bundle maintenance into vehicle financing. Maruti Suzuki leverages its dense dealership network to capture recurring service income across tier-2 and tier-3 cities. Tata Motors anchors its competitive stance through vertical integration into battery cell assembly and electric powertrain production. Hyundai Motor Company differentiates via platform sharing between ICE and electric architectures to reduce development costs.
A passenger car is a motor vehicle designed primarily for personal transportation, typically seating four to five occupants and constructed on a unibody or monocoque chassis with independent suspension systems and crumple zones for occupant protection. The category spans internal combustion, hybrid, and battery-electric propulsion systems, serving individual mobility, family transport, and corporate fleet requirements. SUV and crossover body styles now dominate showroom volumes as ride-height preference and cabin flexibility reshape buyer priorities across customer segments. Electric fuel type represents the fastest-expanding category, though petrol variants sustain the largest installed base due to charging infrastructure gaps and upfront battery cost premiums.
Bharat Stage VI emission norms enforced by the Central Pollution Control Board mandate real-driving emission testing and onboard diagnostic systems, raising engineering costs for petrol and diesel powertrains. The Automotive Research Association of India certifies crash-test compliance under Bharat New Vehicle Safety Assessment Program protocols, while BIS standards govern component quality and interoperability across the supplier base. Stakeholders must monitor how state-level electric vehicle policies in Delhi, Maharashtra, and Karnataka alter registration fee structures and road-tax incentives to determine manufacturing location and model-mix allocation.
Market Dynamics
India's PLI scheme for automotive manufacturing is compressing powertrain development timelines as domestic battery cell assembly scales and Bharat Stage VI norms force real-driving emission compliance across petrol and diesel platforms.
Growth Catalysts
- Fleet electrification mandates:State-level electric vehicle policies in Delhi, Maharashtra, and Karnataka are altering registration fee structures and road-tax incentives, pulling demand from logistics and ride-hailing operators toward battery-electric procurement.
- Component supplier clustering:OEM assembly plants and their captive supplier bases concentrate in Maharashtra, Gujarat, and Tamil Nadu, creating density economies that shorten procurement lead times for domestic manufacturers.
- Bharat New Vehicle Safety Assessment Program:Crash-test certification protocols administered by the Automotive Research Association of India are accelerating structural engineering investment across unibody chassis designs and crumple zone optimization.
Market Restraints
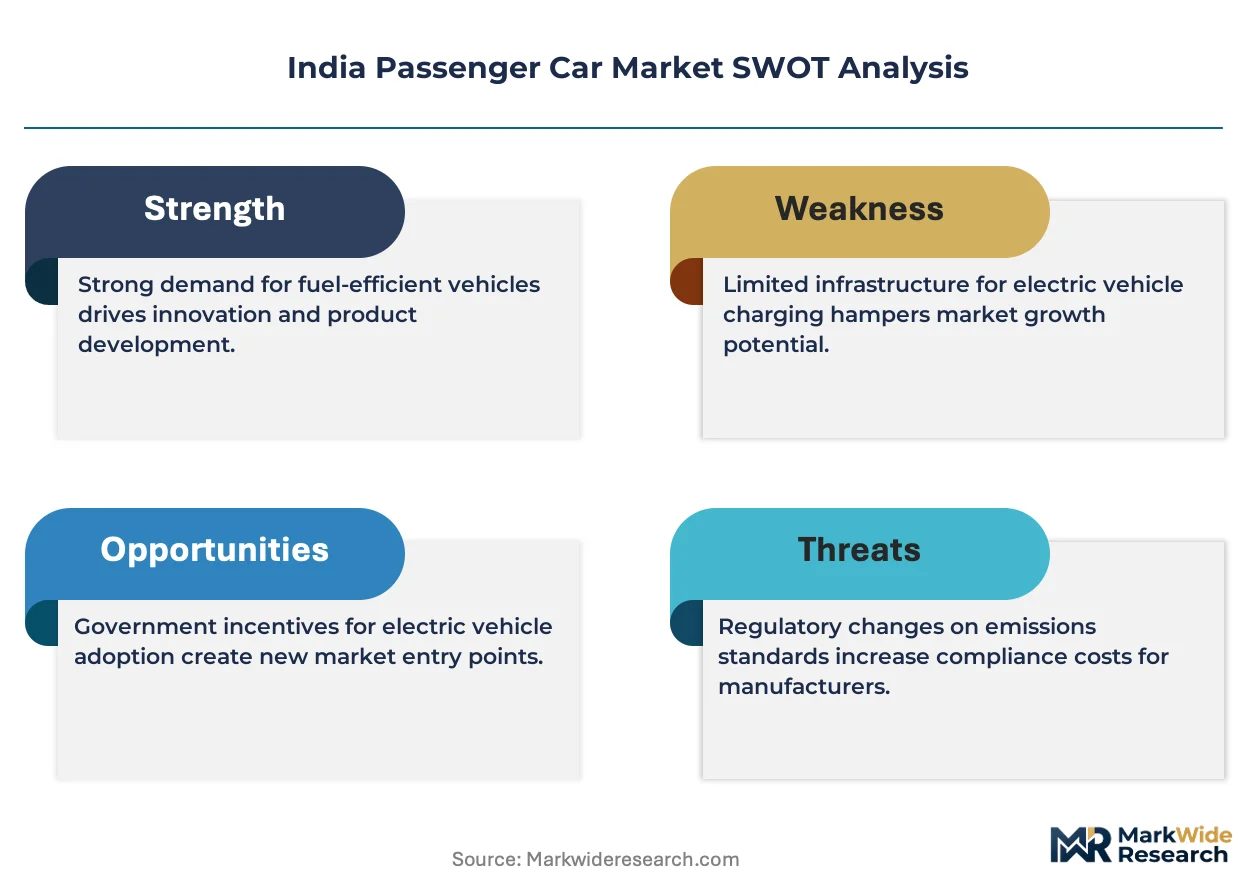
- Lithium-ion cell import dependency:Domestic battery chemistry production remains underdeveloped, forcing OEMs to absorb currency volatility and supply concentration risk from East Asian cathode and electrolyte suppliers.
- Charging infrastructure gaps:Grid reliability and fast-charger deployment density in tier-2 and tier-3 cities sustain petrol variant preference despite total cost of ownership advantages for electric powertrains.
- Bharat Stage VI engineering cost inflation:Real-driving emission testing and onboard diagnostic mandates have raised compliance expenditure for internal combustion platforms without corresponding pricing power recovery.
Strategic Opportunities
- Aftermarket service unbundling:Extended warranty bundling into vehicle financing creates white space for independent service networks to capture maintenance revenue outside OEM-controlled dealership channels.
- Platform sharing architectures:Common skateboard designs spanning internal combustion and electric variants enable model-mix flexibility that responds faster to state-level incentive fluctuations.
- Tier-3 city distribution:Underpenetrated showroom and service presence in smaller urban centers offers first-mover positioning as disposable income growth rotates demand away from metropolitan concentration.
Industry Challenges
- Powertrain engineering talent scarcity:Domestic skill pipelines for electric motor design, battery thermal management, and power electronics integration lag behind PLI scheme production scale-up timelines.
- Dual certification complexity:Simultaneous compliance with BIS component quality standards and Bharat New Vehicle Safety Assessment Program protocols extends homologation cycles and delays model launches.
- Legacy dealer network reconfiguration:Existing franchise structures optimized for internal combustion service revenue require capital-intensive retrofitting for electric vehicle maintenance and battery health diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Passenger Car Market |
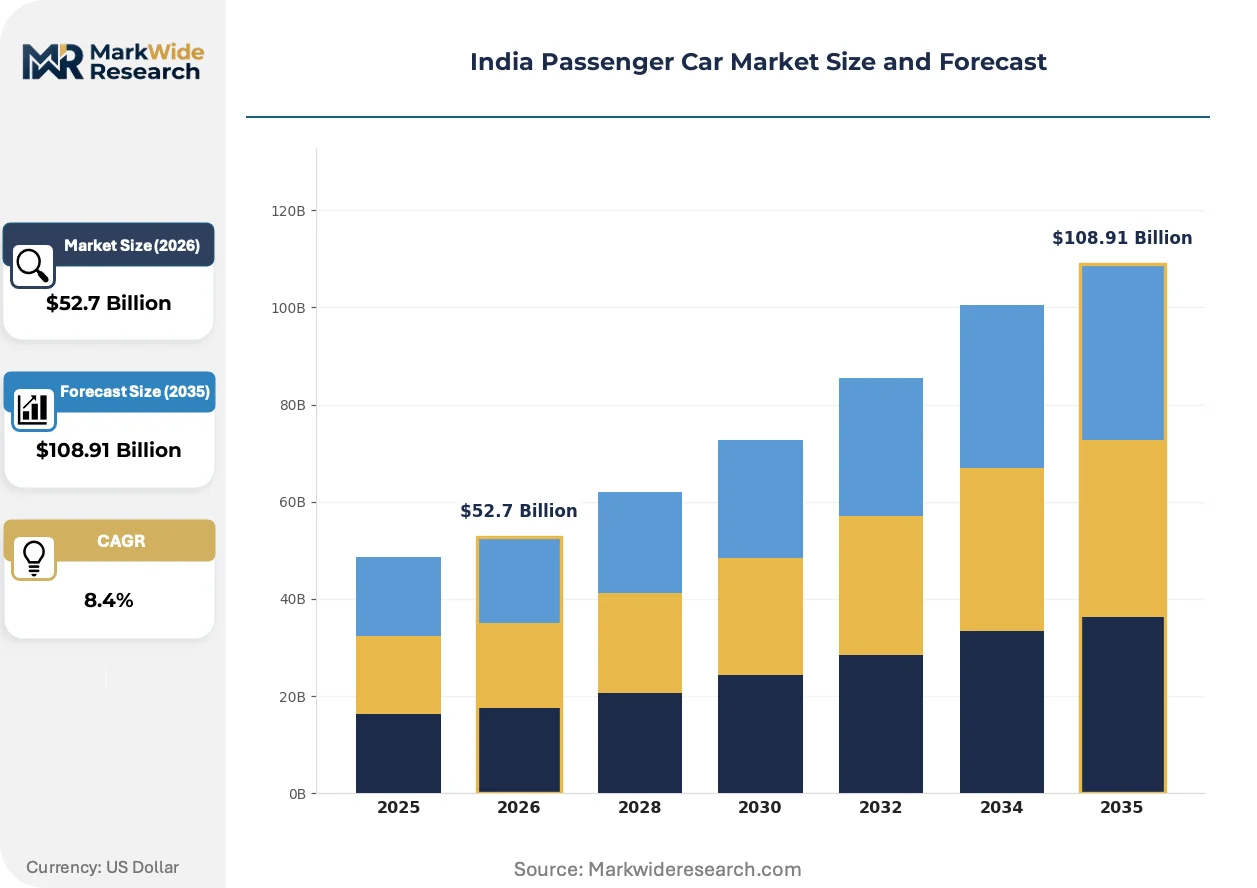
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Crossover Fuel Type: Petrol, Diesel, CNG, Electric Transmission Type: Manual, Automatic, Semi-Automatic, CVT Customer Segment: First-Time Buyers, Families, Corporate Fleet, Luxury Seekers |
| Companies Covered | Tata Motors, Kia Corporation, Maruti Suzuki, Skoda Auto, MG Motor, Mahindra & Mahindra, Toyota Motor Corporation, Honda Motors, Hyundai Motor Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Passenger Car Market Strategic Shifts
Software-defined vehicle architectures are displacing mechanical differentiation as the primary competitive lever, compressing hardware development cycles and enabling feature subscription revenue streams across powertrain variants.
Digital twin simulation is virtualizing physical crash-testing and thermal validation protocols, allowing Tata Motors and Hyundai Motor India to compress Bharat New Vehicle Safety Assessment Program homologation timelines while reducing prototype build costs for crossover and SUV body styles.
BIS standards governing component interoperability are forcing supplier consolidation around certified connector and semiconductor specifications, compelling tier-1 vendors to redesign control modules that previously operated on proprietary protocols across Maharashtra and Tamil Nadu assembly plants.
Direct-to-consumer configurators are displacing traditional dealership inventory models, with buyers in Gujarat and Karnataka specifying feature packages online before allocation to regional distribution centers, compressing order-to-delivery cycles and reducing working capital intensity for showroom operators.
India Passenger Car Market Segmentation
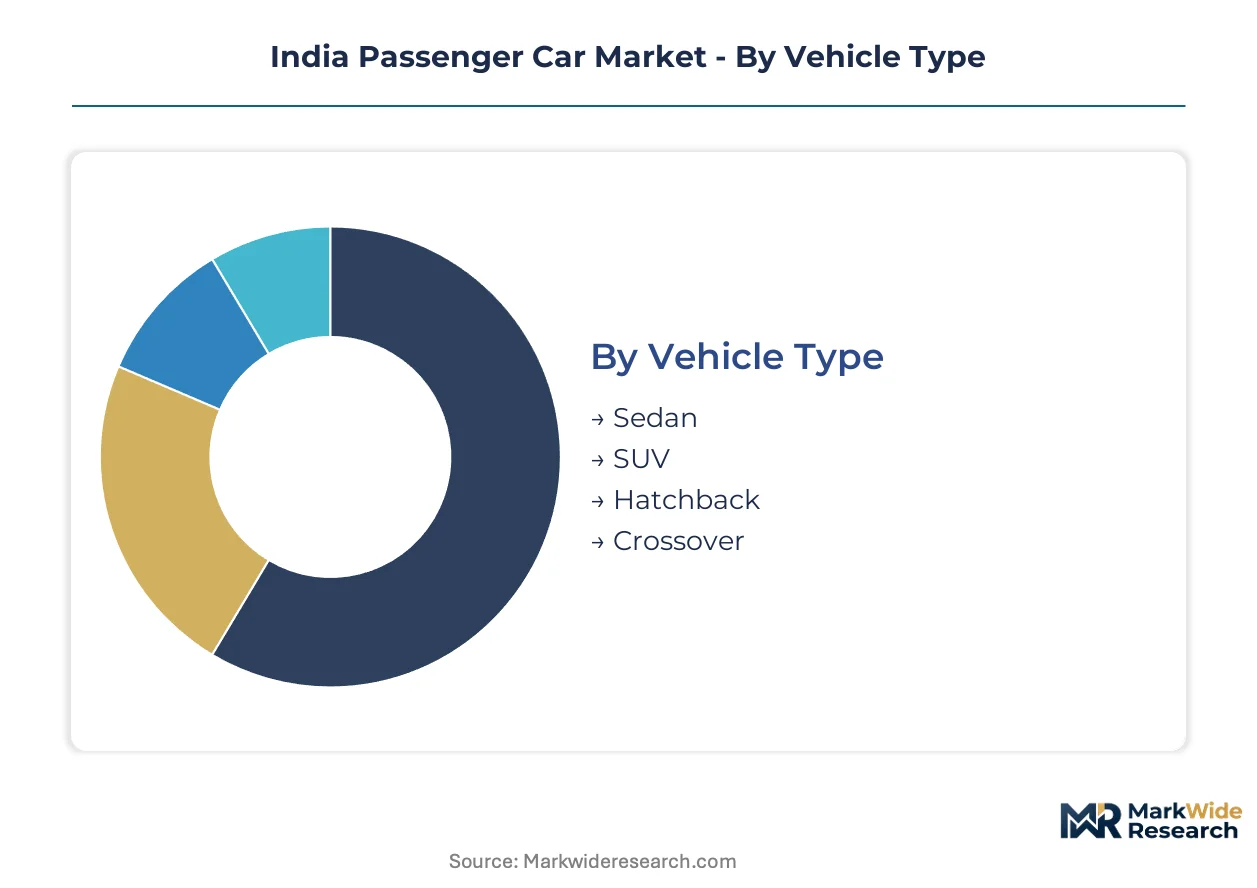
Segmentation in India's passenger car market reveals how purchase cycles, technology transitions, and regional income patterns create distinct competitive arenas. Understanding these divisions allows manufacturers to allocate engineering resources and distribution capacity across powertrain variants and body styles with divergent margin profiles.
Vehicle Type:
Replacement cycles vary sharply across body architectures, with compact hatchbacks turning over every 5-7 years while SUVs extend ownership horizons toward 8-10 years as buyers treat larger vehicles as long-term assets.
- SUV:High-ground-clearance unibody construction with elevated seating positions and flexible cabin configurations. Demand clusters in Gujarat and Maharashtra where road infrastructure variability and family size preferences favor commanding drive positions. Tata Motors and Mahindra anchor this segment through ladder-frame and monocoque platforms spanning sub-4-meter to full-size variants.
- Hatchback:Compact two-box design with truncated rear overhangs optimized for urban parking density and maneuverability. First-time buyers in Tamil Nadu and Karnataka municipalities drive volume, prioritizing acquisition cost over feature load. Maruti Suzuki's Alto and Swift nameplates dominate this entry point with localized powertrain calibration for stop-and-go traffic patterns.
- Sedan:Three-box silhouette with dedicated trunk compartments and extended wheelbases for rear-seat comfort. Corporate fleet procurement in Delhi-NCR and Bengaluru sustains residual demand despite showroom share erosion.
- Crossover:Blended architecture combining hatchback footprint with SUV styling cues through cladding and raised suspension. Urban professionals in Pune and Hyderabad gravitate toward this compromise format.
SUV and hatchback architectures dominate installed base. Crossover body styles are where expansion concentrates as manufacturers bridge portfolio gaps.
Fuel Type:
Powertrain selection maps directly to total cost of ownership calculations, with commercial operators prioritizing running economy while retail buyers weight upfront acquisition against fuel price volatility.
- Petrol:Spark-ignition internal combustion with port or direct fuel injection calibrated for Bharat Stage VI emission limits. Maharashtra and Karnataka urban households sustain largest installed base due to lower powertrain premiums and pervasive refueling infrastructure.
- Electric:Battery-electric propulsion with permanent magnet synchronous motors and liquid-cooled lithium-ion packs. Delhi's EV policy waivers and Maharashtra's road-tax exemptions are pulling fleet operators toward battery procurement despite charging network gaps in tier-2 cities.
- Diesel:Compression-ignition engines with selective catalytic reduction for NOx compliance. Long-distance fleet operators in Gujarat commercial corridors maintain preference for highway torque characteristics.
- CNG:Compressed natural gas bi-fuel systems with dedicated cylinder packaging. Mumbai and Delhi municipal transport ecosystems sustain aftermarket conversion demand.
Petrol powertrains dominate installed base. Electric fuel type is where expansion concentrates as state-level incentive structures reshape procurement economics.
Transmission Type:
Clutch pedal elimination correlates with traffic congestion severity, converting automatic variants from luxury positioning to practical necessity in dense urban corridors.
- Manual:Synchronized multi-speed gearboxes with mechanical clutch actuation. Tier-3 city buyers and commercial operators in Uttar Pradesh and Madhya Pradesh prioritize mechanical simplicity and repair accessibility.
- Automatic:Torque converter or dual-clutch architectures with hydraulic or electro-mechanical gear selection. Bengaluru and Hyderabad traffic conditions are accelerating shift away from manual operation among mid-segment purchasers.
- CVT:Continuously variable ratio systems using steel push belts or chains between variable-diameter pulleys. Maruti Suzuki and Honda deploy this architecture for urban efficiency optimization.
- Semi-Automatic:Automated manual transmissions with servo-actuated clutch and throttle blipping. Cost-conscious buyers seeking automatic convenience without torque converter fuel penalties gravitate toward this intermediate format.
Manual transmissions dominate installed base. Automatic architectures are where expansion concentrates as congestion and convenience preferences reshape buyer calculus.
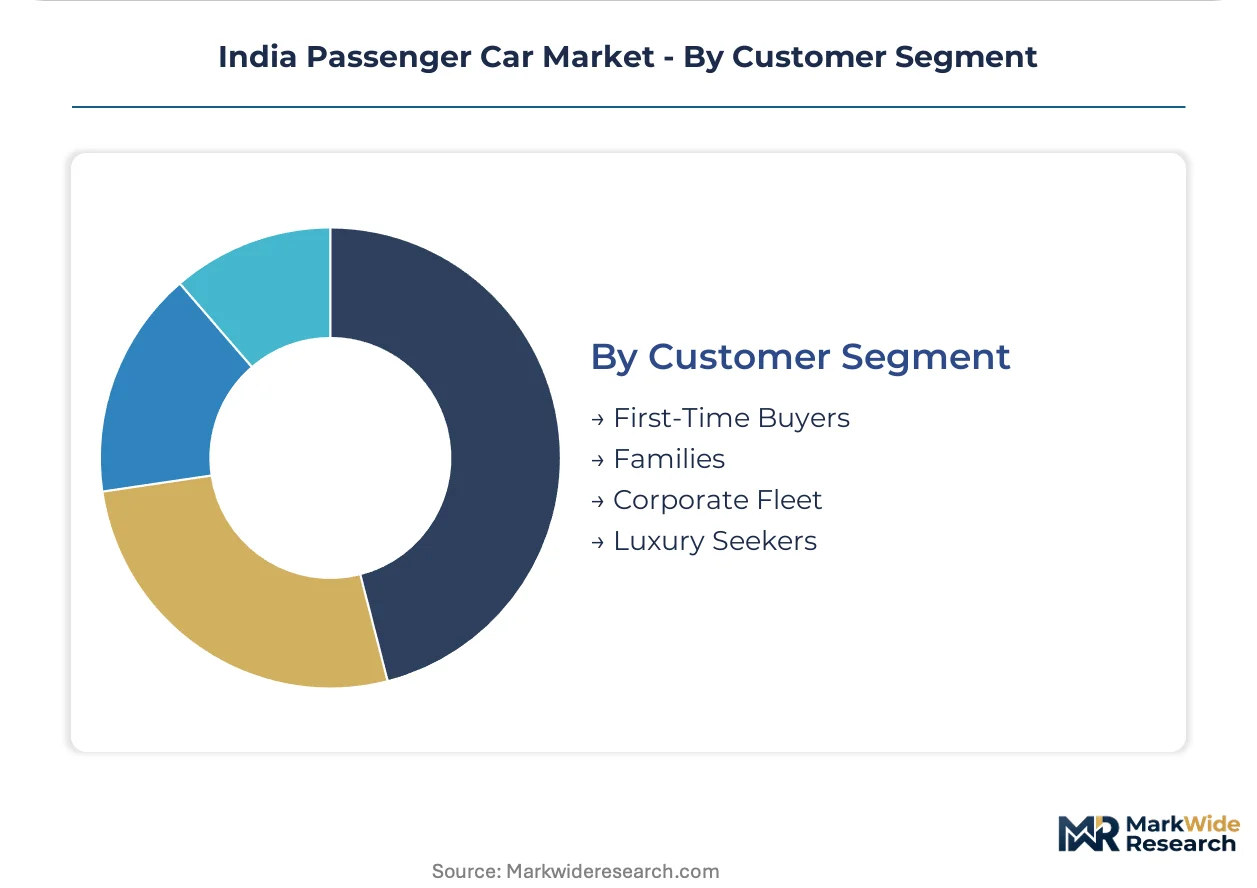
Customer Segment:
Purchase financing structures and feature prioritization diverge sharply across buyer maturity levels, from entry-level two-wheeler upgraders to replacement-cycle luxury seekers.
- First-Time Buyers:Households transitioning from motorized two-wheelers or public transport. Tamil Nadu and Andhra Pradesh districts with rising agricultural commodity incomes are driving compact hatchback and entry sedan volume.
- Families:Multi-generational households requiring flexible seating and cargo configurations. Maharashtra and Gujarat suburban corridors prioritize three-row SUVs and crossovers for weekend mobility.
- Corporate Fleet:Employer-provided vehicles and employee lease programs with standardized specifications. IT services and financial services firms in Bengaluru and Hyderabad sustain mid-size sedan and compact SUV procurement.
- Luxury Seekers:Discretionary purchasers prioritizing brand prestige and feature differentiation over transportation utility. Delhi-NCR and Mumbai premium corridors concentrate this segment's showroom activity.
Family and first-time buyer segments dominate installed base. Corporate fleet electrification is where expansion concentrates as ESG mandates and total cost of ownership advantages converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Indian states, with Gujarat and Maharashtra buyers absorbing premium powertrain costs while Uttar Pradesh and Bihar demand remain acutely sensitive to acquisition price thresholds.
Maharashtra
Fleet electrification mandates from the state transport department are accelerating battery-electric procurement among Mumbai-based logistics operators. The state's EV policy waives road tax and registration fees for commercial electric vehicles through 2027. Pune and Nashik industrial corridors concentrate assembly plant capacity where OEMs are retrofitting production lines for skateboard architectures.
Gujarat
Highway corridor freight operators sustain diesel powertrain preference for long-haul torque characteristics despite emission compliance cost inflation. The state's industrial promotion schemes offer capital subsidies for automotive component manufacturing. Sanand and Halol supplier clusters are expanding machining capacity for Bharat Stage VI exhaust after-treatment systems.
Tamil Nadu
First-time buyer density in Chennai, Coimbatore, and Madurai municipalities drives compact hatchback volume with minimal feature load requirements. The state's electric vehicle policy targets 100% bus fleet electrification by 2030, creating demonstration effects for private car buyers. Sriperumbudur and Oragadam automotive zones anchor export-oriented assembly capacity with integrated supplier parks.
Karnataka
IT services employee lease programs in Bengaluru sustain mid-size sedan and compact SUV procurement with standardized specifications. The state's EV policy mandates 100% electric vehicle government procurement and offers demand incentives for private buyers. Hosur and Bidadi manufacturing belts are scaling lithium-ion pack assembly lines under PLI scheme allocations.
Delhi-NCR
Odd-even traffic restrictions and air quality emergency measures are compressing replacement cycles toward cleaner powertrains among NCR households. The Delhi EV policy offers purchase incentives and registration fee waivers that stack with central subsidies. Gurugram and Manesar industrial areas concentrate premium vehicle assembly and R&D centers serving North Indian distribution networks.
India Passenger Car Market Competitive Environment
Capability concentration sits with integrated powertrain specialists; scale advantage sits with high-volume mass-market manufacturers. The market structure reflects a two-tier hierarchy where a handful of national champions control distribution density while regional assemblers compete on price in specific segments. Three archetypes dominate: vertically integrated conglomerates with captive component supply, platform-sharing global joint ventures, and emerging electric-native challengers. Competitive moves center on dealership network expansion into tier-3 cities and backward integration into battery cell assembly.
Within the integrated conglomerate tier, Tata Motors and Mahindra & Mahindra exemplify backward integration strategies through captive battery chemistry and electric powertrain production. Maruti Suzuki occupies a scale-driven position leveraging dense service coverage across secondary cities. Hyundai Motor Company and Kia Corporation represent platform-sharing global joint ventures optimizing development costs across internal combustion and electric architectures.
| Leading Market Players |
|---|
| Tata Motors |
| Kia Corporation |
| Maruti Suzuki |
| Skoda Auto |
| MG Motor |
| Mahindra & Mahindra |
| Toyota Motor Corporation |
| Honda Motors |
| Hyundai Motor Company |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion cell import dependency from East Asian cathode suppliers compresses pricing power across all tiers while simultaneously forcing OEMs to absorb currency volatility that widens spreads between battery-electric and internal combustion variants. This single-source concentration shapes procurement geography and determines which powertrain configurations achieve viable unit economics.
Pricing Analysis
Aftermarket service revenue, particularly extended warranty bundling and prepaid maintenance contracts, drives lifetime value capture and separates premium OEMs from value-positioned competitors. Three-tier pricing structure across premium, standard, and economy levels reflects battery pack capacity grades and Bharat Stage VI certification tiers rather than trim differentiation alone. Cost compression in entry-level electric variants is intensifying because domestic cell assembly under PLI scheme allocations has not yet achieved scale sufficient to offset import premiums. Fleet operators exhibit lowest price sensitivity due to total cost of ownership calculations, while first-time retail buyers in tier-3 cities remain acutely threshold-constrained.
Supply Chain Analysis
Extended payment terms from OEMs to tier-1 suppliers, coupled with supply-chain finance facilities anchored in Maharashtra banking corridors, determine working capital availability across the component base. Manufacturing concentration rests on China, South Korea, and Japan for lithium-ion cathode materials, electrolyte formulations, and power electronics semiconductors. Domestic production draws from imported lithium carbonate, nickel sulfate, and copper foil substrates that face logistics chokepoint exposure through Mumbai and Chennai port corridors. Distribution runs through captive supplier parks clustered around Sriperumbudur, Sanand, and Pune assembly belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic capability gaps in electric motor design, battery thermal management, and power electronics integration constrain how quickly production scale can respond to PLI scheme incentives. This scarcity dynamic rewards first movers who secure engineering talent pipelines and captive component supply.
For Market Incumbents: Build captive battery chemistry moats through in-house production of lithium-ion cell assembly and electric powertrain components. Secure structural engineering talent from competing sectors to compress Bharat New Vehicle Safety Assessment Program homologation timelines. Defend against emerging electric-native challengers by retrofitting legacy dealership networks for battery health diagnostics and electric vehicle maintenance revenue streams.
For New Entrants and Emerging Players: Mid-market crossover segments in Karnataka and Gujarat represent the most penetrable entry point given underdeveloped showroom presence and state-level EV policy waivers. Tier-3 city distribution networks in Tamil Nadu and Andhra Pradesh offer first-mover positioning as disposable income growth rotates demand away from metropolitan concentration. Pursue direct-to-consumer configurators that compress order-to-delivery cycles before allocation to regional distribution centers.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vertically integrated conglomerates with captive component supply over pure-play assemblers. Long-term viability over the projection horizon hinges on backward integration into battery cell assembly and electric powertrain production. Monitor state-level electric vehicle policy alterations to registration fee structures and road-tax incentives as the primary inflection indicator for manufacturing location and model-mix allocation decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell volumes from East Asian suppliers before PLI scheme domestic scale-up matures. |
| Platform Standardization | Enables Hyundai Motor India to share architectures between ICE and electric variants, reducing development expenditure. |
| Software-Defined Vehicle Investment | Displaces mechanical differentiation as primary competitive lever, enabling feature subscription revenue across powertrain variants. |
| Geographic Manufacturing Footprint | Positions assembly capacity in Maharashtra, Gujarat, and Tamil Nadu to exploit supplier cluster density economies. |
| Charging Infrastructure Partnership | Addresses grid reliability and fast-charger deployment gaps that sustain petrol variant preference in tier-2 and tier-3 cities. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers; and secondary validation against vehicle production databases, IHS Markit registration data, state transport department policy filings, and PLI scheme allocation disclosures. Bottom-up segmentation modeling triangulated with top-down macroeconomic overlays to ensure cross-verification of volume and value estimates.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions across the projection horizon. CAGRs were derived from regression analysis of historical production trends, policy incentive trajectories, and substitution elasticity between powertrain variants. Battery cost decline curves and charging infrastructure deployment schedules served as automotive-specific sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, lithium carbonate spot prices, or central subsidy continuity would shift the trajectory. Forecasts reflect documented assumptions about PLI scheme disbursement timelines and state-level EV policy durability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Medium Cars Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Train Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Small Suvs Market