
 Russia Light Vehicle Market | 2026-2036
Russia Light Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Light Vehicle Market Analytics
Localization of component sourcing is narrowing the technology gap between domestic assembly and imported finished vehicles. AvtoVAZ anchors production volume through its extensive supplier ecosystem across Togliatti and Izhevsk. Haval leverages its full-scale manufacturing presence in Russia's Tula region to sustain competitive positioning in the SUV category. Chery competes through aggressive platform sharing and localized powertrain adaptation.
A light vehicle is a passenger or light commercial automobile with a gross vehicle weight rating below 3,500 kilograms, typically constructed with unibody or body-on-frame architecture and powered by internal combustion, electric, or hybrid propulsion systems. Its primary purpose is personal mobility and light cargo transport within urban and intercity road networks. The SUV segment dominates volume as Russian consumers prioritize ground clearance and all-weather capability across poorly maintained regional road infrastructure. Electric and hybrid fuel types represent the fastest-growing category, though from a low base, as charging infrastructure expands in major population centers. The budget market segment retains the largest addressable volume, while premium and luxury tiers concentrate margin pools in Moscow and St. Petersburg.
Russia's national technical regulator enforces vehicle safety and environmental compliance through mandatory certification procedures that restrict market access for non-compliant imports. The country's central bank and industrial development instruments shape automotive financing conditions and localization incentives for foreign manufacturers. Stakeholders must monitor how evolving trade barrier configurations and domestic content requirements alter competitive entry economics for new participants.
Market Dynamics
Fleet renewal programs in commercial logistics are accelerating platform turnover as operators confront Russia's tightening vehicle safety certification requirements under the national technical regulation framework.
Growth Catalysts
- Central Federal District concentration:Demand clusters around Moscow and its industrial satellite zones, creating economies of scale for distribution networks and service infrastructure.
- Charging infrastructure rollout:Electric and hybrid propulsion systems gain traction as major population centers expand grid-connected refueling capacity.
- Localization mandates:Domestic content requirements under industrial development instruments pull foreign manufacturers toward component sourcing within Russia's supplier ecosystem.
Market Restraints
- Semiconductor input volatility:Disruptions in microprocessor supply chains constrain production scheduling across unibody and body-on-frame architectures.
- Supplier geography concentration:Heavy reliance on Togliatti and Izhevsk production clusters creates vulnerability to localized logistics interruptions.
- Certification timeline friction:Mandatory safety and environmental compliance procedures extend market access timelines for non-compliant import configurations.
Strategic Opportunities
- Regional road infrastructure gap:Ground clearance and all-weather capability requirements in poorly maintained zones outside Moscow-St. Petersburg corridors favor SUV platform expansion.
- Premium tier margin capture:Luxury vehicle demand concentration in Moscow and St. Petersburg enables pricing power extraction from high-net-worth buyers.
- Powertrain convergence:Integration of hybrid systems with localized engine adaptation creates product differentiation against pure internal combustion competitors.
Industry Challenges
- Platform architecture capex intensity:Upgraded vehicle architectures require substantial capital redeployment to meet certification thresholds.
- Skill scarcity in electrification:Technician training lags behind electric and hybrid system complexity, constraining after-sales service capacity.
- Legacy supply chain reconfiguration:Transition from imported finished vehicles to domestic assembly forces wholesale supplier relationship restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Light Vehicle Market |
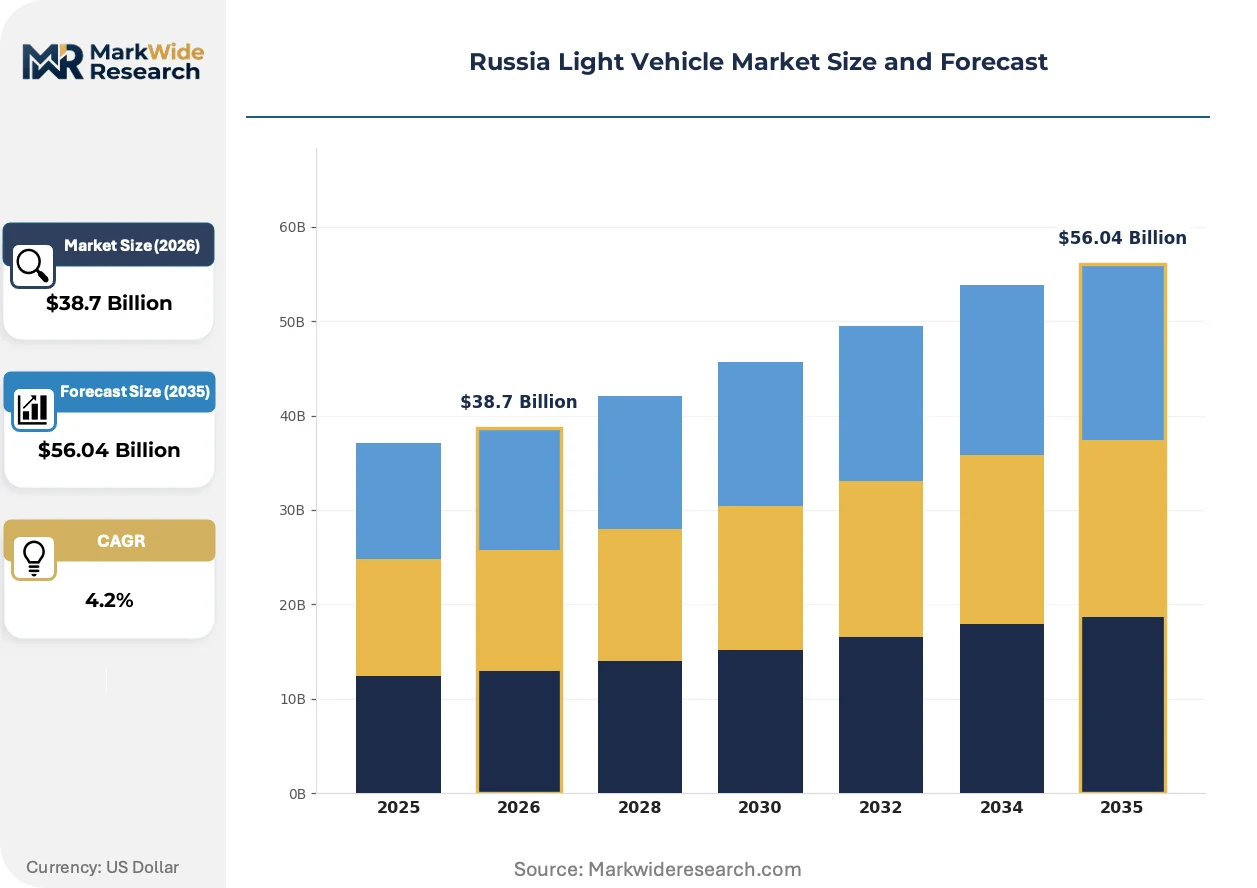
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, Hatchback, SUV, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Transmission: Manual, Automatic, CVT, Semi-Automatic Market Segment: Premium, Budget, Luxury, Mid-Range |
| Companies Covered | AvtoVAZ, Haval, Chery, Geely, GAZ Group, UAZ, Sollers, Avtotor, Moskvitch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Light Vehicle Market Evolving Landscape
Technology trajectories in the Russia Light Vehicle Market center on propulsion diversification, regulatory compliance automation, and buyer preference fragmentation across terrain-specific use cases.
Hybrid powertrain architectures are collapsing the cost-performance gap between conventional internal combustion and full electric platforms. Fleet operators in the commercial logistics sector are adopting these systems at accelerating pace to hedge fuel price exposure. This technology compression is enabling mid-market manufacturers to field competitive entries without full battery-electric infrastructure dependency.
Russia's national technical regulation framework is tightening vehicle safety certification requirements that restrict market access for non-compliant imports. The industrial consequence forces manufacturers toward upgraded platform architectures with enhanced crashworthiness and emissions control. SUV and light commercial segments bear the heaviest compliance burden as these categories dominate renewal program volumes.
Buyer preference is fragmenting toward terrain-specific capability as regional road infrastructure quality diverges sharply between metropolitan corridors and hinterland zones. Dealership networks in the Central Federal District are repositioning inventory toward higher-ground-clearance configurations. This geographic demand rotation favors body-on-frame architectures in satellite industrial zones surrounding Moscow.
Russia Light Vehicle Market Segmentation
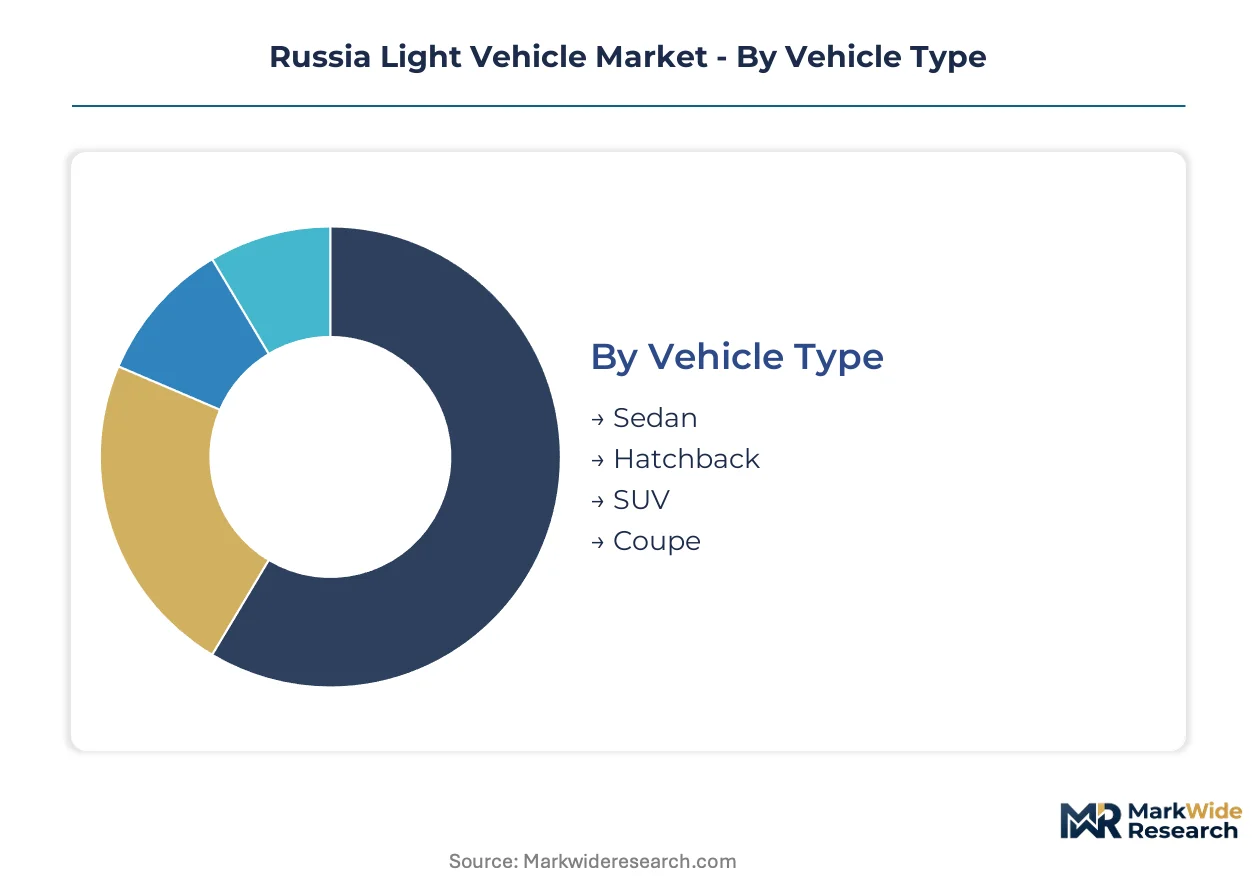
Segmentation in Russia's light vehicle market reveals how platform architectures, propulsion systems, and buyer economics intersect with the country's uneven infrastructure and regulatory framework. Understanding these divisions exposes where capital concentrates and where technology gaps create entry opportunities.
Vehicle Type:
SUV platforms turn over fastest as fleet operators and retail buyers prioritize ground clearance for deteriorating regional roads, while sedans cycle slowest in saturated urban corridors.
- SUV:Body-on-frame and unibody architectures with elevated ride height dominate procurement pipelines. Demand clusters in the Central Federal District's industrial satellite zones where all-weather capability commands premium pricing against delivery reliability requirements.
- Sedan:Three-box passenger configurations with fixed rooflines and dedicated cargo compartments retain the largest installed base. Moscow and St. Petersburg concentrate replacement demand as corporate fleets modernize aging mid-size platforms under tightened certification deadlines.
- Hatchback:Two-box designs with integrated cargo access serve compact urban mobility needs. Togliatti's supplier ecosystem anchors domestic production volume for this category.
- Coupe:Fixed-roof two-door configurations with sport-tuned suspensions occupy niche positioning. St. Petersburg's high-net-worth buyer pool sustains import-dependent supply for this segment.
Sedan dominates installed base. SUV is where expansion concentrates.
Fuel Type:
Petrol powertrains carry the lowest capital commitment per unit, while electric platforms demand longest payback periods despite accelerating infrastructure rollout.
- Petrol:Spark-ignition internal combustion engines with port or direct fuel injection retain broadest service network coverage. Izhevsk production clusters and Togliatti supplier networks ensure parts availability across Russia's hinterland regions.
- Hybrid:Combined internal combustion and electric propulsion with regenerative braking capability is expanding most quickly. Fleet operators in commercial logistics adopt these systems to hedge fuel price exposure without full charging infrastructure dependency.
- Diesel:Compression-ignition engines with higher thermal efficiency serve heavy-duty light commercial applications. Tightening emissions certification under Russia's national technical regulation framework constrains new platform introductions.
- Electric:Battery-electric powertrains with grid-dependent refueling gain traction in major population centers. Charging infrastructure expansion in Moscow creates geographic concentration of viable use cases.
Petrol dominates installed base. Hybrid is where expansion concentrates.
Transmission:
Manual gearboxes offer shortest replacement cycles in price-sensitive fleet segments, while automatic variants extend lifecycle through reduced driver fatigue in premium tiers.
- Automatic:Torque converter-based systems with planetary gearsets command highest attachment rates in Moscow's premium retail channel. Haval's Tula manufacturing presence localizes production for this transmission category.
- Manual:Synchronized mesh gearboxes with clutch actuation retain cost advantage in budget fleet procurement. AvtoVAZ's extensive supplier ecosystem supports volume production for this configuration.
- CVT:Continuously variable ratio systems with belt or chain drive improve fuel economy in compact urban vehicles. Localized powertrain adaptation by Chery expands availability in the mid-market segment.
- Semi-Automatic:Automated manual transmissions with electronic clutch actuation bridge cost-performance requirements. Budget segment buyers in satellite industrial zones surrounding Moscow select this option for delivery vehicle applications.
Manual dominates installed base. Automatic is where expansion concentrates.
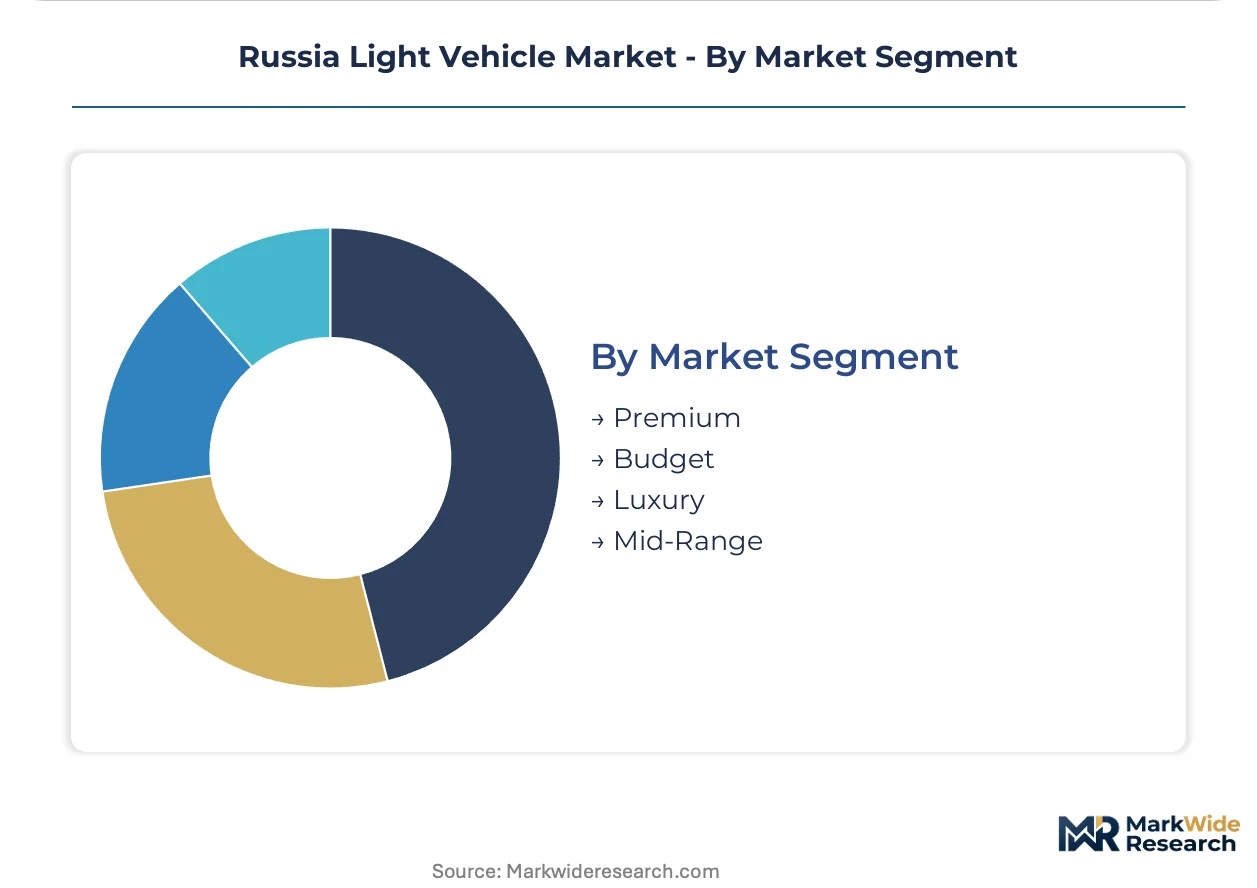
Market Segment:
Budget-tier vehicles achieve fastest inventory velocity through volume distribution networks, while luxury segments sustain extended sales cycles with higher per-unit margins.
- Budget:Entry-price vehicles with essential feature content and localized component sourcing capture largest addressable volume. Chery's platform sharing strategy and aggressive localization targets this tier.
- Premium:Enhanced specification vehicles with advanced safety systems and connectivity features concentrate margin pools. Moscow and St. Petersburg buyers drive demand for upgraded platform architectures.
- Mid-Range:Balanced feature-content vehicles with competitive warranty terms serve fleet renewal programs. Commercial logistics operators in the Central Federal District prioritize total cost of ownership in this tier.
- Luxury:High-specification vehicles with imported components and bespoke configuration options occupy concentrated geography. Moscow's high-net-worth buyer segment enables pricing power extraction despite limited volume.
Budget dominates installed base. Premium is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's light vehicle trade flows primarily through domestic assembly corridors serving the Central Federal District, with component sourcing networks extending into supplier clusters across Togliatti and Izhevsk.
Central Federal District
Moscow anchors procurement volume for corporate fleet renewal programs and premium retail channels. Russia's national technical regulation framework mandates upgraded safety certification for all new vehicle registrations. The industrial satellite zones surrounding Moscow concentrate SUV assembly operations targeting all-weather capability requirements.
Volga Federal District
Togliatti's supplier ecosystem sustains domestic production volume for hatchback and budget-tier segments through extensive component localization. The country's industrial development instruments incentivize foreign manufacturers to deepen domestic content ratios. Izhevsk production clusters anchor manual transmission supply chains serving price-sensitive fleet procurement.
Northwestern Federal District
St. Petersburg concentrates luxury vehicle demand from high-net-worth buyers despite limited import-dependent supply. Russia's central bank shapes automotive financing conditions affecting premium-tier purchasing power. The city's dealer networks reposition inventory toward higher-specification configurations with advanced connectivity features.
Southern Federal District
Rostov-on-Don and Krasnodar serve as distribution nodes for SUV platforms targeting regional road infrastructure gaps. The national technical regulator enforces emissions compliance procedures that constrain diesel powertrain introductions. Commercial logistics operators in this corridor prioritize ground clearance for poorly maintained intercity routes.
Ural Federal District
Yekaterinburg functions as a secondary demand center for mid-range fleet vehicles serving industrial extraction industries. Localization mandates under domestic content requirements pull component sourcing toward established supplier networks. The region's distance from primary production clusters creates logistics cost premiums affecting total cost of ownership calculations.
Russia Light Vehicle Market Competitive Landscape
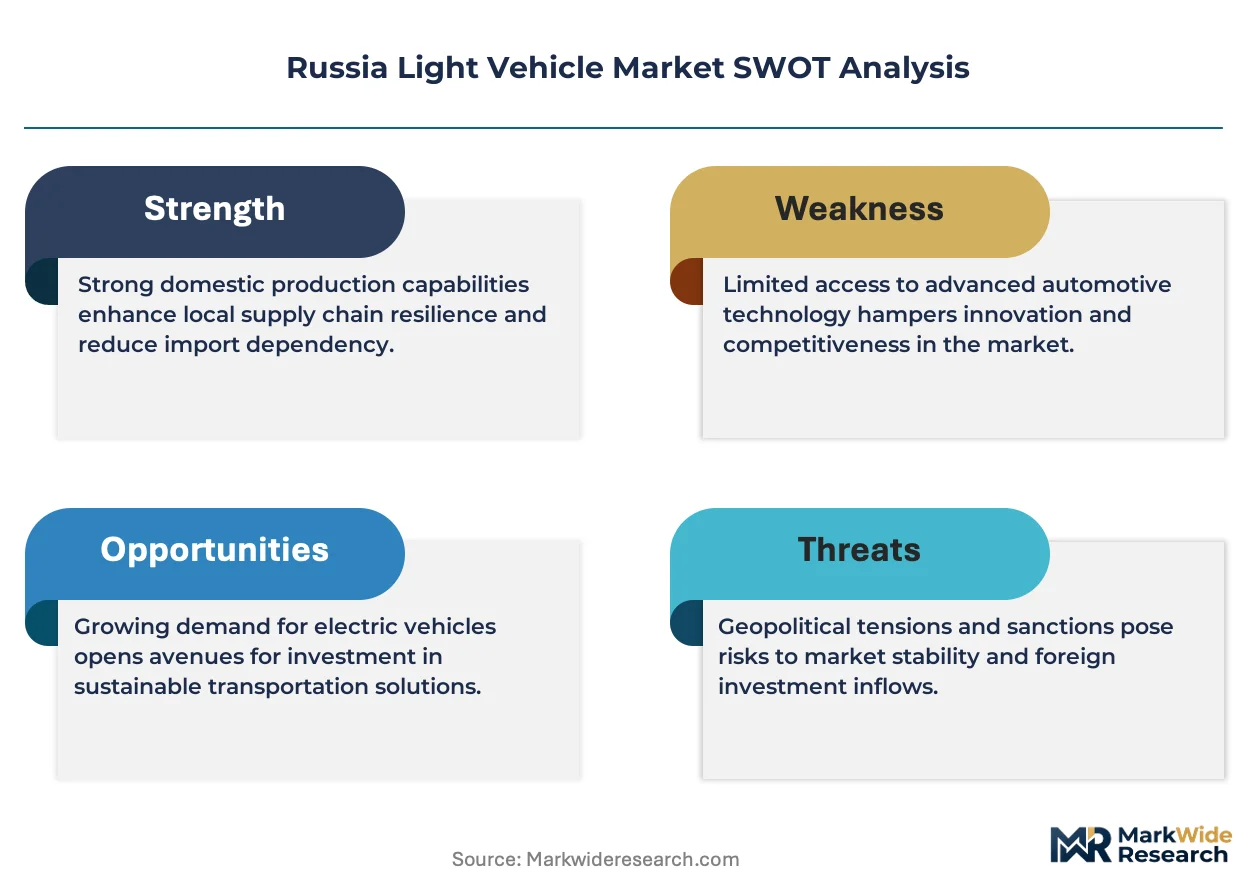
Channel-controlling players compete with product-specialist players across tiered market positions defined by scale and localization depth. The structure concentrates around domestic incumbents with established supplier ecosystems and foreign entrants with manufacturing presence. Two strategic archetypes dominate: vertically integrated domestic champions leveraging captive supply networks, and foreign assemblers adapting global platforms to local certification requirements. Competitive moves center on capacity expansion in the Central Federal District and strategic partnerships for powertrain localization.
Among domestic champions, AvtoVAZ anchors volume production through its Togliatti and Izhevsk supplier ecosystems, representing the vertically integrated archetype. Haval occupies a position as the foreign manufacturing benchmark through its Tula region assembly presence. Chery exemplifies platform-sharing specialists competing through aggressive localization and powertrain adaptation strategies.
| Leading Market Players |
|---|
| AvtoVAZ |
| Haval |
| Chery |
| Geely |
| GAZ Group |
| UAZ |
| Sollers |
| Avtotor |
| Moskvitch |
| Others |
Value Network & Pricing Analysis
Togliatti's supplier ecosystem concentration shapes downstream pricing power across Russia's light vehicle market, with AvtoVAZ's captive production network enabling cost advantages that foreign assemblers struggle to replicate without equivalent localization depth.
Pricing Analysis
Current-generation hybrid powertrains command substantial premiums over prior-generation petrol platforms, while next-generation battery-electric architectures remain priced at fleet-operator resistance thresholds. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and domestic content ratio. Pricing pressure stems from semiconductor input volatility constraining production scheduling. Budget fleet procurement exhibits highest price sensitivity, while Moscow premium retail channels absorb specification-driven premiums with minimal elasticity.
Supply Chain Analysis
Export-control regimes limiting semiconductor and advanced electronics flows have forced reconfiguration of component sourcing relationships for Russian vehicle assembly. Supply draws from China for electronics, South Korea for battery cells, and domestic Togliatti-Izhevsk clusters for mechanical subsystems. Raw material dependencies center on steel sheet, aluminum castings, and copper wiring harnesses. Single-source vulnerability concentrates in microprocessor supply chains. Distribution runs through OEM-controlled dealer networks serving Central Federal District fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's light vehicle market sits at a platform-economics inflection where hybrid powertrain interoperability between domestic and foreign manufacturer ecosystems is collapsing prior technology-generation moats.
For Market Incumbents: Harden supplier relationship control through backward integration into critical electronics sourcing, insulating against semiconductor supply disruptions that threaten production continuity. Deepen captive supply of manual transmission and body-on-frame components to defend cost position against Chery's platform-sharing expansion. Prioritize certification investment ahead of Russia's national technical regulation framework tightening timelines. For New Entrants and Emerging Players: Establish a beachhead in the mid-range hybrid segment where fleet operators seek fuel-price hedging without full charging infrastructure dependency. Target commercial logistics procurement in Central Federal District satellite zones where total cost of ownership calculations favor localized powertrain adaptation. Deploy aggressive domestic content ratio positioning to qualify for industrial development instrument incentives. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because supplier ecosystem control determines sustainable margin extraction as certification barriers rise. Acquisition targets should display vertical integration depth in Togliatti-corridor production clusters. Monitor charging infrastructure rollout velocity in Moscow as the signal indicating battery-electric platform viability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering overhead for hybrid architectures across SUV and sedan lines. |
| Battery Supply Agreement | Secures cell allocation from Chinese or South Korean producers for localized pack assembly. |
| Software-Defined Vehicle Investment | Enables over-the-air updates circumventing physical service network limitations in hinterland regions. |
| Geographic Manufacturing Footprint | Tula region expansion replicates Haval's precedent for foreign manufacturer market access. |
| Charging Infrastructure Partnership | Grid-connected refueling capacity expansion unlocks battery-electric segment viability in Moscow. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement directors, commercial fleet operations managers, and dealership network heads, then refined through secondary validation against vehicle production databases, IHS Markit registration data, customs import records, and industrial development instrument filings. Bottom-up volume builds and top-down macroeconomic anchoring were triangulated to converge estimates.
Demand-supply-balance framing anchored the analytical framework across the modeling period, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from slope analysis of normalized growth trajectories. Forecast inputs incorporated charging infrastructure rollout curves and certification timeline assumptions under Russia's national technical regulation framework.
Stress conditions across semiconductor supply continuity, exchange rate volatility, and domestic content requirement enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or trade barrier reconfiguration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Family Car Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Train Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Solar Passenger Car Market