
 Electric Skateboard Market | 2026-2036
Electric Skateboard Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Skateboard Market Analysis
The capital-intensity divergence between in-house deck fabrication and outsourced assembly is redrawing competitive boundaries within the electric skateboard space. Wowgo leverages direct-to-consumer channel control to sustain margin structures that vertically integrated rivals struggle to match. Meepo anchors its position through concentrated R&D spending on proprietary motor controllers. Backfire competes by dominating European distribution partnerships that smaller brands cannot replicate.
An electric skateboard is a personal mobility device integrating a rechargeable lithium-ion battery pack, brushless DC hub or belt-drive motors, and a composite deck with electronic speed control via handheld remote or weight-sensing interface, engineered primarily for individual urban transportation and recreational riding. Deck fabrication employs layered maple or bamboo veneers with fiberglass or carbon fiber reinforcement to achieve flex ratings and load capacities suited to distinct riding disciplines. Commuter and all-terrain product types capture divergent margin pools, with commuter models benefiting from volume scale in dense metropolitan corridors while all-terrain configurations command premium positioning through suspension complexity and battery capacity upgrades. Carbon fiber and bamboo material segments attract performance-oriented buyers seeking reduced weight without sacrificing structural integrity, whereas maple wood retains cost-sensitive entry positioning.
The Consumer Product Safety Commission enforces electrical and mechanical safety standards that govern battery enclosure design and braking performance thresholds for devices sold in the United States. The EU Machinery Directive and CE marking requirements shape market access protocols for European distribution, compelling manufacturers to adapt certification documentation across regulatory jurisdictions. California state regulations on micromobility device operation in bike lanes directly influence product feature prioritization for brands targeting North American volume. Stakeholders must monitor evolving battery transportation restrictions from aviation authorities and municipal licensing schemes that could reshape channel economics and geographic expansion sequencing.
Market Dynamics
Lithium-ion cell energy density improvements from South Korean manufacturers are compressing battery pack footprints while extending range thresholds, forcing deck architecture and motor placement redesigns across the supply base.
Growth Catalysts
- Urban last-mile delivery fleet electrification:Logistics operators in California are expanding electric skateboard procurement for courier density in congested metropolitan cores.
- Micromobility lane infrastructure:State-level investments in dedicated riding corridors reduce perceived safety barriers and accelerate commuter adoption velocity.
- REACH-compliant battery chemistries:European cell manufacturers are scaling nickel-manganese-cobalt formulations that satisfy ECHA substance restrictions while maintaining thermal stability.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings from South American brine operations compress margin predictability for pack assemblers.
- Aviation battery transport restrictions:FAA and IATA limitations on lithium-ion air freight raise inventory carrying costs and complicate cross-border fulfillment.
- Mechanical braking performance thresholds:CPSC-mandated deceleration rates force heavier actuator hardware that conflicts with weight minimization targets.
Strategic Opportunities
- Campus and corporate mobility-as-a-service:University and tech campus fleets represent underpenetrated demand for pooled short-range devices with centralized charging.
- EU Green Deal mobility incentives:Member state subsidy schemes for zero-emission personal transport create procurement tailwinds for CE-marked products.
- Composite deck additive manufacturing:Convergence of automated fiber placement and topology optimization software enables batch-of-one customization at production economics.
Industry Challenges
- Embedded systems firmware talent scarcity:Competitive hiring for motor control algorithm developers delays product roadmap execution at mid-tier manufacturers.
- Multi-jurisdiction certification timelines:Sequential UL, CE, and FCC testing protocols extend time-to-revenue by 4-8 months for new platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Skateboard Market |
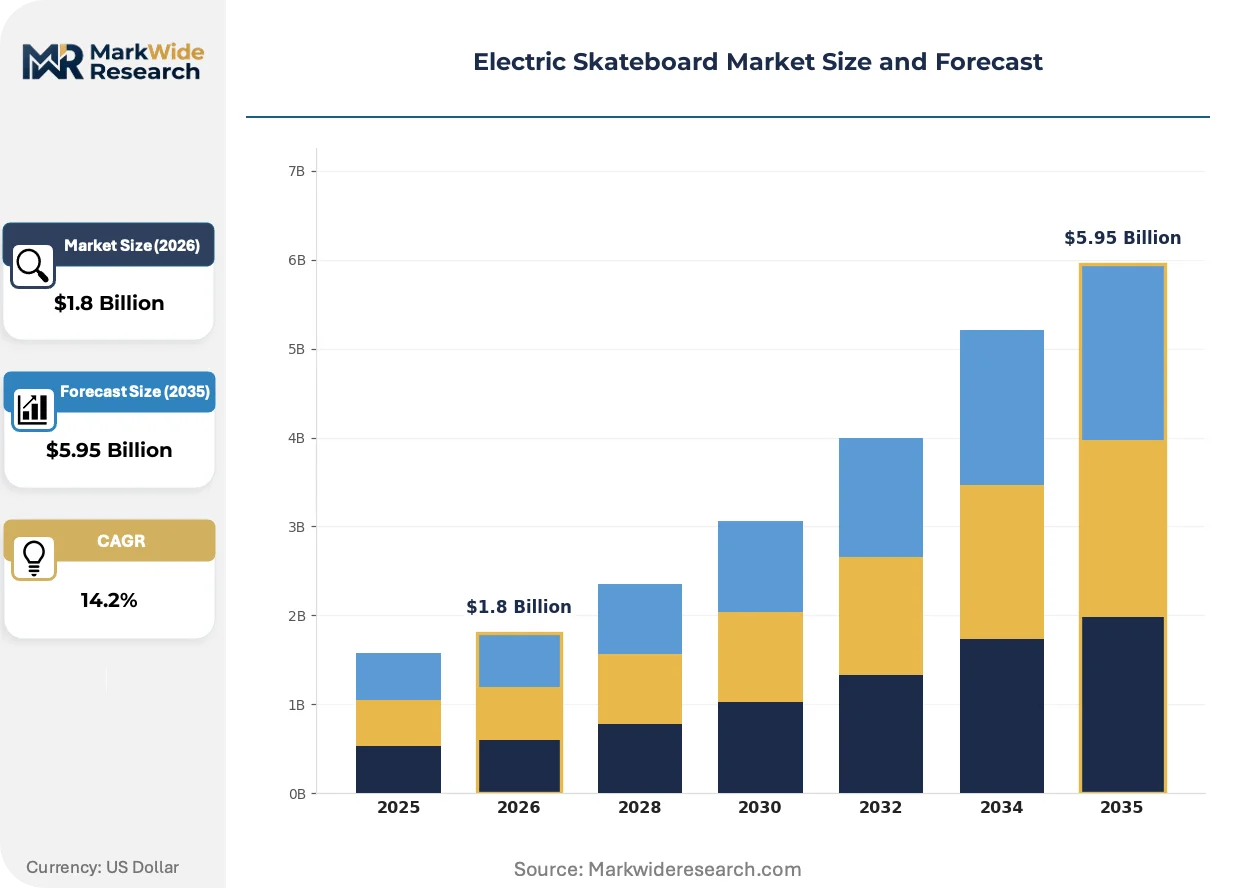
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Terrain, Commuter, Cruiser, Performance Battery Capacity: 2Ah, 4Ah, 6Ah, 10Ah Material: Maple Wood, Bamboo, Aluminum, Carbon Fiber Weight Class: Lightweight, Midweight, Heavyweight, Ultra-Lightweight |
| Companies Covered | Acedeck, Wowgo, Meepo, Tynee, Backfire, OMW Boards, ONSRA, Propel, Ecomobl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Skateboard Market Emerging Trajectories
Component integration density and regulatory harmonization pressures are compressing product development cycles while opening differentiation vectors around connected features and sustainable materials.
Brushless DC hub motor architectures with integrated field-oriented control electronics are miniaturizing powertrain footprints without torque degradation. Performance-oriented commuter segments are adopting these consolidated units to reclaim deck space for battery expansion. This consolidation is miniaturizing the traditional belt-drive assembly category and compressing supplier tiers in the drivetrain value chain.
California state regulations on micromobility device operation in bike lanes are mandating lighting, reflectivity, and maximum speed thresholds that shape product feature prioritization. Manufacturers targeting North American volume must engineer compliance into base configurations rather than aftermarket accessories. This regulatory pressure most affects entry-tier models where cost absorption capacity is thinnest.
Fleet operators and institutional buyers are consolidating procurement through direct manufacturer relationships, disintermediating traditional distributor channels. This concentration shifts margin capture toward OEMs while squeezing regional wholesaler economics. The pattern is most visible in California and Pacific Northwest metropolitan corridors where municipal pilot programs aggregate demand volume.
Electric Skateboard Market Segmentation
Electric skateboard segmentation reveals divergent margin architectures across product tiers. Battery capacity and material composition drive the widest price spreads, while weight class stratification reflects distinct rider demographics and use-case intensity.
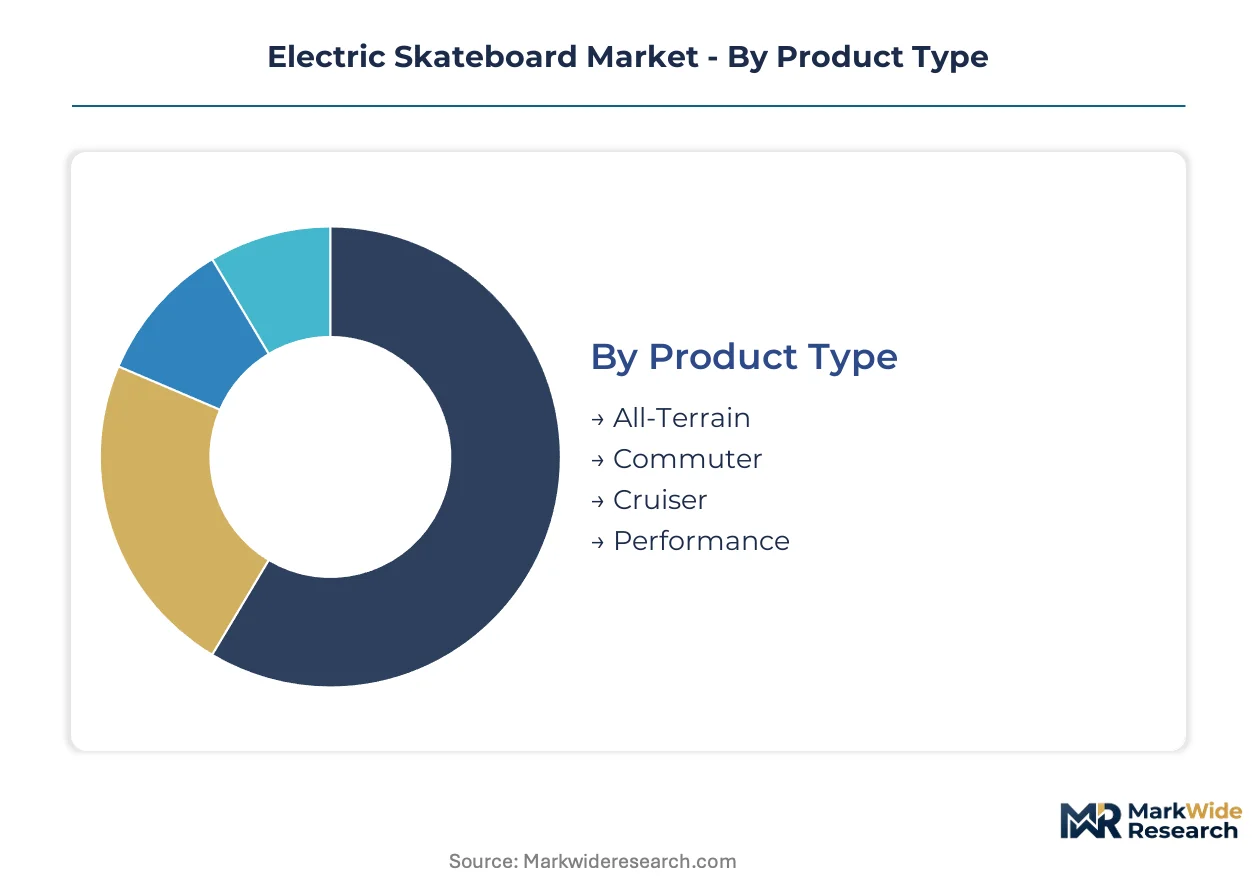
Product Type:
Margin pools concentrate in purpose-built configurations that command premium positioning through suspension complexity and powertrain specifications.
- Commuter:Streamlined deck profiles with integrated lighting and moderate range specifications dominate urban corridor procurement. California fleet operators and European micromobility programs source these units in volume for last-mile delivery density, prioritizing reliability over extreme performance metrics.
- All-Terrain:Dual-motor configurations with pneumatic tires and adjustable suspension absorb rough surfaces at the cost of substantial weight penalties. Demand clusters in recreational markets across Germany and the Pacific Northwest where trail-accessible riding zones reduce road-surface constraints.
- Cruiser:Flex-oriented decks with single-hub motors prioritize ride comfort over acceleration metrics. Cost-conscious entry buyers in university towns favor these units for short-distance campus circulation.
- Performance:High-discharge battery packs paired with belt-drive systems deliver sustained torque for hill-climbing and competitive riding. Limited production volumes restrict this segment to enthusiast collectors and racing circuit participants.
The dominant share belongs to Commuter, while All-Terrain is closing the gap fastest.
Battery Capacity:
Cost tier stratification aligns directly with range anxiety thresholds and charging infrastructure access patterns across metropolitan deployment zones.
- 10Ah:Extended-range configurations utilizing nickel-manganese-cobalt cell chemistries from South Korean manufacturers enable 40+ kilometer routes without intermediate charging. European Green Deal subsidy eligibility and California commercial fleet specifications drive procurement concentration.
- 6Ah:Mid-tier packs balance cell count against deck weight distribution, serving daily commuters with sub-15 kilometer round-trip requirements. German and Dutch urban riders favor this capacity for regulatory compliance with bike-lane weight restrictions.
- 4Ah:Entry-level lithium-ion assemblies from Chinese cell suppliers reduce upfront acquisition costs. Student demographics and occasional recreational users accept range limitations for price accessibility.
- 2Ah:Minimalist configurations for ultra-lightweight deck designs sacrifice endurance for portability. Airport carry-on compliance and multimodal transit integration define this niche.
Procurement volume peaks at 6Ah, though 10Ah configurations show the steepest expansion trajectory among commercial buyers.
Material:
Application-specific durability requirements and weight minimization targets fragment supplier relationships across composite and natural fiber value chains.
- Carbon Fiber:Automated fiber placement enables complex geometries with exceptional stiffness-to-weight ratios. Performance-tier manufacturers in California and Bavaria specify these decks for racing and premium commuter positioning.
- Bamboo:Natural fiber laminates with fiberglass reinforcement deliver tuned flex characteristics for carving disciplines. Southeast Asian veneer suppliers serve cost-sensitive mid-market brands seeking sustainability credentials.
- Maple Wood:Traditional seven-ply constructions retain dominance in entry-tier price positioning. North American hardwood suppliers face pressure from laminated bamboo alternatives in Asian manufacturing.
- Aluminum:Extruded and machined deck platforms provide structural rigidity for heavy-duty commercial applications. Fleet operators in logistics and campus mobility specify these units for damage resistance and service life.
Carbon Fiber commands the highest unit economics, yet Bamboo is gaining share fastest among environmentally positioned brands.
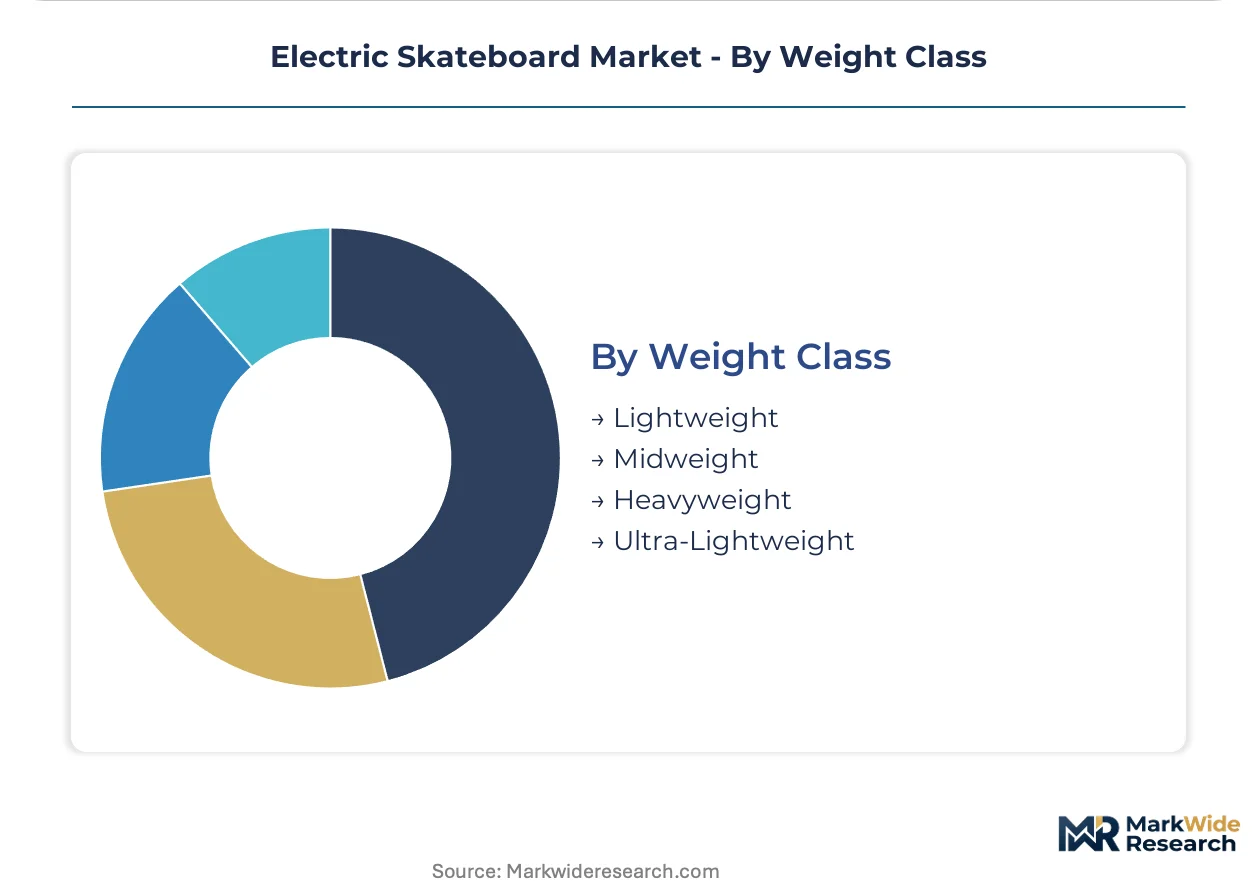
Weight Class:
Customer type differentiation separates recreational enthusiasts from utility-focused commuters through portability thresholds and load-bearing specifications.
- Lightweight:Sub-7 kilogram configurations with compact hub motors and reduced battery capacity prioritize carry convenience. Multimodal transit users in dense European cities and Japanese metropolitan areas demand this class for stair climbing and train boarding.
- Midweight:Balanced 7-10 kilogram platforms accommodate standard-range batteries without excessive bulk. The broadest addressable market spans casual commuters and recreational riders across North American suburbs.
- Heavyweight:Reinforced decks and dual-motor systems exceeding 10 kilograms sacrifice portability for stability and power delivery. All-terrain enthusiasts and heavier riders accept these tradeoffs for control confidence.
- Ultra-Lightweight:Experimental carbon fiber and titanium component integration pushes below 5 kilograms. Early-adopter segments in tech-forward urban clusters test these prototypes for ultimate portability.
Midweight retains the largest installed base, while Lightweight configurations are expanding most quickly among transit-integrated commuters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: price-sensitive student demographics in Germany and the Netherlands favor entry-tier configurations, while premium-tier buyers in California and Bavaria absorb carbon fiber premiums without volume tradeoffs.
United States
California fleet operators aggregate procurement for last-mile delivery density, while individual commuters in the Pacific Northwest prioritize all-terrain capability for trail-accessible riding. The Consumer Product Safety Commission enforces electrical and mechanical safety standards governing battery enclosure design. Los Angeles and San Francisco micromobility infrastructure investments expand dedicated lane networks that reduce perceived safety barriers.
Germany
Recreational riders across Bavaria and North Rhine-Westphalia command premium positioning for adjustable suspension and pneumatic tire configurations. The EU Machinery Directive and CE marking requirements shape market access protocols for European distribution. Stuttgart and Munich industrial clusters host composite deck fabrication specialists serving performance-tier manufacturers with automated fiber placement capabilities.
China
Domestic manufacturers concentrate in the Pearl River Delta and Yangtze River Delta, supplying global brands with lithium-ion cell assemblies and hub motor systems. GB standards and MIIT regulations govern product safety certification for domestic sale. Shenzhen-based electronics integrators compress development cycles through proximity to brushless DC motor suppliers and battery management system developers.
South Korea
Cell manufacturers in Seoul and Busan supply nickel-manganese-cobalt formulations to global pack assemblers, extending range thresholds through energy density improvements. MFDS and national standards bodies coordinate with international aviation authorities on battery transportation protocols. Incheon metropolitan area logistics hubs manage regional distribution for Asia-Pacific OEM procurement.
Netherlands
Urban commuters in Amsterdam and Rotterdam favor lightweight sub-7 kilogram configurations for multimodal transit integration across dense cycling infrastructure. National bike-lane weight restrictions and municipal licensing schemes shape product feature prioritization. Eindhoven Region technology campuses pilot pooled mobility-as-a-service fleets with centralized charging infrastructure.
Electric Skateboard Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes through channel control and concentrated R&D positioning. The market structure compresses into two functional layers: direct-to-consumer brands with margin sustainability and distribution-heavy operators with geographic lock-in. Archetypes include channel-optimized specialists, motor control technology anchors, and European partnership dominators. Competitive moves center on R&D concentration in proprietary electronics and exclusive distribution agreements that smaller rivals cannot replicate.
Within the direct-to-consumer tier, Wowgo exemplifies channel-optimized positioning through margin structures that vertically integrated competitors struggle to match. Meepo occupies a technology-anchor role through concentrated investment in proprietary motor controllers. Backfire sits within the geographic-specialist archetype, dominating European distribution partnerships that create replication barriers for emerging entrants. These three represent distinct competitive vectors—channel economics, electronics differentiation, and regional lock-in—that define strategic positioning across the market.
| Leading Market Players |
|---|
| Acedeck |
| Wowgo |
| Meepo |
| Tynee |
| Backfire |
| OMW Boards |
| ONSRA |
| Propel |
| Ecomobl |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between California fleet operators and South Korean cell manufacturers lock in lithium-ion supply access while stabilizing pack cost visibility against carbonate price swings. These contracts concentrate procurement power among volume buyers, compressing margin buffers for smaller brands dependent on spot market exposure.
Pricing Analysis
After-sales revenue from replacement battery packs and motor controller repairs drives lifetime value capture beyond initial hardware margins. Three-tier pricing structure across premium carbon fiber, standard bamboo composite, and economy maple configurations separates enthusiast buyers from cost-sensitive students. Price differentiation hinges on certification tier — UL-listed units command substantial premiums over unverified alternatives — and deck material grade. Cost compression in entry-tier maple assemblies is intensifying because Chinese veneer suppliers compete on volume, eroding North American hardwood positioning. Fleet procurement managers show lowest price sensitivity, absorbing carbon fiber premiums for damage resistance, while campus commuters remain most responsive to upfront acquisition thresholds.
Supply Chain Analysis
Just-in-time inventory strategies dominate among direct-to-consumer brands, though lithium carbonate volatility is forcing selective stockpiling of nickel-manganese-cobalt cells. Manufacturing concentrates in China's Pearl River Delta for electronics integration, South Korea for cell production, and Vietnam for bamboo veneer processing. The supply chain draws from brushless DC motors, lithium-ion cells, and composite deck materials as core inputs. Single-source vulnerability in South Korean cell supply creates structural exposure if export restrictions tighten. Distribution runs through manufacturer-direct channels for margin retention, with limited regional wholesaler participation in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric skateboard incumbents face substitution pressure from shared e-scooter fleets and micromobility-as-a-service platforms that displace individual ownership models. Defense requires locking in fleet procurement relationships before municipal pilots consolidate around multi-modal operators.
For Market Incumbents: Compound channel control advantages by securing exclusive campus and corporate fleet contracts before shared mobility operators capture procurement volume. Deepen backward integration into proprietary motor controller firmware to escape commodity hub motor pricing traps. Prioritize CE marking and UL certification investments to disqualify uncertified rivals from institutional procurement shortlists.
For New Entrants and Emerging Players: Anchor in lightweight sub-7 kilogram configurations for European multimodal commuters, the most penetrable white space where established brands underinvest. Target Netherlands and German university towns with subscription-based ownership models that reduce upfront price barriers. Deploy repair-forward service positioning to differentiate against disposable-tier competitors.
For Investors and Strategic Acquirers: Capital is best deployed toward direct-to-consumer specialists with proven unit economics and captive assembly capacity in Shenzhen or Dongguan. Long-term viability favors brands that control electronics IP rather than those dependent on outsourced motor controllers. Watch FAA battery transport restriction enforcement as the signal for inventory carrying cost inflection that reshapes working capital requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Motor Controller Development | Escalating R&D concentration in field-oriented control algorithms differentiates torque delivery precision. |
| Campus Fleet Partnership Expansion | Centralized charging infrastructure pilots at Eindhoven and Stanford campuses aggregate demand volume. |
| Composite Deck Additive Manufacturing | Automated fiber placement convergence enables batch-of-one customization at production cost economics. |
| REACH-Compliant Battery Chemistry Scaling | European cell manufacturers expand nickel-manganese-cobalt formulations satisfying ECHA substance restrictions. |
| Direct-to-Consumer Channel Deepening | Margin structures from owned digital distribution resist vertical integration pressures from integrated rivals. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with electric skateboard brand founders, procurement managers at California logistics fleets, composite deck fabricators in Bavaria, and lithium-ion pack assemblers in Shenzhen; alongside secondary validation from CPSC safety filings, EU Machinery Directive documentation, FAA battery transport advisories, and customs trade records. Bottom-up triangulation across component cost buildups and top-down demand aggregation from fleet procurement disclosures cross-verified volume estimates.
Across the projection horizon, the analytical framework modeled segmentation across product type, battery capacity tier, deck material composition, and weight class, with regional regulatory cluster overlays for California, Germany, and Netherlands demand patterns. CAGRs derived from fitted growth curves applied to fleet procurement trajectories and individual commuter adoption velocity, incorporating lithium-ion energy density improvement curves from South Korean cell manufacturers and micromobility lane infrastructure investment pipelines.
Material uncertainties — lithium carbonate price spikes, aviation battery transport restriction tightening, and municipal licensing scheme fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions around fleet electrification continuity and REACH compliance maintenance. Revision becomes warranted when shared micromobility substitution rates cross thresholds that displace individual ownership economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Solar E-Bike Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
Solar Car Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
India Electric Rickshaw Market
Electric Vehicles
Solar Vehicle Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Scooter Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market